
 Spreadable Fats Market | 2026-2036
Spreadable Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Spreadable Fats Market Analytics
Clean-label emulsification technology is fragmenting traditional manufacturing pathways for spreadable fats, forcing processors to choose between enzymatic interesterification and mechanical fractionation systems. Unilever leverages its global R&D network to reformulate margarine lines with reduced saturated fat profiles. Upfield anchors its competitive stance through dedicated plant-based spread facilities across Northern Europe. Cargill competes by controlling upstream oilseed processing and specialty lipid supply chains.
Spreadable fats encompass butter, margarine, cream cheese, and vegetable-based spreads formulated for direct consumption or recipe integration, typically containing 60-82% fat content with emulsifiers and water phases stabilized through scraped-surface heat exchange or votator processing. The product type segment shows butter maintaining premium positioning in European retail while vegetable spreads capture reformulation-driven volume in North American food service. Margarine occupies the mature, price-sensitive institutional channel where bakeries and food manufacturers prioritize functional consistency over brand loyalty.
EFSA standards govern nutritional labeling and health claims for fat-based spreads across EU member states, while FDA regulations in the United States define standardized identity requirements for butter and margarine that constrain formulation flexibility. BIS certification requirements in India affect import access for international spreadable fat suppliers entering organized retail. Stakeholders must monitor evolving front-of-pack labeling mandates and trans-fat limits that will determine which emulsion technologies retain commercial viability.
Market Dynamics
Clean-label emulsification technology is fragmenting traditional manufacturing pathways for spreadable fats, forcing processors to choose between enzymatic interesterification and mechanical fractionation systems. EU F-Gas Regulation and REACH compliance requirements are simultaneously reshaping cold-chain processing standards for fat-based emulsions.
Growth Catalysts
- Artisanal bakery reformulation:Industrial and craft bakers across Germany, France, and Italy are reformulating laminated dough recipes to eliminate partially hydrogenated oils, creating pull for high-performance butter-vegetable fat blends.
- REACH chemical safety mandates:ECHA's evolving substance restrictions on emulsifier chemistries are accelerating adoption of enzymatic interesterification as a cleaner-label processing alternative to chemical interesterification.
- Plant-based spread R&D:Dedicated fermentation-derived lipid facilities in the Netherlands and Denmark are scaling novel fat structuring technologies that replicate butter crystallization behavior without dairy inputs.
Market Restraints
- Palm oil price volatility:Vegetable spread formulations remain exposed to Malaysian and Indonesian palm olein price swings, compressing margin predictability for European margarine producers.
- Fractionation equipment concentration:Scraped-surface heat exchanger and votator system supply concentrates among German and Italian engineering specialists, creating capex bottlenecks for capacity expansion.
- Butterfat supply constraints:Seasonal milk production fluctuations in New Zealand and Ireland limit year-round availability of premium anhydrous milk fat for premium spread formulations.
Strategic Opportunities
- Indian organized retail penetration:BIS certification requirements have historically constrained import access, but reformatted spreadable fat portfolios meeting FSSAI standards can capture modern trade growth in Mumbai and Delhi.
- Direct-to-foodservice channels:Bakeries and QSR chains in Poland and Spain are bypassing traditional wholesale distributors to procure bulk fat emulsions through specialized lipid suppliers.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams for sustainable food processing are subsidizing pilot plants for microbial oil production as butter alternatives.
Industry Challenges
- Emulsion stability expertise gap:Formulation chemists capable of optimizing water-in-oil emulsions across varying temperature profiles remain scarce in Central European processing hubs.
- Dual certification timelines:Simultaneous EFSA health claim validation and national front-of-pack labeling compliance in France and Germany extend product launch cycles by 18-24 months.
- Legacy votator integration:Mechanical fractionation lines installed in the 1990s require costly retrofitting to handle enzymatically interesterified fat bases without crystallization defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spreadable Fats Market |
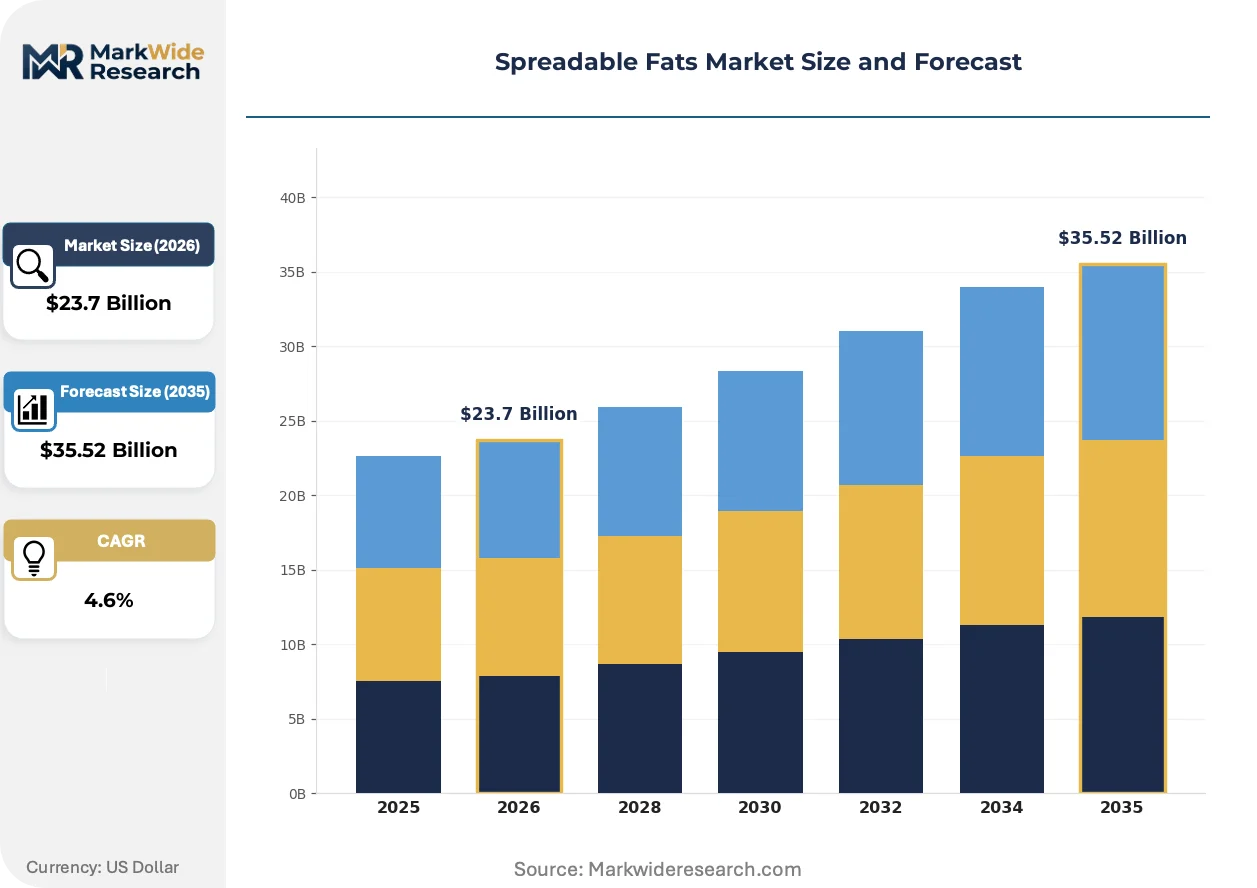
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Cream Cheese, Vegetable Spreads End User: Households, Food Service, Bakeries, Food Manufacturers Packaging Type: Plastic Containers, Glass Jars, Tubs, Squeeze Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Unilever, Upfield, Land O'Lakes, Lactalis Group, Conagra Brands, Cargill, Wilmar International Limited, Archer Daniels Midland Company, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spreadable Fats Market Evolving Landscape
Digital twin modeling is virtualizing process development cycles for spreadable fat manufacturers, compressing pilot-scale validation timelines while regulatory front-of-pack mandates reshape formulation priorities across European retail.
High-pressure processing (HPP) is virtualizing traditional thermal pasteurization steps in cream cheese and fresh dairy spread production. Artisanal producers in Denmark and the Netherlands are adopting HPP lines to extend shelf life without flavor degradation. This technology is virtualizing the conventional cold-chain dependency for preservative-free emulsions, enabling shorter distribution loops from regional dairies to urban retail.
EU F-Gas Regulation phase-down schedules are mandating conversion from hydrofluorocarbon-based refrigeration to ammonia or CO2 cascade systems in spreadable fat cold storage and votator cooling circuits. Margarine processors in Germany and Belgium face accelerated capex cycles to retrofit scraping-surface heat exchange equipment. The bakery ingredient channel is most affected, as temperature-sensitive laminated fat sheets require precise crystallization control that legacy cooling infrastructure cannot guarantee under new refrigerant constraints.
Foodservice procurement is consolidating around specification-grade fat emulsions with certified clean-label credentials. National QSR chains in Spain and Italy are displacing commodity margarine tenders with multi-year contracts tied to enzymatic processing verification and palm oil traceability documentation. This pattern is most visible in the pizza and viennoiserie segments, where laminated dough performance specifications now include explicit emulsifier chemistry disclosures that commodity suppliers cannot meet.
Spreadable Fats Market Segmentation
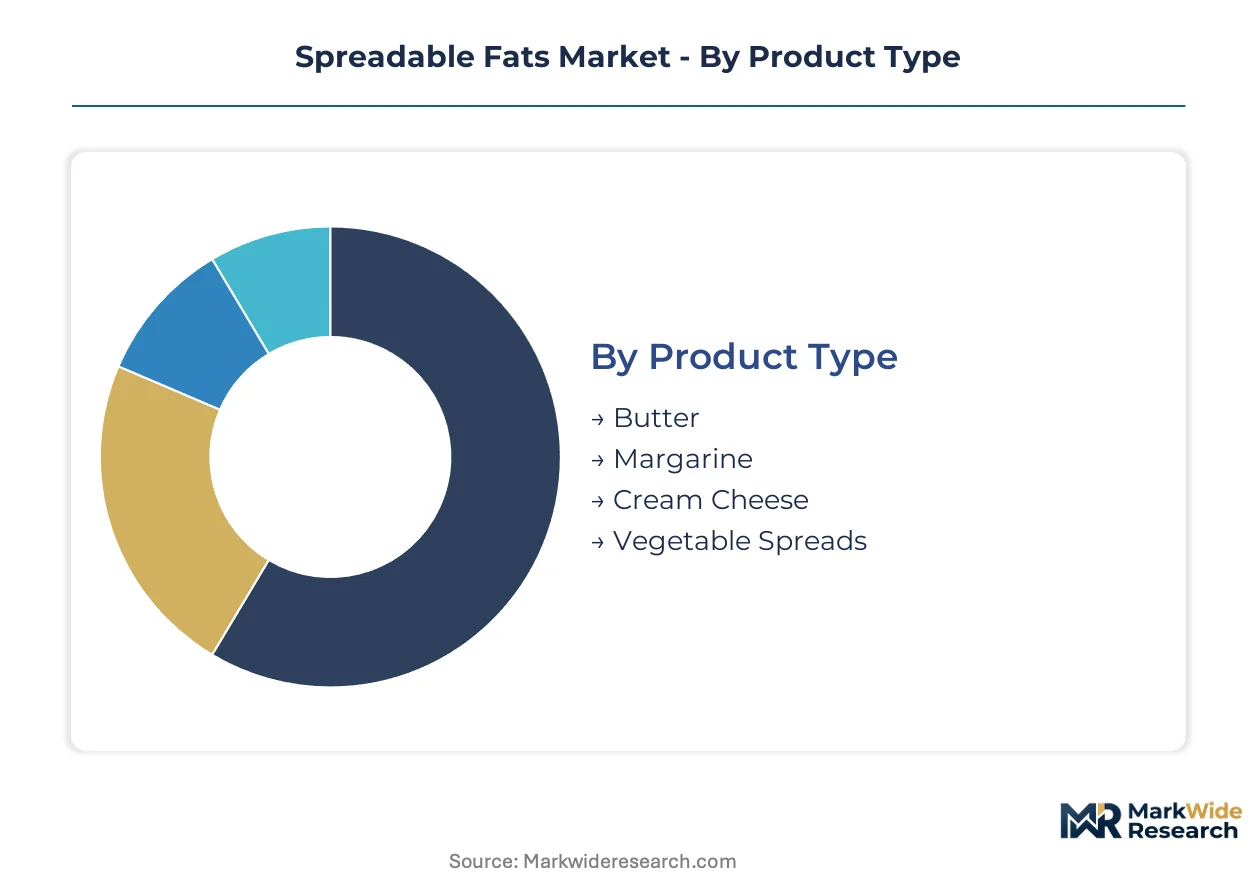
Spreadable fats serve divergent performance requirements across retail, foodservice, and industrial channels, demanding distinct emulsion stability profiles and cold-chain specifications. Segmentation reveals how formulation chemistry, packaging integrity, and procurement patterns fragment the competitive landscape across these use cases.
Product Type:
After-sales technical support intensity varies sharply across product categories, with enzymatic interesterification systems requiring specialized maintenance versus traditional mechanical fractionation lines.
- Butter:Anhydrous milk fat formulations with 82% minimum fat content deliver crystallization behavior prized by artisanal bakers for laminated dough performance. German and French retail channels sustain premium positioning despite seasonal supply constraints from New Zealand and Irish dairy cooperatives.
- Margarine:Water-in-oil emulsions containing 60-80% vegetable fat dominate institutional procurement through functional consistency and price accessibility. North American food manufacturers prioritize margarine for reformulation flexibility under FDA standardized identity constraints.
- Cream Cheese:Fresh dairy spreads with 33% milk fat minimum, stabilized through high-pressure processing in Denmark and Netherlands facilities.
- Vegetable Spreads:Plant-based alternatives leveraging fermentation-derived lipids from Dutch and Danish pilot facilities.
Butter holds the largest share; momentum sits with vegetable spreads.
End User:
Cost tier differentiation separates specification-grade buyers from commodity procurement, with bakeries and food manufacturers commanding volume discounts unavailable to fragmented household channels.
- Households:Retail consumers purchasing 250-500g formats through supermarkets and convenience stores, with German shoppers showing strongest traditional butter loyalty alongside plant-based experimentation.
- Food Service:QSR chains and institutional kitchens procuring bulk emulsions with certified clean-label credentials, particularly in Spain and Italy where pizza and viennoiserie segments drive laminated fat specifications.
- Bakeries:Artisanal and industrial producers across Germany, France, and Italy reformulating laminated dough recipes to eliminate partially hydrogenated oils.
- Food Manufacturers:Processed food companies requiring functional fat emulsions with precise crystallization control for extended shelf-life products.
Food manufacturers command volume concentration; bakeries are expanding most quickly.
Packaging Type:
Volume throughput and margin structure diverge across formats, with industrial tubs and squeeze pouches scaling faster than premium glass formats constrained by weight and breakage costs.
- Plastic Containers:Polypropylene and polyethylene terephthalate formats dominating retail shelf presence for margarine and vegetable spreads across European supermarkets.
- Glass Jars:Premium positioning for cultured butter and specialty cream cheese in specialty stores and gift segments.
- Tubs:Polypropylene formats with resealable lids capturing food service and bakery bulk procurement in Poland and Spain.
- Squeeze Pouches:Flexible packaging gaining traction in convenience-oriented retail and food service portion control applications.
Plastic containers maintain dominant share; squeeze pouches show steepest expansion trajectory.
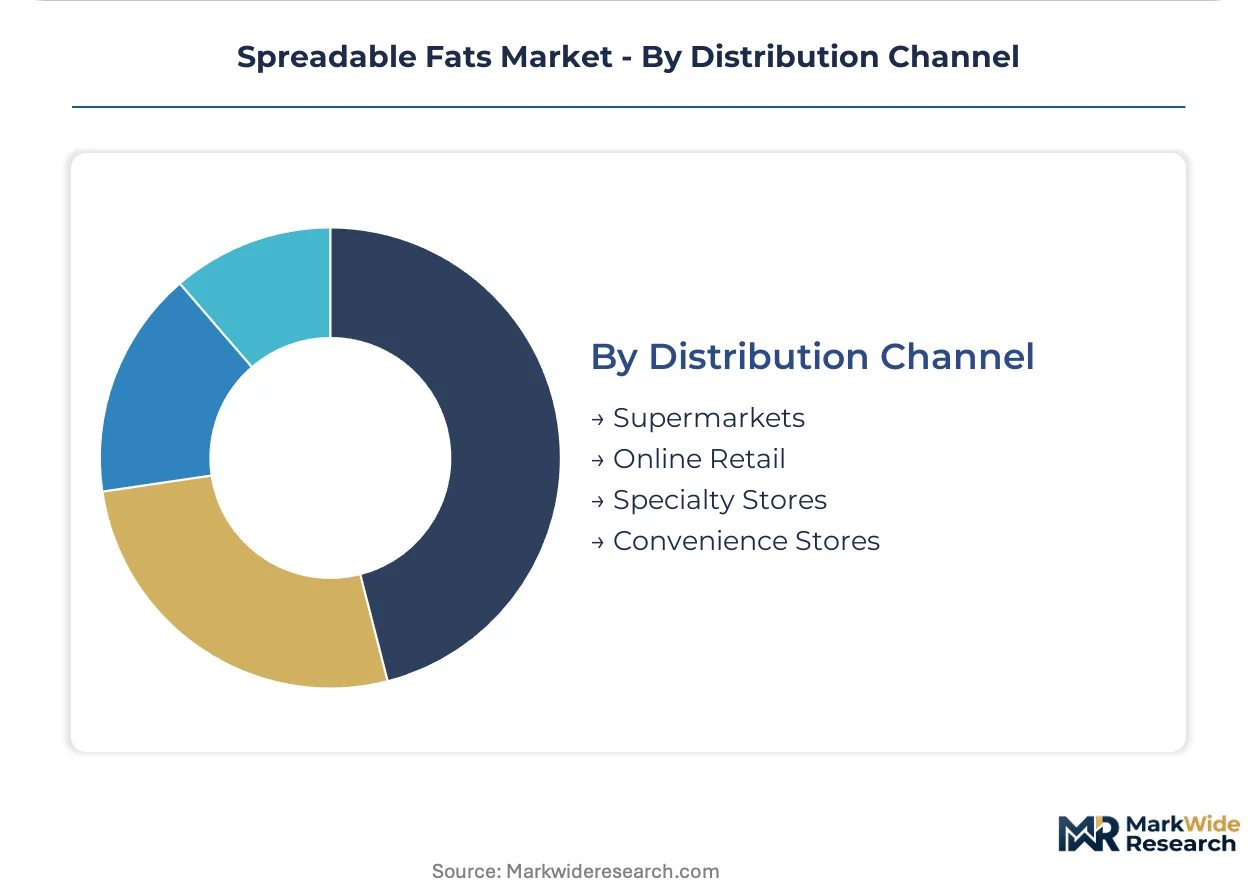
Distribution Channel:
Customer type fragmentation separates specification-driven procurement through specialty and online channels from price-sensitive supermarket and convenience store transactions.
- Supermarkets:Hypermarket and supermarket chains in Germany and France anchoring butter and margarine volume through promotional pricing and private label placement.
- Online Retail:Direct-to-consumer platforms expanding specialty and organic spreadable fat access, particularly in urban Indian markets where BIS certification barriers limit import availability through traditional trade.
- Specialty Stores:Delicatessen and gourmet retailers focusing on artisanal butter, cultured cream cheese, and plant-based premium alternatives.
- Convenience Stores:Small-format urban retail capturing impulse purchases and emergency replenishment for household segments.
Supermarkets retain volume leadership; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand butter exports supply German retail and industrial channels, while Malaysian palm olein flows into European margarine production. This trade architecture concentrates processing expertise in Northern Europe and dairy sourcing in Oceania.
Germany
Traditional butter consumption coexists with plant-based spread innovation across retail and foodservice channels. EFSA nutritional labeling standards govern health claims for fat-based spreads sold through German supermarkets. The Cologne-Düsseldorf corridor hosts specialized votator system engineering firms serving margarine producers retrofitting for F-Gas Regulation compliance.
United States
FDA standardized identity requirements constrain butter and margarine formulation flexibility for North American food manufacturers. Industrial bakeries prioritize functional consistency in institutional procurement of water-in-oil emulsions. Chicago and Minneapolis anchor bulk fat emulsion distribution networks supplying QSR chains and wholesale bakery operations.
India
BIS certification requirements affect import access for international spreadable fat suppliers entering organized retail in Mumbai and Delhi. FSSAI standards determine product launch viability for reformatted spreadable fat portfolios targeting modern trade growth. Maharashtra and Karnataka concentrate dairy processing infrastructure for domestic butter production.
Netherlands
Dedicated fermentation-derived lipid facilities scale novel fat structuring technologies replicating butter crystallization behavior. Horizon Europe bioeconomy incentives subsidize pilot plants for microbial oil production as butter alternatives. Rotterdam and Wageningen anchor R&D clusters linking academic lipid science to commercial spread manufacturing.
France
Artisanal bakers reformulate laminated dough recipes to eliminate partially hydrogenated oils, creating demand for high-performance butter-vegetable fat blends. National front-of-pack labeling compliance extends product launch cycles alongside EFSA validation requirements. The Brittany dairy basin supplies premium anhydrous milk fat for spread formulations.
Spreadable Fats Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base separates into multinational consumer goods conglomerates with retail shelf dominance, agricultural commodity traders controlling upstream oilseed processing, and regional dairy cooperatives with captive milk fat supply. Strategic archetypes include R&D-networked reformulators, upstream-integrated lipid suppliers, and dedicated plant-based spread manufacturers. Competitive moves concentrate on enzymatic processing technology licensing and cold-chain infrastructure retrofitting.
Within the multinational consumer goods tier, Unilever and Upfield occupy positions representing divergent strategic emphases on reduced saturated fat reformulation versus dedicated plant-based facility investment. Among agricultural commodity traders, Cargill anchors upstream control over specialty lipid supply chains. These three entities exemplify how competitive positioning fragments between brand-channel dominance and raw material sovereignty.
| Leading Market Players |
|---|
| Unilever |
| Upfield |
| Land O'Lakes |
| Lactalis Group |
| Conagra Brands |
| Cargill |
| Wilmar International Limited |
| Archer Daniels Midland Company |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity in European enzymatic interesterification facilities is compressing margin flexibility for spreadable fat processors while simultaneously elevating pricing power for German and Italian engineering specialists controlling scraped-surface heat exchanger supply. This utilization asymmetry forces margarine producers to absorb extended lead times for clean-label retrofitting or accept legacy chemical processing cost penalties.
Pricing Analysis
Mechanical fractionation systems carry 40-60% capex premiums over enzymatic interesterification lines, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on certification grade for clean-label credentials and volume scale for institutional bakery procurement. Cost compression in commodity margarine tiers is intensifying because Malaysian palm olein volatility transmits directly into formulation costs. Food manufacturers exhibit highest price sensitivity due to functional specification rigidity, while artisanal bakeries absorb premiums for crystallization performance.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules function as de facto export controls on legacy refrigeration technology, constraining votator cooling circuit flows into spreadable fat processing. Supply concentrates in Germany, Italy, and the Netherlands for fractionation equipment engineering. Raw material dependencies span New Zealand anhydrous milk fat, Malaysian and Indonesian palm olein, and fermentation-derived lipids from Dutch pilot facilities. Single-source vulnerability concentrates in German scraped-surface heat exchanger specialists. Distribution runs through Rotterdam and Hamburg port clusters into European bakery ingredient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spreadable fats market is recovering from a cyclical trough driven by palm oil price normalization following Indonesian export policy adjustments. Reformulation cycles for clean-label compliance are extending replacement demand timelines across bakery and foodservice channels.
For Market Incumbents: Pre-empt enzymatic processing capacity bottlenecks by securing forward contracts with German engineering specialists for votator retrofitting. Anchor backward integration into specialty lipid supply chains through partnerships with Dutch fermentation-derived lipid facilities. Defensive positioning requires accelerating EFSA health claim validation timelines before dual certification mandates extend further in France and Germany.
For New Entrants and Emerging Players: Indian organized retail penetration represents the most accessible white-space target, where BIS certification barriers have historically constrained import competition. FSSAI-compliant reformatted portfolios can capture modern trade growth in Mumbai and Delhi. Direct-to-foodservice channels in Poland and Spain offer secondary entry points, with bakeries bypassing traditional wholesale distributors for bulk fat emulsion procurement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic interesterification sub-segments as F-Gas Regulation compliance mandates accelerate equipment replacement cycles. Long-term viability favors acquisition targets with captive clean-label processing verification and established palm oil traceability documentation. Monitor ECHA substance restriction announcements for emulsifier chemistries as the primary inflection signal for technology obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Technology Licensing | Unilever and Upfield leverage proprietary interesterification protocols to secure clean-label supply contracts with Spanish and Italian QSR chains. |
| Cold-Chain Infrastructure Retrofitting | German margarine processors face accelerated capex cycles to convert hydrofluorocarbon refrigeration to ammonia cascade systems under EU F-Gas mandates. |
| Backward Integration into Oilseed Processing | Cargill anchors competitive positioning through upstream control over specialty lipid supply chains serving North American food manufacturers. |
| Fermentation-Derived Lipid Facility Scale-Up | Dutch and Danish pilot plants replicate butter crystallization behavior without dairy inputs, supported by Horizon Europe bioeconomy funding streams. |
| Direct-to-Foodservice Channel Development | Specialized lipid suppliers in Poland and Spain bypass traditional wholesale distributors to capture bakery and QSR procurement consolidation. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interview programs captured perspectives from plant managers at European margarine processing facilities, procurement leads at industrial bakeries across Germany and France, regulatory affairs specialists navigating EFSA and FDA labeling requirements, and distribution channel partners in Rotterdam and Hamburg port clusters. Secondary sources encompassed ECHA substance restriction databases, FDA standardized identity filings for butter and margarine, EU F-Gas Regulation implementation timelines, customs records for New Zealand butter exports and Malaysian palm olein imports, and SEC disclosures from upstream agricultural commodity traders. Bottom-up volume modeling triangulated against top-down value projections across product type, end user, and regional segments.
Forecast inputs considered emulsion technology adoption curves, regulatory compliance cost trajectories, and raw material price volatility patterns across the projection horizon. Segmentation dimensions encompassed product type crystallization requirements, end-user procurement specifications, packaging format throughput economics, and distribution channel regulatory barriers. CAGRs derived from regression analysis of historical volume trends against capacity expansion announcements and reformulation cycle timing. Industry-specific inputs included enzymatic interesterification yield improvements and F-Gas Regulation retrofitting adoption rates.
Practitioners should monitor ECHA emulsifier substance restriction announcements, Indonesian palm oil export policy shifts, and New Zealand dairy cooperative production forecasts for early signals of forecast deviation. Forecasts reflect assumptions regarding clean-label reformulation pace and enzymatic processing technology cost curves. Material shifts in EU Green Deal bioeconomy incentive allocation or REACH compliance timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Tomato Paste Market
Processed Foods
Pizza Market
Processed Foods
Fermented Foods Market
Processed Foods
US Tomato Paste Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Beef Market
Processed Foods
Yogurt Dip Market
Processed Foods
Egg Powder Market
Processed Foods
Fat Free Soup Market
Processed Foods
Processed Superfruits Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Potato Soup Market
Processed Foods
Low Fat Puddings Market
Processed Foods
United States Processed Meat Market
Processed Foods
Butter Crisco Market