
 Butter Crisco Market | 2026-2036
Butter Crisco Market Size, Share, and Industry Trends Forecast 2026-2036
Butter Crisco Market Outlook
Private-label shortening manufacturing is reshaping margin distribution across the Butter Crisco value chain. Cargill leverages its oilseed crushing network to sustain raw material cost advantages. Bunge anchors North American supply through its extensive processing infrastructure. Wilmar competes across Asia-Pacific markets with integrated palm oil operations.
Butter Crisco denotes hydrogenated and non-hydrogenated vegetable shortening formulated for baking applications, typically containing soybean, palm, or canola oils with emulsifiers to achieve specific melting points between 110°F and 120°F. The product delivers consistent texture and extended shelf stability for commercial and home baking. Shortening dominates volume within product type segments due to institutional bakery procurement scale. Food grade classification captures the majority of value, while bulk packaging commands the industrial channel and sticks maintain retail penetration.
FDA nutrition labeling mandates and USDA dietary guidelines shape trans-fat reduction timelines and reformulation investments across domestic manufacturers. EPA biofuel policies indirectly influence soybean oil feedstock availability and pricing for shortening producers. Stakeholders must monitor emerging state-level clean-label legislation and plant-based certification standards to anticipate compliance costs and product positioning requirements.
Market Dynamics
Clean-label reformulation pressures and trans-fat phase-out mandates are restructuring Butter Crisco manufacturing priorities. Commercial bakeries now demand fully hydrogenated alternatives with identical functional performance, forcing producers to rebuild emulsifier systems and oil blending protocols from molecular specifications upward.
Growth Catalysts
- USDA dietary guidelines:Trans-fat reduction timelines accelerate institutional bakery procurement of reformulated shortenings. Foodservice operators must comply with federal menu labeling standards.
- Commercial bakery consolidation:Large-scale procurement contracts favor suppliers with validated clean-label portfolios. National chains standardize shortening specifications across distributed production networks.
- Emulsifier technology advancement:Mono- and diglyceride innovations enable palm-free formulations with equivalent creaming properties. Midwest soybean processing clusters supply feedstock for enzymatic interesterification.
Market Restraints
- Soybean oil price volatility:EPA biofuel mandates divert domestic oilseed crush toward renewable diesel. Shortening producers compete with fuel refiners for identical feedstock streams.
- Palm oil supply concentration:Southeast Asian plantation networks face EUDR traceability requirements. European import documentation burdens extend procurement lead times.
- Functional equivalence barriers:Fully hydrogenated alternatives lack the plastic range of partially hydrogenated predecessors. Laminated pastry applications resist clean-label substitution.
Strategic Opportunities
- Texas and California industrial bakery corridors:Underpenetrated regional production capacity exists near population growth centers. Co-located shortening facilities reduce inbound logistics costs.
- Plant-based certification standards:Emerging third-party vegan verification creates premium positioning. Retail channels reward differentiated labeling with shelf placement preferences.
- Enzymatic interesterification and fractionation convergence:Combined processing yields tailored melting curves without hydrogenation. Pilot installations demonstrate commercial-scale throughput viability.
Industry Challenges
- Reformulation R&D talent scarcity:Lipid chemistry expertise concentrates with retiring generation. Universities have downsized dedicated fats and oils programs.
- Dual certification timelines:Simultaneous FDA nutrition label updates and state-level clean-label compliance strain regulatory affairs bandwidth. Documentation requirements multiply across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butter Crisco Market |
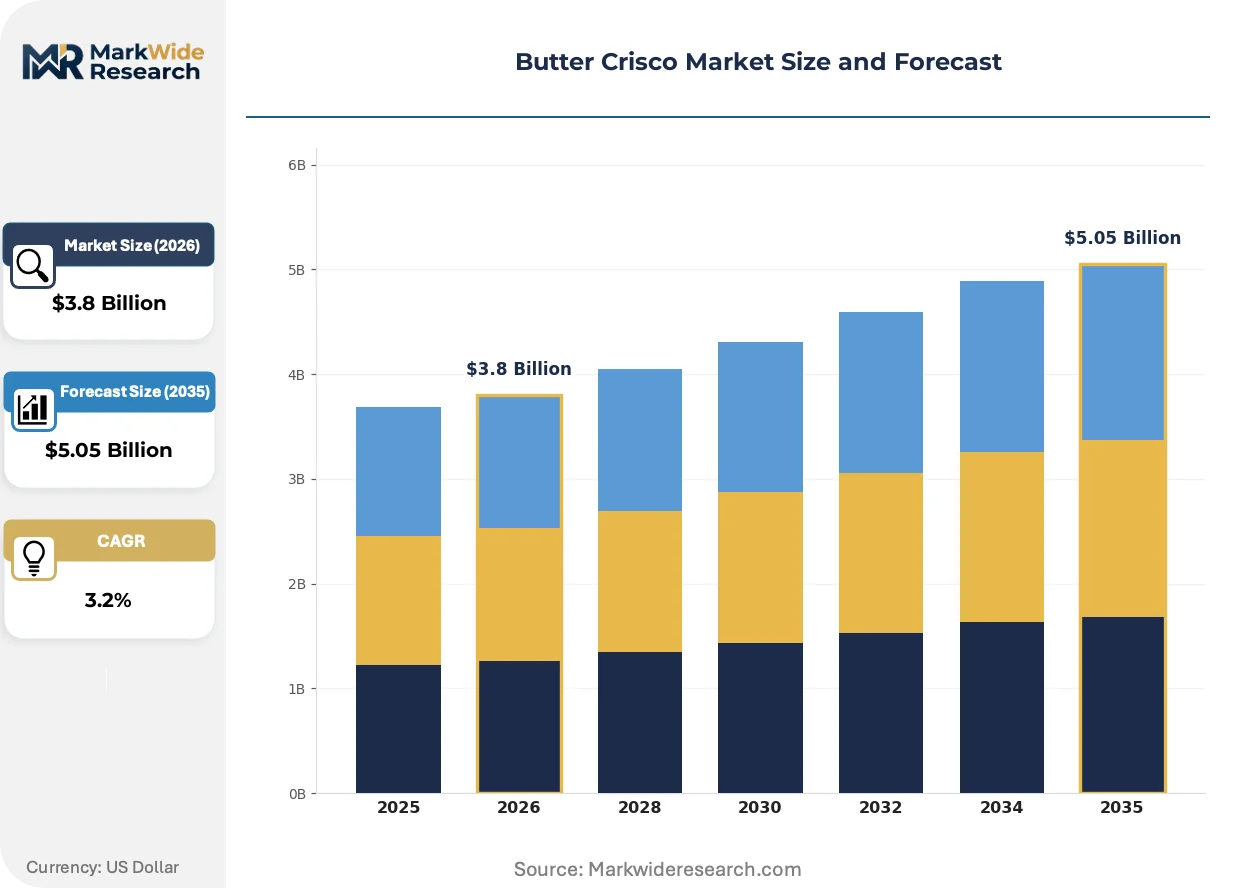
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Shortening, Blends Grade: Food Grade, Industrial Grade, Premium, Standard Packaging Type: Bulk, Tubs, Sticks, Pouches Distribution Channel: Supermarkets, Online Retail, Food Service, Specialty Stores |
| Companies Covered | B&G Foods, Cargill, Bunge, Wilmar, Fuji Oil, Nisshin OilliO, Tillamook, Mazola, Wesson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butter Crisco Market Strategic Shifts
Processing technology and procurement behavior are diverging from legacy shortening paradigms. Manufacturers must reconcile functional performance requirements with molecular composition transparency demanded by downstream buyers.
Enzymatic interesterification systems are rendering obsolete traditional hydrogenation infrastructure for premium shortening tiers. Artisan and specialty bakeries in the Northeast and Pacific Northwest adopt these alternatives despite cost premiums. Equipment retrofit requirements compress margins for mid-scale producers lacking capital access.
California's Proposition 65 warning requirements and New York's trans-fat municipal codes create patchwork compliance obligations. Multi-state operators must maintain parallel inventory SKUs with divergent additive declarations. Regional distributors absorb labeling complexity as a service layer.
Foodservice procurement teams now mandate supplier sustainability scorecards with verified deforestation-free palm documentation. Contract baking facilities in the Southeast and Midwest face audit requirements previously reserved for consumer packaged goods. Third-party verification costs flow through to shortening price negotiations.
Butter Crisco Market Segmentation
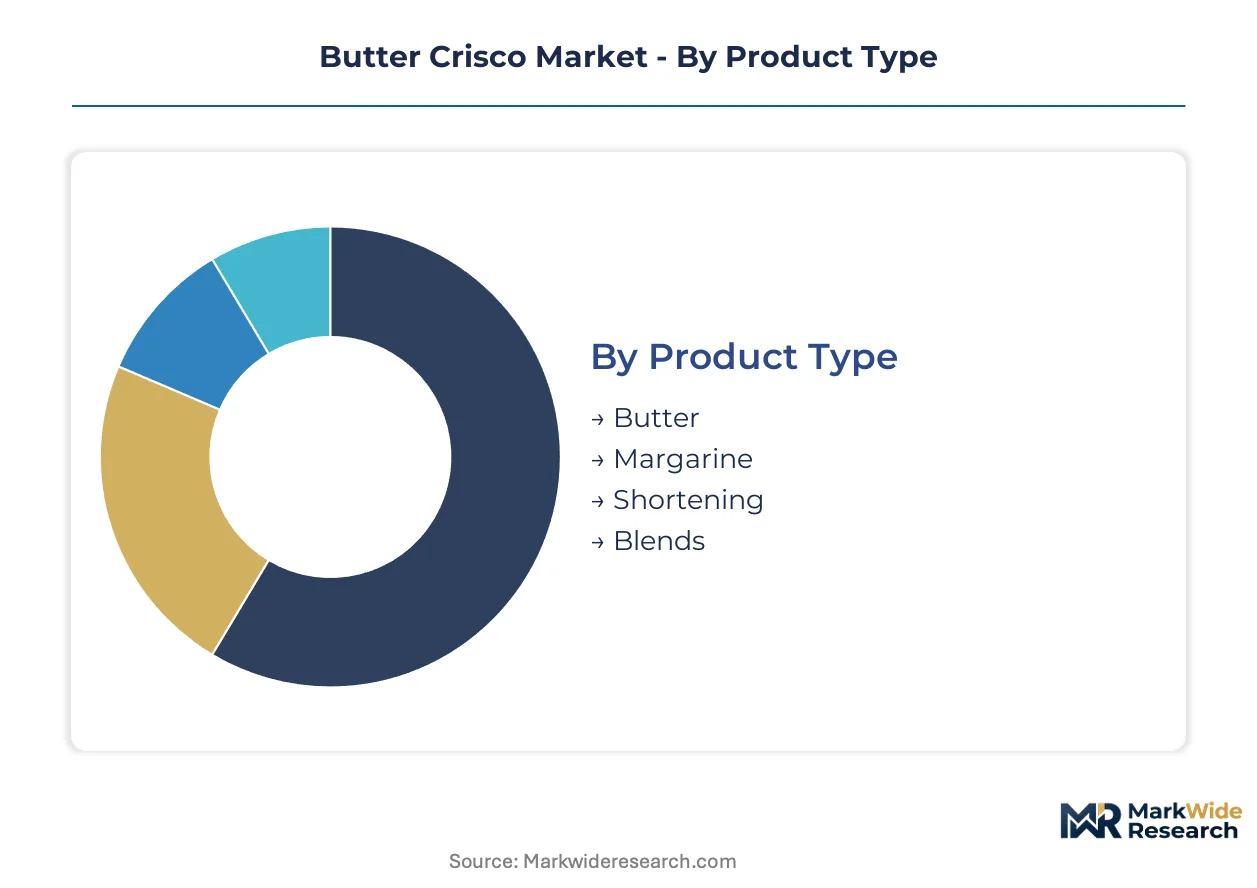
Butter Crisco segmentation reveals how procurement scale, functional requirements, and channel economics fragment demand across distinct buyer profiles. Manufacturers must align formulation investments with the specific performance thresholds and price sensitivities governing each segment cluster.
Product Type:
Use-case spectrum spans artisan home bakers requiring precise creaming properties to industrial facilities optimizing for throughput and shelf stability.
- Shortening:Hydrogenated and non-hydrogenated vegetable formulations deliver controlled melting points between 110°F and 120°F through emulsifier systems. Commercial bakeries in the United States drive procurement volume as clean-label mandates force reformulation toward fully hydrogenated alternatives with identical plastic range.
- Butter:Dairy-derived fat with natural flavor compounds and distinct crystalline structure for laminated pastries. Specialty bakeries in the Northeast and Pacific Northwest absorb cost premiums for authentic taste profiles despite supply volatility from regional dairy cooperatives.
- Margarine:Water-in-fat emulsion with vegetable oil base and milk solids for spreadability and baking functionality. Retail channels in the Midwest sustain volume through price-sensitive household penetration.
- Blends:Hybrid formulations combining butter and vegetable oils to balance flavor with cost and functional consistency. Foodservice operators in institutional settings specify these for standardized recipe execution across distributed locations.
The dominant share belongs to Shortening, while Blends is closing the gap fastest as foodservice procurement teams seek cost-optimized performance equivalence.
Grade:
Cost tier stratification separates premium positioning built on certification and provenance from commodity grades competing on unit economics.
- Food Grade:Meets FDA standards for direct human consumption with documented contaminant thresholds and additive allowances. Packaged goods manufacturers in the United States require validated certificates of analysis for each production lot to satisfy retail audit protocols.
- Premium:Certified non-GMO, organic, or plant-based verified with batch traceability to origin. Clean-label bakeries in California and New York command shelf placement premiums for differentiated positioning.
- Industrial Grade:Technical specifications for non-food applications including lubricants and cosmetic feedstocks. Chemical processors in the Gulf Coast corridor absorb volume with less stringent organoleptic requirements.
- Standard:Baseline compliance with minimum regulatory thresholds without additional certification. Regional distributors in the Southeast leverage this tier for price-competitive foodservice contracts.
Food Grade commands the value concentration, though Premium is expanding most quickly as third-party verification creates pricing power in coastal metropolitan markets.
Packaging Type:
Volume scale and handling automation requirements dictate format selection from bulk tanker deliveries to retail-ready units.
- Bulk:Tanker and tote configurations for high-throughput manufacturing facilities with dedicated receiving infrastructure. Industrial bakery corridors in Texas and California minimize per-unit logistics costs through direct pipeline delivery.
- Sticks:Pre-measured rectangular portions for precise recipe scaling in commercial and home kitchens. Retail penetration in the Midwest depends on refrigerated case placement and seasonal baking promotion cycles.
- Tubs:Reclosable containers for spreadable applications and portion-controlled scooping. Foodservice operators in institutional cafeterias favor this format for sanitation and waste reduction.
- Pouches:Flexible film packaging for single-use or limited-batch applications with reduced material cost. Emerging channel penetration in online retail supports sample sizing and subscription box integration.
Bulk retains the procurement volume leadership, yet Pouches is gaining share fastest as direct-to-consumer channels fragment traditional distribution economics.
Distribution Channel:
Customer type and purchase frequency shape channel strategy from high-velocity retail to specification-driven institutional contracting.
- Food Service:Direct and broadline distribution to commercial bakeries, restaurants, and institutional kitchens with technical specification requirements. National bakery chains in the United States standardize shortening procurement through approved vendor lists with sustainability scorecard mandates.
- Supermarkets:Mass retail placement with trade promotion support and seasonal display programming. Regional grocers in the Midwest and Southeast compete on private-label shortening penetration against heritage brand recognition.
- Online Retail:E-commerce platforms enabling subscription replenishment and specialty product discovery. Direct-to-consumer growth concentrates in metropolitan markets with limited specialty store access.
- Specialty Stores:Independent retailers serving artisan bakers and culinary professionals with technical consultation. Northeast and Pacific Northwest corridors sustain these outlets through density of premium bakery operations.
Food Service captures the dominant procurement value, while Online Retail is climbing the fastest as procurement teams digitize supplier discovery and reorder workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between industrial procurement corridors and heritage-driven retail markets. The United States concentrates commercial bakery volume, while European buyers prioritize clean-label verification. Asian markets blend traditional shortening applications with emerging plant-based certification demands.
United States
Commercial bakery consolidation drives procurement standardization across national chains. FDA trans-fat phase-out mandates accelerate reformulation investments toward fully hydrogenated alternatives. Texas and California industrial corridors attract co-located shortening facilities to reduce inbound logistics costs for high-throughput manufacturers.
China
Bakery sector expansion fuels shortening demand from quick-service chains and convenience retail. SAMR food safety standards tighten additive disclosure requirements for imported formulations. Yangtze River Delta processing clusters integrate enzymatic interesterification capacity to serve coastal metropolitan bakery networks.
Germany
Industrial bakeries prioritize certified sustainable palm sourcing for laminated pastry applications. EUDR traceability requirements extend procurement lead times for Southeast Asian feedstock. North Rhine-Westphalia food manufacturing zones concentrate shortening formulation R&D for European export markets.
Japan
Precision baking culture sustains demand for tailored melting-point shortenings in artisan applications. METI bioeconomy initiatives support enzymatic processing technology adoption. Kansai corridor facilities specialize in premium-grade formulations for domestic confectionery and export to neighboring Asian markets.
Brazil
Expanding foodservice infrastructure drives institutional shortening procurement from quick-service operators. ANVISA nutrition labeling updates align with Mercosur harmonization timelines. São Paulo state industrial zones process domestic soybean feedstock for regional shortening supply chains.
Butter Crisco Market Competitive Environment
Capability concentration sits with integrated oilseed processors; scale advantage sits with diversified agribusiness conglomerates. The market structures around three tiers: upstream crush-and-refine operators, midstream formulation specialists, and downstream brand marketers. Strategic moves center on backward integration into oilseed crushing and forward integration into clean-label certification services.
Among North American agribusiness operators, Cargill and Bunge exemplify the integrated processing archetype with captive oilseed supply networks. Wilmar anchors Asia-Pacific positioning through palm oil plantation linkages and regional distribution density. Fuji Oil occupies a specialist position in enzymatic interesterification technology for premium shortening tiers.
| Leading Market Players |
|---|
| B&G Foods |
| Cargill |
| Bunge |
| Wilmar |
| Fuji Oil |
| Nisshin OilliO |
| Tillamook |
| Mazola |
| Wesson |
| Others |
Value Chain & Pricing Dynamics
Texas and California industrial bakery corridors transmit freight cost volatility directly into shortening price spreads, compressing margins for distributors lacking co-located storage while amplifying pricing power for crush-and-refine operators with captive pipeline delivery. This logistics asymmetry stratifies procurement economics between bulk tanker buyers and packaged goods distributors.
Pricing Analysis
Long-term offtake contracts dominate procurement between national bakery chains and integrated oilseed processors, locking in volume commitments against soybean oil futures benchmarks. Spot market transactions serve regional distributors and artisan bakeries with 15-20% premiums reflecting smaller batch flexibility. Price differentiation hinges on clean-label certification tier and volume scale, with FDA trans-fat compliance documentation commanding additive premiums. Margins are tightening in standard-grade segments due to renewable diesel feedstock competition, while premium enzymatic interesterification formulations absorb cost-insensitive specialty bakery demand.
Supply Chain Analysis
EUDR deforestation-free documentation requirements restrict palm oil flows from Southeast Asian plantation networks, extending procurement lead times for European-bound formulations. The United States, Indonesia, and Brazil concentrate vegetable oil feedstock supply, with domestic soybean crush anchored in Midwest processing clusters and palm sourcing tethered to Malaysian and Indonesian estate networks. Supply chain risk centers on single-source vulnerability for enzymatic processing catalysts and specialty emulsifiers. Distribution runs through foodservice broadline operators for institutional volume, with direct tanker delivery bypassing traditional warehousing for high-throughput bakery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label mandates splinter procurement specifications across state-level regulatory patchworks, creating niche openings for formulation specialists unburdened by legacy hydrogenation infrastructure.
For Market Incumbents: Pre-empt margin erosion in standard-grade shortening by securing captive soybean crush capacity in Iowa and Illinois processing corridors. Accelerate enzymatic interesterification R&D partnerships with Fuji Oil and Nisshin OilliO to defend technical leadership against emerging palm-free competitors. Lock in multi-year offtake agreements with Texas and California bakery chains before regional co-location investments mature. For New Entrants and Emerging Players: The Pacific Northwest artisan bakery corridor offers underpenetrated white-space for premium enzymatic shortening with plant-based certification. Target specialty stores and direct-to-consumer channels with pouch-format sampling programs to bypass entrenched foodservice distribution. Anchor initial production through toll processing agreements with existing Midwest crush facilities to avoid capital-intensive infrastructure. For Investors and Strategic Acquirers: Mid-scale enzymatic formulation specialists with validated clean-label portfolios represent the priority acquisition archetype for strategic consolidation plays. Monitor FDA nutrition label update timelines and state-level trans-fat municipal code expansions as inflection indicators for reformulation demand acceleration. Long-term viability favors upstream integration into oilseed crushing or downstream certification services rather than standalone formulation exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and Bunge demonstrate how captive soybean supply insulates margin against renewable diesel feedstock competition. |
| Enzymatic Interesterification Scale-Up | Fuji Oil pilot installations prove commercial viability for palm-free formulations with equivalent plastic range. |
| Clean-Label Certification Investment | Third-party vegan verification unlocks premium shelf placement in California and New York retail channels. |
| Co-Location with Industrial Bakery Corridors | Texas and California shortening facilities reduce inbound logistics costs for high-throughput manufacturers. |
| Regional Distribution Partnership | Broadline operators absorb multi-state labeling complexity as a service layer for national bakery chains. |
Study Parameters
A standing panel of commercial bakery procurement directors, oilseed processing plant managers, lipid chemistry R&D leads, and foodservice distribution channel heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA labeling guidance documents, USDA dietary guideline publications, EPA biofuel mandate filings, and SEC 10-K disclosures from integrated agribusiness operators. Trade data from customs records and industry association reports supplied volume triangulation against bottom-up production estimates and top-down consumption modeling.
Scenario-bracketing anchored projections across low, baseline, and high growth pathways reflecting divergent trans-fat phase-out enforcement timelines and enzymatic technology adoption curves. Segmentation modeling spanned product type, grade tier, packaging format, and distribution channel with regional production cluster overlays. CAGRs derived from historical volume trajectories adjusted for feedstock availability constraints and reformulation investment cycles. Soybean oil price volatility bands and palm oil traceability compliance cost assumptions informed sensitivity analysis.
Practitioners should monitor EPA renewable diesel mandate expansions and EUDR documentation requirement enforcement for early signals of feedstock cost pressure. Forecasts reflect assumptions regarding enzymatic processing scale-up timelines and state-level clean-label legislative diffusion. Material shifts in FDA trans-fat enforcement posture or breakthroughs in non-hydrogenated functional equivalence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Apple Butter Market
Processed Foods
Egg White Cubes Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Potato Soup Market
Processed Foods
Instant Curry Market
Processed Foods
Processed Superfruits Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Processed Beef Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Pizza Market