
 Dietary Chocolate Products Market | 2026-2036
Dietary Chocolate Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dietary Chocolate Products Market Outlook
Swiss and Belgian cocoa processors is broadening supply-side capacity for high-cocoa dietary formulations. Barry Callebaut leverages its integrated bean-to-bar infrastructure across multiple continents. Lindt and Sprungli anchors premium positioning through sustained investment in conching technology and origin-specific sourcing. Meiji Holdings competes in Asian dietary segments with specialized reduced-sugar product lines.
Dietary chocolate products encompass cocoa-based confectionery formulated with modified nutritional profiles, including reduced sugar, enhanced protein, added fiber, or functional ingredients such as probiotics and adaptogens, manufactured through controlled conching, tempering, and enrobing processes to preserve bioactive flavonoids and achieve specified melting points. These products serve consumers managing caloric intake, blood glucose response, or micronutrient supplementation through indulgent formats. Dark chocolate and sugar-free chocolate command the strongest margin pools due to premium positioning and ingredient cost structures, while organic chocolate attracts supply-constrained price premiums. Powder and spread forms are gaining traction among fitness centers and dietitians seeking versatile incorporation into meal plans.
FDA oversight of nutrient content claims and the USDA organic certification framework shape product labeling and interstate commerce in the United States, while EFSA health claim assessments under EU Regulation 1924/2006 determine which functional benefits manufacturers may communicate to European consumers. Japan's FOSHU system creates a distinct regulatory pathway for functional chocolate positioning in East Asian markets. Stakeholders must monitor evolving sugar taxation regimes and front-of-pack labeling mandates as these policy instruments increasingly determine formulation investments and geographic market prioritization.
Market Dynamics
EU Regulation 1924/2006 health claim assessments are tightening permissible functional positioning, forcing manufacturers to reformulate around substantiated bioactive compounds rather than marketing narratives. This regulatory compression is accelerating investment in clinical validation infrastructure across European processing clusters.
Growth Catalysts
- EFSA-validated health claims:Manufacturers leveraging approved cocoa flavonoid cardiovascular claims gain shelf differentiation in German and Belgian retail channels.
- Fitness center distribution:Powder and spread formats are securing dedicated placement within gym nutrition programs, creating recurring institutional demand.
- Bean-to-bar traceability systems:Blockchain-enabled origin verification commands price premiums among Swiss and Belgian heritage processors.
Market Restraints
- Cocoa butter price volatility:West African supply disruptions transmit directly to high-cocoa formulation costs, compressing margin pools for dark chocolate specialists.
- EFSA substantiation timelines:Novel ingredient health claims require multi-year clinical investment before commercial deployment.
- Sugar alcohol substitution limits:Erythritol and maltitol tolerance thresholds constrain formulation flexibility in reduced-sugar segments.
Strategic Opportunities
- Japan's FOSHU pathway:Functional chocolate positioning under this regulatory framework enables premium pricing in East Asian markets.
- Probiotic-enriched enrobing:Controlled tempering processes preserving live cultures open clinical nutrition applications.
- Dietitian channel partnerships:Direct professional endorsement programs bypass retail margin stacking for therapeutic positioning.
Industry Challenges
- Conching specialist scarcity:Precision temperature control expertise for flavonoid preservation commands wage premiums in Swiss and Belgian labor markets.
- Dual certification complexity:Simultaneous USDA organic and EU organic compliance requires parallel documentation systems for transatlantic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dietary Chocolate Products Market |
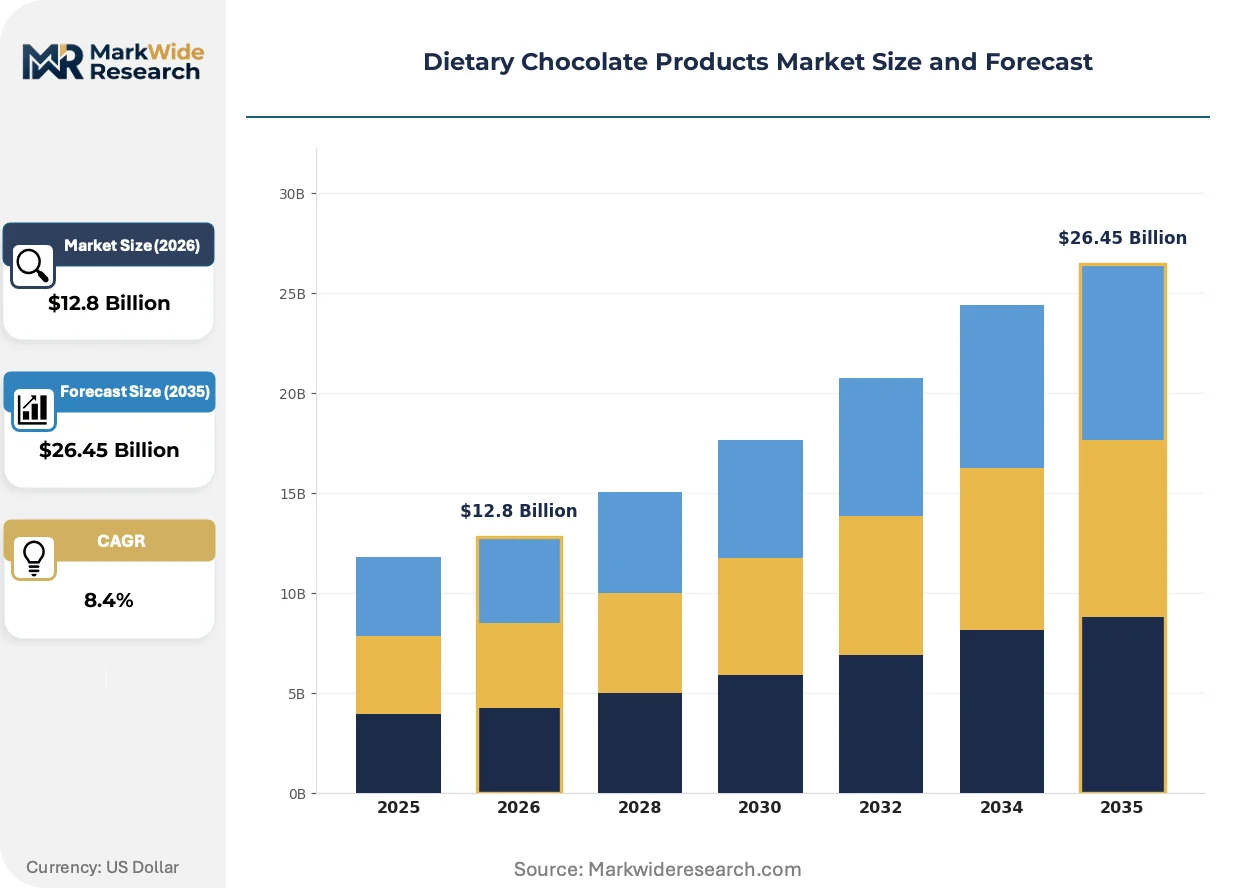
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, Sugar-Free Chocolate, Organic Chocolate End User: Retail Consumers, Health Enthusiasts, Fitness Centers, Dietitians Form: Bars, Drops, Powder, Spreads Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Barry Callebaut, Mondelez International, CEMOI Group, Guittard Chocolate, Gujarat Cooperative Milk Marketing Federation, Lindt and Sprungli, Pascha Chocolate, Meiji Holdings, Migros Cooperatives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dietary Chocolate Products Market Strategic Shifts
Precision fermentation-derived cocoa butter alternatives are disrupting traditional supply dependencies. Manufacturers are reconfiguring tempering protocols around these novel lipid structures while regulatory frameworks scramble to classify their labeling status.
Precision fermentation lipids are overtaking conventional cocoa butter in reduced-calorie formulations. Health-conscious consumers in German metropolitan markets are accepting these alternatives at accelerating rates. This lipid substitution is compressing heritage processor margins while enabling new entrants to bypass West African supply constraints entirely.
EU front-of-pack Nutri-Score mandates are reshaping permissible formulation architectures. Manufacturers must now optimize algorithms rather than single nutrient targets. Dark chocolate segments with naturally favorable fat-sugar ratios are gaining shelf positioning against milk chocolate competitors in French and Belgian retail.
Subscription-based personalized nutrition programs are fragmenting traditional retail concentration. Dietary chocolate is integrating into algorithm-curated supplement bundles rather than standing as impulse confectionery. This channel displacement is most visible in US and UK urban markets where direct-to-consumer wellness platforms dominate acquisition.
Dietary Chocolate Products Market Segmentation
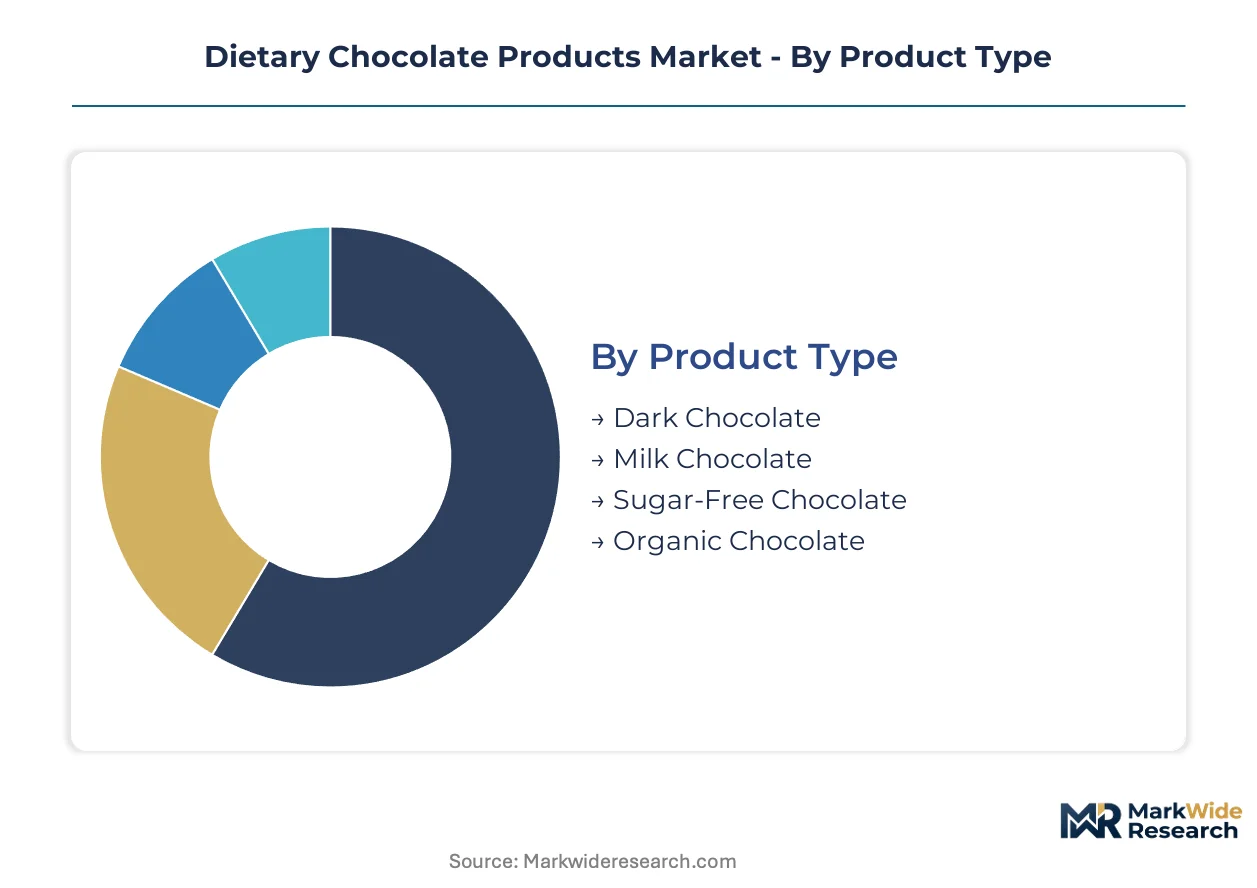
Dietary chocolate formulations diverge sharply across functional intent and consumption context. Segmentation reveals how premium positioning, therapeutic application, and institutional procurement create distinct margin architectures within the same ingredient base.
Product Type:
Customization intensity spans from commodity-adjacent milk chocolate to highly specified organic variants with dual-certification documentation.
- Dark Chocolate:High-cocoa formulations preserve bioactive flavonoids through controlled conching temperatures. Demand concentrates in German and Belgian heritage processing clusters where EFSA-validated cardiovascular claims command retail shelf premiums.
- Sugar-Free Chocolate:Erythritol and maltitol substitution requires precise tempering adjustments to maintain snap and mouthfeel. Health enthusiasts managing blood glucose response drive volume through direct-to-consumer wellness platforms in US urban markets.
- Milk Chocolate:Reduced-sugar variants compete on taste accessibility for caloric-conscious mainstream consumers.
- Organic Chocolate:Dual USDA-EU organic compliance creates supply-constrained price premiums among Swiss processors.
Most installed capacity flows through Dark Chocolate. Expansion is steepest in Sugar-Free Chocolate.
End User:
Procurement authority shifts from impulse retail to institutional specification as therapeutic positioning deepens.
- Health Enthusiasts:Functional nutrition seekers prioritize provenance verification and bioactive compound retention. Fitness center nutrition programs in German metropolitan areas generate recurring institutional demand for powder and spread formats.
- Dietitians:Clinical professionals bypass retail margin stacking through direct endorsement programs. Patient meal planning integration drives specification power for reduced-sugar and probiotic-enriched variants.
- Retail Consumers:Supermarket and convenience channel purchasers respond to front-of-pack labeling mandates.
- Fitness Centers:Gym-based nutrition programs create bundled supplement procurement with algorithm-curated wellness platforms.
Health Enthusiasts anchor volume commitment. Dietitians are gaining specification influence fastest.
Form:
Processing complexity and application versatility determine manufacturing asset allocation across formats.
- Powder:Controlled particle size distribution enables versatile incorporation into protein blends and meal replacements. Fitness centers and dietitians in US and UK urban markets drive accelerating adoption through subscription nutrition programs.
- Spreads:Viscosity engineering for clean-label stability requires specialized emulsification infrastructure. German metropolitan consumers demonstrate accelerating acceptance of precision fermentation lipid bases.
- Bars:Standard portion control format dominates retail shelf presence.
- Drops:Baking and confectionery ingredient applications favor bulk handling efficiency.
Bars retain the broadest manufacturing footprint. Powder is climbing the fastest among format investments.
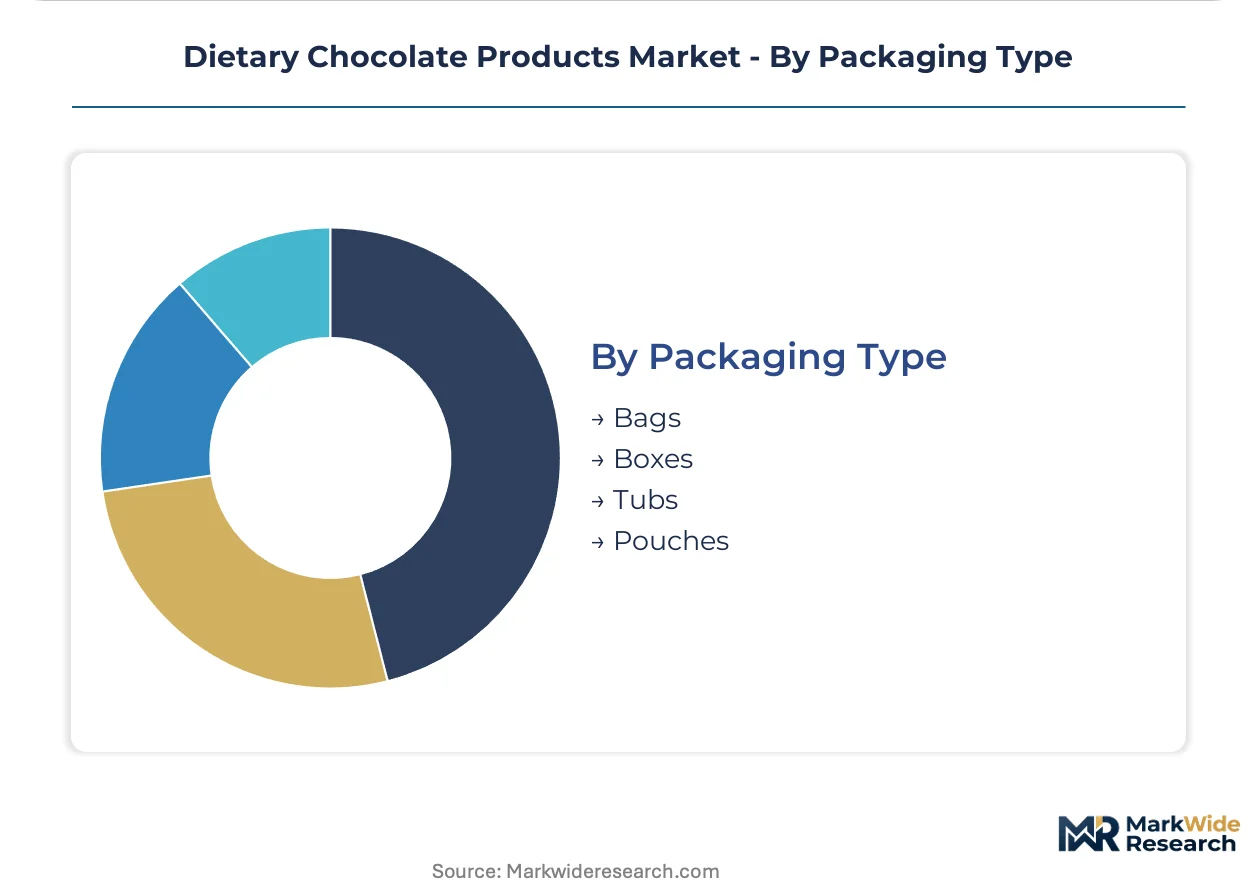
Packaging Type:
Distribution channel and consumption occasion dictate protective barrier requirements and unit economics.
- Pouches:Flexible film structures with modified atmosphere capabilities extend shelf life for high-cocoa formulations. Direct-to-consumer wellness platforms in UK urban markets favor lightweight shipping economics.
- Tubs:Rigid containment suits spread viscosity and institutional foodservice portions. Fitness center bulk procurement programs specify tamper-evident closures.
- Bags:Pillow and stand-up configurations dominate mass retail gravity-fed displays.
- Boxes:Premium gift and seasonal positioning commands structural rigidity for protection.
Bags carry the highest unit throughput. Pouches are gaining share fastest in channel displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers demonstrate stronger acceptance of precision fermentation lipids than Swiss buyers, while Japanese regulators maintain the most distinct functional food pathway worldwide. These divergent demand and policy environments create sharply differentiated investment priorities across national markets.
United States
Fitness centers in Los Angeles and New York Metro drive powder format demand through subscription nutrition platforms. FDA nutrient content claims enforcement shapes interstate labeling compliance for reduced-sugar variants. Pennsylvania and California processing clusters expand capacity for direct-to-consumer wellness channel fulfillment.
Germany
Health enthusiasts in Berlin and Munich prioritize EFSA-validated cardiovascular claims on high-cocoa formulations. EU Regulation 1924/2006 substantiation timelines force clinical validation infrastructure investment. Cologne and Hamburg heritage processors broaden supply-side capacity for clean-label dietary chocolate production.
Switzerland
Swissmedic oversight of functional food positioning intersects with cantonal food safety enforcement in Zurich and Geneva. Lindt and Sprungli anchors premium positioning through sustained conching technology investment. Vevey and Bern processing clusters command wage premiums for precision temperature control expertise.
Belgium
Front-of-pack Nutri-Score mandates reshape permissible formulation architectures in Brussels and Antwerp retail channels. EFSA health claim assessments determine which functional benefits manufacturers communicate to European consumers. Liège heritage processors leverage blockchain-enabled origin verification for price premiums.
Japan
Health-conscious consumers in Tokyo and Osaka accelerate acceptance of functional chocolate positioning. FOSHU regulatory pathway enables premium pricing for probiotic-enriched and reduced-sugar variants. Nagoya and Kyoto manufacturing clusters specialize in clinical nutrition applications with dietitian channel partnerships.
Dietary Chocolate Products Market Competitive Environment
Swiss and Belgian producers anchor the premium heritage tier; American and Japanese specialists hold distinct functional positioning segments. Market structure concentrates around integrated bean-to-bar processors with multi-continent infrastructure and regional specialists with regulatory-optimized portfolios. Three archetypes dominate: heritage European processors with conching expertise, Asian functional food specialists with FOSHU pathway access, and North American direct-to-consumer wellness platforms. Competitive moves center on clinical validation infrastructure buildout and precision fermentation lipid adoption.
Within the heritage processor tier, Barry Callebaut and Lindt and Sprungli exemplify integrated supply chain control with multi-continent bean-to-bar infrastructure. Meiji Holdings occupies a distinct position among Asia-Pacific functional food specialists leveraging Japan's FOSHU regulatory framework for premium therapeutic positioning.
| Leading Market Players |
|---|
| Barry Callebaut |
| Mondelez International |
| CEMOI Group |
| Guittard Chocolate |
| Gujarat Cooperative Milk Marketing Federation |
| Lindt and Sprungli |
| Pascha Chocolate |
| Meiji Holdings |
| Migros Cooperatives |
| Others |
Value Chain & Pricing Dynamics
Integrated bean-to-bar infrastructure across Swiss and Belgian heritage clusters anchors both supply security and premium pricing power for high-cocoa formulations. This vertical control over conching technology and origin-specific sourcing insulates EFSA-validated cardiovascular claim products from West African cocoa butter volatility while commanding shelf premiums in German retail channels.
Pricing Analysis
Capacity additions in Cologne and Hamburg are reshaping price floors for clean-label dietary chocolate production. Three-tier pricing structure across premium, standard, and economy levels differentiates EFSA-substantiated functional claims from commodity-adjacent reduced-sugar variants. Cost compression in the premium tier is intensifying as precision fermentation lipids bypass traditional cocoa butter dependencies. Health enthusiasts demonstrate lowest price sensitivity for blockchain-verified origin products, while retail consumers in mass channels drive volume at thinner margins.
Supply Chain Analysis
Regional distribution centers in Antwerp and Rotterdam feed hub-and-spoke patterns across EU retail networks. West African cocoa bean sourcing, Swiss conching equipment, and German precision fermentation lipid production form the tripartite input base. Single-source vulnerability in Ivory Coast and Ghana bean supply transmits directly to formulation cost volatility. Distribution runs through heritage processor direct accounts for institutional buyers and algorithm-curated wellness platforms for subscription consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation lipid adoption creates margin-expansion headroom by decoupling premium formulations from commodity cocoa butter exposure. This cost-down driver enables heritage processors to defend position while new entrants arbitrage supply constraints.
For Market Incumbents: Extend clinical validation infrastructure investments to preempt EFSA substantiation bottlenecks for novel bioactive compounds. Secure captive supply agreements for precision fermentation lipids before capacity constraints emerge. Counter precision fermentation entrants by emphasizing blockchain-verified bean-to-bar provenance as a non-replicable heritage asset. For New Entrants and Emerging Players: Japan's FOSHU regulatory pathway in Tokyo and Osaka opens a window for functional chocolate positioning without multi-year EFSA timelines. Target probiotic-enriched and reduced-sugar variants where heritage processors lack clinical nutrition partnerships. Deploy dietitian channel direct endorsement programs to bypass retail margin stacking and establish therapeutic credibility. For Investors and Strategic Acquirers: Roll-up economics work for regional functional food specialists with FOSHU pathway access because regulatory-optimized portfolios command scarcity premiums in East Asian markets. Five-to-ten year viability hinges on clinical validation infrastructure rather than formulation alone. Monitor EFSA health claim approval velocity as the inflection signal for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Infrastructure Buildout | EFSA-substantiated cardiovascular claims secure shelf differentiation in German and Belgian retail channels. |
| Precision Fermentation Lipid Adoption | Novel cocoa butter alternatives bypass West African supply constraints while enabling reduced-calorie formulation architectures. |
| Blockchain-Enabled Origin Verification | Bean-to-bar traceability systems command price premiums among Swiss heritage processors and health enthusiasts. |
| FOSHU Regulatory Pathway Navigation | Japan's functional food framework enables premium pricing for probiotic-enriched variants in Tokyo and Osaka markets. |
| Dietitian Channel Partnership Development | Direct professional endorsement programs bypass retail margin stacking for therapeutic positioning in clinical nutrition. |
Study Parameters
Direct dialogue with cocoa processing executives, regulatory affairs specialists at heritage European firms, fitness center nutrition program directors, and dietitian channel partners grounded qualitative findings in operational reality. Secondary validation drew from EFSA health claim registers, EU organic certification databases, FOSHU-approved product listings, and customs trade records for cocoa butter and cocoa bean flows. Bottom-up volume estimates from segment-level production capacity and top-down demand calibration from retail audit data were triangulated to constrain forecast variance.
Bottom-up modeling tracked high-cocoa, sugar-free, milk, and organic product types across powder, spread, bar, and drop formats through health enthusiast, dietitian, retail consumer, and fitness center end-use channels. Geographic splits reflected national regulatory frameworks including FDA nutrient content claim enforcement, EFSA substantiation timelines, and Japan's FOSHU approval pathways. CAGRs were derived from segment growth rate differentials applied to base-year market estimates across the analysis window. Forecast inputs incorporated precision fermentation lipid adoption curves and EU front-of-pack labeling mandate compliance costs.
Revisions become necessary when EFSA substantiation timelines extend beyond modeled assumptions, West African supply disruptions exceed historical volatility bands, or precision fermentation lipid regulatory classification shifts alter labeling requirements. Forecasts reflect documented assumptions about regulatory pathway access and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Confectionery Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Mints Market
Confectionery
Sugar Free Lollipops Market
Confectionery
US Dark Chocolate Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Low Calorie Nutella Market
Confectionery
Vegan Candies Market
Confectionery
Confectionery Fats Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
White Chocolate Market
Confectionery
Crunchy Chocolate Market