
 Ready to Serve Prefabricated Dishes Market | 2026-2036
Ready to Serve Prefabricated Dishes Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Serve Prefabricated Dishes Market Insights
Commercial kitchen labor shortages across North America and Western Europe is reorganizing how foodservice operators source prepared meal components, accelerating contract manufacturing partnerships with packaged food specialists. Nestlé leverages its frozen and chilled ready-meal infrastructure to secure long-term supply agreements with European retail banners. Tyson Foods anchors its position through backward integration into protein processing, giving it cost control over the primary input in prefabricated entrees. McCain Foods competes on manufacturing scale, operating production lines that switch between potato-centric frozen dinners and vegetable-based meal bowls.
Ready to serve prefabricated dishes comprise fully or partially cooked food formulations that require minimal consumer preparation, typically involving thermal processing, blast chilling, and modified-atmosphere or vacuum packaging to achieve shelf stability or frozen preservation. These products serve institutional buyers and retail consumers seeking meal solutions that reduce active cooking time to under five minutes. Frozen dinners occupy the largest revenue pool among product type segments, sustained by entrenched cold-chain logistics and consumer familiarity with microwave-reheat formats. Meal kits represent the fastest-expanding category, as subscription platforms and grocery retailers bundle pre-portioned ingredients with recipe instructions to capture younger demographics seeking perceived freshness without full scratch cooking. Online retailers within the distribution channel segment are capturing disproportionate growth, driven by direct-to-consumer fulfillment models that bypass traditional supermarket slotting fees.
FDA oversight of nutrition labeling and food safety modernization shapes product formulation and packaging claims for US-manufactured prefabricated dishes, while the EU's MDR and EFSA guidelines on novel foods influence ingredient approval timelines for European market entrants. China's SAMR enforces GB standards on prepackaged food labeling and additive limits, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon-footprint disclosure requirements that will determine which product lines retain shelf access in key retail channels.
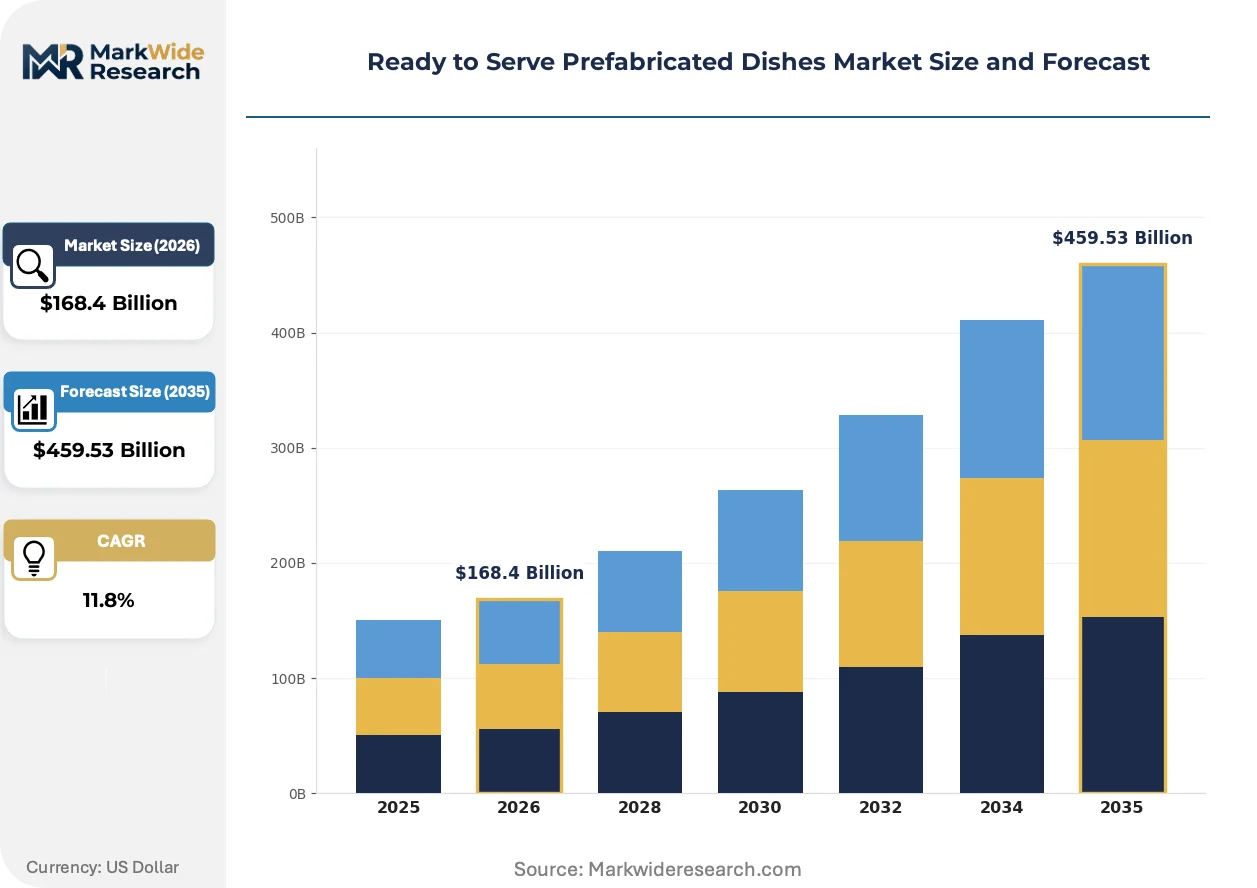
Market Dynamics
Commercial kitchen labor shortages across North America and Western Europe are reorganizing how foodservice operators source prepared meal components, accelerating contract manufacturing partnerships with packaged food specialists and reshaping procurement patterns across institutional channels.
Growth Catalysts
- Dual-income household density:Metropolitan corridors in the United States with concentrated professional employment are driving demand for sub-five-minute meal solutions that eliminate active cooking time.
- SAMR labeling tightening:China's State Administration for Market Regulation has mandated cleaner ingredient declarations for prepackaged foods, pushing manufacturers toward reformulation that appeals to health-conscious urban consumers.
- Blast chilling advancement:Thermal processing and modified-atmosphere packaging technologies are extending shelf stability without freezing, opening new retail placement opportunities for ambient meal formats.
Market Restraints
- Protein input volatility:Fluctuations in poultry and beef commodity markets compress margin predictability for entree-centric product lines dependent on animal protein formulations.
- Cold-chain infrastructure gaps:Frozen dinner distribution remains constrained in secondary cities across India and Southeast Asia where refrigerated logistics networks remain underdeveloped.
- Preservative regulatory friction:EFSA guidelines on novel food additives and EU MDR compliance timelines delay ingredient approval for European market entrants seeking clean-label positioning.
Strategic Opportunities
- Subscription platform expansion:Meal kit bundling of pre-portioned ingredients with recipe instructions is capturing younger demographics seeking perceived freshness without full scratch cooking.
- Corporate cafeteria outsourcing:Workplace dining facilities are shifting from in-house preparation to contracted shelf-stable meal procurement, creating institutional volume anchors.
- Front-of-pack labeling mandates:Evolving carbon-footprint disclosure requirements in EU member states will reward early adopters of transparent supply chain reporting with preferred retail placement.
Industry Challenges
- Refrigeration technician scarcity:Maintenance of blast chillers and modified-atmosphere packaging equipment requires specialized skills that food manufacturing regions struggle to source.
- Cross-format production complexity:Manufacturing lines switching between frozen dinners and vegetable-based meal bowls demand changeover protocols that reduce effective capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Serve Prefabricated Dishes Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $459.53 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwave Meals, Frozen Dinners, Instant Soups, Meal Kits Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Food Service Customer Type: Families, Singles, Senior Citizens, Students Packaging Type: Trays, Pouches, Cans, Bowls |
| Companies Covered | Nestlé, Conagra Brands, Kraft Heinz, Tyson Foods, Unilever, General Mills, Nomad Foods, McCain Foods, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Serve Prefabricated Dishes Market Trends and Innovations
Active thermal processing and packaging technologies are compressing preparation time requirements while regulatory pressure on ingredient transparency is forcing reformulation across multiple geographies. These forces are converging to reshape product development priorities and distribution channel economics.
High-pressure processing is displacing traditional thermal sterilization for refrigerated ready-meals. European retail banners and North American grocery chains are adopting this technology at accelerating pace to deliver extended shelf life without the texture degradation associated with conventional heat treatment. The structural consequence is compressing the quality gap between fresh-prepared and packaged alternatives, forcing traditional frozen dinner manufacturers to defend position through price repositioning.
China's GB standards enforcement on prepackaged food labeling and additive limits is tightening compliance requirements for multinational suppliers. Industrial consequence includes mandatory reformulation of preservative-dependent product lines and extended approval timelines for new ingredient introductions. Western multinational suppliers targeting Chinese urban clusters are responding by establishing dedicated regulatory affairs functions in Shanghai and Beijing to navigate SAMR interpretation variance.
Direct-to-consumer fulfillment models are bypassing traditional supermarket slotting fees and capturing disproportionate growth within distribution channels. Online retailers and subscription platforms are disrupting conventional grocery retail by aggregating niche dietary preferences and delivering customized meal solutions. This channel rotation is most visible in United States metropolitan corridors with high e-commerce penetration and dual-income household density, where convenience positioning outweighs price sensitivity.
Ready to Serve Prefabricated Dishes Market Segmentation
Segmentation reveals how procurement patterns diverge across institutional buyers versus retail consumers, and how packaging formats dictate cold-chain investment requirements. Manufacturers calibrate production capacity across these divides to match margin profiles with logistics infrastructure.
Product Type:
Frozen dinners and microwave meals dominate domestic consumption in established markets, while meal kits concentrate export-led growth into Asia-Pacific urban clusters.
- Frozen Dinners:Fully cooked entrees preserved through blast freezing and modified-atmosphere packaging, requiring sustained cold-chain integrity from production through retail display. Demand clusters in United States metropolitan corridors with entrenched frozen food retail infrastructure and dual-income household density.
- Meal Kits:Pre-portioned ingredient bundles with recipe instructions, emphasizing perceived freshness through refrigerated logistics rather than frozen preservation. Subscription platforms in Shanghai, Tokyo, and Singapore drive the steepest demand acceleration as younger demographics reject full scratch cooking.
- Microwave Meals:Shelf-stable or refrigerated single-serve formats optimized for sub-90-second thermal processing in commercial or residential microwave units.
- Instant Soups:Dehydrated or retort-pouched broth formulations with reconstitution requirements under three minutes.
Frozen dinners command the established base. The steepest expansion runs through meal kits.
Distribution Channel:
Channel selection determines working capital intensity, with food service and online retailers demanding opposite fulfillment architectures.
- Online Retailers:Direct-to-consumer platforms bypassing supermarket slotting fees through centralized fulfillment centers and last-mile cold-chain delivery. United States and Chinese urban clusters with high e-commerce penetration concentrate demand as convenience positioning outweighs price sensitivity.
- Food Service:Institutional procurement by quick-service restaurants, corporate cafeterias, and hospitality operators seeking shelf-stable meal components to offset commercial kitchen labor shortages.
- Supermarkets:Traditional brick-and-mortar retail with frozen and chilled section slotting governed by category management fees and promotional calendar alignment.
- Convenience Stores:Ambient and refrigerated grab-and-go placement targeting immediate consumption occasions in high-traffic urban locations.
Food service anchors institutional volume. Online retailers are climbing the fastest.
Customer Type:
Demographic targeting shapes formulation decisions around portion sizing, sodium content, and packaging accessibility.
- Singles:Single-serve formats with minimal preparation residue and disposal requirements, concentrated in urban rental markets across Germany, Japan, and the United States.
- Families:Multi-portion trays and value-oriented bundles targeting suburban household replenishment shopping patterns.
- Senior Citizens:Texture-modified and nutritionally fortified formulations with simplified opening mechanisms and extended shelf stability.
- Students:Price-sensitive single-serve options distributed through campus retail and meal plan integration.
Families represent the volume core. Singles are gaining share fastest.
Packaging Type:
Material selection drives recyclability compliance costs and microwave safety certification requirements across regulatory jurisdictions.
- Trays:Rigid polymer or aluminum containers for frozen and refrigerated entrees, dominant in North American and European retail.
- Pouches:Flexible retort or vacuum-sealed formats enabling vertical storage and reduced shipping cube, expanding in Asian markets.
- Bowls:Round rigid containers for soup and noodle applications, common in Japanese and South Korean convenience retail.
- Cans:Metal containment for ambient-stable soups and stews, constrained by recycling mandate compliance in EU member states.
Trays hold the installed base. Pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States households favor frozen microwave formats for speed. Chinese urban buyers gravitate toward meal kits emphasizing ingredient transparency. European procurement prioritizes clean-label positioning and carbon disclosure compliance.
United States
Dual-income households in metropolitan corridors drive demand for sub-five-minute meal solutions. FDA nutrition labeling modernization shapes reformulation priorities for sodium reduction and front-of-pack disclosure. Cold-chain logistics concentrate in Chicago, Dallas, and Los Angeles distribution hubs serving retail banners.
China
Younger demographics in Shanghai, Beijing, and Shenzhen reject full scratch cooking while demanding ingredient provenance clarity. SAMR enforcement of GB standards on prepackaged food labeling accelerates manufacturer reformulation away from preservative-dependent lines. Yangtze River Delta production clusters host dedicated regulatory affairs functions navigating interpretation variance.
Germany
Single-person households in Berlin, Munich, and Hamburg rental markets favor minimal-preparation formats with reduced packaging residue. EFSA guidelines on novel food additives delay approval timelines for clean-label entrants. Bavaria and North Rhine-Westphalia host contract manufacturing partnerships with retail banners seeking shelf-stable meal components.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya drive texture-modified and nutritionally fortified formulations. METI standards on food manufacturing equipment certification shape blast chiller and modified-atmosphere packaging investment. Kanto and Kansai industrial corridors concentrate production of round rigid bowl formats for convenience retail.
India
Urban professional households in Mumbai, Delhi-NCR, and Bangalore generate emerging demand for refrigerated ready-meals. FSSAI enforcement of packaged food safety standards constrains preservative use in ambient formats. Maharashtra and Karnataka cold-chain infrastructure gaps limit frozen dinner distribution to primary cities.
Ready to Serve Prefabricated Dishes Market Competitive Landscape
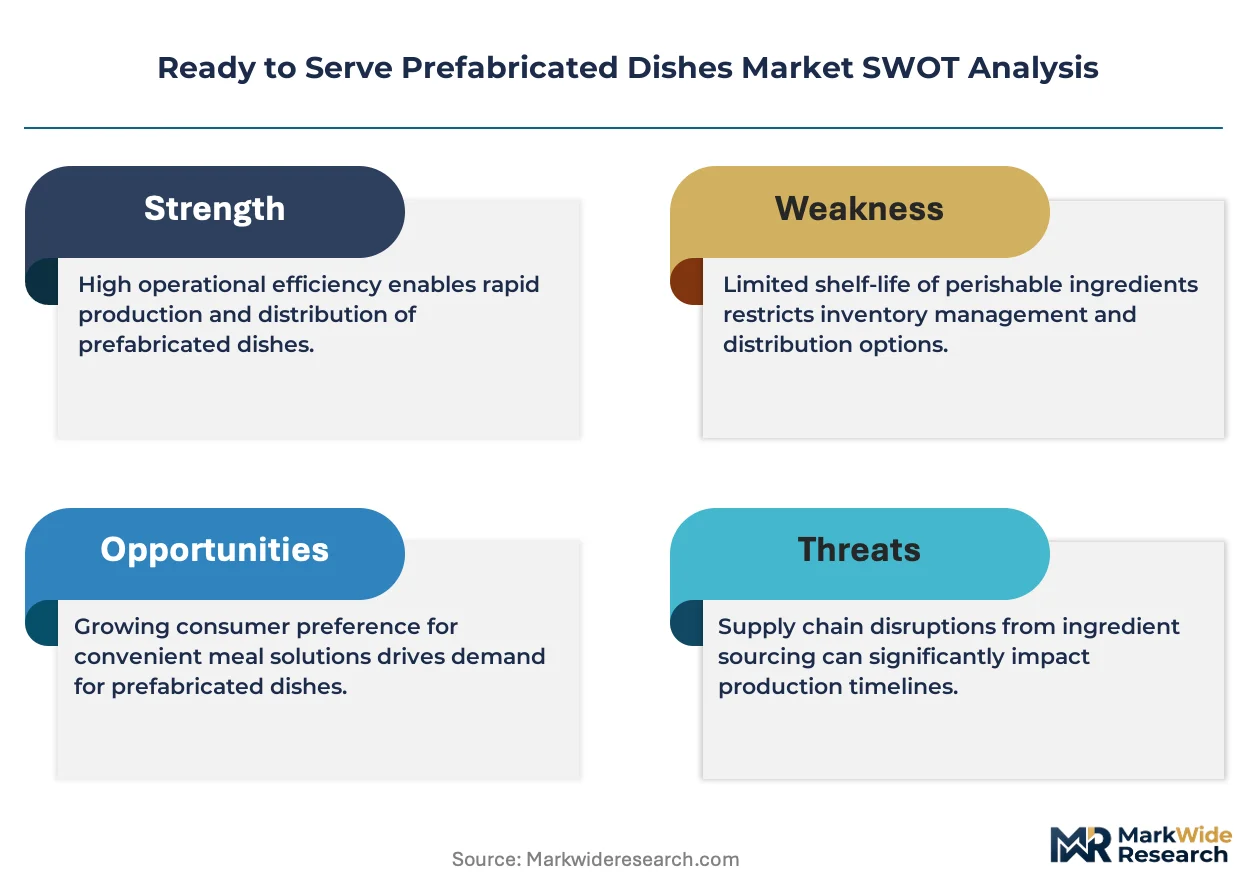
A small set of integrated leaders sits above a broader specialist tier in this market structure. Multinational packaged food conglomerates leverage frozen and chilled infrastructure to secure long-term retail supply agreements. Mid-scale protein processors and vegetable processors compete through backward integration into primary input control. Dominant competitive moves include capacity expansion in blast chilling and modified-atmosphere packaging, plus strategic partnerships between contract manufacturers and foodservice operators offsetting commercial kitchen labor shortages.
Among Switzerland-based conglomerates, Nestlé occupies a position exemplifying integrated frozen and chilled ready-meal infrastructure deployment. US-based Tyson Foods represents protein-centric backward integration archetypes, while Canadian-based McCain Foods sits within the scale-driven manufacturing tier. These three entities anchor distinct competitive vectors without exhausting the participant base.
| Leading Market Players |
|---|
| Nestlé |
| Conagra Brands |
| Kraft Heinz |
| Tyson Foods |
| Unilever |
| General Mills |
| Nomad Foods |
| McCain Foods |
| Danone |
| Others |
Pricing and Supply Chain Analysis
FDA nutrition labeling modernization gates both supplier qualification and price differentiation simultaneously, as compliance investments separate certified manufacturers from commodity processors while enabling premium positioning through clean-label claims.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement between quick-service restaurant chains and contract manufacturers, locking volume commitments that insulate against protein commodity swings. Price differentiation rests on certification tier and cold-chain reliability rather than brand equity alone. Cost compression in economy-tier frozen dinners intensifies as private-label entrants replicate blast-chilling capabilities. Corporate cafeteria operators exhibit lowest price sensitivity due to labor-cost offset calculus, while student-facing convenience retail segments demand maximum unit economy.
Supply Chain Analysis
Strategic stockpiling of protein inputs characterizes manufacturer inventory strategy, buffering against poultry and beef commodity volatility that would otherwise destabilize margin structures. Production concentrates in the United States, China, and Germany, each anchoring distinct regional cold-chain hubs. Raw material dependencies center on animal protein streams, modified-atmosphere packaging films, and blast-chilling equipment components. Single-source vulnerability runs through specialized refrigeration technician labor pools. Distribution feeds from centralized production facilities into retail banner distribution centers and direct-to-consumer fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as subscription meal-kit ecosystems aggregate fragmented consumer preferences into addressable demand pools, creating interoperability standards between recipe content, ingredient sourcing, and last-mile logistics.
For Market Incumbents: Consolidate manufacturing capacity in Yangtze River Delta and North American Midwest corridors to capture scale efficiencies against emerging contract manufacturing entrants. Deepen backward integration into protein processing to defend margin structures against commodity volatility. Prioritize SAMR regulatory affairs investment as Chinese labeling enforcement accelerates reformulation costs for unprepared competitors. For New Entrants and Emerging Players: Anchor in refrigerated ready-meal segments where high-pressure processing technology gaps create temporary shelter from entrenched frozen dinner incumbents. Target Indian metropolitan corridors—Mumbai, Delhi-NCR, Bangalore—where cold-chain infrastructure underdevelopment has suppressed multinational penetration. Pursue direct-to-consumer fulfillment models that bypass supermarket slotting fee structures dominating established markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blast-chilling and modified-atmosphere packaging equipment tiers, favoring scaled operators over asset-light challengers. Acquisition candidates should demonstrate established regulatory affairs functions in both FDA and SAMR jurisdictions. Monitor EFSA novel food additive approval velocity as inflection indicator for clean-label positioning viability in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | European retail banners deploy HPP to compress quality gaps between fresh-prepared and packaged alternatives. |
| Backward Integration into Protein Processing | Tyson Foods anchors cost control over primary input in prefabricated entrees through captive supply. |
| Direct-to-Consumer Fulfillment Buildout | Online retailers bypass supermarket slotting fees in United States metropolitan corridors with high e-commerce penetration. |
| SAMR Regulatory Affairs Investment | Western multinationals establish dedicated Shanghai and Beijing functions to navigate GB standards interpretation variance. |
| Corporate Cafeteria Contract Manufacturing | Workplace dining facilities shift from in-house preparation to contracted shelf-stable meal procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with food manufacturing executives, regulatory affairs specialists, and retail category buyers; and secondary validation through FDA nutrition labeling filings, SAMR GB standards documentation, and cold-chain logistics trade data. Bottom-up triangulation across production capacity estimates and top-down reconciliation against retail banner procurement volumes anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, distribution channel, packaging format, and customer demographic cluster. CAGRs derived from regression analysis against dual-income household density indices and e-commerce penetration rates. Forecast inputs incorporated blast-chilling equipment installation trajectories and protein commodity futures curve assumptions.
Decision-makers should treat outputs as directional under sustained cold-chain infrastructure investment and stable regulatory enforcement intensity assumptions; material deviation would warrant model refresh. Revision becomes warranted when SAMR labeling interpretation variance or EFSA novel food additive approval delays cross thresholds that reshape manufacturer reformulation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
North America Soup Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Tomato Puree Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
South America Soup Market
Processed Foods
United States Ice Cream Market
Processed Foods
Industrial Margarine Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Noodles Market
Processed Foods
Fat Free Food Market
Processed Foods
Tomato Paste Market