
 Food Stabilizer Systems Market | 2026-2036
Food Stabilizer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Food Stabilizer Systems Market Foresight
China is tilting toward expanded hydrocolloid extraction capacity to serve regional dairy and beverage formulators. Cargill Incorporated leverages its integrated agricultural supply chain to control raw material costs for pectin and cellulose derivatives. Palsgaard A/S specializes in emulsifier-stabilizer blends for plant-based applications, while Kerry Group plc sustains R&D intensity across clean-label texture solutions.
Food stabilizer systems comprise synergistic blends of hydrocolloids, emulsifiers, enzymes, and acidity regulators designed to control viscosity, prevent syneresis, and maintain shelf-stable texture in processed foods. These systems typically function at concentrations between 0.1% and 2.0% by weight, with hydrocolloids such as guar gum and xanthan gum providing water-binding matrices that respond to ionic strength and thermal processing. Hydrocolloids occupy the largest value share due to their versatility across dairy and bakery matrices, while emulsifiers capture premium margins in meat alternatives where fat-protein stabilization proves technically demanding. Enzymes represent the fastest-expanding category as manufacturers replace chemical modifiers with biocatalytic texture improvement.
The FDA governs stabilizer safety through GRAS determinations and food additive petitions, while the USDA oversees label claims for organic and clean-label positioning that directly influence ingredient selection. EFSA and EMA frameworks in Europe enforce stricter purity standards for hydrocolloid sources, compelling suppliers to validate traceability from seaweed farms or fermentation tanks. Stakeholders must monitor evolving definitions of natural and clean-label across jurisdictions to anticipate reformulation mandates before they disrupt existing supply agreements.
Market Dynamics
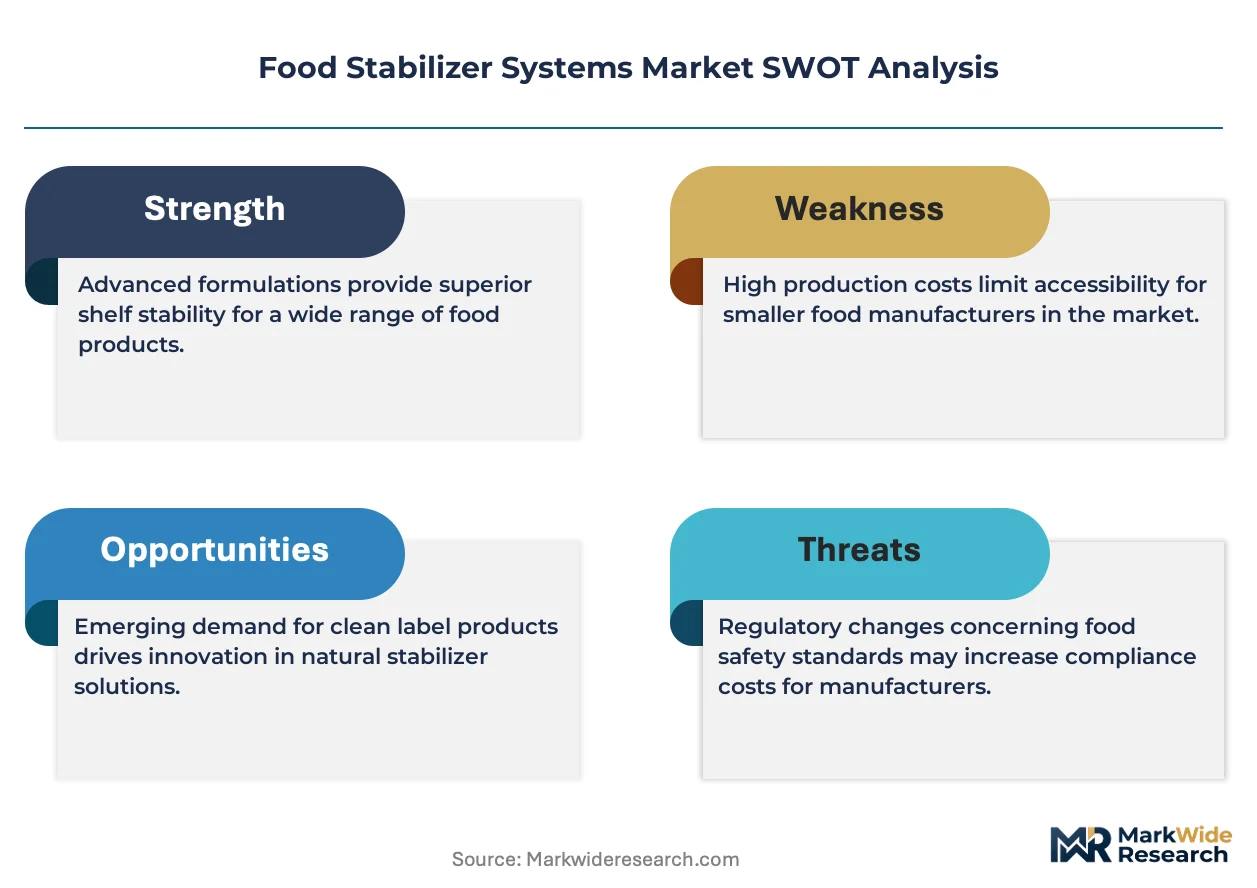
Clean-label regulatory mandates across multiple jurisdictions are forcing processed food manufacturers to abandon synthetic hydrocolloids in favor of fermentation-derived and seaweed-extracted alternatives, restructuring supplier relationships and raw material sourcing patterns.
Growth Catalysts
- EU Green Deal agricultural targets:The EU's Farm to Fork strategy mandates 25% organic farming coverage by 2030, accelerating demand for certified-natural stabilizers in dairy and plant-based meat matrices.
- Plant-based meat formulation complexity:Fat-protein stabilization in extruded vegetable proteins requires sophisticated emulsifier-hydrocolloid blends that command premium positioning in retail and foodservice channels.
- Enzymatic texture modification:Transglutaminase and amylase biocatalysts replace chemical cross-linkers in clean-label bakery and noodle applications, expanding the enzyme segment's addressable market.
Market Restraints
- Seaweed harvest volatility:Carrageenan and agar supply concentrates in Philippine and Indonesian coastal waters, exposing formulators to climate-driven crop failures and price spikes.
- Guar gum import dependency:Over 80% of global guar gum originates from Rajasthan and Gujarat in India, creating single-origin risk for hydraulic fracturing competition and monsoon-dependent harvests.
- EFSA purity standard escalation:European Food Safety Authority's tightening heavy metal and microbial specifications for hydrocolloid sources extend validation timelines and raise testing costs for suppliers.
Strategic Opportunities
- Fermentation-derived hydrocolloids:Precision fermentation of xanthan gum and gellan gum in controlled bioreactors decouples supply from agricultural weather patterns and enables consistent quality grading.
- South Korean functional beverage expansion:MFDS-approved texture modifiers for probiotic and collagen drinks create specialized demand for low-viscosity hydrocolloid systems with suspension stability.
- Cell-cultured meat scaffolding:Emerging cultivated protein producers require novel stabilizer systems for growth medium viscosity control and final product texture engineering.
Industry Challenges
- Fermentation scale-up engineering:Commercial bioreactor capacity for food-grade hydrocolloids lags pharmaceutical standards, requiring capital-intensive facility construction and sterile process validation.
- Cross-jurisdictional natural definition alignment:Divergent FDA GRAS, EFSA, and FSSAI interpretations of "natural" and "clean-label" force parallel formulation tracks and complicate global product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Stabilizer Systems Market |
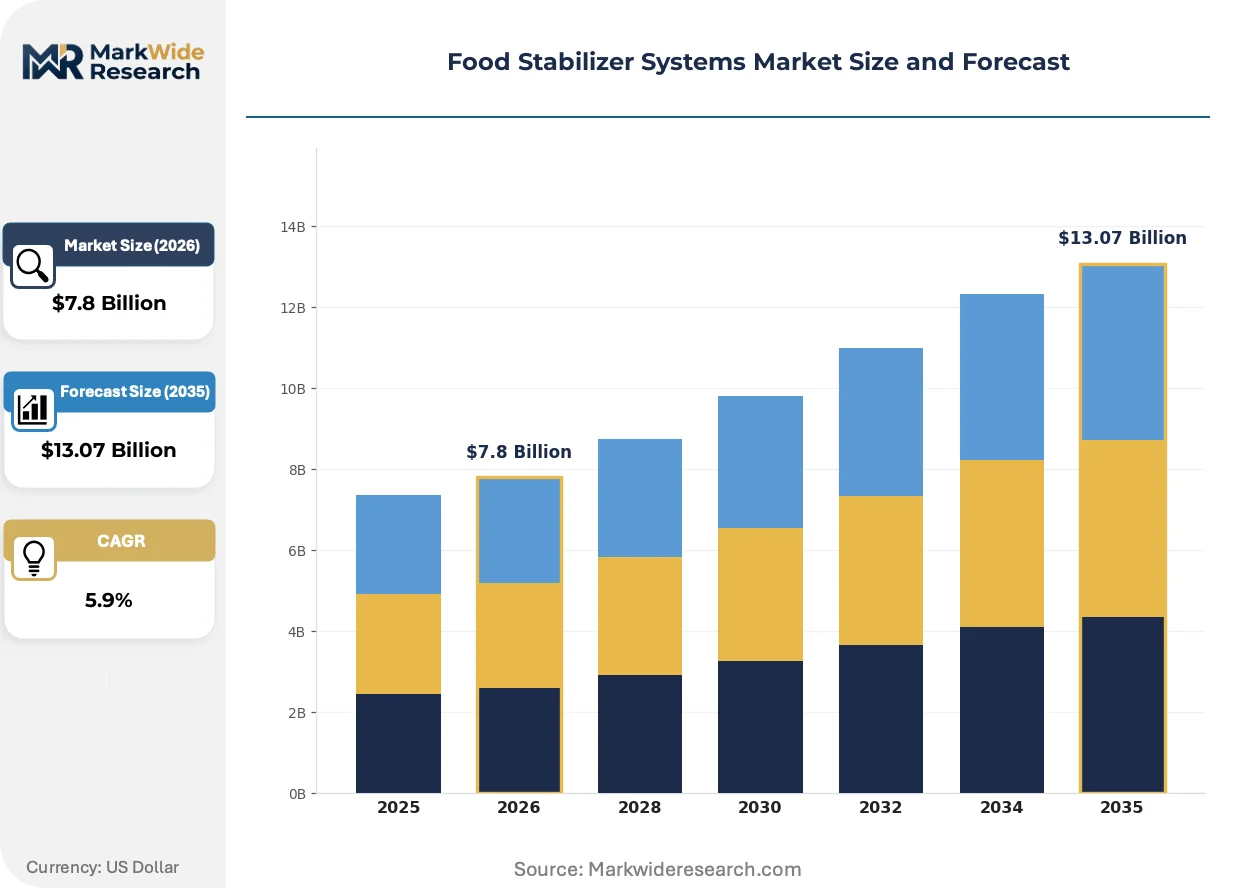
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Hydrocolloids, Enzymes, Antioxidants, Acidity Regulators Application: Dairy Products, Bakery Items, Meat Alternatives, Beverages, Confectionery End User: Food Manufacturers, Ingredient Suppliers, Foodservice Outlets, Specialty Bakeries Packaging Type: Powder, Liquid, Granular, Tablet, Sachet |
| Companies Covered | Archer Daniels Midland Company, CP Kelco, Cargill Incorporated, DuPont de Nemours Inc., Palsgaard A/S, Ingredion Incorporated, Kerry Group plc, BASF SE, Tate & Lyle plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Stabilizer Systems Market Shifts & Advancements
Biotechnology-enabled ingredient production and regulatory harmonization efforts are converging to redefine how texture-modifying systems are manufactured, certified, and deployed across food categories.
Precision fermentation of hydrocolloids is migrating from pilot-scale demonstration to industrial commercialization. Ginkgo Bioworks and similar synthetic biology platforms engineer microbial strains for customized polysaccharide structures. This technology is compressing the traditional agricultural supply chain for xanthan and gellan gums, enabling manufacturers to specify molecular weight distributions and functional properties rather than accepting batch-to-batch harvest variation.
EFSA's updated guidance on novel food ingredients and enzyme preparations tightens toxicological data requirements for biocatalytic texture modifiers. The industrial consequence is extended approval timelines for transglutaminase and amylase variants not previously consumed in the EU. Bakery and pasta manufacturers in Germany and Italy are responding by accelerating domestic enzyme screening programs and building regulatory dossiers ahead of submission deadlines.
Direct procurement relationships between food manufacturers and fermentation technology providers are displacing traditional ingredient distributor intermediaries. Large dairy and alternative protein processors in the United States negotiate supply agreements directly with biotech firms for customized hydrocolloid blends. This channel compression is most visible in California's plant-based protein cluster, where formulators prioritize technical collaboration over catalog purchasing.
Food Stabilizer Systems Market Segmentation
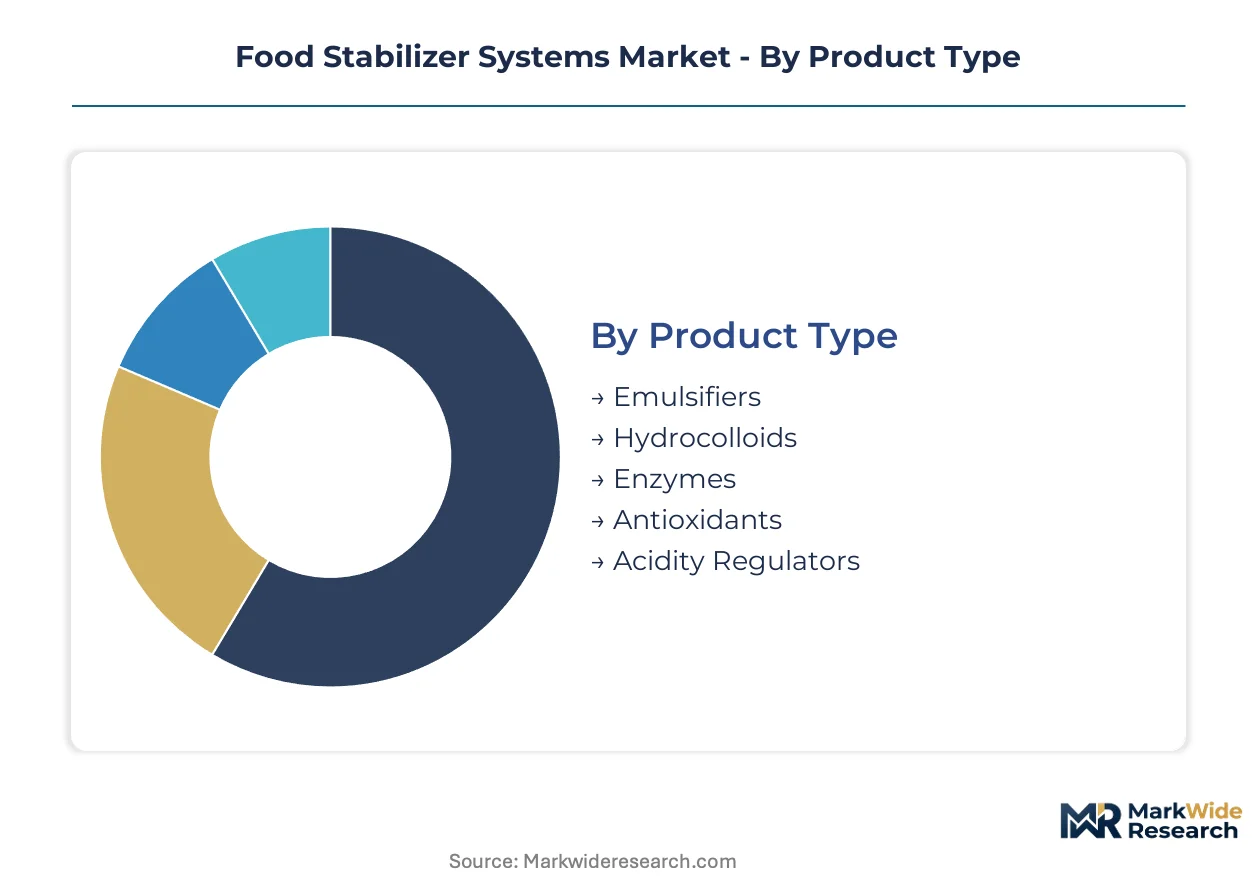
Stabilizer system selection hinges on matrix compatibility, processing conditions, and label-positioning requirements. Manufacturers configure blends across multiple classification dimensions to optimize cost-performance ratios for specific food categories.
Product Type:
Mature hydrocolloid technologies coexist with emerging enzymatic solutions, creating a bifurcated supply landscape.
- Hydrocolloids:Polysaccharide matrices from guar, xanthan, and cellulose derivatives bind water and control viscosity across dairy and bakery applications. Carrageenan and pectin dominate dairy stabilization in the United States and European Union, though EFSA purity mandates are forcing supplier validation upgrades.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates stabilize fat-protein interfaces in plant-based meat extrusion. Demand concentrates in California's alternative protein cluster where texture optimization commands premium formulation spending.
- Enzymes:Transglutaminase and amylase biocatalysts replace chemical cross-linkers in clean-label positioning.
- Antioxidants:Ascorbates and tocopherols extend shelf stability in lipid-rich matrices.
- Acidity Regulators:Citric acid and phosphates maintain pH stability in beverage systems.
Hydrocolloids handle the majority of throughput; enzymes are gaining share fastest as clean-label mandates intensify.
Application:
Volume distribution tracks processed food consumption patterns, with emerging categories reshaping stabilizer blend specifications.
- Dairy Products:Yogurt, ice cream, and cheese matrices require syneresis control and freeze-thaw stability. Hydrocolloid-enzyme combinations dominate European formulations where EFSA enforces strict additive purity standards.
- Meat Alternatives:Extruded vegetable proteins demand sophisticated emulsifier-hydrocolloid blends for fat-protein stabilization and fibrous texture replication. Plant-based meat alternatives represent the fastest-expanding end-use application for stabilizer systems.
- Bakery Items:Amylase-modified starches and hydrocolloid gums extend shelf life in packaged bread.
- Beverages:Low-viscosity hydrocolloids maintain suspension stability in functional drinks.
- Confectionery:Gelling agents control texture in gummies and jellies.
Dairy Products anchor volume demand; Meat Alternatives show the steepest expansion trajectory.
End User:
Procurement sophistication varies dramatically across customer tiers, from technical specification buyers to price-driven commodity purchasers.
- Food Manufacturers:Large-scale processors in the United States negotiate direct supply agreements with fermentation technology providers for customized hydrocolloid blends. Technical collaboration supersedes catalog purchasing in California's plant-based protein cluster.
- Ingredient Suppliers:Distributors and blenders aggregate volume across multiple hydrocolloid sources to serve mid-tier formulators.
- Foodservice Outlets:Commercial kitchens require pre-blended stabilizer systems for consistency in high-volume preparation.
- Specialty Bakeries:Artisan producers seek clean-label enzymatic solutions for texture modification without synthetic additives.
Food Manufacturers concentrate procurement volume; Specialty Bakeries are expanding most quickly as clean-label positioning penetrates premium segments.
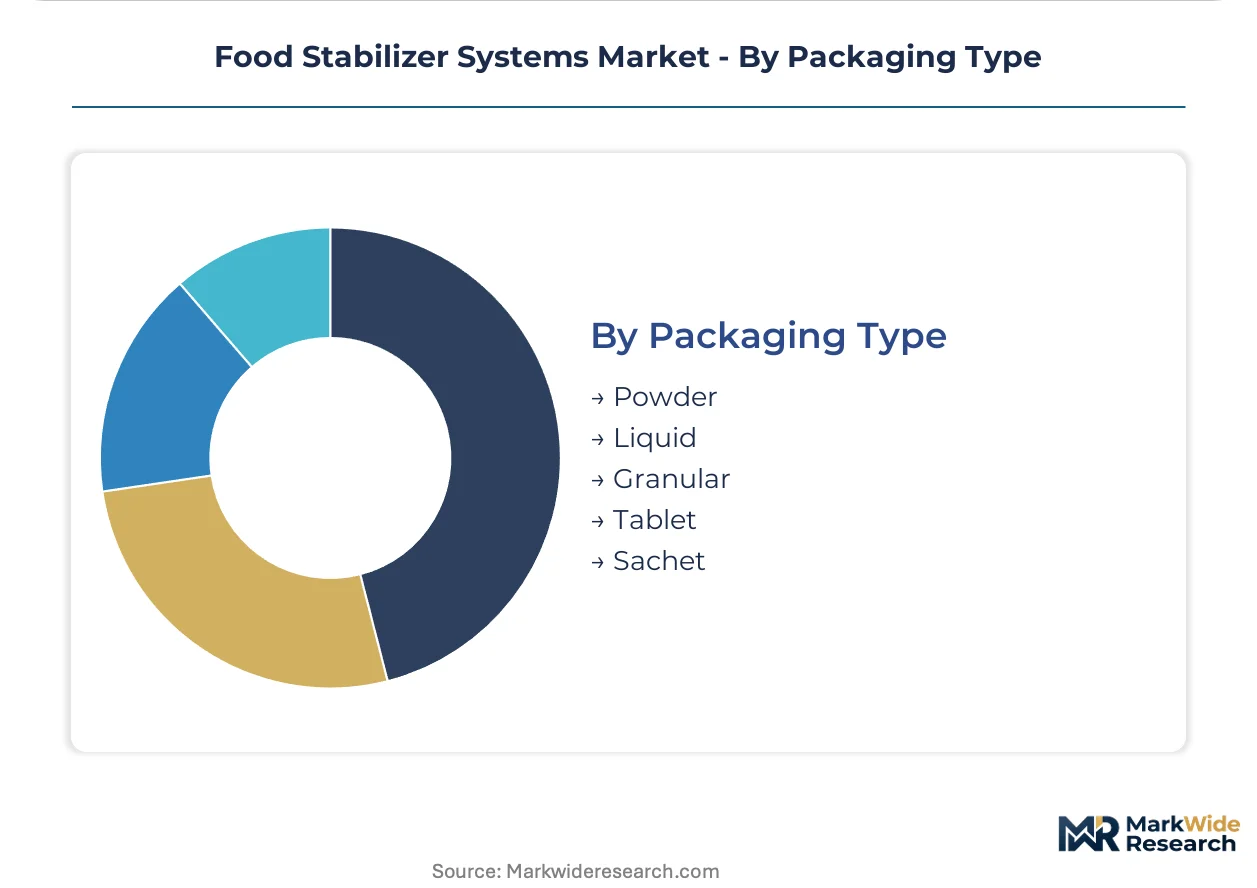
Packaging Type:
Format selection balances dispersion efficiency, shelf stability, and handling economics across manufacturing environments.
- Powder:Dried hydrocolloid and emulsifier blends dominate bulk industrial procurement due to extended shelf stability and lower shipping costs. Most guar gum and xanthan gum moves in powder form to dairy and bakery processors.
- Liquid:Pre-hydrated emulsifier concentrates accelerate production line integration for beverage and sauce manufacturers.
- Granular:Intermediate dispersion properties suit mid-scale bakery operations.
- Tablet:Unit-dose formats serve small-batch foodservice and specialty applications.
- Sachet:Pre-measured single-use packets target artisan and test-kitchen environments.
Powder handles the majority of throughput; Liquid is climbing the fastest as continuous processing lines proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrocolloid extraction capacity clusters in coastal zones and agricultural belts where climate and cultivation economics align. Manufacturers calibrate supply agreements around harvest reliability and regulatory compliance rather than transport cost alone.
United States
Processed food manufacturers in the Midwest and California's alternative protein corridor drive demand for texture optimization systems. The FDA governs stabilizer safety through GRAS determinations that influence ingredient selection timelines. Chicago and Minneapolis anchor dairy formulation clusters where hydrocolloid-enzyme combinations dominate yogurt and ice cream production.
Germany
Bakery and pasta manufacturers accelerate domestic enzyme screening programs ahead of EFSA submission deadlines for biocatalytic texture modifiers. The EU Green Deal's Farm to Fork strategy mandates organic farming coverage expansion that reshapes stabilizer sourcing requirements. Bavaria's food technology institutes collaborate with industrial bakers on clean-label reformulation protocols.
China
Dairy and beverage formulators in the Yangtze River Delta and Pearl River Delta expand hydrocolloid extraction capacity to serve regional processing growth. SAMR enforces food additive purity standards that parallel EFSA specifications for heavy metal content. Zhengzhou and Shanghai concentrate blending operations for guar gum and xanthan gum distribution.
India
Rajasthan and Gujarat supply over 80 percent of global guar gum, creating single-origin exposure for hydraulic fracturing competition and monsoon-dependent harvests. FSSAI interpretations of natural and clean-label diverge from FDA and EFSA frameworks, forcing parallel formulation tracks. Ahmedabad and Jodhpur cluster gum processing and export logistics infrastructure.
South Korea
Functional beverage producers seek MFDS-approved texture modifiers for probiotic and collagen drink applications. The regulator's novel food ingredient pathway creates specialized demand for low-viscosity hydrocolloid systems with suspension stability. Seoul's beverage innovation district hosts formulators developing next-generation texture solutions for Asian market export.
Food Stabilizer Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on raw material extraction and fermentation technology. The market structures around three archetypes: agricultural commodity processors controlling pectin and cellulose supply chains, precision fermentation technology providers engineering microbial strains for customized polysaccharides, and emulsifier-hydrocolloid blenders serving plant-based protein formulators. Competitive moves concentrate on backward integration into seaweed farming and fermentation capacity expansion, plus direct procurement relationships that displace traditional distributor intermediaries.
Among agricultural supply chain operators, Cargill Incorporated exemplifies the integrated commodity processor archetype with upstream control over raw material costs. Precision fermentation specialists include CP Kelco and DuPont de Nemours Inc., representing the biotechnology-enabled production tier that decouples hydrocolloid supply from agricultural weather patterns. Kerry Group plc occupies a position within the clean-label texture solutions segment, serving dairy and alternative protein manufacturers seeking regulatory-compliant formulation support.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| CP Kelco |
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Palsgaard A/S |
| Ingredion Incorporated |
| Kerry Group plc |
| BASF SE |
| Tate & Lyle plc |
| Others |
Supply & Pricing Matrix
Rajasthan and Gujarat guar gum concentration anchors upstream pricing power for hydrocolloid processors, while fermentation-derived alternatives capture premium positioning downstream. Margin pools sit with bioreactor operators who decouple supply from monsoon-dependent agricultural cycles.
Pricing Analysis
EFSA purity standard escalation dictates the pricing tier structure across European supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived hydrocolloids from certified-natural seaweed extracts and commodity-grade agricultural gums. Pricing pressure stems from hydraulic fracturing competition for guar gum feedstock. Specialty bakeries exhibit highest price sensitivity; plant-based meat manufacturers accept premium positioning for technical performance.
Supply Chain Analysis
Extended payment terms from large dairy processors in the United States and Germany strain working capital for mid-tier ingredient suppliers. Raw material sourcing draws from Philippine carrageenan farms, Indian guar gum processing clusters, and Chinese xanthan gum fermentation facilities. Single-source vulnerability concentrates in Rajasthan agricultural belts where monsoon failure disrupts global supply. Distribution runs through direct procurement relationships that displace traditional distributor intermediaries in California's alternative protein corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision fermentation platforms that engineer microbial strains for customized polysaccharide structures. Enzymatic biocatalysts threaten traditional hydrocolloid positioning in clean-label bakery applications.
For Market Incumbents: Insulate core hydrocolloid franchises through backward integration into seaweed farming operations in Philippine and Indonesian coastal zones. Secure captive fermentation capacity before bioreactor construction costs escalate. The priority lever rests on direct supply agreements with California plant-based protein formulators that displace distributor intermediaries.
For New Entrants and Emerging Players: Establish a beachhead in South Korean functional beverage applications where MFDS-approved texture modifiers command specialized demand. Target white-space opportunities in cell-cultured meat scaffolding for growth medium viscosity control. A technical collaboration go-to-market approach with Seoul beverage innovation clusters accelerates regulatory pathway navigation.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation technology providers with demonstrated strain engineering capabilities and sterile process validation. Long-term viability over the coming decade hinges on decoupling hydrocolloid supply from agricultural weather exposure. Watch for EFSA novel food ingredient approval timelines as an inflection indicator for enzymatic texture modifier market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | CP Kelco and DuPont bioreactor investments decouple xanthan gum supply from Rajasthan monsoon cycles. |
| Seaweed Farming Backward Integration | Cargill coastal lease agreements in Philippine waters secure carrageenan raw material traceability for EFSA compliance. |
| Direct Procurement Channel Development | Kerry Group technical collaboration agreements with California plant-based protein formulators displace distributor intermediaries. |
| Enzymatic Texture Modifier R&D | Palsgaard transglutaminase screening programs address clean-label reformulation mandates in German bakery applications. |
| Regulatory Dossier Preparation | Ingredient suppliers build EFSA submission packages ahead of tightened toxicological data requirements for biocatalytic modifiers. |
Research Methodology
Cross-validation between primary interviews with food manufacturer procurement directors and secondary analysis of FDA GRAS filings anchors the qualitative findings. Stakeholder engagement encompassed dairy formulators in Chicago and Minneapolis, plant-based protein R&D leads in California, hydrocolloid extraction facility managers in Zhengzhou, and regulatory affairs specialists navigating EFSA novel food pathways. Secondary sources included SAMR food additive purity standards, EU Farm to Fork strategy documentation, customs records tracking guar gum export volumes from Gujarat, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across hydrocolloid, emulsifier, and enzyme product categories.
Calibration against historical capacity expansion timelines and regulatory approval duration patterns shaped the projection framework. Segmentation dimensions encompassed product type, application matrix, end-user procurement sophistication, and packaging format. CAGRs derived from weighted average growth contributions across dairy, meat alternative, bakery, and beverage end-use segments. Industry-specific inputs included fermentation scale-up engineering timelines and EFSA purity standard escalation trajectories.
Sensitivities concentrate around monsoon variability in Indian guar gum belts, bioreactor construction cost inflation, and divergent natural definition interpretations across FDA, EFSA, and FSSAI jurisdictions. Forecasts reflect documented assumptions regarding regulatory harmonization pace and precision fermentation commercialization timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Food Supplement Ingredients Market