
 Fermented Foods Market | 2026-2036
Fermented Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Foods Market Intelligence
South Korea's kimchi infrastructure expansion is reshaping regional supply dynamics for fermented vegetables. Groupe Lactalis S.A. leverages its dairy fermentation expertise to dominate European yogurt value chains. Danone S.A. anchors its portfolio in probiotic science, while Nestlé S.A. extends its reach through shelf-stable fermented formats across emerging markets.
Fermented foods denote products transformed by controlled microbial activity—lactic acid bacteria, yeasts, or molds—operating at temperatures between 20°C and 45°C to develop acidity, texture, and bioactive compounds. These processes yield preserved foods with enhanced digestibility, extended shelf stability, and documented contributions to gastrointestinal microbiome diversity. Yogurt occupies the largest margin pool within product type segments due to established dairy economies and premium probiotic positioning. Kefir represents the fastest-expanding liquid format, while specialty stores within distribution channels capture disproportionate value through curated artisan positioning and education-intensive purchasing environments.
The FDA regulates live-and-active culture claims in the United States, compelling substantiation of colony-forming unit counts at expiration. EFSA's health claim assessments in Europe restrict specific probiotic benefit language, reshaping product marketing and R&D investment toward strain-specific clinical validation. Stakeholders must monitor evolving strain-level regulatory thresholds across jurisdictions to align pipeline development with enforceable compliance frameworks.
Market Dynamics
FDA's live-and-active culture labeling standards are compressing formulation timelines and forcing manufacturers to validate colony-forming unit counts at expiration, reshaping R&D investment toward strain-specific clinical trials.
Growth Catalysts
- MFDS export certification frameworks:South Korea's streamlined kimchi export protocols are accelerating cross-border fermented vegetable distribution into Japan and Southeast Asian retail channels.
- Gut microbiome research pipelines:Academic institutions and food science labs are generating peer-reviewed data on lactic acid bacteria strains, enabling probiotic health claims that health stores use to justify premium shelf placement.
- Temperature-controlled fermentation:Precision-controlled 20°C to 45°C processing systems are reducing batch variability and enabling artisan producers to scale without sacrificing bioactive compound consistency.
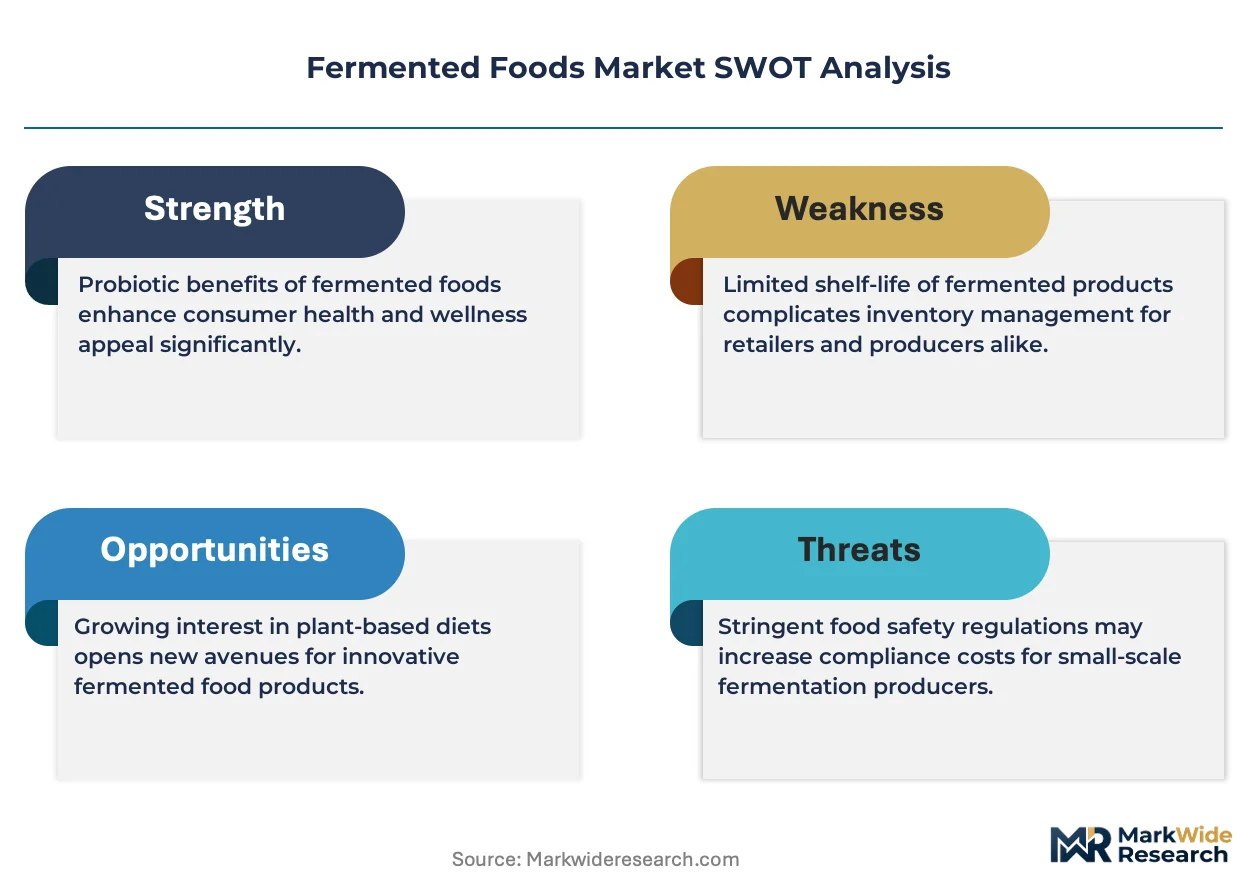
Market Restraints
- Live culture stability costs:Cold chain requirements for maintaining viable probiotic counts through distribution impose logistics premiums that compress margins in ambient retail channels.
- EFSA health claim restrictions:Europe's stringent substantiation requirements for specific probiotic benefits limit marketing language and force reformulation toward generic wellness positioning.
- Dairy input volatility:Milk powder and cream supply fluctuations in New Zealand and Australia create margin pressure for yogurt and kefir producers locked into annual retail pricing contracts.
Strategic Opportunities
- Indonesia's halal certification pathway:The country's expanding middle-class appetite for functional foods creates first-mover advantage for fermented products securing MUI halal approval.
- Shelf-stable fermentation formats:Retort and aseptic processing innovations are opening military, disaster relief, and remote mining camp procurement channels previously closed to live-culture products.
- Direct-to-subscription models:Curated monthly fermentation boxes bypass conventional retail slotting fees while capturing recurring revenue from gut-health committed households in urban Australia.
Industry Challenges
- Strain banking and IP fragmentation:Proprietary lactic acid bacteria deposits across competing culture collections create licensing complexity for multi-regional product launches.
- Traditional fermentation knowledge attrition:Aging master fermenters in Korean and Japanese artisan facilities are retiring without documented standard operating procedures, threatening batch consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Foods Market |
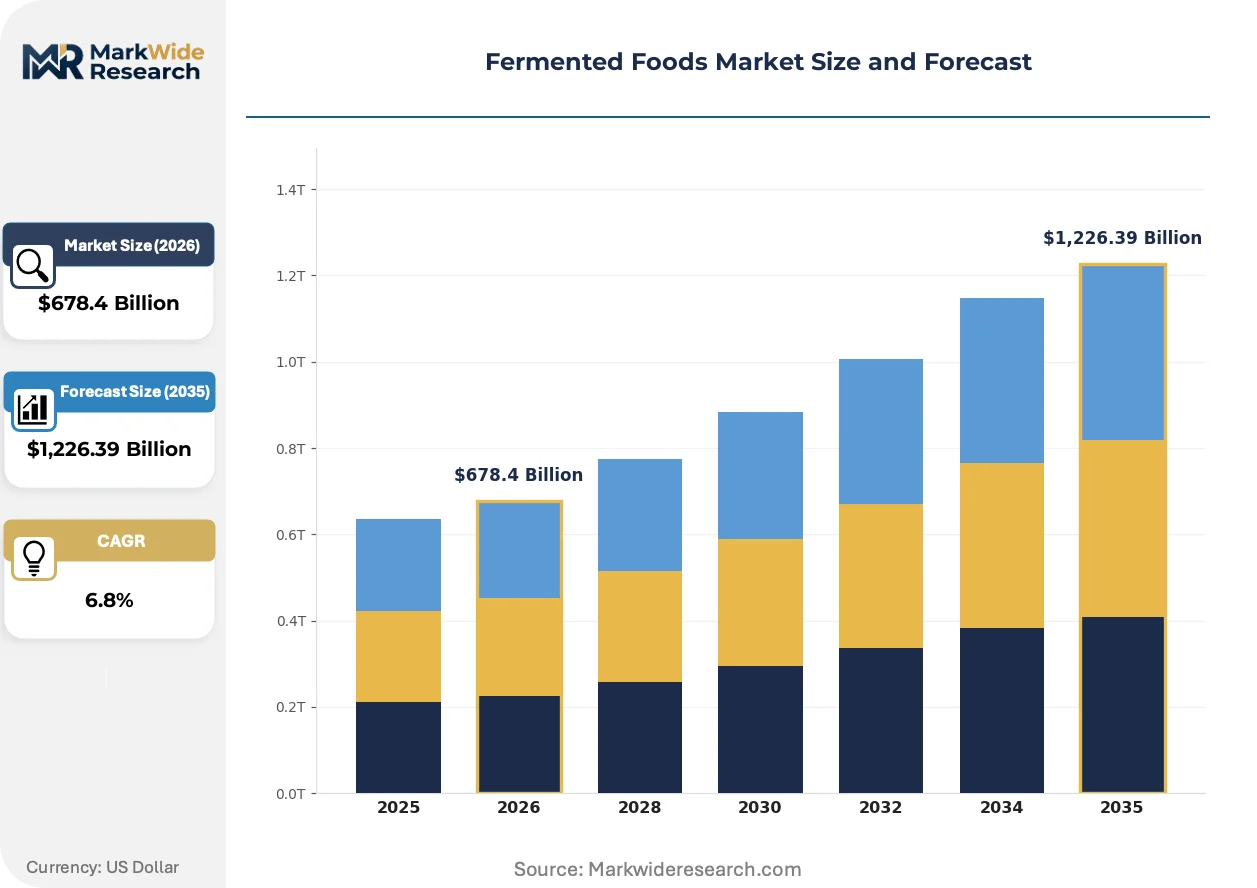
| Market Size in 2026 | $678.4 Billion |
| Market Size in 2035 | $1,226.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kimchi, Sauerkraut, Kefir End User: Households, Restaurants, Food Processing, Health Stores Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers' Markets Form: Liquid, Solid, Powdered, Freeze-Dried |
| Companies Covered | Chobani Inc., Groupe Lactalis S.A., Danone S.A., GT’s Living Foods, Lifeway Foods Inc., Nestlé S.A., Fonterra Co-operative Group Limited, General Mills, Inc., Yakult Honsha Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Foods Market Strategic Shifts & Innovations
Controlled microbial processing is advancing beyond dairy into novel substrates, while regulatory science and consumer education converge to create premium positioning opportunities for validated live-culture products.
Starter culture technology is migrating from undefined mixed-strain inoculants toward single-strain precision formulations with documented genome sequences. Large-scale yogurt manufacturers are adopting these characterized cultures to meet FDA substantiation requirements for live-and-active claims. This shift is compressing the competitive advantage previously held by heritage producers relying on undefined house cultures.
EFSA's evolving health claim assessment protocols are forcing European manufacturers to redesign clinical validation strategies. The regulator's demand for strain-specific human intervention trials is redirecting R&D budgets from marketing toward gastrointestinal microbiome research partnerships. Kefir and specialty fermented beverages face the steepest compliance burden due to their complex multi-strain compositions.
Health stores are displacing conventional supermarkets as the primary education venue for fermented food purchasing decisions. Trained staff at these outlets explain colony-forming unit counts and strain diversity to consumers, justifying price premiums that mass retail cannot replicate. This channel shift concentrates value capture in curated specialty environments across Germany, the Netherlands, and California.
Fermented Foods Market Segmentation
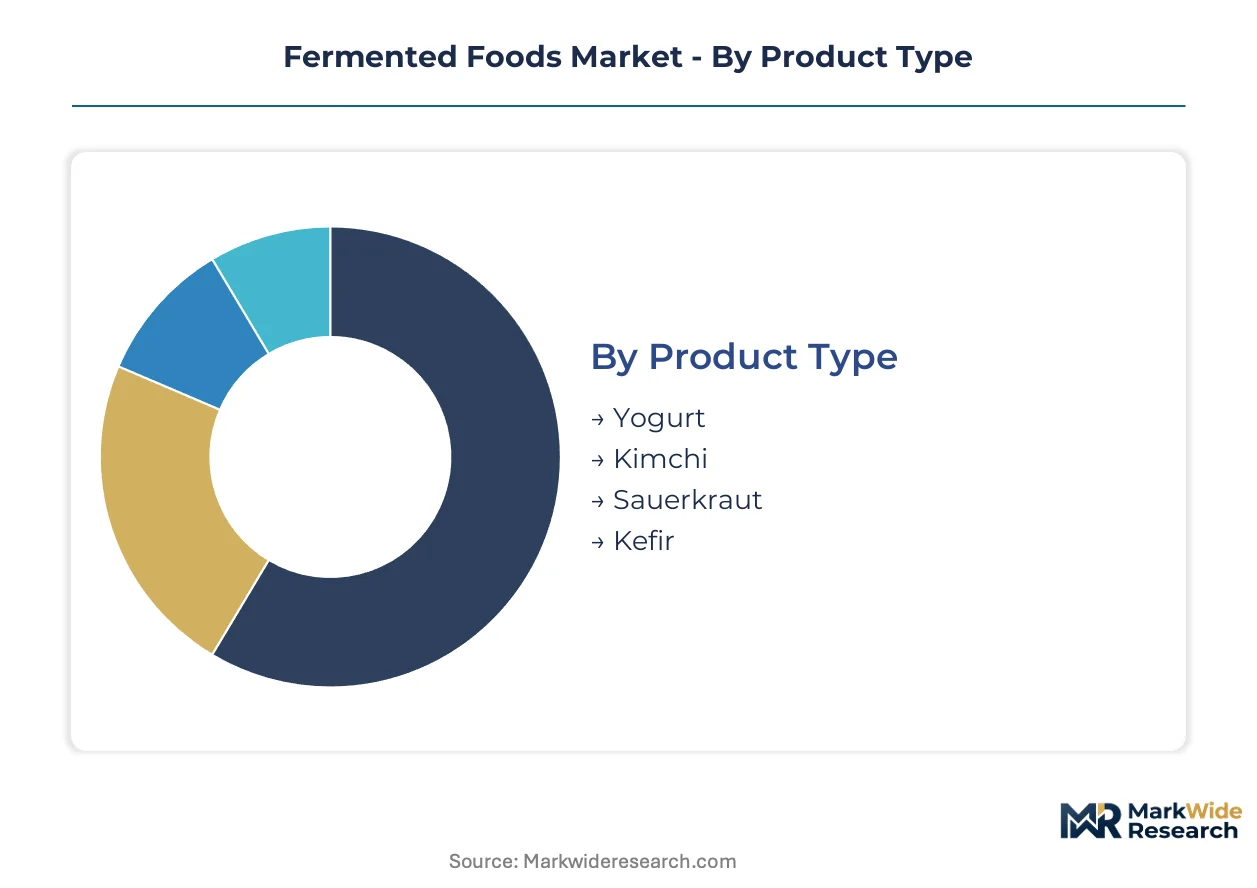
Segmentation in fermented foods reveals how microbial processing techniques, preservation formats, and distribution infrastructure create distinct value pools. Manufacturers align R&D investment and regulatory compliance strategies against specific segment characteristics rather than pursuing undifferentiated market presence.
Product Type:
Mature dairy-based formats anchor revenue stability while emerging vegetable fermentation builds export momentum.
- Yogurt:Lactic acid bacteria fermentation of milk at 40-45°C produces standardized acidity and protein gel structures. Demand concentrates in European retail chains where EFSA health claim restrictions force strain-specific clinical validation for premium positioning.
- Kefir:Multi-strain symbiotic cultures of bacteria and yeasts create effervescent liquid matrices with broader microbial diversity than yogurt. South Korean and German health stores drive demand for this format as consumers seek alternatives to conventional dairy probiotics.
- Kimchi:Lacto-fermented napa cabbage and radish with chili, garlic, and seafood seasonings undergoes ambient temperature processing for 1-3 weeks. MFDS export certification frameworks in South Korea enable cross-border distribution into Japanese retail channels.
- Sauerkraut:Shredded cabbage fermentation by Leuconostoc and Lactobacillus species delivers shelf-stable acidic preservation without thermal processing. German and Polish traditional consumption patterns support steady household procurement through supermarkets.
Yogurt retains volume leadership; kefir holds the steepest expansion curve.
End User:
Procurement patterns diverge sharply between price-sensitive bulk buyers and education-dependent premium channels.
- Health Stores:Curated retail environments with trained staff explaining colony-forming unit counts and strain diversity justify 30-50% price premiums over mass retail. California, Berlin, and Amsterdam outlets concentrate this demand as gut wellness positioning dominates purchasing decisions.
- Households:Direct consumption spans daily meal integration in South Korea and functional supplement routines in North American urban centers. Refrigerated storage capacity and cold chain access constrain format selection for this segment.
- Restaurants:Foodservice procurement emphasizes consistent flavor profiles and extended ambient stability for menu integration. Korean and Japanese restaurant chains specify fermented vegetable suppliers with documented batch consistency protocols.
- Food Processing:Industrial buyers incorporate fermented ingredients as flavor modulators, acidulants, and shelf-life extenders in prepared meals and sauces. Clean-label positioning drives substitution of synthetic preservatives with cultured vegetable extracts.
Health stores capture the fastest margin expansion; households dominate absolute volume throughput.
Distribution Channel:
Channel selection determines viable product formats based on temperature control capabilities and consumer education intensity.
- Specialty Stores:Independent retailers with fermentation-focused merchandising provide strain-specific education that justifies premium pricing for artisan producers. Staff training investments create defensive positioning against supermarket private label encroachment.
- Supermarkets:Mass retail slotting fees and standardized shelving configurations favor shelf-stable or short-code refrigerated formats with established brand recognition. Live-culture products face margin compression from cold chain cost allocation.
- Online Retail:Direct-to-consumer platforms enable subscription models for curated monthly fermentation boxes, bypassing conventional retail fees. Australian and UK urban households drive recurring revenue through gut-health committed purchasing.
- Farmers' Markets:Local producer-direct sales support small-batch artisan positioning with minimal regulatory documentation burden. Seasonal availability and uncontrolled temperature exposure limit scale for live-culture products.
Supermarkets retain volume leadership; specialty stores command the steepest price premiums.
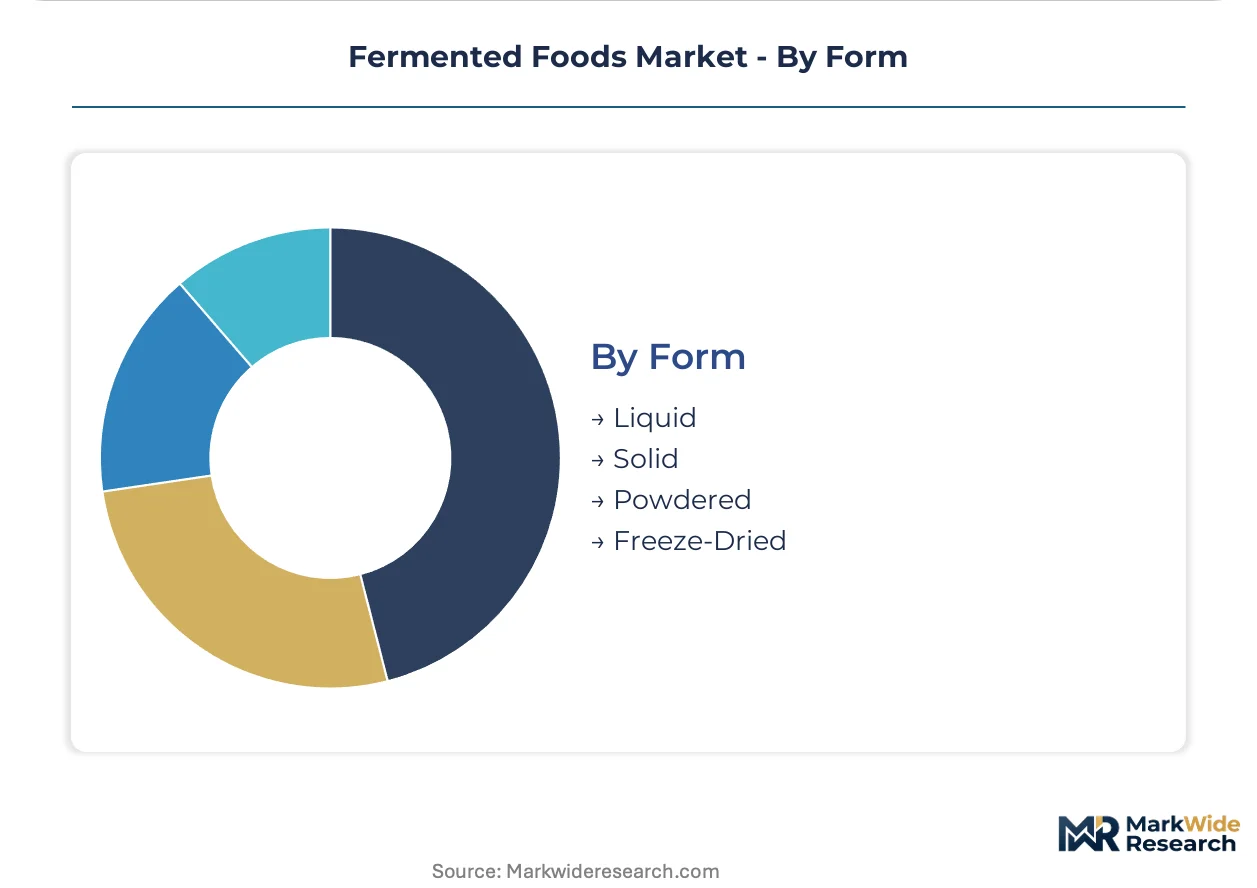
Form:
Processing intensity and preservation technology determine addressable end-use applications and geographic reach.
- Liquid:Beverage formats including kefir, drinking yogurt, and fermented vegetable juices require continuous cold chain maintenance. South Korean convenience store distribution and German organic retail channels concentrate demand for portable probiotic consumption.
- Solid:Whole or cut vegetable products and set yogurt formats represent the lowest processing intensity with maximum sensory authenticity. Traditional kimchi and sauerkraut consumption patterns favor this form for meal accompaniment.
- Powdered:Spray-dried or freeze-dried concentrates enable ambient distribution and extended shelf stability for food processing applications. Military and disaster relief procurement specifications drive demand for this format.
- Freeze-Dried:Lyophilization preserves viable probiotic counts at room temperature, opening remote mining camp and expedition supply channels previously closed to refrigerated products. Premium pricing reflects processing energy intensity and specialized equipment requirements.
Solid formats retain volume leadership; freeze-dried products are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's kimchi export corridor, connecting refrigerated container flows to Japanese and Southeast Asian retail networks. This maritime infrastructure underwrites the country's dominance in fermented vegetable trade volumes.
United States
Health stores in California and New York Metro drive premium kefir and kombucha procurement as gut wellness positioning captures urban household spending. FDA live-and-active culture labeling standards compel manufacturers to validate colony-forming unit counts at expiration, reshaping formulation timelines. Denver and Austin fermentation clusters concentrate artisan producers scaling precision-controlled temperature systems.
Germany
Traditional sauerkraut consumption in Bavaria and North Rhine-Westphalia sustains steady household demand through supermarket channels. EFSA health claim restrictions limit specific probiotic benefit language, forcing reformulation toward generic wellness positioning. Berlin specialty stores command 30-50% price premiums through trained staff education on strain diversity.
South Korea
Seoul Capital Area households integrate kimchi into daily meal patterns while MFDS export certification frameworks accelerate cross-border distribution into Japan. Busan-Ulsan industrial zones host automated fermentation facilities scaling napa cabbage processing for international retail. Daegu-Gyeongbuk regions anchor heritage artisan production threatened by aging master fermenter retirements.
Japan
Tokyo and Osaka metropolitan areas sustain demand for miso and natto as functional meal components in aging household demographics. METI standards on fermented soybean product labeling shape domestic manufacturing compliance investments. Nagoya industrial corridors concentrate large-scale producers supplying convenience store distribution networks.
Australia
Sydney and Melbourne urban households drive recurring revenue through direct-to-subscription fermentation box models bypassing retail slotting fees. TGA probiotic guidance documents influence import screening for live-culture products entering through Port Botany. Queensland health stores concentrate education-intensive purchasing environments for kefir and drinking yogurt formats.
Fermented Foods Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in culture supply and fermentation equipment. The vendor base organizes around three tiers: multinational dairy conglomerates with captive fermentation infrastructure, mid-cap regional brands leveraging heritage positioning, and artisan specialists scaling through subscription channels. Consolidation pressures concentrate among yogurt manufacturers adopting single-strain precision cultures to meet FDA substantiation requirements. Capacity expansion and strain-specific clinical validation represent the dominant competitive moves reshaping R&D allocation.
Within the multinational dairy tier, Groupe Lactalis S.A. and Danone S.A. occupy positions anchored by European fermentation expertise and probiotic science portfolios respectively. Nestlé S.A. exemplifies shelf-stable format expansion into emerging markets where cold chain constraints limit live-culture distribution. Among Japanese specialists, Yakult Honsha Co. Ltd represents the single-strain precision culture model that FDA validation requirements increasingly favor over undefined mixed-strain heritage approaches.
| Leading Market Players |
|---|
| Chobani Inc. |
| Groupe Lactalis S.A. |
| Danone S.A. |
| GT's Living Foods |
| Lifeway Foods Inc. |
| Nestlé S.A. |
| Fonterra Co-operative Group Limited |
| General Mills, Inc. |
| Yakult Honsha Co. Ltd |
| Others |
Cost & Logistics Intelligence
South Korean napa cabbage cultivation clusters anchor upstream input costs for kimchi producers, concentrating margin capture in export-certified processing facilities downstream. Cold chain logistics premiums and live-culture stability requirements redistribute value toward temperature-controlled distribution tiers.
Pricing Analysis
FDA live-and-active culture labeling dictates the pricing tier structure across the United States market. Three-tier pricing structure across premium, standard, and economy levels separates strain-validated probiotic products from generic fermented goods. Certification grade and cold chain compliance serve as primary price differentiation drivers. Price erosion runs through ambient retail channels as supermarkets allocate shelf fees to refrigerated live-culture formats. Health stores exhibit lowest price sensitivity; mass retail households demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from South Korean export processors to napa cabbage cooperatives stabilize seasonal harvest financing. Raw material sourcing draws from South Korea, Germany, and New Zealand for cabbage, dairy cultures, and milk powder respectively. Starter culture supply hinges on proprietary strain deposits across competing culture collections. Single-source vulnerability concentrates in legacy artisan facilities facing master fermenter retirements. Distribution runs through refrigerated container networks from Busan to Japanese retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as gut wellness education displaces mass retail purchasing decisions, creating niches for validated live-culture specialists.
For Market Incumbents: Entrench market position through backward integration into captive starter culture banking and precision fermentation equipment manufacturing. Capacity addition in South Korea's Busan-Ulsan corridor secures kimchi export certification advantages. Investment in strain-specific clinical validation defends against FDA substantiation requirements compressing formulation timelines. For New Entrants and Emerging Players: Pursue white-space capture in Indonesia's halal-certified functional foods segment and Australian direct-to-subscription fermentation box channels. MUI halal approval represents the most penetrable regulatory gateway for cross-border distribution. Curated monthly delivery models bypass conventional retail slotting fees while building recurring revenue. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale precision fermentation specialists with documented genome sequencing capabilities and established health store channel relationships. Long-term viability across the analysis window favors platforms bridging artisan authenticity with scalable temperature-controlled processing. Watch for inflection signals in MFDS export certification volume acceleration into Southeast Asian retail networks.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Clinical Validation | FDA live-and-active culture claims require documented colony-forming unit counts at expiration. |
| Halal Certification Pathway | MUI approval unlocks Indonesia's expanding middle-class functional foods procurement. |
| Cold Chain Infrastructure Expansion | Refrigerated container flows from Busan anchor kimchi export momentum into Japan. |
| Direct-to-Subscription Launch | Curated fermentation boxes capture recurring revenue from gut-health committed households. |
| Precision Culture Banking | Single-strain genome sequencing meets EFSA health claim substantiation requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation facility managers, health store category buyers, cold chain logistics coordinators, and regulatory affairs specialists at multinational dairy conglomerates. Secondary validation drew from FDA labeling guidance documents, MFDS export certification records, EFSA health claim assessment registers, and refrigerated trade flow data. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Calibration against historical production volumes and validated live-culture product launches anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product type, end-user procurement pattern, distribution channel temperature requirements, and preservation format. CAGRs were derived from fitted growth curves against documented strain-specific clinical trial pipelines and health store expansion trajectories. Industry-specific forecast inputs included MFDS certification throughput rates and EFSA probiotic claim approval velocity.
Sensitivities concentrate around regulatory threshold revisions for live-culture viability claims and cold chain cost inflation trajectories. Forecasts embody assumptions regarding sustained gut wellness consumer education and stable dairy input pricing from New Zealand supply zones. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Pizza Market
Processed Foods
Processed Cashew Market
Processed Foods
Low Moisture Food Market
Processed Foods
Chocolate Filling Market
Processed Foods
Apple Butter Market
Processed Foods
Butter Crisco Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Coffee Creamer Market
Processed Foods
Yogurt Dip Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Block Margarine Market
Processed Foods
Fat Free Soup Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Low Calorie Rice Pudding Market