
 United States Fresh Noodles Market | 2026-2036
United States Fresh Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fresh Noodles Market Outlook
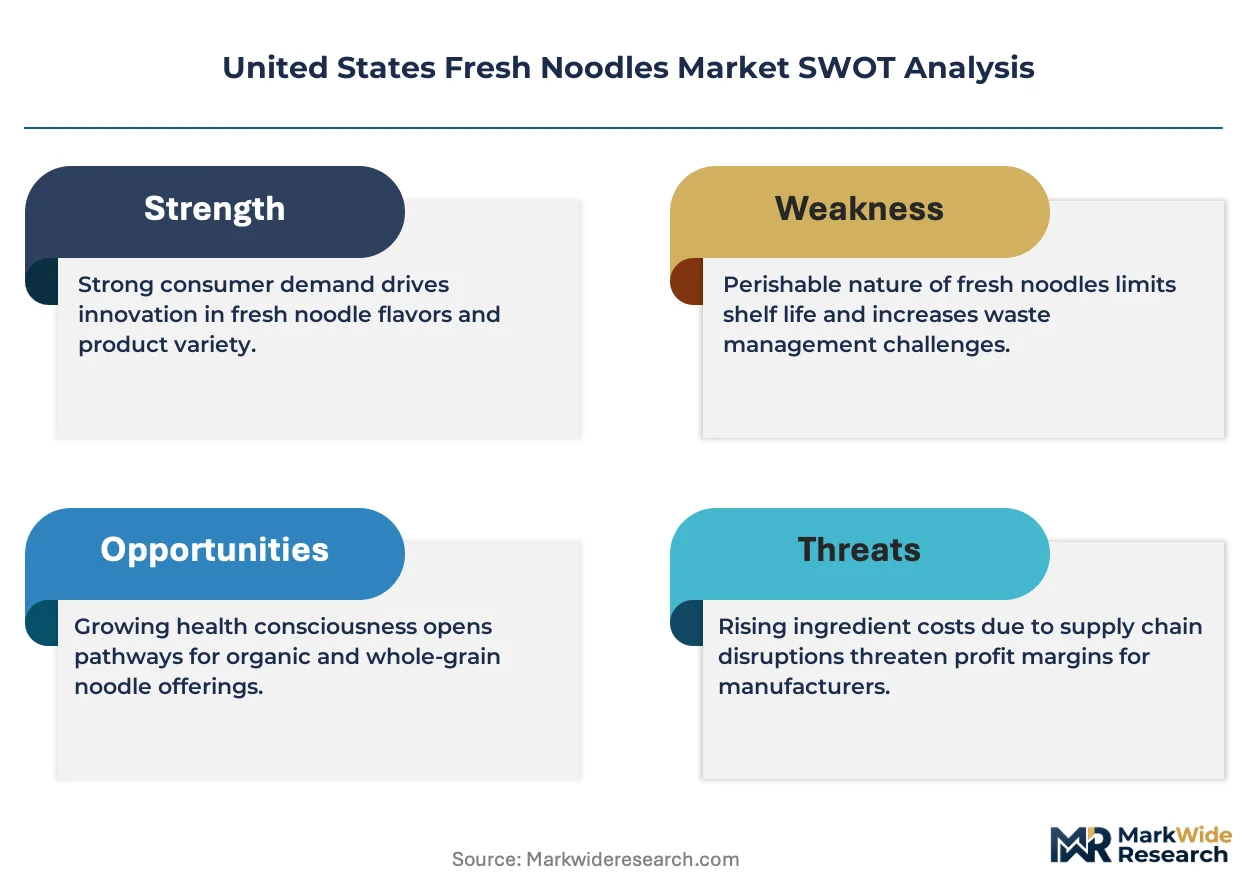
Automated sheeting and cutting systems with integrated humidity control is tilting production economics toward larger-scale fresh noodle manufacturing. Nissin Foods Holdings Co. Ltd. leverages its proprietary flash-steaming know-how to sustain extended shelf life without chemical preservatives. Maruchan Inc. anchors the value-tier segment through dominant supermarket distribution networks. NONGSHIM AMERICA INC. differentiates via Korean-style formulations that occupy the fast-casual restaurant supply channel.
Fresh noodles are wheat- or rice-based dough strips, extruded or sheeted to 1-3 millimeter thickness, then pasteurized and refrigerated at 0-4°C for distribution within 14-21 day windows. Their primary commercial purpose is delivering cooked texture and flavor absorption superior to dried alternatives in foodservice and home preparation. Wheat noodles dominate volume through broad menu compatibility across Italian, Asian, and fusion applications. Rice noodles represent the fastest-growing product type as gluten-free positioning attracts health-conscious households and specialty restaurants. Supermarkets control the largest margin pool through private-label programs and dedicated refrigerated case space.
The FDA enforces pathogen standards under FSMA preventive controls for human food, while USDA's Agricultural Marketing Service oversees grain quality specifications affecting noodle flour procurement. State-level cottage food laws in Texas and Florida create uneven market access for small-batch producers versus federally inspected facilities. Stakeholders must monitor evolving refrigeration energy standards from the Department of Energy, as compliance costs will reshape plant location decisions and distribution radius economics.
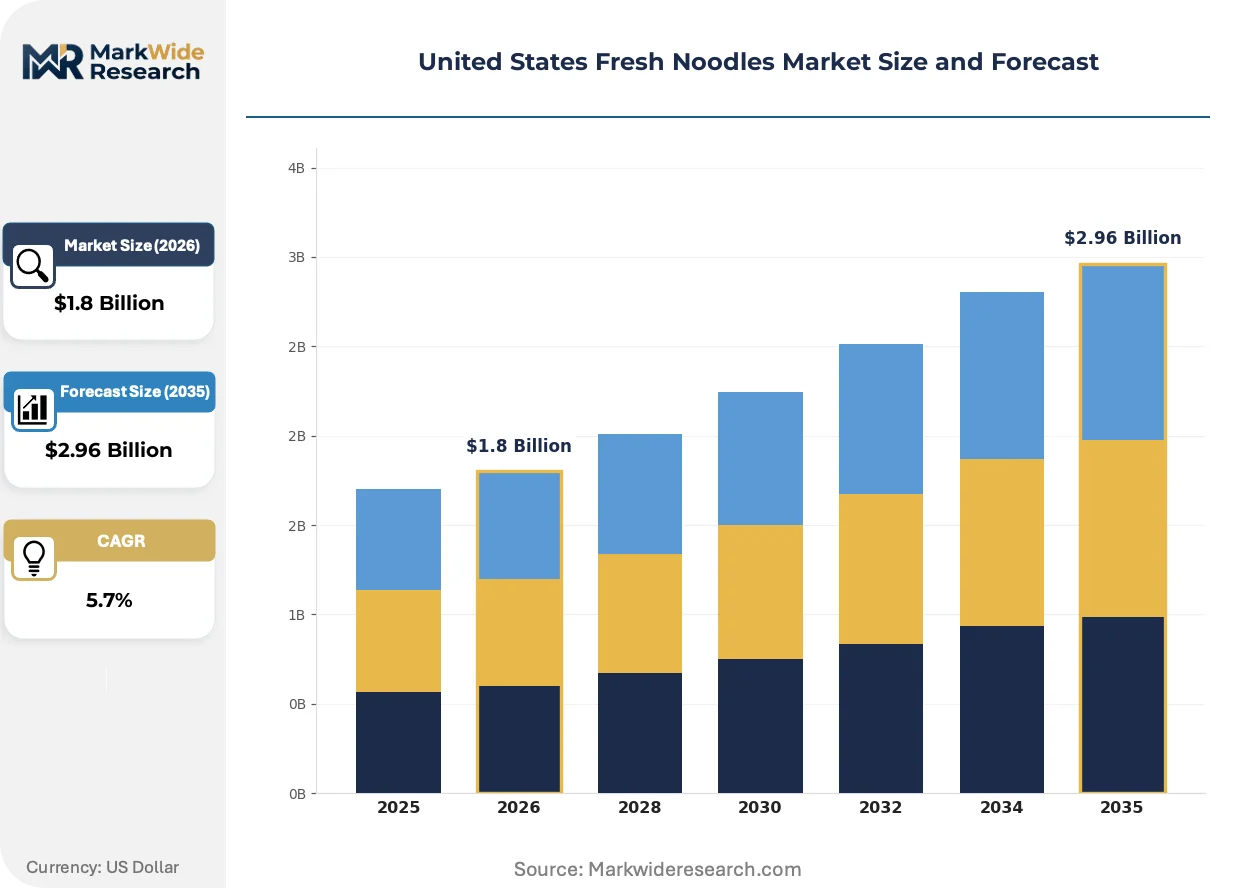
Market Dynamics
The FDA's updated Food Safety Modernization Act enforcement on ready-to-eat products is pressuring smaller producers to upgrade cold-chain infrastructure, consolidating production economics toward larger-scale manufacturers with automated sheeting and integrated humidity control systems.
Growth Catalysts
- FSMA Preventive Controls:The FDA's stricter pathogen standards are accelerating facility consolidation as smaller producers exit, freeing shelf space for scaled manufacturers with compliant HACCP systems.
- Asian-American population density:California's Bay Area and Los Angeles metro clusters sustain specialty retail procurement and fast-casual restaurant supply contracts for Korean and Japanese formulations.
- Automated sheeting technology:Integrated humidity control systems are compressing unit labor costs and extending viable distribution radii for refrigerated products.
Market Restraints
- Refrigeration energy standards:The Department of Energy's evolving compliance costs are reshaping plant location decisions and narrowing economically viable distribution windows.
- Wheat flour input volatility:USDA Agricultural Marketing Service grain quality specifications create procurement friction for noodle flour with consistent protein content.
- Cottage food law fragmentation:Texas and Florida state-level exemptions create uneven competitive access between home-kitchen producers and federally inspected facilities.
Strategic Opportunities
- Gluten-free rice noodle expansion:Health-conscious households and specialty restaurants in the Midwest and Southeast represent underpenetrated demand for allergen-positioned formats.
- Flash-steaming shelf-life extension:Proprietary pasteurization know-how without chemical preservatives opens foodservice channels previously closed to fresh formats.
- Private-label supermarket programs:Dedicated refrigerated case space in dominant retail chains offers margin pool capture for scaled producers with consistent supply.
Industry Challenges
- Cold-chain talent scarcity:Qualified technicians for maintaining 0-4°C distribution integrity through 14-21 day windows are concentrated in established logistics hubs.
- Legacy equipment integration:Retrofitting existing plants with automated cutting systems requires production downtime that smaller operators cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fresh Noodles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Noodles, Rice Noodles, Egg Noodles, Buckwheat Noodles Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores End User: Households, Restaurants, Food Service, Catering Services Packaging Type: Plastic Bags, Boxes, Vacuum Packs, Bulk Packaging |
| Companies Covered | Maruchan Inc., Nissin Foods Holdings Co. Ltd., NONGSHIM AMERICA INC., Sanyo Foods Corp. of America, Mandarin Noodle, House Foods Group Inc., Conagra Brands Inc., Nestlé S.A., Ajinomoto Co. Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fresh Noodles Market Strategic Shifts
Automation and regulatory compliance are compressing the viable producer base while shifting competitive advantage toward capital-intensive manufacturing and proprietary shelf-life technologies.
Automated sheeting and cutting systems with real-time moisture sensors are rendering obsolete manual production lines dependent on skilled noodle craftsmen. Foodservice distributors and multi-unit restaurant chains are adopting these systems to secure consistent texture and reduce labor dependency. The technology is compressing the price premium between artisan and industrial fresh noodles.
The FDA's Food Safety Modernization Act preventive controls for human food are mandating environmental monitoring and supply chain documentation that manual facilities cannot sustain. Compliance investments are diverting capital from product development toward validation protocols and third-party audits. Smaller producers in Texas and Florida are responding by exiting refrigerated formats or seeking co-manufacturing partnerships.
Restaurant procurement is consolidating volume through broadline distributors rather than direct relationships with specialty mills. Multi-unit chains in the Midwest and Southeast are standardizing specifications across regions, displacing local supplier relationships. This concentration is most visible in fast-casual Asian concepts expanding fresh noodle menu offerings.
United States Fresh Noodles Market Segmentation
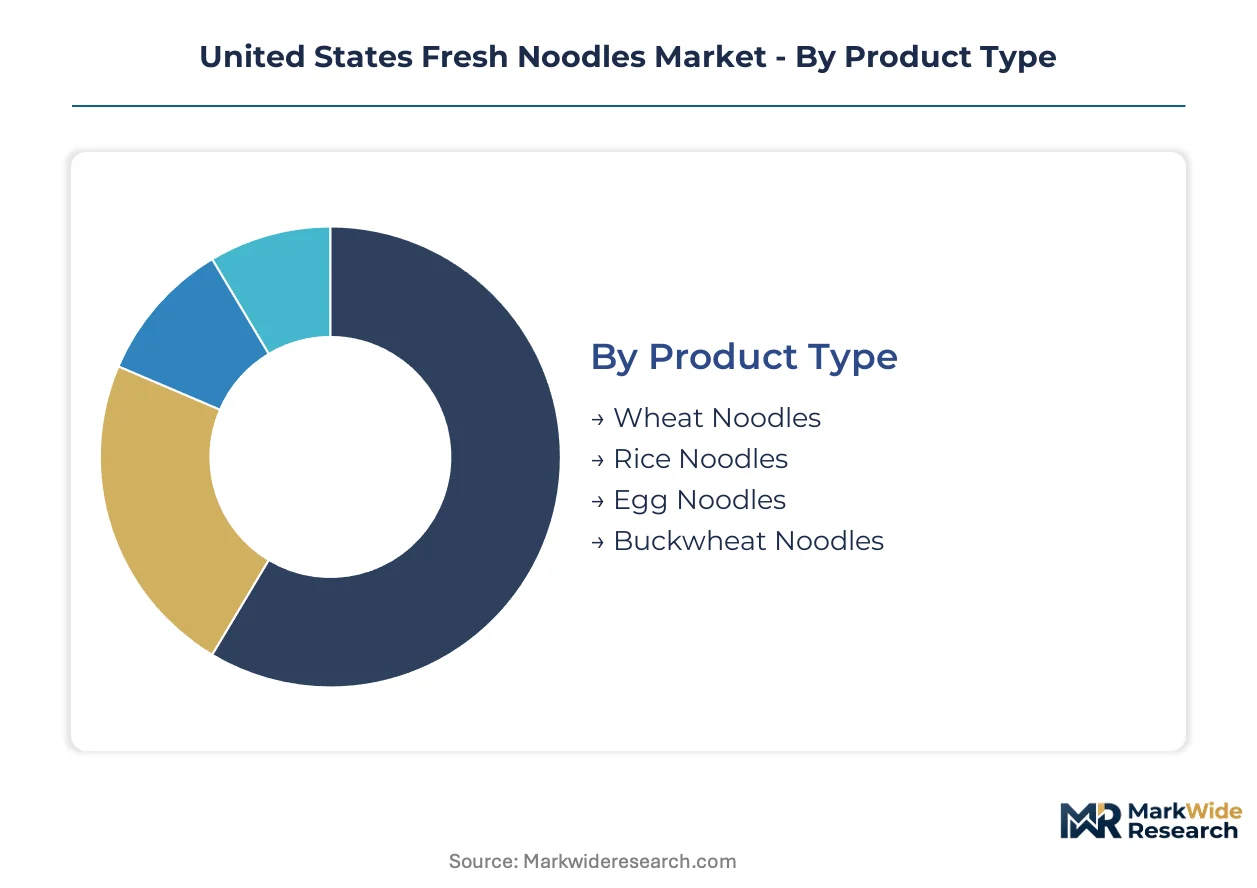
Fresh noodle segmentation in the United States tracks divergent velocity profiles across product formats and procurement channels. Wheat-based SKUs rotate through refrigerated cases in 14-day windows while rice noodle variants command premium shelf positioning with slower turnover but higher margins per linear foot.
Product Type:
Wheat noodles clear inventory fastest through broad menu compatibility, while buckwheat formats sit longest due to niche positioning and seasonal demand spikes.
- Wheat Noodles:Standard 1-3 millimeter extruded strips formulated from hard red winter wheat with 12-14% protein content. Bay Area and Los Angeles fast-casual chains standardize procurement around these specifications for ramen and pasta fusion menus. The segment absorbs volume shocks from flour price volatility better than alternatives due to diversified end-use.
- Rice Noodles:Rice flour-based sheets cut to width specifications for pho, pad thai, and gluten-free substitution applications. Midwest and Southeast specialty restaurants are expanding refrigerated rice noodle SKUs as celiac-positioned menu items attract health-conscious households. Supply concentrates in California mills with dedicated gluten-free production lines.
- Egg Noodles:Enriched dough incorporating whole egg solids for yellow coloration and tender bite texture. Traditional Jewish and Eastern European delis in the Northeast maintain consistent refrigerated procurement.
- Buckwheat Noodles:Soba-style formulations requiring precise 80-20 buckwheat-wheat ratios for structural integrity. Japanese and Korean restaurant supply channels in Hawaii and Pacific Northwest metro areas sustain limited production runs.
Wheat noodles dominate installed base. Rice noodles are where expansion concentrates.
Distribution Channel:
Channel economics stratify by margin capture versus logistics burden, with supermarkets extracting the highest per-unit profit while convenience stores optimize for emergency purchase occasions.
- Supermarkets:Dedicated refrigerated case space in chains like Kroger and Albertsons anchors private-label fresh noodle programs with 21-day turnover targets. These retailers negotiate direct procurement from scaled manufacturers with FSMA-compliant HACCP documentation, displacing regional distributors.
- Online Retailers:Cold-chain fulfillment through insulated packaging and same-day delivery slots is expanding rice noodle access in secondary markets lacking Asian specialty retail. Amazon Fresh and Instacart partnerships with Nissin and Nongshim are normalizing direct-to-consumer refrigerated logistics.
- Specialty Stores:Independent Asian grocers in California and New York maintain direct relationships with small-batch producers for artisan wheat and buckwheat varieties.
- Convenience Stores:Limited SKU counts and restricted refrigerated footprint relegate fresh noodles to emergency substitution purchases near college campuses and urban transit hubs.
Supermarkets control margin pool concentration. Online retailers are climbing the fastest as cold-chain fulfillment investments mature.
End User:
Procurement patterns split between predictable household replenishment cycles and volatile foodservice batch ordering with specification variability.
- Households:Home cooks in Asian-American population clusters purchase refrigerated wheat and rice noodles for weekly meal preparation, with Los Angeles and San Francisco metros showing highest per-capita consumption. These buyers prioritize 14-day shelf life windows and clear labeling for allergen management.
- Restaurants:Fast-casual Asian concepts across the Midwest and Southeast are expanding fresh noodle menu items, standardizing specifications through broadline distributors rather than direct mill relationships. Multi-unit chains negotiate volume commitments against guaranteed supply continuity.
- Food Service:Institutional cafeterias and corporate dining programs in Texas and Florida source bulk-packaged wheat noodles through group purchasing organizations with stringent FSMA documentation requirements.
- Catering Services:Event-based procurement for weddings and corporate functions drives seasonal spikes in egg noodle demand for buffet-style pasta stations.
Households anchor baseline demand stability. Restaurants are where specification consolidation is forcing supplier consolidation.
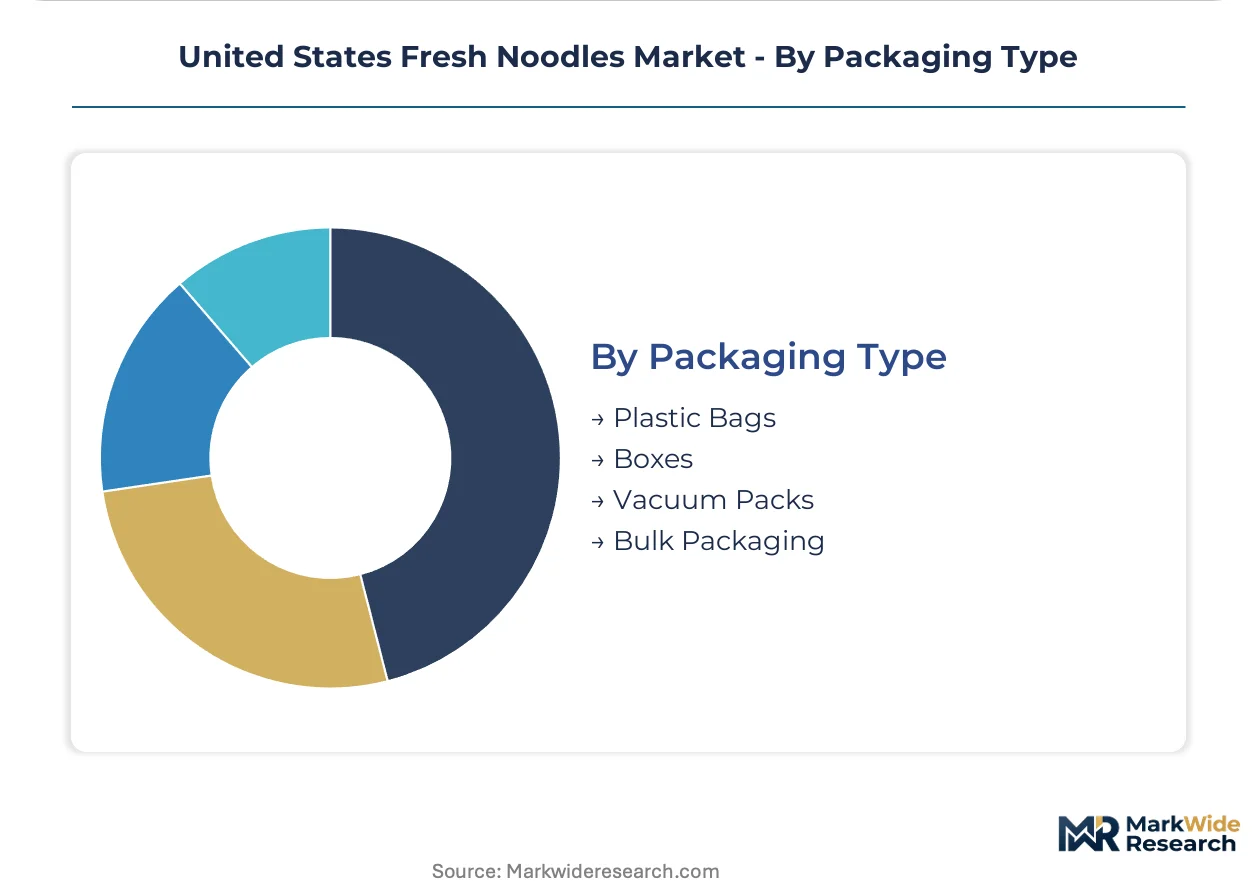
Packaging Type:
Packaging selection trades shelf-life extension against sustainability positioning and retail display economics.
- Plastic Bags:Standard polyethylene pouches with modified atmosphere flushing dominate supermarket private-label programs due to lowest unit cost and clear product visibility. These formats support 14-21 day refrigerated distribution windows with nitrogen displacement of oxygen.
- Vacuum Packs:Thermoformed barrier films with oxygen scavenger inserts extend viable shelf life toward 21-day maximums for foodservice distributors covering extended rural delivery routes. Nissin's flash-steaming technology pairs with vacuum packaging to eliminate chemical preservatives.
- Boxes:Paperboard cartons with polyethylene liners serve premium positioning in specialty retail channels with sustainability-conscious positioning.
- Bulk Packaging:Foodservice totes and pails for restaurant and catering procurement minimize per-pound packaging cost at the expense of retail shelf presence.
Plastic bags dominate unit volume. Vacuum packs are where shelf-life technology investments are concentrating competitive advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in Asian-American population clusters drive concentrated demand, with restaurant procurement consolidating through broadline distributors rather than direct mill relationships across metropolitan statistical areas.
California
Bay Area and Los Angeles metro areas sustain the highest per-capita fresh noodle consumption through specialty retail procurement and fast-casual restaurant supply contracts. FDA FSMA preventive controls enforcement pressures smaller producers to upgrade cold-chain infrastructure or exit. Mills in the Central Valley with dedicated gluten-free production lines supply rice noodle expansion to Midwest and Southeast markets.
Texas
State-level cottage food laws create uneven market access for home-kitchen producers versus federally inspected facilities in Dallas-Fort Worth and Houston corridors. USDA Agricultural Marketing Service grain quality specifications create procurement friction for consistent protein content in noodle flour. Institutional cafeterias and corporate dining programs in Austin source bulk-packaged wheat noodles through group purchasing organizations.
New York Metro
Traditional Jewish and Eastern European delis in Brooklyn and Queens maintain consistent refrigerated egg noodle procurement for heritage menu items. Independent Asian grocers in Manhattan and Flushing sustain direct relationships with small-batch producers for artisan wheat and buckwheat varieties. Multi-unit fast-casual chains standardize specifications across locations, displacing local supplier relationships.
Midwest
Chicago and Detroit restaurant chains are expanding fresh noodle menu offerings as consumer preference shifts from dried to refrigerated formats. Automated sheeting technology with integrated humidity control compresses unit labor costs and extends viable distribution radii for refrigerated products. Cold-chain talent scarcity concentrates qualified technicians for maintaining distribution integrity in established logistics hubs.
Southeast
Atlanta and Miami fast-casual Asian concepts drive specification consolidation forcing supplier consolidation through broadline distributors. Health-conscious households and specialty restaurants represent underpenetrated demand for allergen-positioned rice noodle formats. Flash-steaming shelf-life extension without chemical preservatives opens foodservice channels previously closed to fresh formats.
United States Fresh Noodles Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Supermarket private-label programs and dedicated refrigerated case space anchor margin capture for scaled manufacturers with FSMA-compliant HACCP documentation. Three archetypes dominate: multinational packaged food conglomerates with broad distribution networks, Asian-origin specialists with formulation heritage, and private-label suppliers serving retail chain programs. Competitive moves concentrate on strategic partnerships with broadline foodservice distributors and portfolio diversification into gluten-free and extended shelf-life formats.
Within the Asian-origin specialist tier, Nissin Foods Holdings Co. Ltd., NONGSHIM AMERICA INC., and Maruchan Inc. occupy positions defined by proprietary shelf-life technologies and restaurant supply channel penetration. Nissin exemplifies the flash-steaming technology archetype, while Nongshim represents Korean-style formulation specialization. Maruchan anchors value-tier positioning through dominant supermarket distribution networks. These three companies sit alongside multinational conglomerates including Nestlé S.A., Conagra Brands Inc., and Ajinomoto Co. Inc., which leverage existing refrigerated infrastructure across broader portfolio categories.
| Leading Market Players |
|---|
| Maruchan Inc. |
| Nissin Foods Holdings Co. Ltd. |
| NONGSHIM AMERICA INC. |
| Sanyo Foods Corp. of America |
| Mandarin Noodle |
| House Foods Group Inc. |
| Conagra Brands Inc. |
| Nestlé S.A. |
| Ajinomoto Co. Inc. |
| Others |
Value Chain & Pricing Dynamics
The I-5 corridor freight lanes connecting California's Central Valley mills to Los Angeles distribution hubs concentrate cost dynamics that ripple through supply concentration and downstream price tiers. Refrigerated trucking rates on this artery compress margins for smaller producers while scaled manufacturers absorb fuel volatility through volume commitments, creating three distinct price bands that separate flash-steamed premium formats from standard private-label offerings.
Pricing Analysis
Cost-plus contracts with wheat futures indexation dominate procurement between flour mills and noodle manufacturers, locking protein-content premiums into 12-14% hard red winter wheat specifications. Price differentiation rests on shelf-life technology certification and FSMA compliance documentation, with vacuum-packed flash-steamed products commanding premium positioning over standard modified-atmosphere formats. Pricing pressure stems from refrigerated energy standard compliance costs as the Department of Energy tightens cold-chain efficiency mandates. Value-tier supermarket private-label buyers exhibit highest price sensitivity, while fast-casual restaurant chains prioritize supply continuity over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced food-processing automation limit equipment flows from Germany and Japan to domestic facilities, constraining capacity expansion timelines for humidity-controlled sheeting systems. Raw material procurement draws from North American hard red winter wheat regions, California rice milling operations, and imported tapioca starch for gluten-free formulations. Single-source vulnerability concentrates in flash-steaming equipment suppliers, where proprietary know-how creates captive relationships. Distribution runs through broadline foodservice distributors consolidating restaurant volume rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh noodle manufacturing increasingly attaches value through cold-chain logistics services and extended shelf-life guarantees that expand faster than base product revenue. Recurring revenue from temperature-monitoring subscriptions and FSMA compliance documentation support is displacing pure product margins as the primary profit pool.
For Market Incumbents: Harden cold-chain infrastructure against FDA FSMA enforcement escalation by upgrading HACCP systems and securing qualified technician pipelines in established logistics hubs. Consolidate supplier relationships through backward integration into flour milling operations to lock protein-content consistency. Defensive priority centers on absorbing smaller producer exits to capture freed supermarket shelf space. For New Entrants and Emerging Players: Build out gluten-free rice noodle production capacity targeting Midwest and Southeast specialty restaurants where allergen-positioned formats remain underpenetrated. White-space concentration appears in online retail cold-chain fulfillment partnerships with insulated packaging providers. Go-to-market execution should anchor on direct relationships with independent Asian grocers seeking artisan buckwheat and egg noodle differentiation. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaged food conglomerates divesting non-core refrigerated pasta operations to focus on shelf-stable portfolios. Long-term viability over the coming decade hinges on proprietary shelf-life technology ownership and FSMA-compliant facility access. Signal to monitor: accelerated exit announcements from Texas and Florida cottage food law-dependent producers facing compliance cost cliffs.| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Steaming Technology Licensing | Nissin's proprietary pasteurization know-how opens foodservice channels previously closed to fresh formats. |
| Private-Label Program Expansion | Kroger and Albertsons refrigerated case negotiations capture margin pools through dedicated shelf space. |
| Gluten-Free Production Line Investment | California Central Valley mills supply rice noodle expansion to Midwest and Southeast health-conscious households. |
| Broadline Distributor Partnership | Consolidated restaurant procurement through Sysco and US Foodservice displaces direct mill relationships. |
| Cold-Chain Infrastructure Upgrade | DOE refrigeration energy standard compliance reshapes plant location economics and viable distribution radii. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA FSMA enforcement records, USDA Agricultural Marketing Service grain quality specifications, and Department of Energy refrigeration efficiency standards. Primary inputs drew from plant managers at Central Valley milling operations, procurement leads at fast-casual restaurant chains, cold-chain logistics coordinators, and supermarket category buyers. Secondary validation incorporated SEC filings from publicly traded food manufacturers, customs data on food-processing equipment imports, and trade association cold-chain benchmarking reports. Bottom-up volume estimates from production facility capacity and top-down demand calibration from retail scanner data were cross-referenced for triangulation.
Forecast inputs span wheat noodle and rice noodle product types, supermarket and online retail distribution channels, household and restaurant end users, and vacuum pack versus plastic bag packaging formats across the analysis window. CAGRs were derived from segment-level growth trajectory blending with macroeconomic consumption elasticity assumptions. Industry-specific inputs included Asian-American population cluster density projections and FDA enforcement intensity scoring.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational conglomerates or sudden cottage food law harmonization would shift outcomes. Material shifts in FDA FSMA audit frequency or wheat futures volatility spikes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Fat Free Soup Market
Processed Foods
Potato Soup Market
Processed Foods
Instant Curry Market
Processed Foods
Egg Powder Market
Processed Foods
Ready to Cook Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Dairy Desserts Market
Processed Foods
Processed Meat Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Low Moisture Food Market
Processed Foods
US Tomato Paste Market
Processed Foods
North America Ice Cream Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Middle East and Africa Processed Meat Market