
 Asia-Pacific Soup Market | 2026-2036
Asia-Pacific Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Soup Market Outlook
E-commerce grocery platforms is reconfiguring how soup reaches consumers across Southeast Asian megacities. Nongshim Co., Ltd. leverages its domestic manufacturing scale to anchor shelf presence in South Korean convenience channels. Indofood Sukses Makmur dominates instant soup sachet distribution across Indonesian archipelago retail networks. Unilever PLC extends its brand portfolio through localized flavor development for health-positioned ranges.
Asia-Pacific soup comprises liquid or dehydrated food preparations typically containing water, vegetables, proteins, and seasonings, processed through retort sterilization or hot-fill methods to achieve shelf stability without refrigeration. The category serves commercial and household meal solutions where speed and minimal preparation define purchasing decisions. Ready-to-Eat Soup commands premium positioning in Japanese and Australian supermarkets where cold-chain integrity supports fresher ingredient claims. Instant Soup sustains volume leadership across lower-income demographics in Indonesia and the Philippines where boiling water accessibility drives format preference. Bouillon maintains entrenched usage in Chinese home cooking despite rising competition from concentrated liquid alternatives.
Japan's Consumer Affairs Agency enforces strict nutritional labeling standards that compel sodium reduction across processed soup portfolios. Australia's Food Standards Code governs health claim eligibility, restricting how manufacturers market functional benefits on front-of-pack labeling. China's National Health Commission issues dietary guidelines that indirectly pressure reformulation toward lower-salt profiles. Stakeholders must monitor evolving front-of-pack warning systems and clean-label certification requirements as regulatory divergence between Northeast and Southeast Asian markets intensifies sourcing complexity.
Market Dynamics
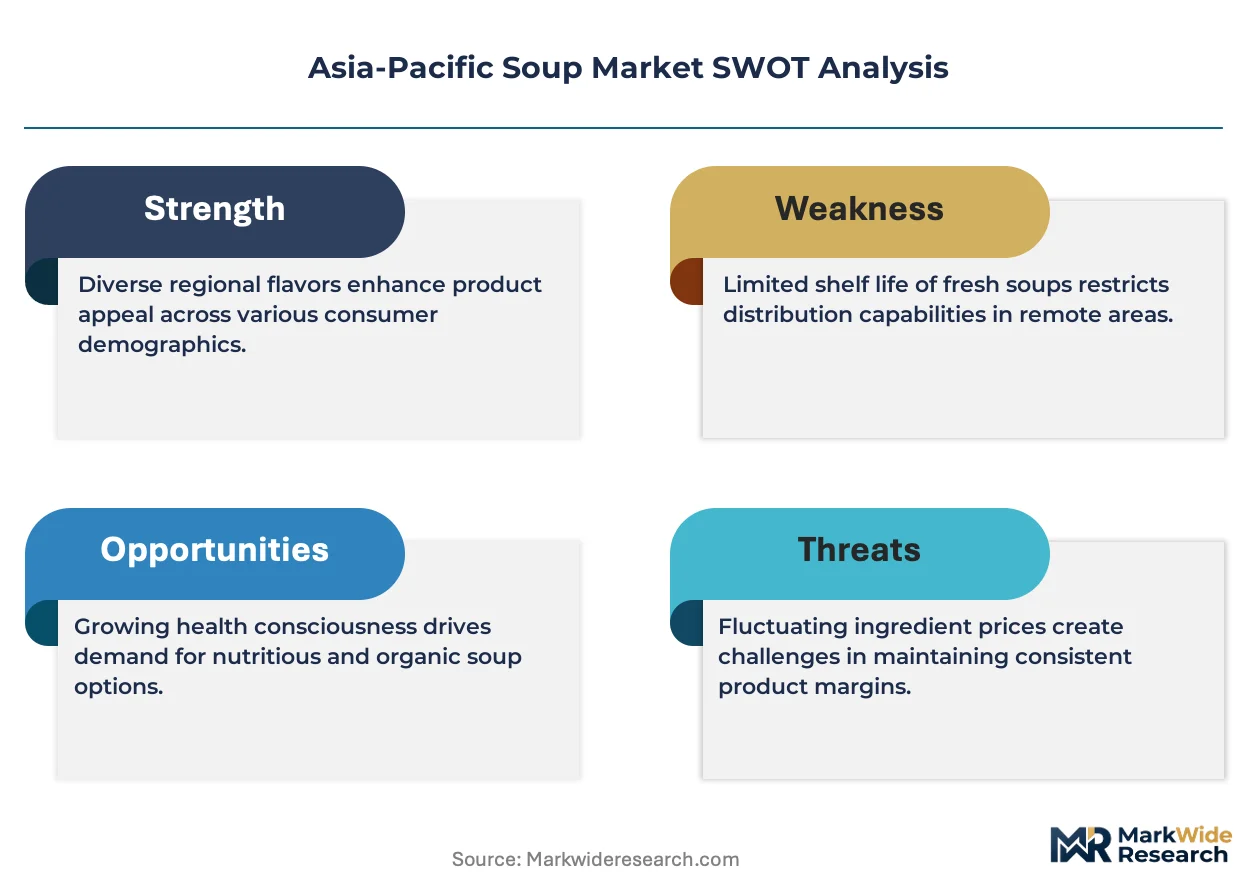
Japan's Consumer Affairs Agency sodium labeling mandates are forcing accelerated reformulation across processed soup portfolios, compressing margins while creating first-mover advantages for brands that achieve clean-label compliance ahead of enforcement deadlines.
Growth Catalysts
- Convenience-seeking urban professionals:Dense populations in Shanghai, Tokyo, and Seoul sustain demand for single-serve formats requiring minimal preparation time.
- Cold-chain infrastructure maturation:China's tier-one cities now support refrigerated ready-to-eat distribution networks that enable fresher ingredient positioning.
- Sodium reduction frameworks:Australia's Food Standards Code health claim eligibility rules incentivize manufacturers to reformulate toward functional benefit marketing.
Market Restraints
- Input cost volatility:Wheat and palm oil price fluctuations squeeze margin structures for dehydrated soup producers dependent on commodity sourcing.
- Supply concentration risk:Retort packaging capacity clusters in Thailand and Malaysia, creating single-point vulnerability for shelf-stable liquid formats.
- Technical limitation:Current aseptic filling technologies struggle to preserve texture integrity in vegetable-heavy formulations beyond twelve-month shelf life.
Strategic Opportunities
- Vietnamese secondary cities:Ho Chi Minh City and Da Nang exhibit underpenetrated modern trade coverage for premium soup formats.
- Regulatory tailwind:China's National Health Commission dietary guidelines create implicit pressure rewarding lower-sodium product development.
- Technology convergence:Modified atmosphere packaging combined with high-pressure processing is hybridizing to extend chilled soup shelf life without thermal degradation.
Industry Challenges
- Reformulation expertise scarcity:Food technologists skilled in salt replacer systems and umami enhancement remain concentrated in Japan and South Korea.
- Dual certification timelines:Simultaneous compliance with Japan's JIS standards and Australia's TGA-equivalent food code requirements extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Soup Market |
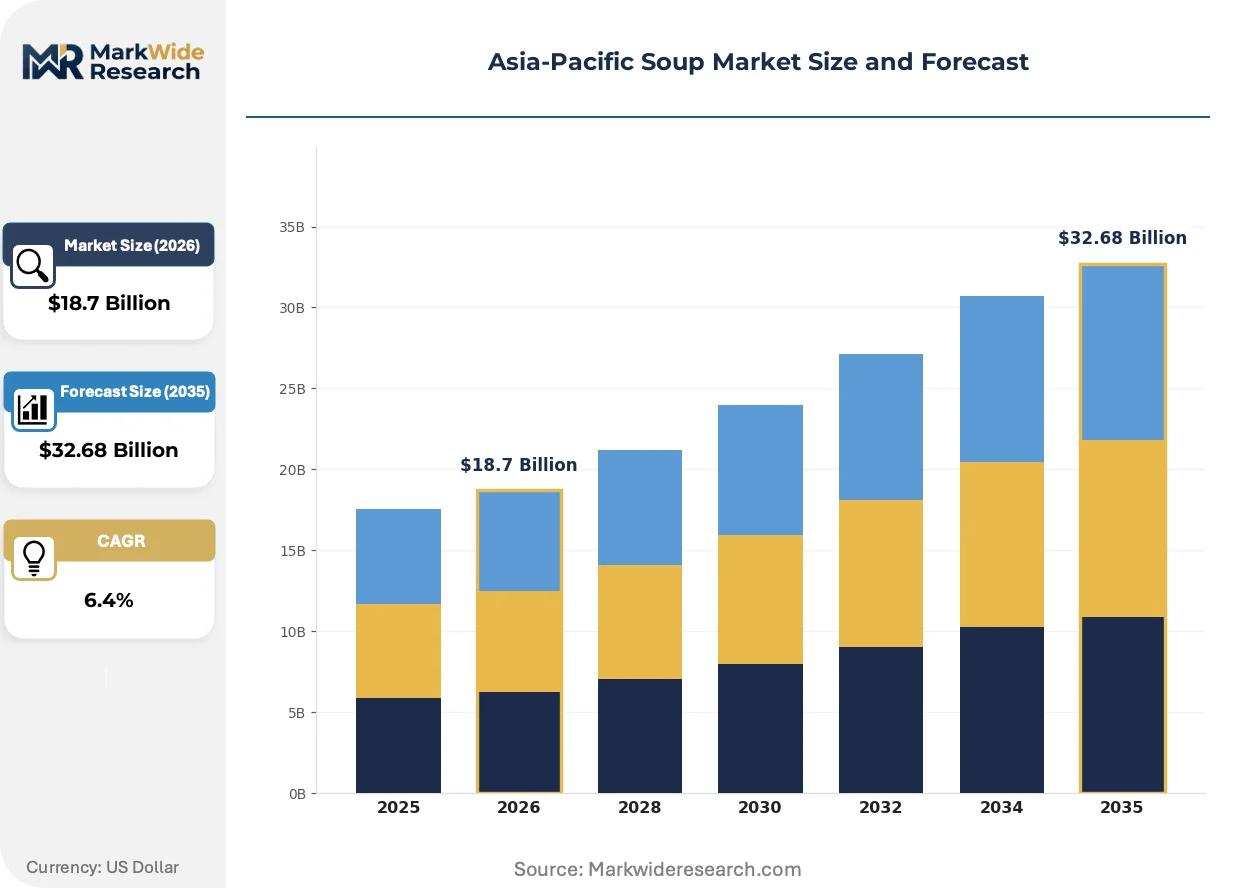
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Soup, Ready-to-Eat Soup, Bouillon, Canned Soup Ingredient Type: Vegetable, Meat, Seafood, Legumes Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores Consumer Type: Health-Conscious Consumers, Busy Professionals, Families, Students |
| Companies Covered | Ajinomoto Co., Inc., Nongshim Co., Ltd., Nestlé S.A., The Kraft Heinz Company, Indofood Sukses Makmur, Unilever PLC, Nissin Foods Holdings Co., Ltd., General Mills, Inc., Campbell Soup Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Soup Market Strategic Shifts
Processing technology and distribution infrastructure are converging to enable fresher-positioned formats that challenge the dominance of traditional shelf-stable offerings across Asia-Pacific metropolitan markets.
High-pressure processing is hybridizing thermal and non-thermal preservation approaches to maintain nutritional integrity in chilled vegetable soups. Premium supermarket chains in Sydney and Melbourne are adopting these formats at accelerated rates. The technology is compressing the traditional trade-off between shelf stability and fresh taste claims that has defined category architecture for decades.
Front-of-pack warning label expansion is tightening across Southeast Asian markets following Thailand's Ministry of Public Health sodium disclosure requirements. Manufacturers must now redesign packaging architectures to accommodate mandatory octagonal warning symbols on high-sodium variants. Indonesian and Philippine instant soup segments face the steepest compliance redesign costs given existing portfolio salt levels.
Direct-to-pantry subscription models are fragmenting traditional retail concentration for premium soup brands in Australian and Japanese urban households. E-commerce platforms are displacing conventional supermarket aisle discovery with algorithmic personalization based on dietary preference profiles. Melbourne and Tokyo exhibit the highest subscription penetration rates, with cold-chain last-mile capabilities enabling weekly replenishment cycles.
Asia-Pacific Soup Market Segmentation
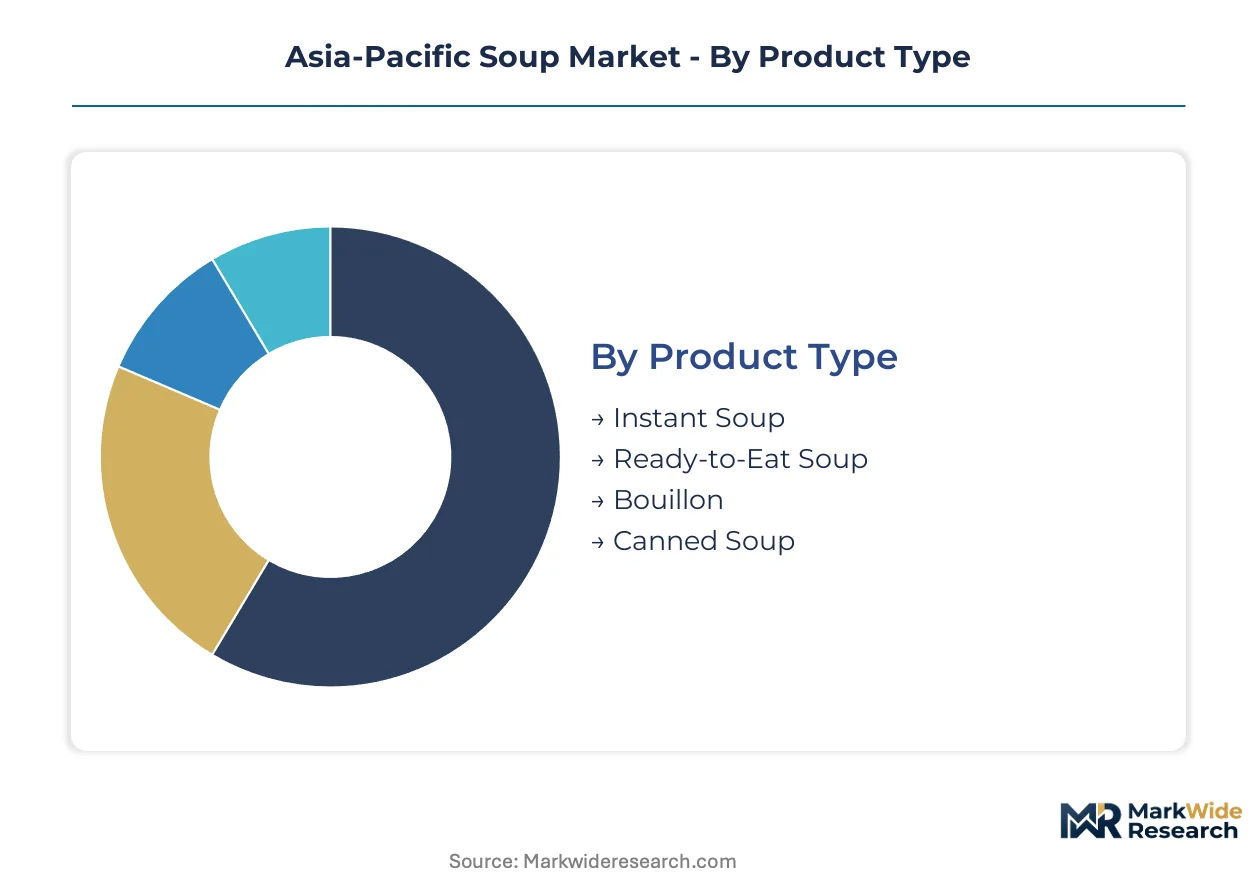
Segmentation in Asia-Pacific soup markets reveals how format preferences diverge across income tiers and urban infrastructure maturity. Understanding these divides exposes where cold-chain investment unlocks premium positioning versus where dehydrated formats retain structural advantage.
Product Type:
Inventory velocity varies dramatically across formats, with chilled ready-to-eat turning weekly while canned formats sit for months. This cycle-time spread shapes working capital requirements and shelf-space negotiation leverage.
- Instant Soup:Dehydrated powder or noodle blocks requiring only boiling water activation. Volume concentrates in Indonesian and Philippine urban corridors where kitchen space constraints and boiling water access dominate household decision-making.
- Ready-to-Eat Soup:Thermally processed liquid soups in refrigerated distribution. Demand clusters in Tokyo, Seoul, and Shanghai where cold-chain last-mile density supports fresh taste claims and premium pricing acceptance.
- Bouillon:Concentrated flavor bases for home cooking dilution. Retains entrenched usage in Chinese household cooking traditions despite encroachment from liquid concentrate alternatives.
- Canned Soup:Retort-sterilized metal-container formats with extended ambient shelf stability. Sustains residual demand in Australian rural markets and Japanese emergency preparedness stockpiling.
Instant Soup dominates installed base. Ready-to-Eat Soup is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates commodity protein inputs from premium positioning claims. Vegetable and legume formulations command manufacturing margin premiums in health-positioned ranges.
- Vegetable:Plant-based formulations leveraging regional produce sourcing. Australian and Japanese consumers drive demand for organic certification and clean-label vegetable content in premium supermarket channels.
- Meat:Protein-enhanced soups with beef, pork, or poultry content. South Korean and Chinese markets sustain volume leadership for meat-based instant formats despite sodium reformulation pressures.
- Seafood:Marine protein soups including fish, shellfish, and seaweed derivatives. Coastal Chinese provinces and Japanese markets exhibit concentrated preference for umami-dense seafood formulations.
- Legumes:Bean, lentil, and pea-based protein soups. Emerging positioning in Australian health-conscious segments as plant-protein alternatives gain trial.
Meat formulations anchor revenue concentration. Vegetable variants are climbing the fastest as sodium reduction and clean-label trends reshape portfolio priorities.
Distribution Channel:
Channel mix reflects urban density gradients and modern trade penetration depth. Convenience stores and online platforms are displacing traditional supermarket dominance in megacity cores.
- Supermarkets:Large-format retail with dedicated soup aisles and promotional stacking. Retains importance in Australian suburban markets and Japanese regional cities where weekly stock-up trips persist.
- Online Stores:E-commerce platforms with direct-to-home replenishment and subscription bundling. Melbourne, Sydney, and Tokyo exhibit highest penetration as algorithmic personalization displaces aisle discovery.
- Specialty Stores:Health-focused and organic retailers with curated premium assortments. Concentrated in Australian metropolitan markets and Japanese urban wellness corridors.
- Convenience Stores:High-frequency small-format retail with immediate consumption positioning. South Korean CU and 7-Eleven networks anchor instant soup single-serve velocity in dense urban districts.
Supermarkets retain the broadest installed base. Online Stores are gaining share fastest as last-mile cold-chain capabilities mature across tier-one cities.
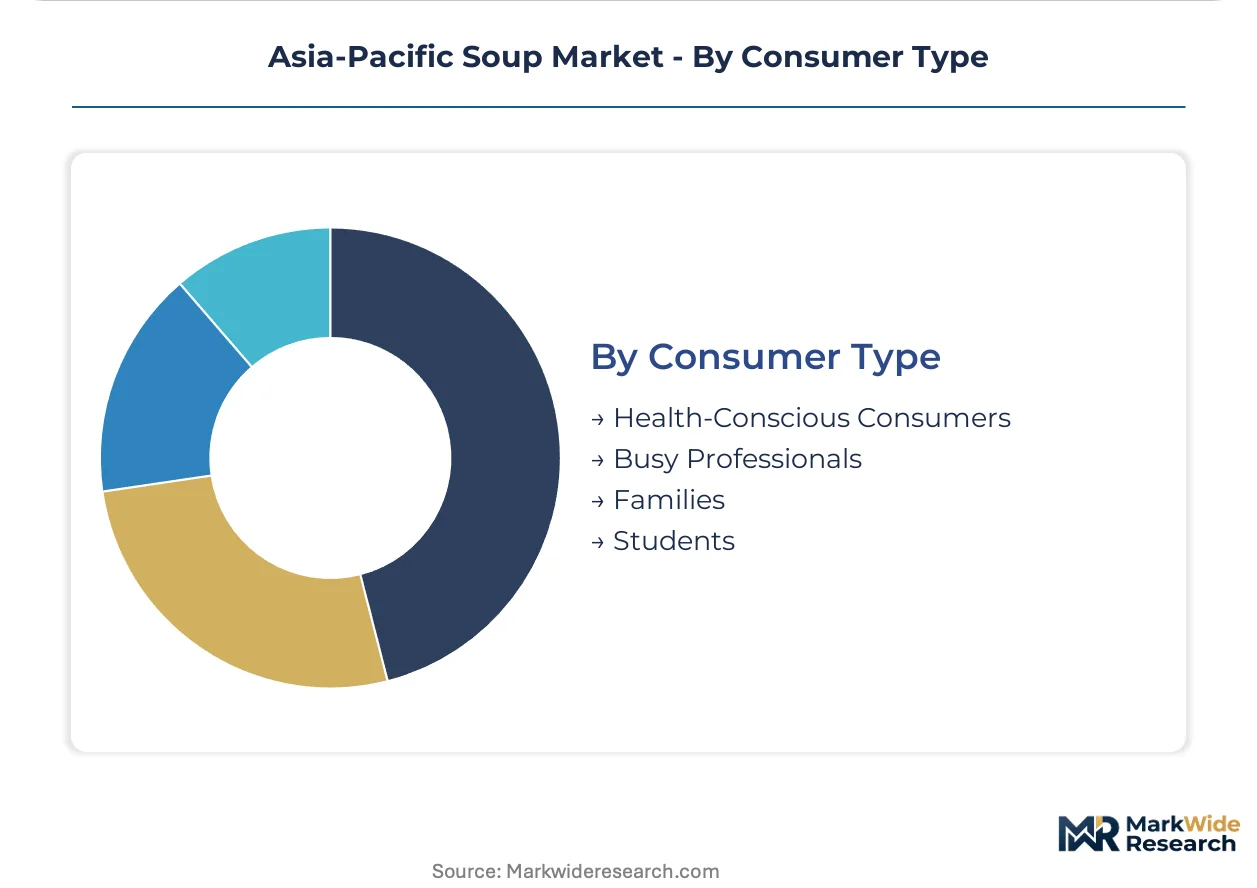
Consumer Type:
Application context separates at-desk consumption from family meal occasions. This usage divide determines format sizing, sodium tolerance, and price elasticity thresholds.
- Health-Conscious Consumers:Nutrition-label scrutinizing purchasers prioritizing sodium reduction and clean ingredients. Australian and Japanese regulatory environments reinforce this segment's influence on manufacturer reformulation roadmaps.
- Busy Professionals:Time-constrained urban workers seeking single-serve minimal-preparation solutions. Shanghai, Tokyo, and Seoul office districts sustain demand for grab-and-go chilled formats and premium instant varieties.
- Families:Multi-person household purchasers optimizing cost-per-serving and child palatability. Indonesian and Philippine family units drive large-format instant soup and value-positioned canned selections.
- Students:Price-sensitive younger consumers with limited kitchen facilities. Dormitory and shared-housing contexts across Chinese and Southeast Asian university towns sustain economy instant soup volume.
Families represent the deepest installed base. Health-Conscious Consumers are where portfolio premiumization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing acceptance in Tokyo and Seoul diverges sharply from value-driven purchasing across Indonesian and Philippine urban corridors. This asymmetry shapes manufacturer portfolio segmentation and cold-chain investment prioritization across the region.
Japan
Health-conscious urban professionals in Tokyo and Osaka sustain demand for sodium-reduced ready-to-eat formats. Japan's Consumer Affairs Agency enforces strict nutritional labeling standards that compel reformulation toward clean-label compliance. Kanto region manufacturing clusters concentrate high-pressure processing capacity for chilled vegetable soups.
China
Tier-one cities including Shanghai and Beijing drive premium soup adoption through mature cold-chain logistics networks. China's National Health Commission issues dietary guidelines that indirectly pressure manufacturers toward lower-sodium profiles. Yangtze River Delta distribution hubs enable refrigerated last-mile delivery for fresh-positioned formats.
South Korea
Seoul's dense office districts sustain single-serve instant and chilled soup velocity among time-constrained workers. South Korea's Ministry of Food and Drug Safety regulates sodium disclosure requirements that shape front-of-pack labeling strategies. Convenience store networks in the capital region anchor grab-and-go format penetration.
Australia
Melbourne and Sydney households exhibit highest subscription penetration for direct-to-pantry premium soup delivery. Australia's Food Standards Code governs health claim eligibility, restricting functional benefit marketing on packaging. Victorian and New South Wales supermarket chains accelerate adoption of high-pressure processed chilled varieties.
Indonesia
Family units across Jakarta and Surabaya drive volume demand for large-format instant soup sachets. Indonesia's national food and drug regulator enforces evolving labeling requirements that challenge existing portfolio salt levels. Archipelago retail networks concentrate distribution of value-positioned dehydrated formats.
Asia-Pacific Soup Market Competitive Environment
Multinational conglomerates and domestic manufacturing specialists split the market across format tiers. The vendor base concentrates around three strategic archetypes: diversified food conglomerates with cross-category scale, regional instant noodle specialists leveraging distribution density, and health-positioned challengers exploiting clean-label gaps. Capacity expansion in retort packaging and cold-chain partnerships represent the dominant competitive moves as players defend shelf presence.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever PLC occupy positions spanning multiple price points and format categories. Nongshim Co., Ltd. exemplifies the regional specialist archetype with manufacturing scale concentrated in its domestic market. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across premium and mass-market segments.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Nongshim Co., Ltd. |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Indofood Sukses Makmur |
| Unilever PLC |
| Nissin Foods Holdings Co., Ltd. |
| General Mills, Inc. |
| Campbell Soup Company |
| Others |
Value Chain & Pricing Dynamics
Thailand's retort packaging corridor concentrates shelf-stable liquid soup capacity, granting its manufacturers asymmetric leverage over pricing negotiations with brands dependent on ambient distribution networks. This geographic chokepoint amplifies margin pressure when input costs fluctuate, forcing downstream players to absorb volatility or reformulate toward alternative formats.
Pricing Analysis
The customization-premium spread in Asia-Pacific soup markets separates configured-to-order chilled formulations from standard dehydrated sachets. Three-tier pricing structure across premium, standard, and economy levels tracks cold-chain access and sodium certification tiers. Pricing pressure stems from wheat and palm oil commodity swings squeezing margin structures in mass-market instant segments. Family purchasers across Indonesian and Philippine markets exhibit highest price sensitivity, while health-conscious professionals in Tokyo and Sydney accept substantial premiums for clean-label positioning.
Supply Chain Analysis
Extended payment terms from Thai and Malaysian retort packaging suppliers to soup manufacturers compress working capital cycles across the industry. Geographic supply concentration centers on Thailand, Malaysia, and South Korea for thermal processing equipment and packaging substrates. Raw material dependencies rest on Australian wheat, Indonesian palm oil derivatives, and Chinese vegetable concentrate inputs. Single-source vulnerability pervades retort pouch film supply. Distribution runs through archipelago retail networks in Indonesia and convenience store chains in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific soup market constitutes a defensive-moat opportunity anchored in regulatory entrenchment. Japan's sodium labeling mandates and Australia's health claim eligibility rules erect compliance barriers that favor established reformulation capabilities over new entrants lacking technical infrastructure.
For Market Incumbents: Pre-empt emerging clean-label challengers by accelerating sodium-reduced pipeline development ahead of Southeast Asian warning label expansion. Secure captive supply of salt replacer systems through backward integration into Japanese and South Korean umami technology specialists. Defend shelf position in South Korean convenience channels through exclusive cold-chain partnerships that raise rival distribution costs.
For New Entrants and Emerging Players: Vietnamese secondary cities including Da Nang and Can Tho present underpenetrated modern trade coverage where premium chilled formats lack established competitors. Target health-positioned subscription models in Australian metropolitan markets where algorithmic personalization displaces incumbent brand loyalty. Pursue direct-to-pantry go-to-market angles leveraging e-commerce platform partnerships rather than conventional retail slotting fee battles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with hybrid thermal-non-thermal processing capabilities that bridge shelf-stable and fresh-positioned formats. The five-to-ten year viability window rewards targets possessing high-pressure processing expertise and established cold-chain relationships in tier-one Chinese and Japanese markets. Watch for inflection signals in Southeast Asian front-of-pack warning label implementation timelines that would accelerate incumbent portfolio restructuring and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction Reformulation | Achieves compliance with Japan's Consumer Affairs Agency labeling mandates ahead of enforcement deadlines. |
| Cold-Chain Partnership Expansion | Secures refrigerated last-mile density in Shanghai and Tokyo for premium ready-to-eat positioning. |
| Direct-to-Consumer Subscription Launch | Displaces supermarket aisle discovery with algorithmic personalization in Melbourne and Sydney households. |
| Modified Atmosphere Packaging Adoption | Extends chilled soup shelf life without thermal degradation through high-pressure processing hybridization. |
| Southeast Asian Distribution Buildout | Captures underpenetrated modern trade coverage in Vietnamese secondary cities before incumbent response. |
Study Parameters
A standing panel of category buyers at Australian supermarket chains, brand managers at Japanese and South Korean manufacturers, supply planners at Indonesian retail networks, and regulatory affairs specialists across the region provided ongoing calibration for demand assumptions. This primary intelligence combined with secondary validation from customs records, Nielsen retail audit data, national food regulator filings, and SEC disclosures from listed food conglomerates. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity disclosures and import-export flows.
Scenario-bracketing framed analytical approach across the projection horizon, testing sensitivity to sodium regulation acceleration and cold-chain infrastructure buildout pace. Segmentation dimensions modeled included product format, ingredient type, distribution channel, and consumer archetype alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves anchored to observable penetration rates in comparable adjacent markets. Forecast inputs incorporated wheat and palm oil futures trajectory assumptions and convenience store channel expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label entrants or technology-led challengers would shift outcomes beyond modeled ranges. Macroeconomic deviation, regulatory enforcement acceleration, or breakthrough processing technology commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Spray Cheese Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
South America Soup Market
Processed Foods
Fruit Processing Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Industrial Margarine Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Processed Egg Market
Processed Foods
Block Margarine Market
Processed Foods
Potato Soup Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
North America Ice Cream Market
Processed Foods
Fat Free Soup Market
Processed Foods
Casual Marinated Products Market