
 Processed Vegetable Market | 2026-2036
Processed Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Vegetable Market Analysis
Food processing labor availability is reorganizing regional production economics, particularly in Midwestern canning corridors where seasonal harvest peaks strain permanent staffing. Conagra Brands leverages its multi-plant network to sustain year-round output across vegetable categories. Bonduelle SCA anchors European supply through its frozen vegetable specialization. Seneca Foods Corporation dominates private-label canned vegetable contracts with North American retailers.
Processed vegetables comprise raw or minimally cooked plant materials preserved through thermal processing, dehydration, acidification, or freezing to achieve shelf stability and nutrient retention, typically standardized to moisture content, salt concentration, or blanching time specifications for downstream food manufacturing and direct consumption. Frozen vegetables command the fastest expansion as food service buyers prioritize yield consistency and reduced prep labor, while canned vegetables retain volume leadership in emergency relief and institutional procurement channels where storage longevity outweighs texture preferences. Pouch packaging is gaining share from rigid formats in household segments seeking microwave-ready convenience and reduced shipping weight.
The FDA enforces Hazard Analysis and Risk-Based Preventive Controls under FSMA, compelling processors to validate kill-step temperatures and allergen segregation protocols across multi-vegetable production lines. USDA grading standards for canned and frozen vegetables shape contract specifications between processors and institutional buyers, creating tiered market access based on defect tolerances and uniformity scores. Stakeholders must weigh capital allocation between aseptic pouch capacity and traditional canning infrastructure as distribution channels fragment between e-commerce fulfillment and food service broadline distribution.
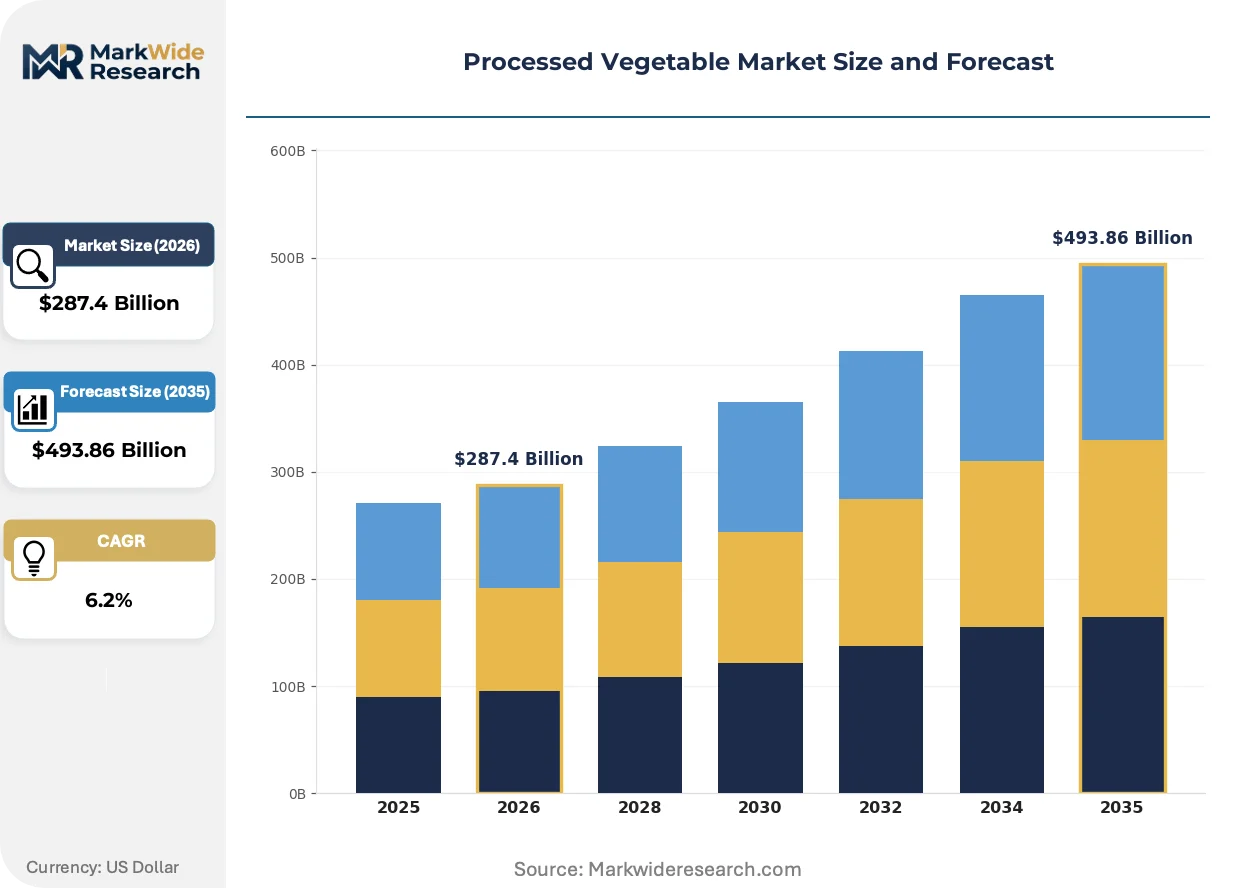
Market Dynamics
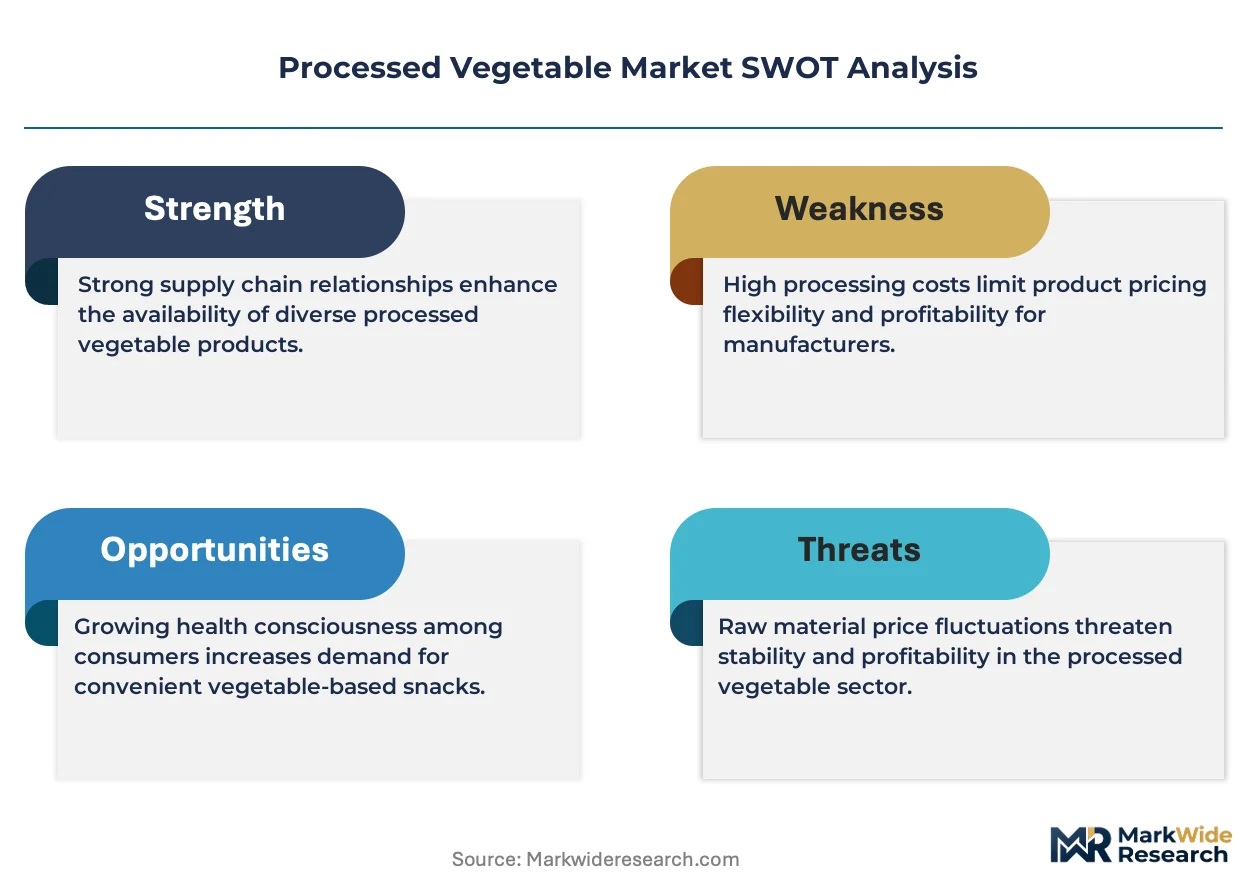
FSMA traceability mandates are compressing supplier consolidation timelines as food service buyers demand validated kill-step documentation before contract renewal, forcing mid-scale processors to choose between capital-intensive HACCP upgrades and exit.
Growth Catalysts
- Food service yield standardization:Institutional kitchens prioritize frozen vegetable portion consistency to reduce prep labor and waste, expanding procurement volumes from broadline distributors.
- FDA preventive control enforcement:The Food Safety Modernization Act's updated human food rules compel processors to document supply chain hazards, advantaging facilities with existing validated protocols.
- Blanching automation:Continuous steam blanching systems reduce water usage and energy intensity while improving nutrient retention, attracting sustainability-focused retail chains.
Market Restraints
- Seasonal labor scarcity:Midwestern canning corridors face permanent staffing gaps during harvest peaks, forcing overtime premiums that erode margin on commodity contracts.
- Aluminum can sheet concentration:Domestic steel and aluminum input supply concentrates among limited domestic smelters, exposing processors to tariff-driven cost volatility.
- Texture degradation in long-shelf formats:Canned vegetables suffer irreversible cellular breakdown during retort processing, limiting penetration in premium household segments.
Strategic Opportunities
- India cold chain expansion:FSSAI modernization and private cold storage investment enable frozen vegetable distribution beyond urban coastal corridors into tier-two cities.
- Aseptic pouch capacity:Retort pouch lines offer microwave-ready convenience with reduced shipping weight, capturing e-commerce fulfillment channels.
- EU Green Deal farm-to-fork targets:The European Commission's 25% organic land use mandate by 2030 creates contract windows for certified organic processed vegetable suppliers.
Industry Challenges
- Multi-allergen line segregation:Shared equipment processing celery, mustard, and sulfite-treated vegetables demands validated cleaning protocols that extend changeover downtime.
- Legacy ERP integration:Traceability software upgrades must interface with decades-old production scheduling systems, delaying FSMA compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Vegetable Market |
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $493.86 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Vegetables, Frozen Vegetables, Dried Vegetables, Pickled Vegetables Packaging Type: Bags, Jars, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Food Service, Restaurants, Catering Services |
| Companies Covered | Conagra Brands, The Kraft Heinz Company, Ardo, Seneca Foods Corporation, Del Monte Foods, Dole Food Company, Bonduelle SCA, General Mills, B&G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Vegetable Market Emerging Trajectories
Processing equipment and packaging formats are converging around labor reduction and energy efficiency, with automation investments accelerating as wage pressures outpace equipment depreciation schedules.
High-pressure processing (HPP) for vegetable-based ready meals is miniaturizing from industrial batch systems to in-line continuous units. Food service manufacturers adopting HPP report extended refrigerated shelf life without thermal degradation. The technology is miniaturizing capital requirements for mid-scale co-packers, enabling regional processors to compete with national frozen brands on clean-label positioning.
REACH chemical restrictions in the European Union are phasing out certain epoxy-based can coatings, compelling manufacturers to accelerate migration to polyester and acrylic alternatives. Canneries serving EU export markets face reformulation timelines that compress R&D windows. Spanish and Italian vegetable processors report the tightest certification deadlines as they supply both domestic retail and North African institutional buyers.
Direct sourcing contracts between retail chains and regional freezing cooperatives are displacing traditional broker-mediated procurement in the United States. Kroger and Albertsons have established preferred supplier programs that bypass broadline distributors for frozen vegetable categories. The Upper Midwest and Pacific Northwest growing regions show the densest contract concentration as retailers optimize for truckload consolidation and reduced handling points.
Processed Vegetable Market Segmentation
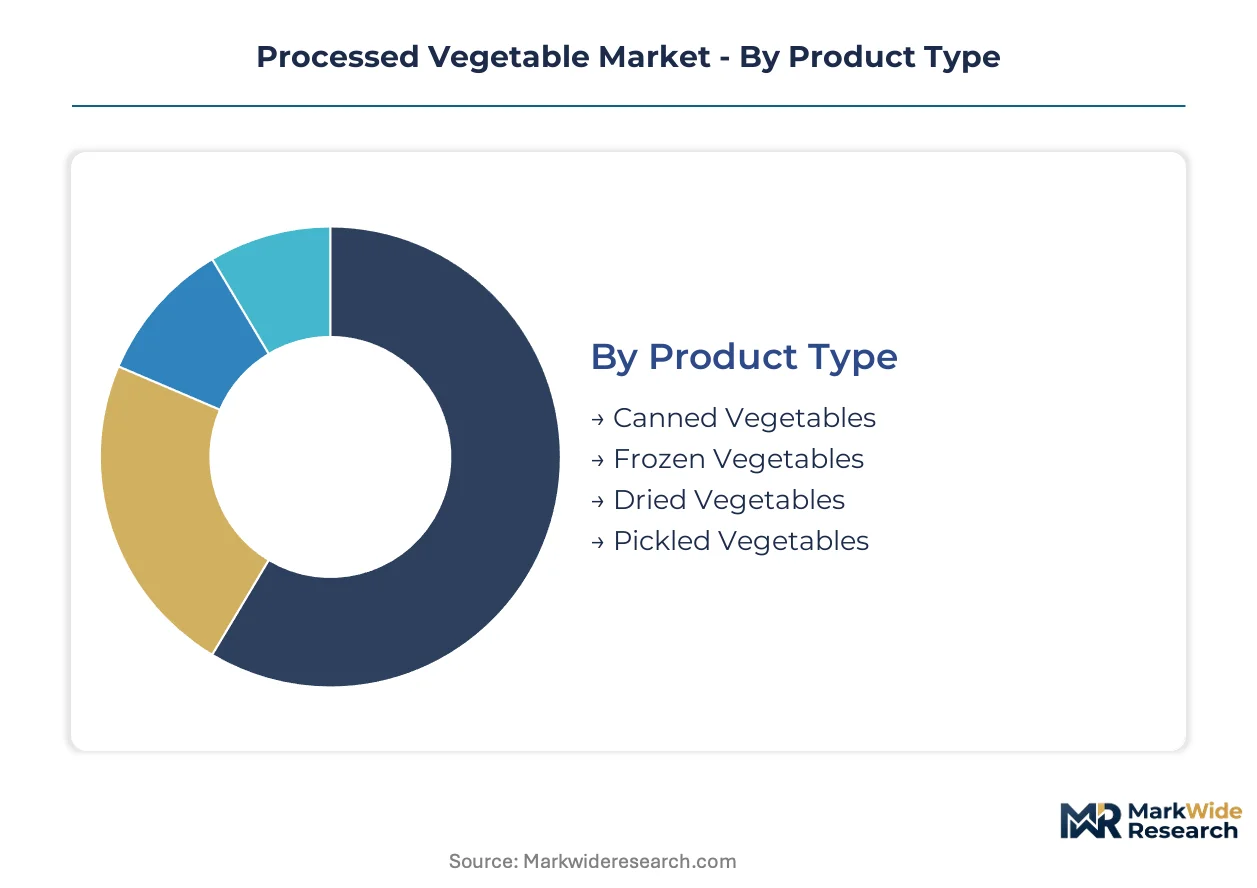
Segmentation in processed vegetables reveals how preservation technology, packaging format, and channel economics allocate margin across the value chain. Procurement specifications from institutional buyers and retail chains now override traditional commodity trading patterns.
Product Type:
FDA preventive controls under FSMA impose divergent validation burdens across thermal and non-thermal preservation methods.
- Frozen Vegetables:Rapid individual quick freezing preserves cellular structure and nutrient density. Food service buyers in the United States prioritize portion-controlled formats to reduce kitchen labor, driving procurement consolidation through broadline distributors.
- Canned Vegetables:Retort processing achieves commercial sterility through sustained high-temperature treatment. Institutional procurement channels favor these formats for emergency stockpiles and school nutrition programs where shelf stability outweighs texture degradation.
- Dried Vegetables:Dehydration removes moisture to inhibit microbial growth; lightweight formats serve backpacking and military ration applications.
- Pickled Vegetables:Acidification with vinegar or fermentation creates shelf-stable products with distinct flavor profiles for ethnic cuisine segments.
Established volume favors canned formats; emerging adoption favors frozen varieties.
Packaging Type:
Material selection determines shipping economics and microwave compatibility across distribution channels.
- Pouches:Multilayer flexible films enable retort sterilization with reduced shipping weight. E-commerce fulfillment channels favor these formats for dimensional efficiency in parcel networks.
- Cans:Aluminum and steel containers maintain oxygen barrier integrity through extended distribution cycles. Domestic smelter concentration exposes processors to tariff volatility.
- Bags:Polyethylene films suit frozen vegetable bulk packs for food service institutional procurement.
- Jars:Glass containers serve pickled vegetable segments where premium positioning justifies higher unit costs.
Legacy infrastructure anchors can demand; sustainability pressures accelerate pouch conversion.
Distribution Channel:
Channel control determines traceability documentation requirements and lot-size economics.
- Supermarkets:Retail chains demand validated kill-step documentation and allergen segregation protocols for private-label procurement.
- Wholesale:Broadline distributors consolidate truckload volumes from multiple processors for food service institutional delivery.
- Online Retail:Direct-to-consumer fulfillment requires parcel-compatible packaging and inventory visibility systems.
- Convenience Stores:Small-format retail prioritizes shelf-stable single-serve units with extended dating.
Consolidated procurement favors wholesale; fragmentation favors online retail expansion.
End User:
User specifications diverge on yield consistency, prep labor reduction, and storage infrastructure.
- Food Service:Institutional kitchens specify frozen vegetable portion packs to standardize plate costs and minimize waste.
- Restaurants:Full-service operators balance prep labor savings against premium positioning for fresh-like texture.
- Households:Retail consumers prioritize microwave-ready convenience and resealable formats for smaller household sizes.
- Catering Services:Event-based volume demands shelf-stable formats with flexible portion scaling.
Labor cost pressures favor food service automation; convenience positioning favors household pouch adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preventive controls under FSMA have restructured procurement relationships across the United States, while parallel regulatory tightening in the European Union and emerging cold chain investments in India reshape competitive access.
United States
Institutional buyers and retail chains consolidate supplier relationships around validated kill-step documentation. The FDA enforces Hazard Analysis and Risk-Based Preventive Controls, compelling processors to upgrade HACCP protocols. Midwestern canning corridors from Wisconsin to Illinois strain under seasonal harvest labor peaks.
France
Bonduelle SCA anchors European frozen vegetable supply through specialized production networks. EFSA standards and EU Green Deal farm-to-fork targets drive organic certification requirements. Northern French processing clusters near Lille supply both domestic retail and export channels.
India
FSSAI modernization enables frozen vegetable distribution beyond urban coastal corridors into tier-two cities. Private cold storage investment accelerates under government PLI scheme incentives. Maharashtra and Gujarat host the densest contract farming concentrations for pea and corn processing.
Germany
REACH chemical restrictions phase out epoxy-based can coatings, compressing reformulation timelines for exporters. The country's central European position supports distribution hub functions for North African institutional buyers. Baden-Württemberg packaging specialists accelerate polyester and acrylic alternative testing.
China
SAMR food safety standards tighten traceability requirements for domestic and export markets. Yangtze River Delta freezing cooperatives expand direct sourcing contracts with international retail chains. Zhejiang and Jiangsu provinces concentrate aseptic pouch manufacturing capacity.
Processed Vegetable Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in multi-plant networks and private-label contract density determining procurement access. The structure rewards backward integration into agricultural sourcing and capital-intensive equipment automation. Three archetypes dominate: diversified packaged food conglomerates with vegetable category presence, frozen vegetable specialists with European supply anchoring, and private-label contract manufacturers serving North American retail consolidation. Competitive moves concentrate on aseptic pouch capacity expansion and direct sourcing partnerships that bypass traditional distributor layers.
Among the integrated packaged food tier, Conagra Brands and General Mills represent scale-driven portfolio diversification across frozen and shelf-stable formats. Bonduelle SCA exemplifies the European specialist archetype with frozen vegetable concentration. Seneca Foods Corporation occupies the private-label manufacturing position, anchoring North American retailer contract relationships. These three entities collectively illustrate how procurement consolidation favors players with validated FSMA protocols and multi-channel distribution infrastructure.
| Leading Market Players |
|---|
| Conagra Brands |
| The Kraft Heinz Company |
| Ardo |
| Seneca Foods Corporation |
| Del Monte Foods |
| Dole Food Company |
| Bonduelle SCA |
| General Mills |
| B&G Foods |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles in Midwestern canning corridors concentrate pricing power among processors with validated FSMA protocols, while spot-market buyers face tariff-driven aluminum volatility that compresses contract margins.
Pricing Analysis
Midwestern contract premiums over Pacific Northwest frozen vegetable benchmarks reflect trucking cost differentials and FSMA compliance investment recovery. Pricing stratifies across premium, standard, and economy tiers based on USDA grade certification and organic accreditation. Pricing pressure stems from seasonal labor premiums that erode commodity contract profitability. Institutional food service buyers exhibit highest price sensitivity due to fixed-budget procurement mandates, while premium retail chains absorb certification premiums for traceability assurance.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes inflate inbound logistics costs for epoxy-free can coating materials bound for EU export facilities. Supply concentrates in the United States, France, and China, with each anchoring distinct preservation technology specializations. Raw material dependencies center on aluminum sheet, frozen vegetable feedstock, and multilayer pouch films. Tariff exposure on domestic smelter supply creates single-source vulnerability for North American canners. Distribution runs through broadline distributors for food service consolidation and direct retail chain contracts for frozen categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through FSMA validation protocols creates switching costs that institutional buyers cannot readily circumvent.
For Market Incumbents: Fortify multi-plant network redundancy to offset seasonal labor scarcity in Midwestern corridors. Deepen backward integration into contract farming in the Upper Midwest and Pacific Northwest to secure feedstock priority. Expand aseptic pouch capacity ahead of e-commerce fulfillment channel growth. Prioritize ERP-traceability system integration to compress FSMA compliance timelines against mid-scale competitors. For New Entrants and Emerging Players: Lead with aseptic pouch specialization targeting online retail fulfillment channels where dimensional efficiency commands premium positioning. Target India's tier-two city expansion where FSSAI modernization and private cold storage investment outrun established frozen vegetable distribution. Penetrate organic processed vegetable segments ahead of EU Green Deal farm-to-fork procurement mandates. Deploy direct sourcing partnerships with regional freezing cooperatives to bypass entrenched broadline distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaged food conglomerates seeking portfolio rationalization away from commodity vegetable categories. Frame long-term viability around regulatory compliance infrastructure as a durable asset with decade-scale depreciation. Pursue mid-scale processors with validated HACCP protocols and underutilized pouch capacity. Monitor FSSAI enforcement intensity in India as inflection signal for emerging market frozen vegetable penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Pouch Capacity Expansion | Captures e-commerce fulfillment growth with microwave-ready formats that reduce shipping weight. |
| Backward Integration into Contract Farming | Secures feedstock priority in Upper Midwest and Pacific Northwest growing regions ahead of harvest peaks. |
| FSMA Traceability System Upgrade | Validates kill-step documentation for institutional buyer contract renewal and procurement consolidation. |
| Direct Sourcing Partnership Programs | Bypasses broadline distributor layers to capture margin from Kroger and Albertsons preferred supplier structures. |
| Organic Certification Investment | Positions for EU Green Deal farm-to-fork procurement mandates and premium retail channel access. |
Methodological Framework
A spread of perspectives from food processing plant managers, institutional procurement officers at broadline distributors, retail category buyers, and cold chain logistics specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA FSMA guidance documents, USDA grading standards, FSSAI modernization circulars, and customs trade data on aluminum and vegetable feedstock flows. Bottom-up capacity modeling across preservation technology segments triangulated against top-down demand aggregation from food service and retail channels.
Segmentation dimensions modeled include preservation technology, packaging format, distribution channel, and end-user specification across the projection horizon. CAGRs were derived from volume trajectory analysis incorporating seasonal harvest patterns, labor availability constraints, and regulatory compliance timelines. Industry-specific forecast inputs encompassed cold chain investment rates in India, EU organic land use mandate implementation pacing, and aluminum tariff exposure scenarios.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity, stable aluminum supply pricing, and cold chain infrastructure investment continuity would require recalibration. Forecasts reflect documented assumptions regarding institutional procurement consolidation trajectories and e-commerce fulfillment channel penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Superfruits Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Broth Market
Processed Foods
Tomato Puree Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
South America Soup Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Apple Butter Market
Processed Foods
Butter Crisco Market
Processed Foods
Processed Peanut Market
Processed Foods
Processed Mango Products Market
Processed Foods
Global Pasta Market