
 Soup Market | 2026-2036
Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Soup Market Intelligence
Demand from health-conscious and time-constrained working professionals is collapsing the traditional distinction between shelf-stable convenience and fresh, artisanal quality. Campbell Soup Company leverages its extensive distribution network to place premium ready-to-eat options in mainstream supermarkets. Unilever PLC competes by innovating with plant-based and globally inspired flavor profiles in its instant and powdered soup lines. Nestle S.A. sustains its market position through significant R&D investment in low-sodium and fortified soup formulations.
Soup is a primarily liquid food, generally served warm or hot, made by combining ingredients of meat or vegetables with stock, milk, or water. Commercial production involves processes like retort canning or aseptic packaging to ensure shelf stability and microbiological safety. Within product types, ready-to-eat soup formats are gaining share over traditional canned soup due to convenience. Online retailers are emerging as the fastest-growing distribution channel, challenging the long-held dominance of supermarkets.
Food safety and labeling regulations from bodies such as the US FDA, the European Food Safety Authority (EFSA), and the FSSAI in India govern sodium content, allergen declarations, and health claims. These standards directly influence product formulation and packaging choices for manufacturers seeking market access in these key geographies. Producers must navigate the challenge of developing healthier, clean-label products while managing input cost volatility for key vegetable and protein ingredients.
Market Dynamics
The central tension shaping the soup market is the consumer demand for both extreme convenience and fresh, clean-label ingredients. This dynamic is forcing manufacturers to overhaul traditional production and packaging methods to deliver shelf-stable products with an artisanal quality.
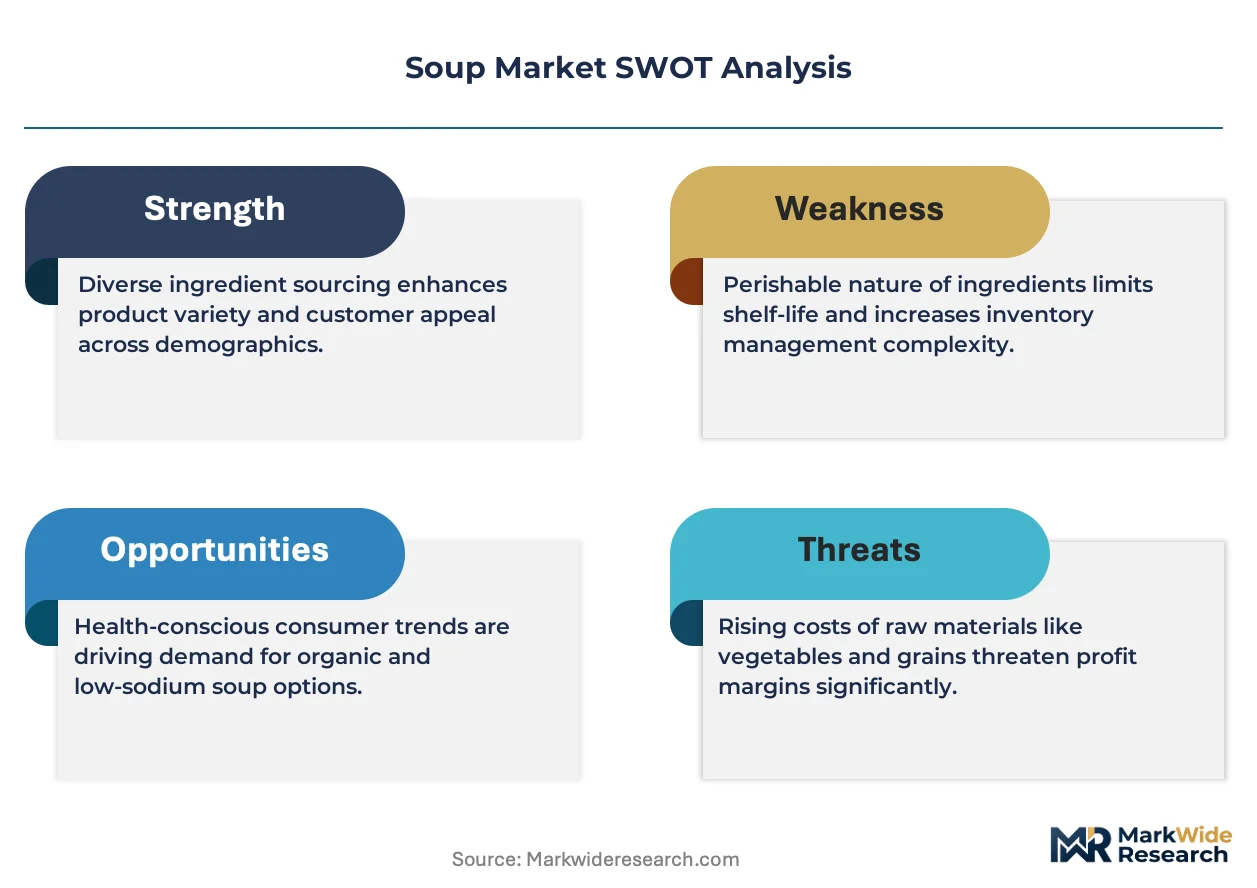
Growth Catalysts
- Aseptic Packaging Technology:This process allows for shelf-stable soups without requiring refrigeration or extensive preservatives, directly meeting consumer demand for cleaner ingredient lists and longer pantry life.
- Urban Consumption Patterns:Increasing population density in cities within Germany, the United States, and Japan concentrates demand from time-constrained working professionals who prioritize ready-to-eat meal solutions.
- Plant-Based Diet Adoption:The mainstreaming of vegetarian and vegan diets creates significant demand for innovative vegetable- and legume-based soup formulations, expanding the category beyond traditional meat and dairy bases.
Market Restraints
- Input Cost Volatility:Manufacturers face unpredictable pricing for key agricultural inputs, including vegetables, legumes, and protein sources, which directly impacts final product margins and pricing stability.
- Sodium Reduction Mandates:Regulatory pressure from bodies like the US FDA and Europe's EFSA to lower sodium content presents a significant formulation challenge, as reducing salt can negatively affect taste and preservation.
- Threat from Meal Kits:The rise of fresh meal kit delivery services presents a direct substitution threat, offering a similar value proposition of convenience and fresh ingredients for home-cooked meals.
Strategic Opportunities
- Functional Formulations:There is a growing opportunity for soups fortified with functional ingredients that target specific wellness benefits, such as immune support, gut health, or cognitive function.
- DTC Subscription Models:Direct-to-consumer channels allow brands to bypass crowded retail environments, cultivate direct customer relationships, and gather valuable data for product development and personalization.
- Expansion in Southeast Asia:Rising disposable incomes and the increasing adoption of Western dietary habits in emerging economies present a significant white-space opportunity for packaged soup products.
Industry Challenges
- Cold Chain Management:The growing segment of fresh, refrigerated soups requires a robust and costly cold chain infrastructure to ensure product safety and quality from the factory to the consumer's home.
- Allergen Labeling Complexity:Manufacturers must navigate a patchwork of international allergen declaration laws, such as those enforced by the US FDA and EFSA, which complicates packaging and export strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soup Market |
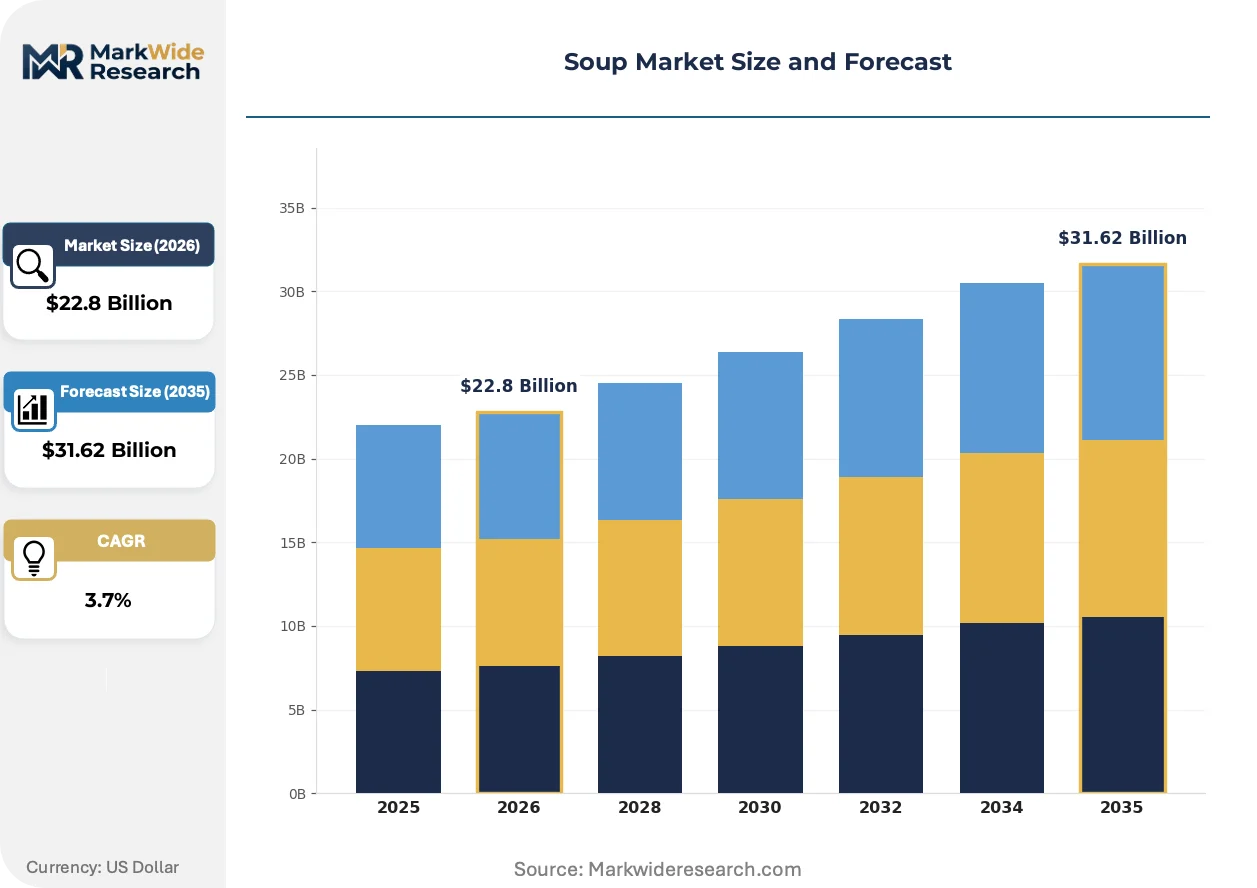
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Instant Soup, Ready-to-Eat Soup, Frozen Soup, Powdered Soup Flavor: Chicken, Tomato, Vegetable, Mushroom, Seafood, Beef Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Wholesale Clubs Consumer Demographic: Children, Adults, Elderly, Athletes, Working Professionals |
| Companies Covered | Conagra Brands, Inc., Unilever PLC, Campbell Soup Company, B&G Foods, Inc., The Hain Celestial Group, Inc., Nestle S.A., The Kraft Heinz Company, Ajinomoto Co., Inc., General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soup Market Strategic Shifts & Innovations
Product development is increasingly driven by the fusion of food science with data analytics, enabling the creation of soups that meet highly specific dietary, functional, and flavor preferences. This moves the category beyond simple convenience toward personalized nutrition.
High-pressure processing (HPP) is a non-thermal pasteurization technique that preserves the flavor, color, and nutritional value of fresh ingredients. Premium and artisanal soup brands are rapidly adopting HPP for their chilled, ready-to-eat product lines. This technology is miniaturizing the quality and taste gap between a packaged product and a freshly prepared one, supporting premium price positioning.
Front-of-pack nutrition labeling systems, including Nutri-Score in several European countries, are directly influencing consumer purchasing decisions. This regulatory visibility is forcing brands to reformulate products to achieve more favorable scores, especially by lowering sodium and fat. Mass-market canned and powdered soup categories are the most affected, accelerating R&D into healthier formulations.
Subscription-based purchasing models are altering how consumers buy soup, moving away from single, large shopping trips. This shift disrupts the historical dominance of supermarkets and hypermarkets for shelf-stable goods, creating an opening for specialized e-commerce platforms. The trend is most pronounced in dense urban areas across the United States and Japan with mature logistics networks.
Soup Market Segmentation
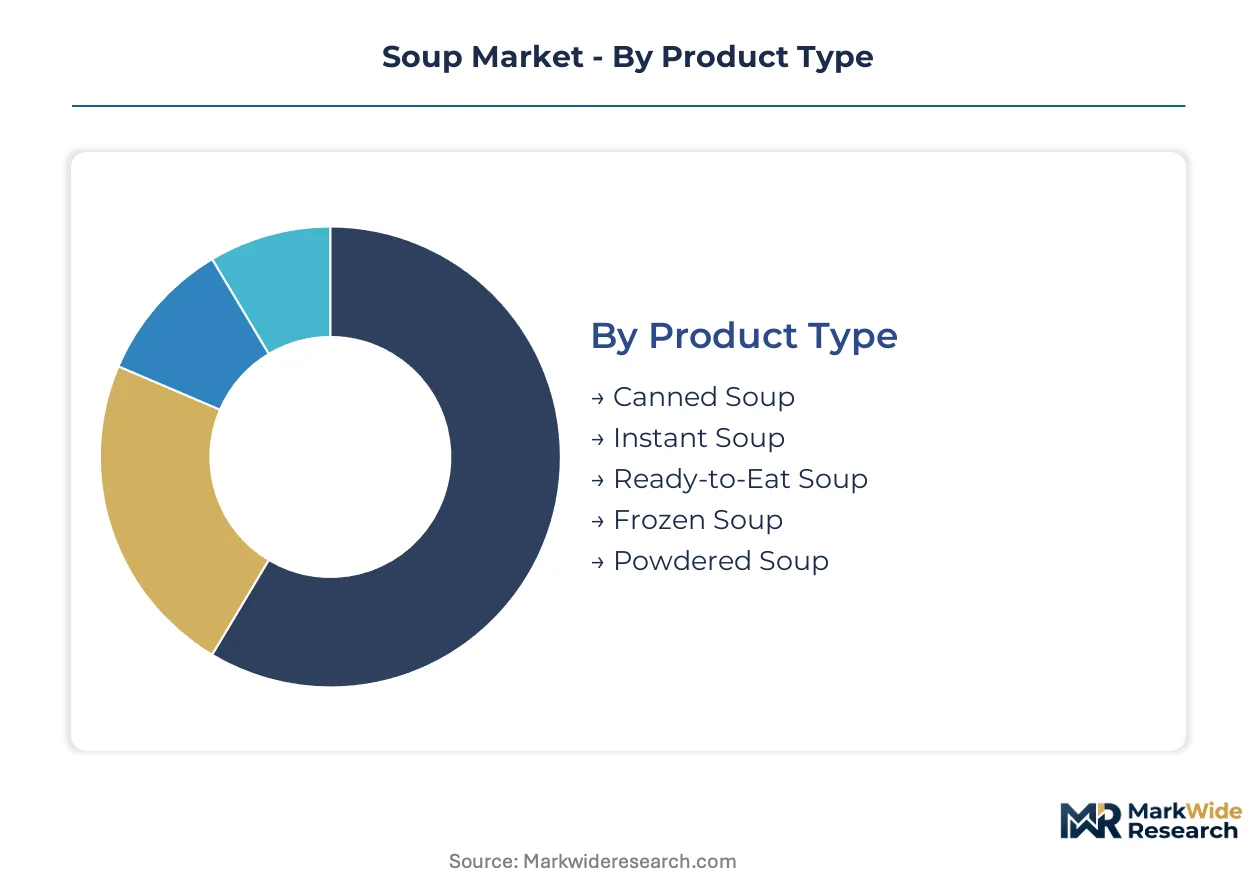
The soup market exhibits diverse segmentation, reflecting varied consumer preferences and evolving lifestyle demands. Understanding these distinct segments is crucial for manufacturers to tailor product development and optimize market penetration strategies. This analysis highlights the key categories shaping the industry's competitive landscape.
Product Type:
The product type segment faces intense substitution pressure, particularly for traditional formats challenged by newer, more convenient alternatives.
- Ready-to-Eat Soup:These convenience-focused products require minimal preparation, often in microwaveable containers. Demand concentrates in urban areas like New York and Tokyo, driven by time-constrained working professionals seeking quick meals.
- Canned Soup:This traditional format uses retort canning for extended shelf stability, containing broth, vegetables, and proteins. Volume remains significant in the United States and Germany, supported by consumer familiarity and broad retail availability.
- Instant Soup:Powdered or dehydrated formulations offer extreme convenience, popular among students and office workers.
- Frozen Soup:These products maintain freshness through freezing, positioned as premium, requiring cold chain logistics.
- Powdered Soup:Dehydrated ingredients in sachet or canister form provide long shelf life, favored in cost-sensitive segments.
Canned Soup retains volume leadership; Ready-to-Eat Soup holds the steepest expansion curve.
Flavor:
Flavor profiles often align with different cost tiers, where premium ingredients and complex recipes command higher price points.
- Vegetable:Comprising various plant-based ingredients, these soups align with vegetarian and vegan dietary trends, often featuring clean labels. Demand is strong in Europe, particularly Germany, driven by health-conscious consumers.
- Chicken:A classic and widely consumed flavor, typically featuring chicken broth, meat, and vegetables, appealing broadly. This flavor maintains consistent popularity across the United States and Japan, valued for its comfort food association.
- Tomato:A versatile and popular base, often consumed standalone or as an ingredient, appealing to diverse palates.
- Mushroom:Earthy and savory, this flavor targets gourmet or specialty segments, often with exotic mushroom varieties.
- Seafood:Featuring fish or shellfish, these soups are popular in coastal regions for specialized culinary experiences.
- Beef:Robust and hearty, beef-based soups often include meat chunks, popular in colder climates for satiety.
Demand for Vegetable flavors is driven by plant-based preferences; Chicken remains a foundational choice across many markets.
Distribution Channel:
Each distribution channel serves distinct application scenarios, from immediate consumption needs to bulk household stocking.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales and subscription models, offering convenience and broader selection. This channel represents the fastest-growing trajectory in the United States and Japan, supported by mature logistics.
- Supermarkets:Large retail formats offer extensive shelf space for various soup brands, serving as the primary purchasing point for households. They dominate volume sales across Germany and the United States, leveraging broad consumer reach.
- Convenience Stores:These outlets cater to impulse purchases, stocking single-serve options for on-the-go consumers.
- Specialty Stores:Focused on gourmet, organic, or niche products, these stores attract consumers seeking premium or health-oriented formulations.
- Wholesale Clubs:Membership-based warehouses offer bulk quantities at competitive prices, appealing to large families and institutional buyers.
The shift towards Online Retailers reflects evolving consumer purchasing habits, impacting traditional Supermarket dominance.
Consumer Demographic:
Different consumer demographics exhibit unique purchasing behaviors and prioritize specific attributes in their soup choices.
- Working Professionals:This demographic prioritizes speed and ease of preparation, driving demand for ready-to-eat and instant soups. They concentrate in urban centers of Germany and the United States, seeking convenient, nutritious meals.
- Adults:Representing the broadest segment, this group seeks a balance of taste, nutritional value, and price across soup types. Their demand spans all geographies, including Japan and India, influencing product lines.
- Children:This segment often prefers milder flavors and fun packaging, with parents prioritizing nutritional content.
- Elderly:This demographic often seeks easily digestible, low-sodium, and fortified options, with convenience and nutrition key factors.
- Athletes:These consumers look for protein-rich, functional soups that support recovery and energy.
Working Professionals prioritize convenience attributes, influencing product development for the broader Adults segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for packaged soup flows from established markets like the United States to emerging economies in Southeast Asia. This trade reflects evolving consumer preferences for both extreme convenience and health attributes across diverse geographies. Manufacturers are tailoring product lines to meet regional tastes and stringent regulatory requirements.
United States
Demand for ready-to-eat soups in the United States concentrates among time-constrained working professionals seeking quick, nutritious meals. The US FDA enforces strict food safety and labeling standards, influencing product formulations and ingredient sourcing. Urban centers like New York City and Los Angeles drive significant consumption of premium, convenient soup options.
Germany
Health-conscious consumers in Germany prioritize vegetable-based and clean-label soup options, driving market growth. The European Food Safety Authority (EFSA) mandates clear allergen declarations and sodium content limits for all food products. High-density urban areas such as Berlin and Munich exhibit strong demand for fresh and refrigerated soup formats.
Japan
Time-constrained urban populations in Japan fuel the market for instant and ready-to-eat soup varieties, favoring convenience. Japan's Ministry of Economy, Trade and Industry (METI) promotes innovation in food processing and aseptic packaging technologies. Tokyo's mature logistics networks support the growth of online retail channels for diverse soup products.
India
Rising disposable incomes in India contribute to the increasing adoption of Western dietary habits, including packaged soups. The FSSAI regulates food product safety and nutritional labeling, impacting new product introductions. Major metropolitan areas like Mumbai and Delhi are seeing expanded distribution of instant and powdered soup lines.
United Kingdom
Consumers in the United Kingdom show a preference for functional and plant-based soup formulations, aligning with wellness trends. The UK's Food Standards Agency (FSA) oversees allergen information and health claims on food packaging. London's diverse culinary scene encourages innovation in globally inspired flavor profiles for soup products.
Soup Market Key Industry Players
Listed leaders compete with private specialists across product innovation and distribution reach. The market structure exhibits consolidation among established brands, alongside fragmentation from numerous niche players. Strategic archetypes include global food conglomerates, regional convenience specialists, and artisanal fresh soup producers. Companies often pursue portfolio diversification and geographic expansion to secure market share.
Within the global food conglomerate archetype, Unilever PLC and Nestle S.A. represent extensive research and development capabilities, particularly in plant-based and fortified formulations. Unilever PLC, a European multinational, often innovates with globally inspired flavor profiles for its instant and powdered soup lines. Nestle S.A., a Swiss multinational, anchors the market through significant R&D investment in low-sodium and fortified soup formulations. Campbell Soup Company, an American corporation, exemplifies a strong focus on ready-to-eat options and leverages established distribution networks in core markets, positioning itself as a leader in convenience.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Unilever PLC |
| Campbell Soup Company |
| B&G Foods, Inc. |
| The Hain Celestial Group, Inc. |
| Nestle S.A. |
| The Kraft Heinz Company |
| Ajinomoto Co., Inc. |
| General Mills, Inc. |
Cost & Logistics Intelligence
Economies of scale in large-batch soup production drive supply concentration among major manufacturers, influencing price floors for mass-market offerings. This dynamic creates a cost advantage for established brands, impacting competitive pricing across various product segments.
Pricing Analysis
The pricing gap between traditional canned soup and high-pressure processed (HPP) fresh soup reflects differing technology generations. A hybrid pricing model exists, combining per-unit transactional sales with subscription models for premium ready-to-eat options. Brand premium for established names like Campbell Soup Company and ingredient quality drive price differentiation. Cost compression in the powdered soup segment intensifies due to input cost volatility for key vegetable and protein ingredients. Students and cost-sensitive consumers exhibit high price sensitivity for instant soups, while working professionals prioritize convenience over lowest price.
Supply Chain Analysis
Just-in-time inventory strategies are common for fresh, refrigerated soup lines, contrasting with strategic stockpiles for shelf-stable canned products. Raw material sourcing concentrates in agricultural regions of the United States, Germany, and India for key vegetables and legumes. The industry relies on consistent supplies of tomatoes, chicken, and various vegetables. Input cost volatility for agricultural commodities presents a significant structural risk. Distribution primarily runs through large supermarket chains and increasingly via online retailers with mature logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soup market offers a service-attach opportunity, with subscription-based purchasing models for ready-to-eat options expanding faster than traditional single-purchase sales.
For Market Incumbents: Secure control over critical ingredient sourcing to mitigate input cost volatility, a persistent threat to margins. Invest in aseptic packaging technology to extend shelf life for clean-label products and expand direct-to-consumer channels. Leverage existing distribution networks to place premium ready-to-eat options, countering competition from fresh meal kits.
For New Entrants and Emerging Players: Nutri-Score certification fast-tracking provides a clear go-to-market angle for health-focused plant-based soup formulations. Target underpenetrated functional soup segments, such as immune support or gut health, for working professionals in urban centers. Southeast Asia represents a highly penetrable geography for innovative packaged soup products.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized HPP soup producers with robust cold chain capabilities. Long-term viability across a five-to-ten-year window hinges on scalable production of clean-label, functional formulations. Acquisition targets should include agile brands innovating in plant-based or globally inspired flavor profiles. The increasing market share of online retailers for premium soup products signals evolving consumer purchasing habits.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expands consumer appeal by introducing globally inspired flavor profiles and functional formulations. |
| Distribution Channel Expansion | Leverages online retailers and direct-to-consumer models to reach time-constrained urban populations. |
| Aseptic Packaging Investment | Ensures shelf stability and microbiological safety for clean-label soups without extensive preservatives. |
| Plant-Based Formulation R&D | Captures demand from health-conscious consumers and aligns with vegetarian and vegan dietary trends. |
| Cold Chain Infrastructure Upgrade | Supports the growing segment of fresh, refrigerated soups, maintaining product quality and safety. |
Research Approach
Desk research of company annual reports, regulatory filings, and industry association publications preceded structured interviews with food scientists, supply chain managers, and retail category buyers. This approach combined primary insights from industry stakeholders with extensive secondary validation. Secondary data sources included trade statistics from the US Department of Agriculture, EFSA reports on food safety, and market data from leading consumer insights firms. Bottom-up market sizing and top-down validation ensured robust data triangulation.
Variance decomposition analysis isolated the impact of key market drivers and restraints on soup market growth across the analysis window. The analytical framework modeled segmentation across product type, flavor, distribution channel, and consumer demographic, alongside packaging innovation. Compound annual growth rates were derived from historical data trends and projected shifts in consumer preferences. Forecast inputs included population density changes in urban areas and plant-based diet adoption rates.
Decision-makers should treat outputs as directional under current regulatory stability and agricultural commodity price assumptions; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging that significant shifts in global trade policies or consumer dietary trends could alter projections. Revision becomes warranted when major food safety regulations or input cost fluctuations cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
India Ready to Mix Food Market
Processed Foods
North America Soup Market
Processed Foods
Global Potato Flake Market
Processed Foods
Tomato Puree Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Dairy Desserts Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Processed Vegetable Market
Processed Foods
Pizza Market
Processed Foods
Apple Butter Market
Processed Foods
Spray Cheese Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Ready to Cook Market
Processed Foods
Ice Cream Parlor Market