
 Apple Butter Market | 2026-2036
Apple Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Butter Market Outlook
FDA nutrition labeling modernization is restructuring compliance costs for small-batch producers entering interstate commerce. The J.M. Smucker Company leverages its national distribution network to sustain shelf-space dominance in conventional retail. Stonewall Kitchen, LLC anchors its premium positioning through specialty store placement and gift-channel segmentation. Conagra Brands, Inc. competes on manufacturing scale across mass-market private-label and branded lines.
Apple butter is a concentrated fruit spread produced by slow-cooking apples with sugar and spices to a thick, spreadable consistency, typically containing 43–49 percent soluble solids by refractometer measurement. Its primary commercial purpose centers on bakery filling applications, breakfast condiment use, and ingredient incorporation in sauces and marinades. Organic and sugar-free product types command widening margin pools as health-conscious households shift procurement away from conventional formulations. Glass jar packaging dominates premium positioning but faces displacement pressure from pouches in foodservice and single-serve channels.
USDA organic certification and FDA food facility registration requirements shape product standards and market access for domestic and imported apple butter entering the United States. State-level cottage food laws in Virginia, Pennsylvania, and Ohio create fragmented pathways for small producers seeking direct retail access. Stakeholders must monitor evolving added-sugar disclosure rules and state-level labeling preemption battles that could reshape formulation economics and channel eligibility.
Market Dynamics
Clean-label reformulation mandates from FDA and USDA are compressing formulation flexibility for apple butter processors, forcing simultaneous sugar reduction and organic certification investments that reshape competitive economics across production tiers.
Growth Catalysts
- Specialty Bakery Procurement:Artisan cafés and premium bakeries are expanding apple butter volumes for differentiated pastry fillings and breakfast applications, creating pull-through demand for small-batch certified organic supply.
- USDA Organic Certification:Federal organic standards enable price premiums in conventional retail channels, rewarding processors who complete the three-year transition and maintain compliant orchard partnerships.
- Reduced-Sugar Formulation:Alternative sweetener technologies and slow-cooking process refinements allow soluble solids compliance at lower added-sugar levels, aligning product labels with evolving disclosure requirements.
Market Restraints
- Input Cost Volatility:Apple concentrate and heritage varietal pricing fluctuates with Pacific Northwest and Appalachian orchard yields, squeezing margin predictability for processors lacking forward contracting.
- Regulatory Fragmentation:Virginia, Pennsylvania, and Ohio cottage food laws create inconsistent interstate commerce barriers for small-batch producers seeking direct retail expansion beyond home-state boundaries.
- Substitution Threat:Fruit preserves, nut butters, and date-based spreads compete for shelf space and consumer attention in breakfast and baking applications, limiting category expansion velocity.
Strategic Opportunities
- Foodservice Pouch Formats:Single-serve flexible packaging is displacing glass jars in institutional bakery and quick-service channels, opening volume contracts with commercial kitchen operators.
- Clean-Label Marinade Applications:Sauce manufacturers are incorporating apple butter as a natural sweetener base for barbecue and glazing formulations, extending usage beyond traditional spread categories.
- State-Level Labeling Preemption Battles:Emerging legislative conflicts over added-sugar disclosure rules create first-mover advantages for processors with compliant formulations already in market.
Industry Challenges
- Refractometer Calibration Expertise:Achieving consistent 43–49 percent soluble solids measurement requires skilled quality control technicians, creating hiring bottlenecks for scaling operations.
- Multi-Certification Timelines:Simultaneous pursuit of FDA facility registration, USDA organic, and state cottage food approvals extends market entry timelines for new entrants.
- Legacy Equipment Retrofit Costs:Slow-cooking kettles and evaporative systems require capital-intensive upgrades to meet modern sanitation and energy efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Butter Market |
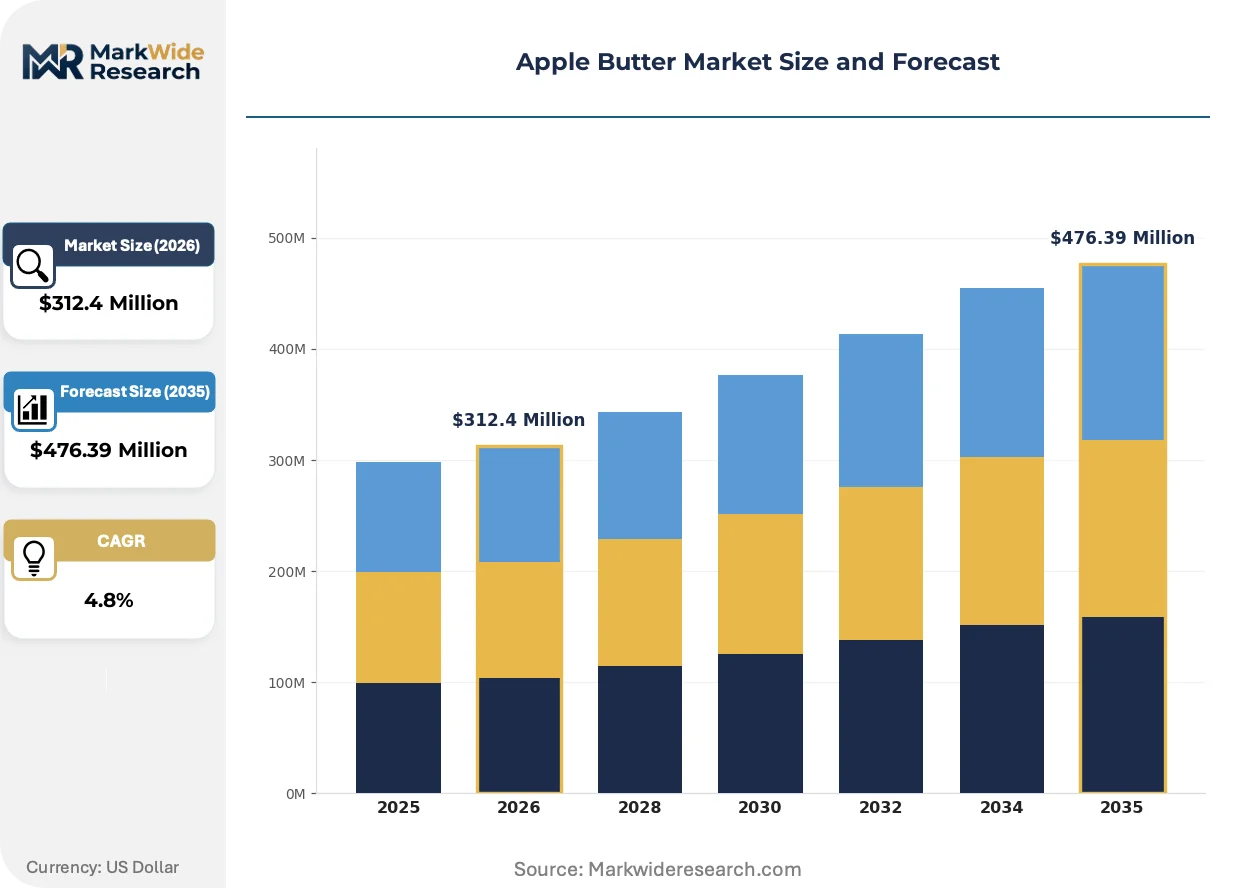
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homemade, Organic, Conventional, Sugar-Free Packaging Type: Glass Jars, Plastic Containers, Tetra Packs, Pouches Sales Channel: Online Retail, Supermarkets, Farmers' Markets, Specialty Stores End User: Households, Restaurants, Cafés, Bakeries |
| Companies Covered | Walmart Inc., Albertsons Companies, Inc., The J.M. Smucker Company, Stonewall Kitchen, LLC, Conagra Brands, Inc., Groupe Andros SA, The Kroger Co., Canyon Spice Fruit Company, Hero AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Butter Market Strategic Shifts
Refractometer-guided process control and alternative sweetener integration are compressing the gap between artisan texture and mass-market scale, reshaping how processors balance heritage methods with regulatory compliance.
Precision evaporative technology is expanding into apple butter production lines, enabling real-time soluble solids monitoring that reduces batch-to-batch variation. Mid-scale processors in Pennsylvania and Ohio are adopting these systems to maintain artisan consistency at higher throughput. The technology is expanding into private-label manufacturing, allowing co-packers to serve multiple brand specifications from shared equipment bases.
FDA nutrition labeling modernization is restructuring compliance investments for interstate commerce entrants, particularly affecting small-batch producers crossing state lines. The updated rules mandate added-sugar line-item disclosure that compresses formulation flexibility for conventional recipes. Appalachian and Pacific Northwest processors are responding with front-of-package reformulation and dual-SKU strategies separating retail and direct-sale channels.
Clean-label ingredient scrutiny is rotating procurement priorities toward orchard-provenance transparency and reduced-sugar claims. Specialty retailers and direct-to-consumer channels are capturing volume from conventional supermarkets as buyers prioritize certification visibility over price. This behavioral shift concentrates most visibly in Virginia and Ohio direct-market clusters where cottage food producers leverage face-to-face origin storytelling.
Apple Butter Market Segmentation
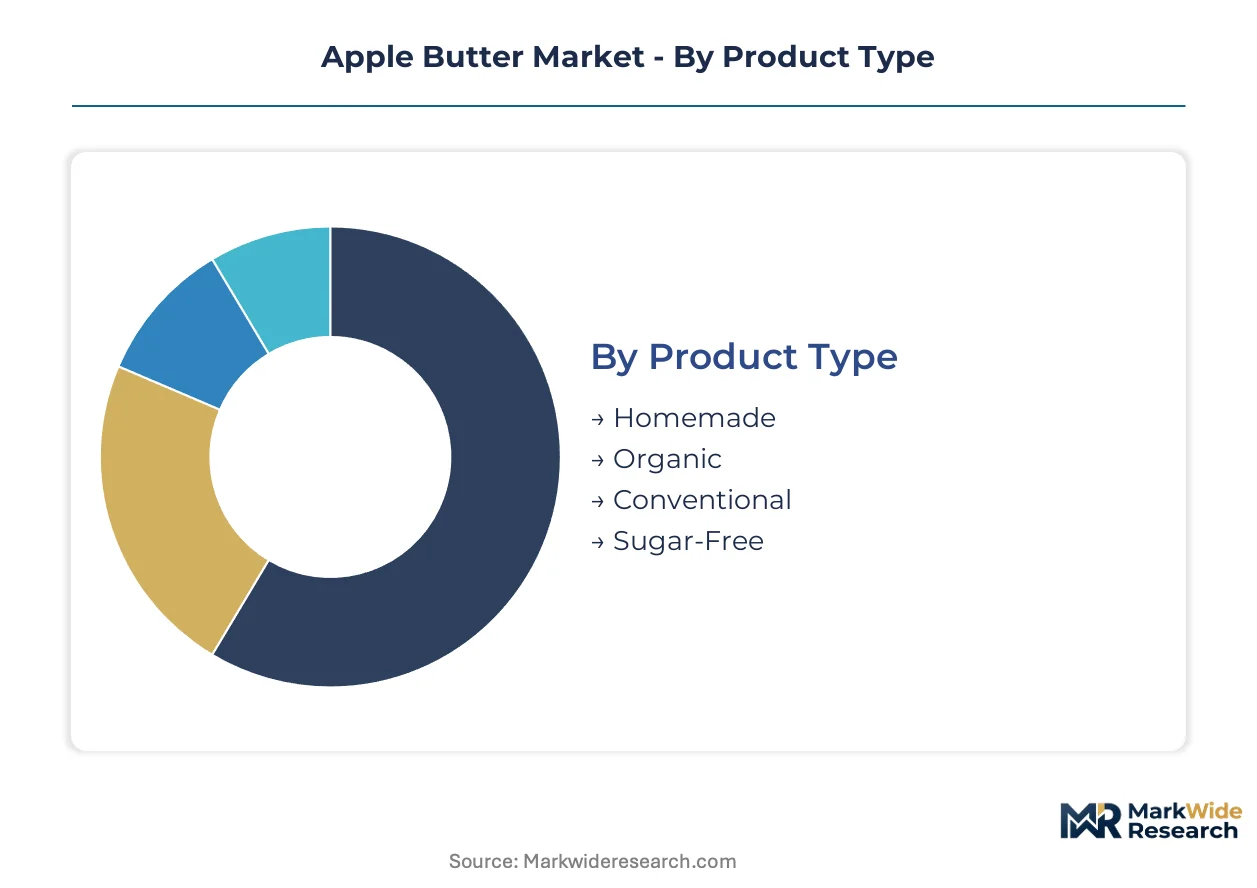
Apple butter processors navigate distinct margin pools and certification requirements across product formulations, with channel placement and end-use specifications driving SKU proliferation. Segmentation clarity enables targeted investment in organic transition, packaging format flexibility, and foodservice contract eligibility.
Product Type:
Reformulation cycles accelerate as FDA added-sugar disclosure rules compress conventional recipe viability, pushing processors toward certified alternatives or reduced-sugar engineering.
- Homemade:Small-batch production under state cottage food laws in Virginia, Pennsylvania, and Ohio leverages heritage recipes and direct-market access. Appalachian orchard partnerships supply heritage varietals that command price premiums at farmers' markets and seasonal festivals.
- Organic:USDA certification requires three-year orchard transition and compliant supply chain documentation, enabling placement in conventional retail at significant margin uplift. Pacific Northwest processors dominate certified volume through established cooperative partnerships.
- Conventional:Mass-market formulations rely on apple concentrate procurement and standardized spice profiles for price-competitive grocery placement. J.M. Smucker Company and Conagra Brands sustain scale advantages through national distribution networks.
- Sugar-Free:Alternative sweetener integration and refractometer-guided process control achieve soluble solids compliance without added sugar. Mid-scale Pennsylvania processors pilot these formulations for health-channel positioning.
Volume placements concentrate in Conventional; the faster expansion belongs to Organic.
Packaging Type:
Channel-specific durability requirements and sustainability positioning drive format selection, with foodservice contracts reshaping procurement toward operational efficiency.
- Glass Jars:Premium positioning dominates specialty retail and gift-channel segmentation, with heritage aesthetics supporting origin storytelling. Appalachian producers leverage transparent packaging to showcase color consistency and artisan texture.
- Plastic Containers:Lightweight durability serves mass-market retail and institutional procurement at lower unit cost. Conagra Brands deploys this format across private-label manufacturing for price-sensitive supermarket placement.
- Tetra Packs:Extended shelf stability enables foodservice bulk procurement and export logistics for processors seeking international market access. Aseptic technology investments concentrate among co-packers serving multiple brand specifications.
- Pouches:Single-serve flexible packaging displaces glass in quick-service bakery and commercial kitchen channels, opening volume contracts with institutional operators. Ohio processors adopt precision filling equipment to serve this expanding segment.
Glass Jars retain the largest installed base; Pouches are climbing the fastest.
Sales Channel:
Consumer procurement fragmentation across digital, conventional retail, and direct-market access requires parallel distribution infrastructure investment.
- Online Retail:Direct-to-consumer platforms enable subscription models and gift-bundle segmentation for processors with USDA organic certification and compelling origin narratives. Virginia cottage food producers leverage e-commerce to circumvent interstate commerce barriers.
- Supermarkets:Shelf-space competition demands slotting fee capacity and national distribution scale, favoring J.M. Smucker Company and Conagra Brands. Clean-label reformulation pressures reshape conventional retail assortment toward reduced-sugar SKUs.
- Farmers' Markets:Face-to-face origin storytelling supports premium pricing for heritage varietal products in Appalachian and Pacific Northwest production clusters. State cottage food laws enable direct retail without FDA facility registration.
- Specialty Stores:Stonewall Kitchen anchors premium positioning through curated placement and gift-channel segmentation. Certification visibility and small-batch provenance drive procurement decisions over price sensitivity.
Supermarkets absorb the highest absolute volume; Online Retail shows the steepest expansion trajectory.
End User:
Application-specific viscosity and flavor intensity requirements differentiate procurement specifications across consumer and commercial segments.
- Households:Breakfast condiment use and home baking applications drive recurring purchase patterns, with health-conscious households shifting procurement toward organic and sugar-free formulations. Clean-label scrutiny concentrates demand in direct-to-consumer and specialty retail channels.
- Restaurants: Sauce manufacturers incorporate apple butter as natural sweetener base for barbecue and glazing formulations, extending usage beyond traditional spread categories. Foodservice pouch formats enable portion control and kitchen efficiency.
- Cafés:Artisan breakfast and pastry applications create pull-through demand for small-batch certified organic supply. Specialty bakery procurement patterns favor heritage texture profiles and orchard-provenance transparency.
- Bakeries:Commercial filling applications require consistent refractometer-measured soluble solids for batch uniformity in pastry production. Pennsylvania and Ohio processors invest in precision evaporative technology to serve institutional contracts.
Households dominate current consumption; Bakeries are gaining share fastest through foodservice contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian Opportunity Zones and Pacific Northwest orchard districts concentrate apple butter production through federal tax incentives and heritage varietal cultivation. FDA facility registration requirements and USDA organic certification standards shape interstate commerce access across state boundaries.
United States
Specialty bakeries in Virginia and Pennsylvania drive procurement of heritage-variety apple butter for artisan pastry applications. FDA nutrition labeling modernization mandates added-sugar disclosure that compresses formulation flexibility for conventional recipes. Appalachian production clusters in West Virginia and eastern Ohio leverage cottage food laws for direct-market access at farmers' markets and seasonal festivals.
Canada
Health Canada food facility regulations govern cross-border import compliance for US processors seeking Ontario and Quebec retail placement. Provincial organic equivalency agreements with USDA enable certified product flow without duplicate certification burdens. British Columbia orchard zones supply heritage apple varieties to specialty condiment producers serving Vancouver and Toronto metropolitan markets.
Germany
EU organic regulation (EU 2018/848) governs certification standards for apple butter imports from third countries. EFSA clean-label scrutiny rotates procurement priorities toward reduced-sugar formulations in Berlin and Munich specialty retail channels. Baden-Württemberg fruit processors concentrate on premium fruit spread manufacturing for domestic and export markets.
France
ANSM food safety oversight and DGCCRF labeling enforcement shape compliance requirements for condiment imports. Île-de-France gastronomy channels absorb premium apple butter volumes for pastry and breakfast applications. Auvergne-Rhône-Alpes agricultural cooperatives supply heritage varietal apples to regional artisan producers.
United Kingdom
FSA novel food guidance and post-Brexit UK organic regulation create dual certification pathways for imported specialty spreads. London specialty retail and direct-to-consumer channels concentrate demand for certified organic condiments. Scottish orchard revival programs in Perthshire and the Borders supply heritage varieties to small-batch producers.
Apple Butter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered pricing strata anchored by certification grade and channel placement. Consolidated shelf-space dominance in conventional retail contrasts with fragmented artisan production under state cottage food frameworks. Three archetypes populate the competitive terrain: mass-market manufacturers with national distribution networks, premium specialty houses with gift-channel segmentation, and small-batch cottage producers with direct-market access. M&A activity concentrates among diversified food conglomerates seeking condiment portfolio expansion, while strategic partnerships link orchard cooperatives to certified organic processors.
Within the diversified conglomerate tier, The J.M. Smucker Company and Conagra Brands, Inc. occupy positions defined by manufacturing scale and private-label service capabilities. Among specialty positioning archetypes, Stonewall Kitchen, LLC exemplifies premium gift-channel segmentation through curated retail placement. These three entities represent distinct competitive vectors: scale-driven mass-market penetration, diversified brand portfolio management, and artisan premium positioning through provenance storytelling.
| Leading Market Players |
|---|
| Walmart Inc. |
| Albertsons Companies, Inc. |
| The J.M. Smucker Company |
| Stonewall Kitchen, LLC |
| Conagra Brands, Inc. |
| Groupe Andros SA |
| The Kroger Co. |
| Canyon Spice Fruit Company |
| Hero AG |
| Others |
Value Chain & Pricing Dynamics
FDA added-sugar disclosure mandates are compressing formulation flexibility for conventional apple butter recipes, forcing processors toward costly organic certification and alternative sweetener investments that reshape competitive economics across production tiers.
Pricing Analysis
Short lead-time premiums reward processors with USDA organic certification and compliant supply chains already in market, while spot inventory discounts concentrate among conventional mass-market producers facing compressed margins. Three-tier pricing structure across premium, standard, and economy levels separates certified organic heritage varietals from conventional formulations and private-label commodity supply. Price differentiation hinges on certification grade and orchard-provenance transparency, with Appalachian and Pacific Northwest origin claims commanding sustained premiums. Cost compression in conventional tiers is intensifying because concentrate input volatility and reformulation compliance burdens squeeze processors lacking forward contracting.
Supply Chain Analysis
Regional distribution centers in Pennsylvania, Ohio, and Virginia anchor hub-and-spoke patterns serving Appalachian production clusters and Pacific Northwest orchard zones. Geographic supply concentrates in the United States, with secondary sourcing from Canadian British Columbia cooperatives and limited European import flow. Raw material dependencies center on heritage apple varietals, organic concentrate supply, and alternative sweetener inputs. Single-source vulnerability runs through Pacific Northwest orchard yield fluctuations. Distribution runs through foodservice pouch channels displacing traditional glass jar logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory compression is accelerating consolidation by squeezing margin economics for small-batch producers lacking certification infrastructure or interstate distribution scale.
For Market Incumbents: Hedge against cottage food law fragmentation by securing multi-state FDA facility registration and USDA organic certification ahead of added-sugar disclosure enforcement. Backward integration into Appalachian orchard partnerships reduces concentrate price exposure. Channel control through foodservice pouch format adoption defends volume position against artisan competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for Virginia and Ohio cottage food producers seeking revenue beyond farmers' market seasonality. Target white-space in sugar-free formulations for health-channel positioning. White-label manufacturing for specialty retailers provides go-to-market traction without slotting fee capacity. For Investors and Strategic Acquirers: The window for entry favors mid-scale processors with existing USDA organic certification and precision evaporative technology installed. Long-term viability rests on consolidation of fragmented Appalachian production capacity. Watch for state-level labeling preemption battles as inflection signal for first-mover regulatory advantage.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks conventional retail placement and price premiums for Appalachian processors. |
| Foodservice Pouch Format Expansion | Captures institutional bakery contracts displacing glass jar logistics. |
| Heritage Orchard Partnership Development | Secures provenance storytelling and supply chain differentiation against concentrate-based competitors. |
| Alternative Sweetener Formulation R&D | Aligns product labels with FDA added-sugar disclosure mandates. |
| Multi-State Distribution Infrastructure | Overcomes cottage food law fragmentation for interstate commerce eligibility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving orchard cooperative managers, FDA compliance officers at processing facilities, specialty retail category buyers, and foodservice procurement directors. USDA organic certification databases, FDA food facility registration records, state cottage food law statutes, and regional customs import data provided validation layers. Bottom-up volume modeling triangulated against top-down value estimates from distributor and retail audit sources.
Granularity-level modeling operated at product type, packaging format, and sales channel dimensions, with additional segmentation by Appalachian versus Pacific Northwest production cluster. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment across the projection horizon. Orchard yield forecasts, alternative sweetener adoption curves, and foodservice contract penetration rates served as industry-specific forecast inputs.
The model holds under stable FDA enforcement timelines and organic certification equivalency agreements; deviation in state-level labeling preemption rulings or Pacific Northwest orchard yield shocks would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Africa Soup Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Potato Soup Market
Processed Foods
Margarine Market
Processed Foods
South America Processed Meat Market
Processed Foods
Instant Curry Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Fresh Pasta Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Processed Superfruits Market
Processed Foods
Dairy Desserts Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Low-Calorie Margarine Market