
 Pizza Market | 2026-2036
Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Market Intelligence
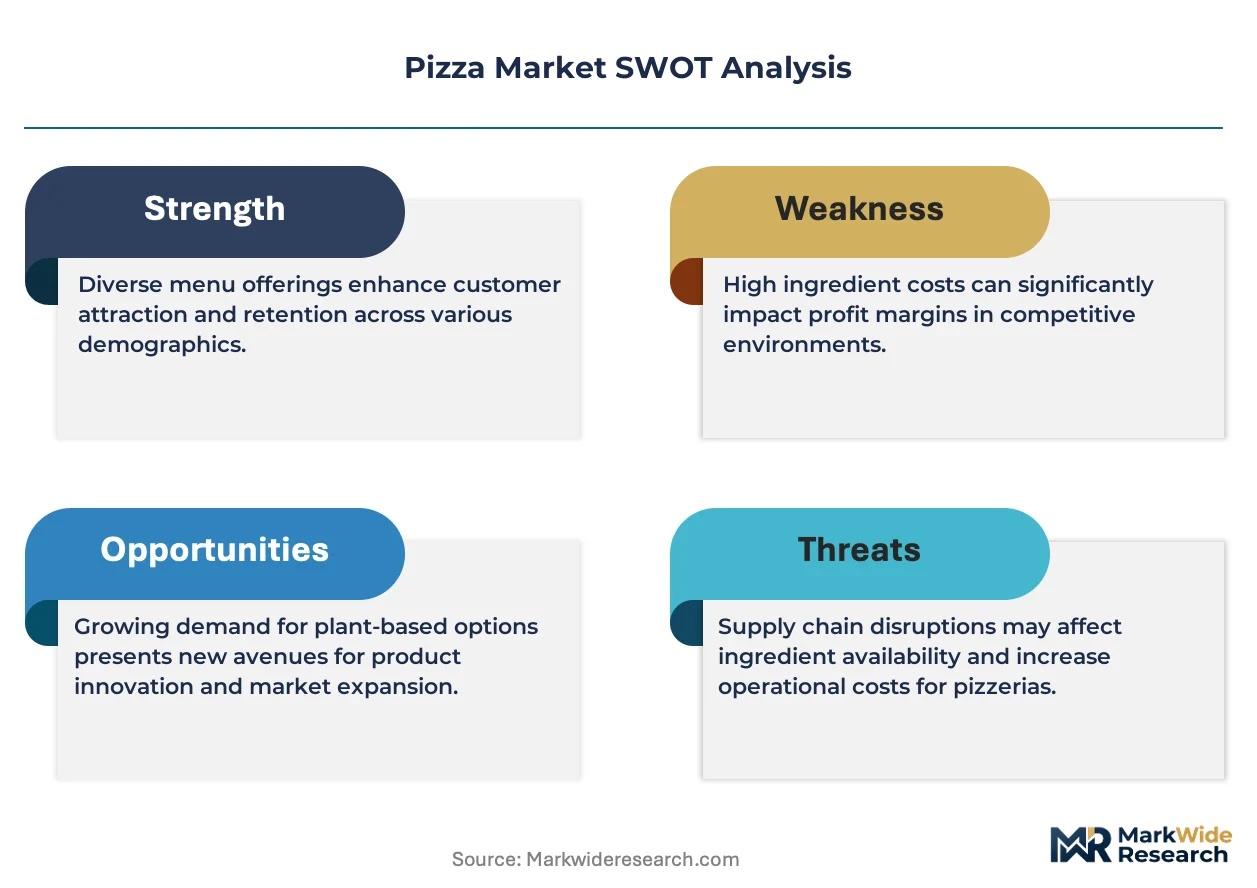
EU Green Deal sustainability targets for food packaging and waste reduction is repositioning how pizza operators source materials and design delivery formats. Domino's Pizza leverages its proprietary delivery logistics network to sustain last-mile efficiency across dense metropolitan zones. Little Caesars anchors value-positioned throughput with automated production systems that compress order-to-pickup intervals. Papa Johns Pizza differentiates through ingredient transparency protocols that respond to health-conscious buyer scrutiny.
Pizza comprises a leavened wheat-based flatbread typically topped with tomato sauce, cheese, and variable proteins or vegetables, then baked at temperatures between 450°F and 800°F depending on crust style and equipment type; its commercial purpose centers on delivering convenient, customizable prepared meals for immediate consumption across retail and foodservice channels. Frozen Pizza commands the largest volume share due to extended shelf stability and pantry-stocking behavior, while Gluten-Free Pizza captures accelerated growth as celiac awareness and wheat-avoidance diets expand the addressable consumer base. Foodservice distribution generates premium margin pools through dine-in experience and delivery markup structures that supermarkets struggle to replicate.
The FDA enforces allergen disclosure and nutritional labeling standards that shape pizza formulation and menu communication, while USDA guidelines on dairy and wheat commodities influence input cost structures and supplier qualification. State-level health departments impose varying grading systems and inspection frequencies that create operational compliance complexity for multi-state operators. Stakeholders must monitor evolving packaging regulations and delivery wage classification rules that threaten unit economics in key metropolitan markets.
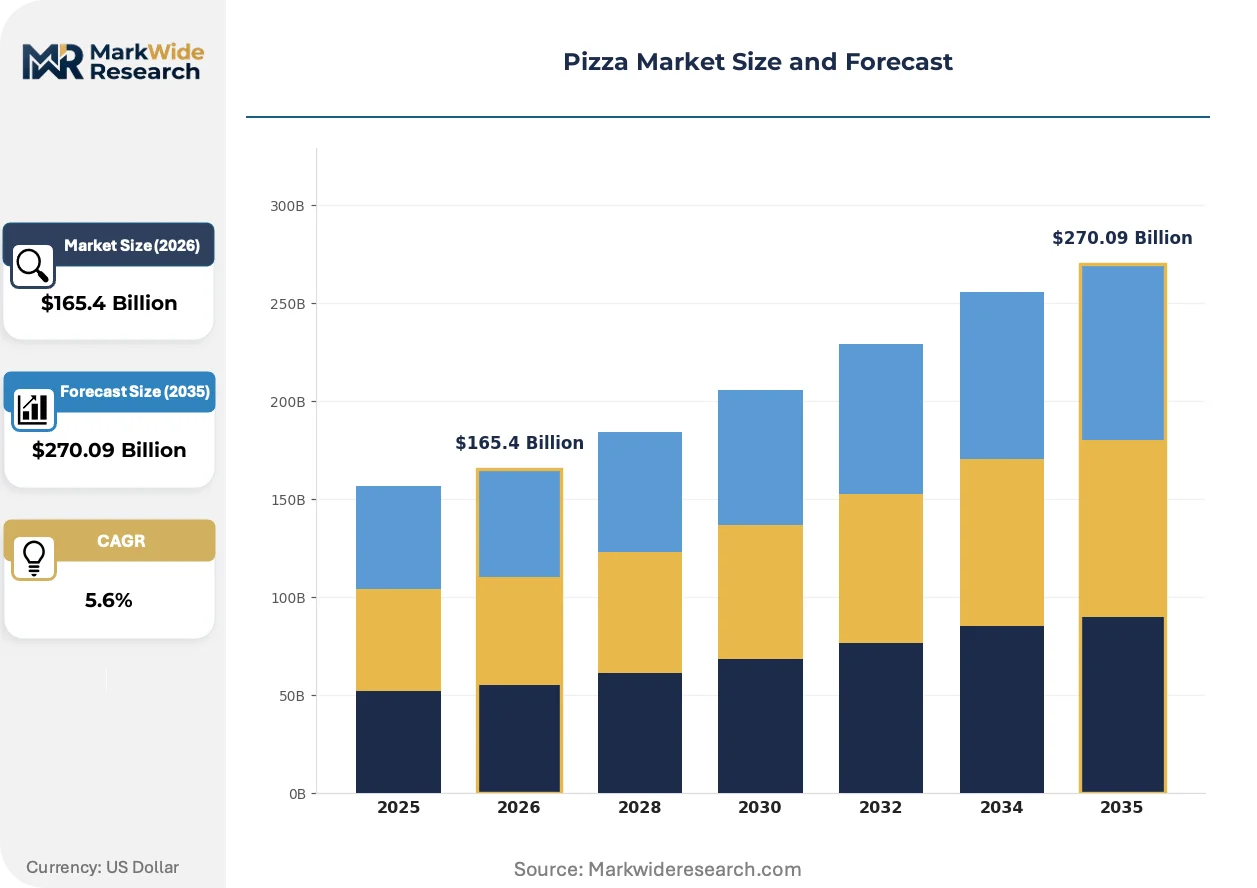
Market Dynamics
Third-party delivery platform economics are compressing operator margins while simultaneously expanding addressable demand, forcing chains to choose between volume scale through aggregator partnerships or margin defense through proprietary logistics infrastructure.
Growth Catalysts
- EU Green Deal packaging mandates:Sustainability targets for food packaging and waste reduction are repositioning how operators source materials and design delivery formats, creating first-mover advantages for compliant suppliers.
- Third-party delivery penetration:Platform density in metropolitan zones enables working professionals to access convenience meals with minimal friction, expanding the addressable consumer base beyond traditional dine-in and carryout channels.
- Celiac awareness expansion:Wheat-avoidance diets and diagnosed celiac conditions are accelerating demand for alternative crust formulations, opening premium pricing tiers previously inaccessible to mass-market operators.
Market Restraints
- Dairy and wheat commodity volatility:USDA price support programs and global grain markets create input cost instability that compresses formulation flexibility for cheese and crust-dependent operators.
- Multi-state compliance fragmentation:State-level health department grading systems and inspection frequency variations impose operational complexity that scales disproportionately with geographic expansion.
- Delivery wage classification uncertainty:Municipal and state-level rules on contractor versus employee status threaten unit economics in key metropolitan markets where labor represents the largest variable cost.
Strategic Opportunities
- Gluten-free formulation white space:Underpenetrated segments among diagnosed celiac consumers and discretionary wheat-avoiders offer premium margin capture for operators with certified production protocols.
- Proprietary logistics networks:Captive delivery infrastructure reduces aggregator dependency and enables data collection on customer behavior that platforms currently monopolize.
- FDA menu labeling transparency:Nutritional disclosure requirements create differentiation openings for operators with cleaner ingredient decks and supply chain traceability systems.
Industry Challenges
- Automated production integration:Capital-intensive kitchen robotics and order management systems require significant upfront investment with payback horizons that strain franchisee balance sheets.
- Allergen cross-contamination protocols:FDA enforcement of allergen disclosure standards demands rigorous kitchen segmentation and staff training that slows throughput during peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Market |
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $270.09 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Pizza, Fresh Pizza, Snack Pizza, Gluten-Free Pizza Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Foodservice Price Tier: Premium, Mid-range, Economical, Discount Customer Type: Families, Young Adults, Children, Health-Conscious Consumers |
| Companies Covered | Papa Johns Pizza, Marco's Pizza, Domino's Pizza, Modpizza, Papa Murphy's, Pizza Hut, Hunt Brothers Pizza, Jets Pizza, Little Caesars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Market Strategic Shifts & Innovations
Automation, regulatory transparency mandates, and shifting consumption occasions are restructuring how pizza moves from production to consumption, with implications for capital deployment and competitive positioning across the value chain.
Automated production systems are consolidating kitchen operations across high-volume operators. Quick-service chains deploy robotic saucing, topping distribution, and oven loading to compress order-to-pickup intervals during peak demand windows. Labor cost pressure and throughput requirements are consolidating competitive advantage around operators with capital depth to deploy these systems at scale.
EU Green Deal sustainability targets for food packaging are reshaping material sourcing decisions across prepared foods. Single-use plastic restrictions and extended producer responsibility frameworks compel operators to redesign delivery containers and source fiber-based alternatives. European markets are responding fastest, with regulatory timelines accelerating supplier qualification processes for compostable and recyclable formats.
Pantry-stocking behavior around frozen pizza is rotating toward premium positioned offerings with cleaner ingredient labels. Supermarket buyers are reallocating shelf space toward products with transparent supply chain claims and reduced preservative content. This shift is most visible in United States retail channels where FDA nutritional labeling enables direct comparison between competing brands.
Pizza Market Segmentation
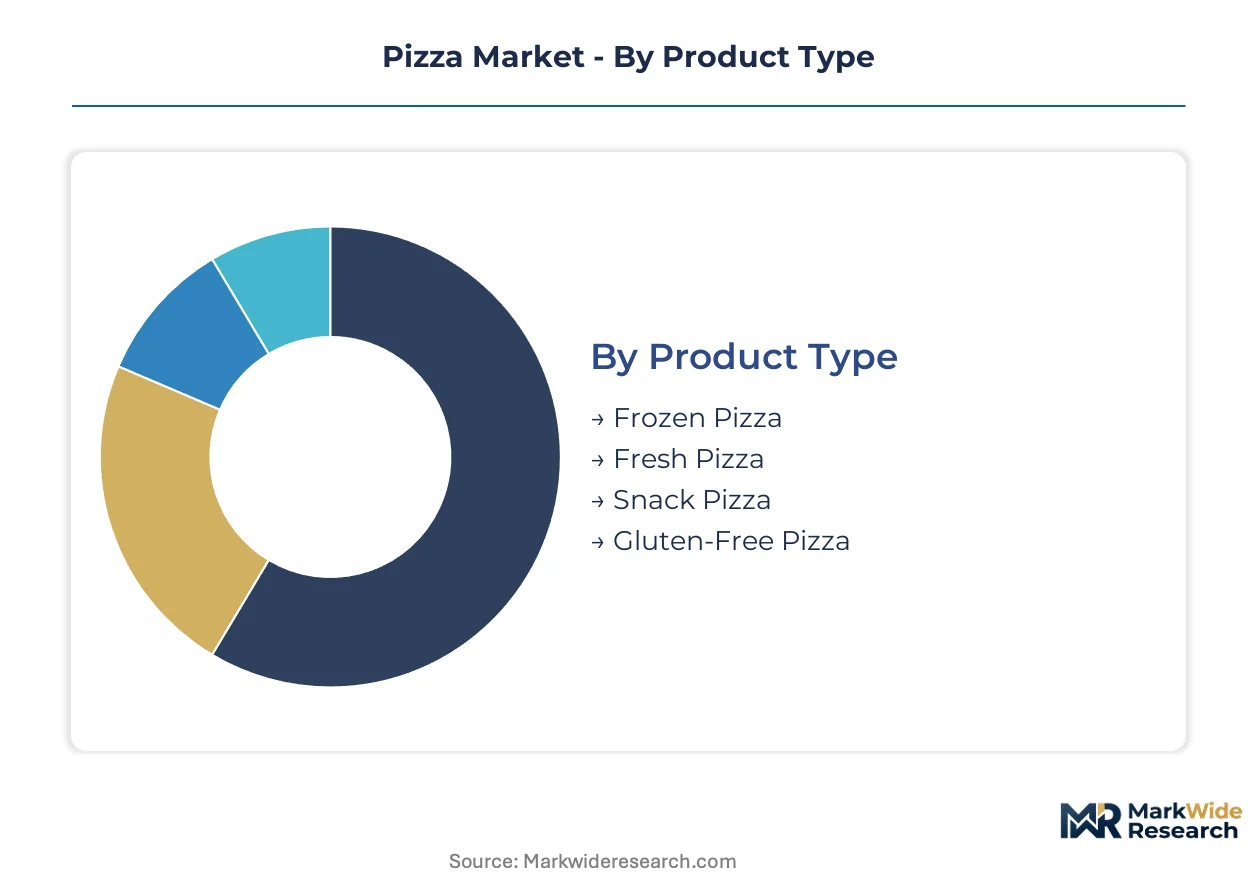
Pizza operators configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles, certification requirements, and channel access rules that shape capital allocation and geographic expansion strategies.
Product Type:
Frozen formulations require FDA nutritional labeling compliance and extended shelf-stability testing, while fresh and gluten-free variants demand additional allergen segregation protocols and third-party certification audits.
- Frozen Pizza:Par-baked or fully baked crusts with flash-freezing preserve texture through retail distribution. Extended shelf stability drives pantry-stocking behavior in United States households, though cold-chain infrastructure requirements limit penetration in emerging markets with unreliable electricity.
- Gluten-Free Pizza:Alternative crusts using rice flour, cauliflower, or almond meal require dedicated production lines to prevent wheat cross-contamination. Celiac awareness campaigns in Germany and Australia have expanded the addressable base beyond diagnosed patients to discretionary wheat-avoiders willing to pay premium prices.
- Fresh Pizza:Refrigerated dough and pre-assembled pies deliver shorter ingredient decks to health-conscious buyers. United Kingdom retailers emphasize shorter ingredient lists as a differentiation lever against frozen competitors.
- Snack Pizza:Miniaturized formats target single-serve consumption occasions and lunchbox packing. Convenience store distribution in Japan favors portion-controlled packaging that aligns with bento culture.
Frozen Pizza sits at the top of the volume ranking, with Gluten-Free Pizza climbing the fastest.
Distribution Channel:
Channel selection dictates margin capture and data ownership, with foodservice enabling premium pricing and direct retail exposing operators to slotting fee pressure and price transparency.
- Foodservice:Full-service restaurants, quick-service chains, and institutional cafeterias generate premium margins through dine-in experience and delivery markup structures. Pizza Hut and Domino's operate captive logistics networks that aggregator platforms cannot replicate.
- Supermarkets:Grocery retail moves the highest unit volumes but compresses margins through promotional pricing and private-label competition. Kroger and Albertsons in the United States demand clean-label reformulations to justify shelf space allocation.
- Online Retail:Direct-to-consumer and third-party marketplace sales enable subscription models and bundle economics. Amazon Fresh and Ocado in the United Kingdom prioritize frozen formats with extended delivery windows.
- Convenience Stores:Impulse-driven purchases favor single-serve and heat-and-eat formats with minimal preparation. 7-Eleven Japan and Circle K in North America rotate limited-time offerings to sustain traffic.
Supermarkets dominate absolute volume, while Online Retail expands most quickly as delivery infrastructure matures.
Price Tier:
Pricing stratification reflects ingredient provenance, production scale, and brand equity, with premium tiers requiring supply chain traceability investments that economy players bypass.
- Premium:Artisanal ingredients, certified organic sourcing, and wood-fired preparation justify price multiples above mass-market alternatives. Whole Foods Market and Eataly in Italy target affluent households seeking restaurant-quality at home.
- Mid-range:Balanced quality and convenience positioning captures weekly family purchasing without trading down to private label. This tier concentrates promotional activity and loyalty program investment.
- Economical:Value-engineered formulations prioritize calorie density and satiety over ingredient transparency. Little Caesars anchors this tier with automated production that compresses unit costs.
- Discount:Deep promotional pricing and temporary price reductions drive trial and pantry loading. Dollar General and Aldi in the United States rotate aggressive temporary price cuts to capture price-sensitive households.
Economical tier commands the largest buyer base, with Premium gaining share fastest as ingredient transparency becomes a purchase trigger.
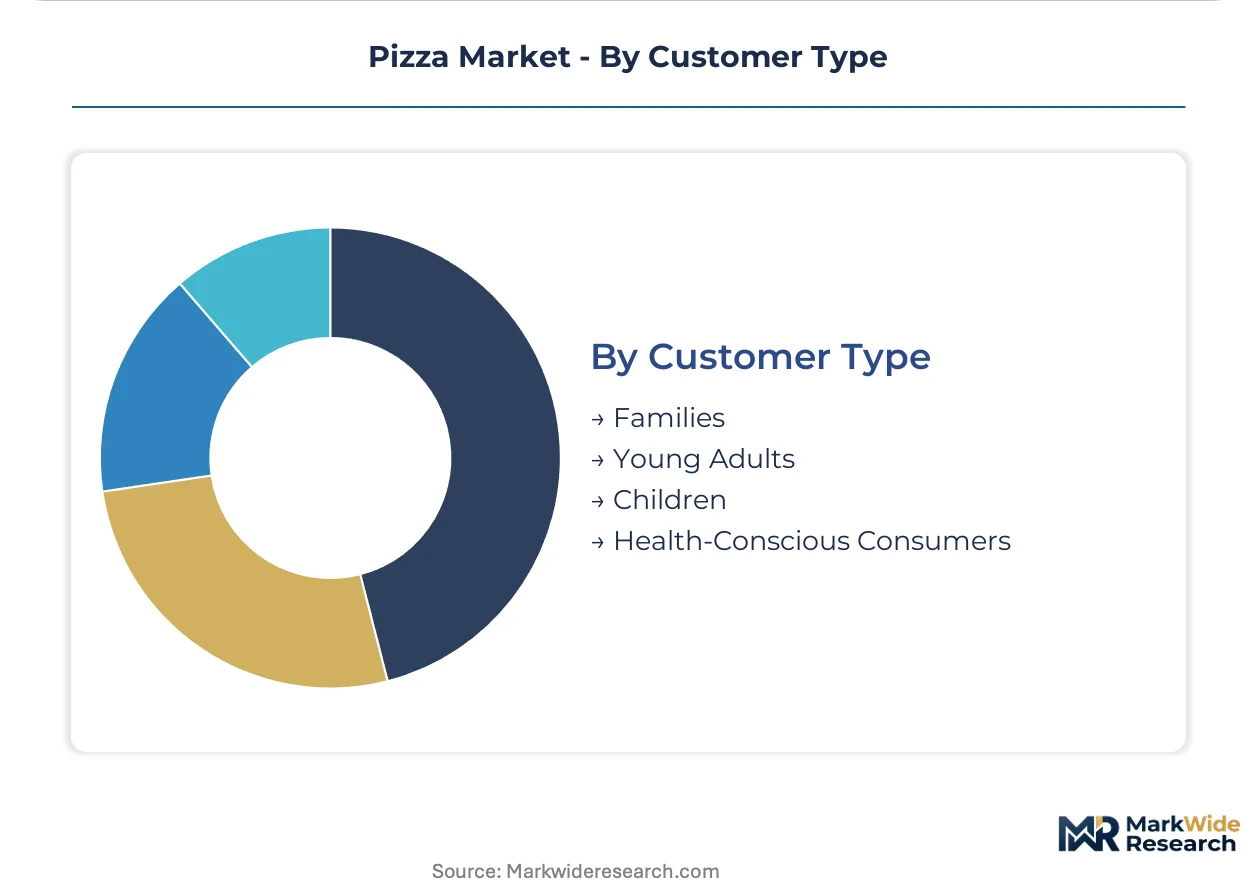
Customer Type:
Demographic targeting shapes product development pipelines, with family-oriented formats emphasizing value and portion sizing while health-conscious segments drive reformulation toward cleaner labels.
- Families:Multi-serve formats, value bundles, and predictable flavor profiles reduce decision fatigue for household purchasers. Costco in the United States moves bulk frozen pizzas through warehouse club economics.
- Young Adults:Digital-native buyers prioritize delivery speed, customization, and social media shareability. This segment concentrates on third-party platform usage in urban United States markets.
- Children:Milder flavor profiles, character licensing, and lunchbox-compatible portions drive parental purchase. School cafeteria contracts in France require reduced sodium formulations.
- Health-Conscious Consumers:Macro-nutrient tracking, organic certification, and allergen-free claims justify price premiums. This buyer pool expands fastest in California and Nordic markets with strong wellness cultures.
Families represent the largest addressable pool, with Health-Conscious Consumers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pizza originated in Naples, Italy, before achieving industrial scale in post-war United States. The market now spans five concentrated demand centers with distinct regulatory and consumption patterns.
United States
Third-party delivery platform penetration in metropolitan zones drives working professional demand for convenience meals. FDA menu labeling requirements reshape formulation transparency across quick-service chains. New York and Chicago anchor foodservice density, while California health-conscious consumers accelerate gluten-free adoption.
Germany
Celiac awareness campaigns expand the addressable base beyond diagnosed patients to discretionary wheat-avoiders. EU Green Deal packaging mandates reposition how operators source materials and design delivery formats. Berlin and Munich concentrate quick-service expansion with automated production systems compressing order intervals.
Italy
Artisanal heritage and wood-fired preparation traditions sustain premium positioning in domestic and export markets. EFSA food contact material regulations influence packaging migration limits for hot-fill delivery containers. Naples and Rome maintain production gravity as origin markets with protected designation status for traditional recipes.
United Kingdom
Refrigerated fresh pizza with shorter ingredient decks captures health-conscious supermarket buyers. Food Standards Agency allergen disclosure enforcement demands rigorous kitchen segmentation protocols. London and Manchester concentrate third-party aggregator density enabling digital-native young adult demand.
Japan
Convenience store distribution favors single-serve formats aligning with bento culture and portion-controlled consumption. METI plastic resource circulation policies accelerate fiber-based packaging transitions. Tokyo and Osaka anchor quick-service automation investments targeting compressed pickup windows.
Pizza Market Key Industry Players
Capital-heavy producers with captive logistics networks compete with asset-light operators dependent on third-party aggregators. The market structure consolidates around three tiers: global chains with proprietary infrastructure, regional specialists with automated throughput, and emerging fast-casual concepts. Dominant competitive moves include proprietary delivery network expansion and kitchen robotics deployment at scale.
Among US-based quick-service operators, Domino's Pizza and Papa Johns Pizza exemplify divergent logistics strategies, with the former sustaining captive last-mile efficiency and the latter differentiating through ingredient transparency protocols. Little Caesars anchors the value-positioned tier with automated production compressing unit costs. These three represent the primary archetypes shaping competitive dynamics: infrastructure-integrated, transparency-differentiated, and automation-driven value.
| Leading Market Players |
|---|
| Papa Johns Pizza |
| Marco's Pizza |
| Domino's Pizza |
| Modpizza |
| Papa Murphy's |
| Pizza Hut |
| Hunt Brothers Pizza |
| Jets Pizza |
| Little Caesars |
| Others |
Cost & Logistics Intelligence
Captive delivery infrastructure anchors both supply positioning and pricing power for quick-service operators, as proprietary logistics networks insulate margin pools from third-party aggregator commissions while enabling data ownership that supports dynamic pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by ingredient provenance and service velocity. Premium tiers capture health-conscious households through certified organic sourcing and wood-fired preparation claims, while economy positioning depends on automated throughput at Little Caesars to compress unit costs. Pricing pressure stems from dairy and wheat commodity volatility under USDA price support programs, squeezing formulation flexibility. Value-seeking families exhibit highest price sensitivity, whereas health-conscious consumers in California and Nordic markets tolerate substantial premiums for transparency credentials.
Supply Chain Analysis
Wheat supply rests on North American and Black Sea grain belts, with cheese production concentrated in Wisconsin, California, and European dairy cooperatives. Tomato paste sourcing draws from California's Central Valley and Italian processing regions. Single-source vulnerability concentrates in specialized mozzarella suppliers serving quick-service chains at scale. Distribution runs through cold-chain foodservice networks for fresh formats and retail grocery channels for frozen inventory, with third-party delivery platforms increasingly intermediating last-mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pantry-stocking behavior rotates toward premium frozen offerings with cleaner ingredient labels and transparent supply chain claims.
For Market Incumbents: Deepen proprietary logistics infrastructure to defend margin pools from DoorDash and Uber Eats commission structures that compress unit economics. Expand automated production systems in high-density metropolitan zones to compress order-to-pickup intervals during peak windows. Prioritize gluten-free certification investments to capture celiac-aware consumers willing to pay premium multiples. For New Entrants and Emerging Players: Enter via certified gluten-free production protocols targeting underpenetrated diagnosed celiac segments in Germany and Australia where awareness campaigns have expanded addressable demand. White-space exists in fresh refrigerated formats with shortened ingredient decks for United Kingdom supermarket buyers. Pursue direct-to-consumer subscription models to bypass slotting fee pressure and build recurring revenue. For Investors and Strategic Acquirers: Roll-up economics work for regional automated throughput specialists because capital-intensive kitchen robotics create barriers that fragment competitive structure and reward scale. Five-to-ten-year viability hinges on capturing delivery infrastructure or premium positioning rather than commodity frozen volume. Monitor FDA menu labeling enforcement intensity as signal for transparency-differentiated operator performance.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Delivery Network Expansion | Captive logistics insulates Domino's from aggregator commissions that compress Papa Johns margins. |
| Automated Production Scale-Up | Robotic saucing and topping distribution compress Little Caesars order intervals during peak demand windows. |
| Gluten-Free Certification Investment | Third-party audits unlock premium pricing tiers from celiac-aware consumers in Germany and Australia. |
| Sustainable Packaging Transition | EU Green Deal compliance creates first-mover advantages for fiber-based container suppliers serving European markets. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Kroger and Albertsons slotting fees while capturing customer behavior data. |
Research Approach
Multiple input streams — executive interviews with quick-service chain operations directors, foodservice distributor procurement leads, and retail grocery category buyers; FDA and USDA regulatory filings; EU Green Deal implementation timelines; and Nielsen retail audit data — were reconciled through bottom-up and top-down triangulation to produce volume and value estimates.
Data-stream reconciliation across product type, distribution channel, price tier, and customer segmentation dimensions enabled CAGR derivation through trend extrapolation and elasticity modeling. Commodity price indices for wheat and dairy, third-party delivery platform penetration metrics, and celiac diagnosis rate trajectories informed projection sensitivity.
Inputs from foodservice operators and retail buyers were available through the study window; gaps in proprietary delivery cost structures and automated production ROI data introduce uncertainty bands around margin forecasts. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and consumer willingness-to-pay for transparency claims. A small set of triggers — EU packaging mandate acceleration, municipal delivery wage reclassification, and gluten-free certification standard harmonization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low Moisture Food Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Soup & Broth Market
Processed Foods
Fruit Processing Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
South America Soup Market
Processed Foods
Fermented Foods Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
United States Ice Cream Market
Processed Foods
Instant Cooking Food Market
Processed Foods
North America Ice Cream Market
Processed Foods
Pates Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Egg White Cubes Market
Processed Foods
Coffee Creamer Market