
 Processed Mango Products Market | 2026-2036
Processed Mango Products Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Mango Products Market Outlook
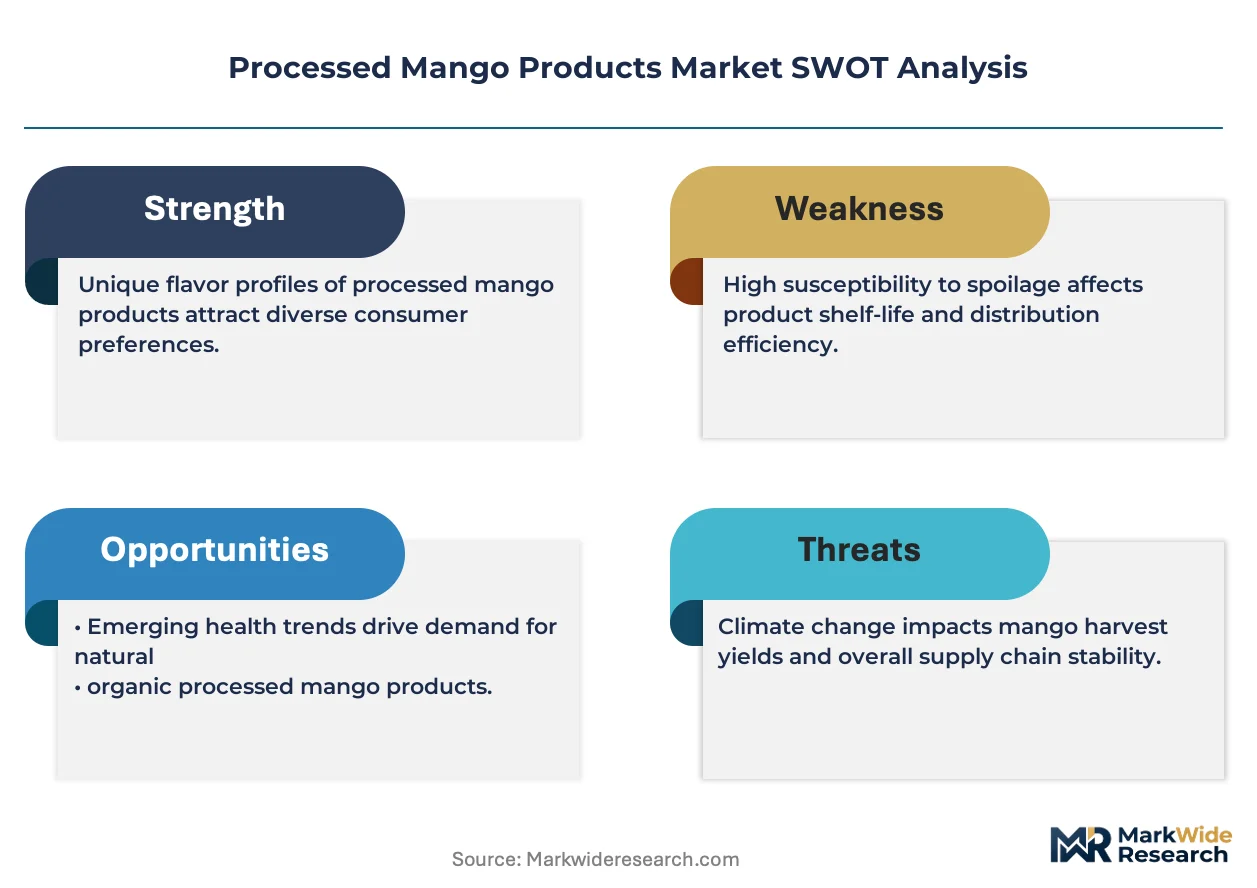
The gap between premium and commodity tiers is broadening as cold-pressed, single-origin mango pulps command shelf space distinct from bulk aseptic concentrates. Fresh Del Monte Produce Inc. leverages its plantation-to-processing infrastructure across Central American origins to sustain quality consistency. Jain Irrigation Systems Ltd. anchors its position through captive mango orchards in Maharashtra and Gujarat, while Olam International Limited competes on procurement networks spanning West African and Southeast Asian supply basins.
Processed mango products encompass pulp, puree, dried slices, and concentrate derived from Mangifera indica fruit through mechanical extraction, dehydration, or thermal concentration, typically standardized to 14–16 Brix for industrial use and 28–32 Brix for beverage formulations. These materials serve as flavor carriers, texturizers, and natural sweeteners across food and drink manufacturing. Mango pulp retains the largest volume footprint due to its versatility in dairy blends and confectionery, though flexible pouch packaging is gaining traction as brands target convenience-oriented retail channels and reduce freight costs against glass alternatives.
FDA enforcement of the Food Safety Modernization Act preventive controls shapes import requirements for mango processors targeting United States distribution, while EFSA pesticide residue thresholds under EU Regulation 396/2005 determine market access for Indian and Pakistani exporters. BIS certification under Indian Standard IS 11683 governs domestic pulp quality benchmarks, with CDSCO oversight extending to nutraceutical-grade mango extracts. Stakeholders must monitor evolving maximum residue limits and packaging sustainability mandates as determinants of competitive viability in regulated import markets.
Market Dynamics
HACCP and ISO 22000 compliance mandates in the European Union are compressing export timelines for tropical fruit processors while simultaneously bifurcating supply tiers between certified premium operators and commodity bulk handlers.
Growth Catalysts
- Functional beverage formulation:Beverage manufacturers are expanding mango puree incorporation into probiotic and vitamin-fortified drink lines, creating steady industrial demand for standardized pulp grades.
- FSSAI enforcement:India's Food Safety and Standards Authority is tightening domestic quality benchmarks, pushing organized processors toward BIS-certified infrastructure that qualifies for export channels.
- Flexible packaging adoption:Pouch-based mango pulp formats are displacing glass jars in retail channels, cutting freight costs by up to sixty percent for Southeast Asian exporters targeting Middle Eastern markets.
Market Restraints
- Input cost volatility:Fresh mango prices fluctuate seasonally across Indian and Thai growing belts, squeezing margin predictability for processors locked into annual supply contracts.
- Geographic supply concentration:Over seventy percent of raw material sourcing clusters in Maharashtra, Gujarat, and Uttar Pradesh, exposing buyers to monsoon disruption and regional pest outbreaks.
- Substitution pressure:Peach and apricot purees from Mediterranean and Central Asian origins compete directly in dairy and confectionery applications where color matching is less critical.
Strategic Opportunities
- West African supply base:Olam International and regional traders are cultivating processing partnerships in Senegal and Côte d'Ivoire, diversifying sourcing beyond South Asian origins.
- Nutraceutical extraction:CDSCO-registered mango kernel and peel extract facilities can access India's expanding Ayurvedic and functional food ingredient channels.
- E-commerce direct distribution:Specialty mango product brands are bypassing traditional import-distributor networks through Amazon and regional grocery platforms in the UAE and Saudi Arabia.
Industry Challenges
- Certification timeline compression:EU Regulation 396/2005 pesticide residue testing requires batch-level documentation that extends lead times by three to four weeks for Indian exporters.
- Cold chain capex requirements:Aseptic processing and controlled-atmosphere storage infrastructure demands capital deployment that mid-tier processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Mango Products Market |
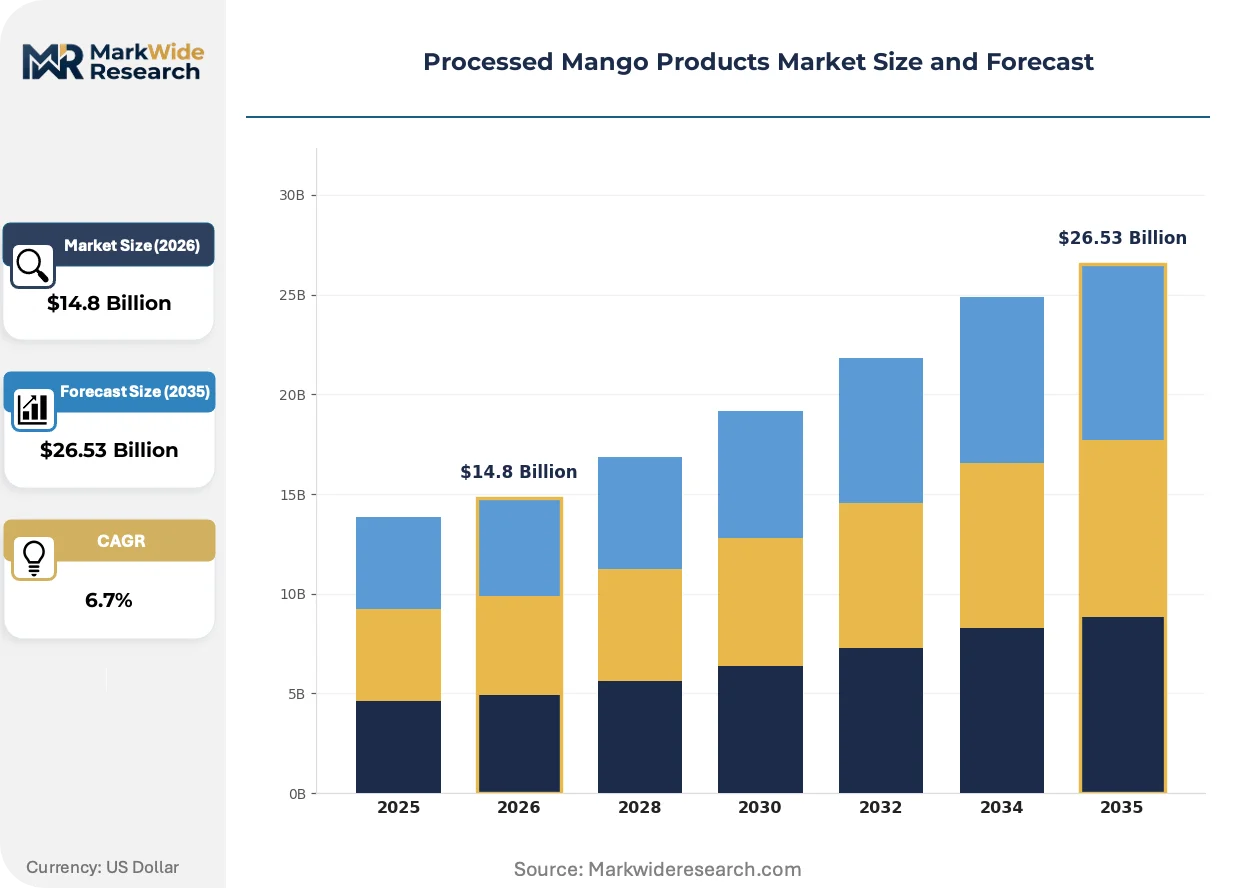
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mango Pulp, Dried Mango, Mango Puree, Mango Slices Packaging Type: Glass Jar, Plastic Container, Flexible Pouch, Sachet Distribution Channel: Supermarket, Online Retail, Specialty Store, Wholesale End Use: Food Industry, Beverage Industry, Retail, Catering Services |
| Companies Covered | Archer-Daniels-Midland Company, Tate & Lyle PLC, Fresh Del Monte Produce Inc., Food & Inns Ltd., Nestlé S.A., Dole Food Company, Inc., Ingredion Incorporated, Jain Irrigation Systems Ltd., Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Mango Products Market Strategic Shifts
Processing technology and packaging formats are converging to reduce thermal degradation while extending shelf stability, reshaping how mango derivatives move through industrial and retail channels.
High-pressure processing technology is integrating into puree production lines across Thai and Mexican facilities, preserving volatile aromatic compounds that conventional pasteurization destroys. Premium juice and smoothie manufacturers in North American and European markets are specifying HPP-treated mango bases for clean-label product positioning. This shift is compressing the price gap between fresh-frozen and shelf-stable mango ingredients.
EFSA's evolving guidance on novel food applications is creating compliance complexity for processors introducing enzymatically clarified mango concentrates into EU markets. The industrial consequence is a two-track approval pathway where traditional thermal concentrates move faster than enzymatically modified alternatives. Infant nutrition and clinical food segments are most affected, with formulators reverting to established concentrate specifications pending regulatory clarity.
Buyers in the foodservice channel are consolidating procurement through specialized tropical ingredient distributors rather than sourcing directly from origin processors. This consolidation is compressing supplier margins while reducing quality variance for end-users operating multi-location chains. The shift is most visible in the United States, where regional restaurant groups and co-manufacturers are outsourcing supplier qualification and logistics to dedicated mango product importers.
Processed Mango Products Market Segmentation
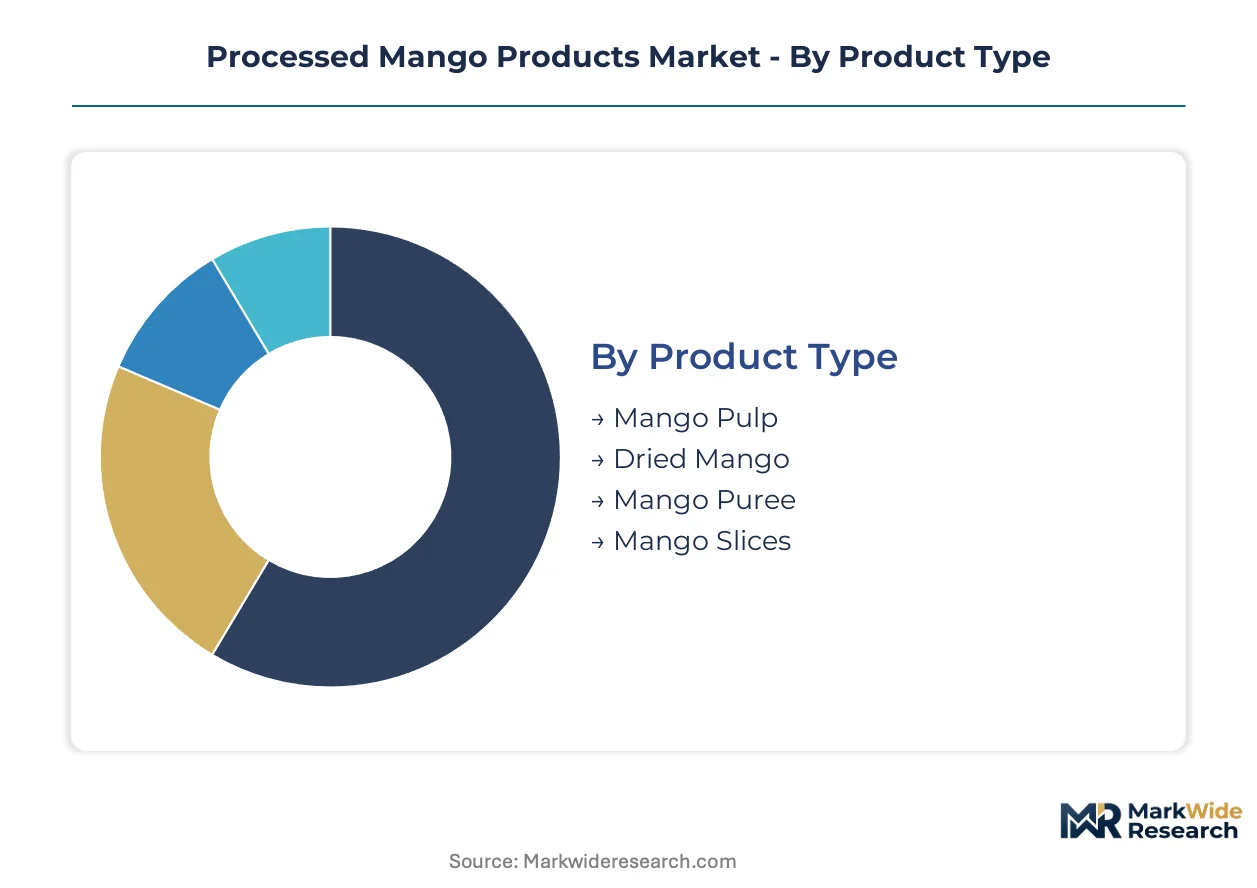
Processed mango derivatives serve divergent functional roles across industrial and consumer channels, with specification standards varying sharply between beverage formulation, confectionery texturization, and direct retail consumption. Segmentation clarity enables procurement teams to match Brix levels, packaging formats, and shelf-stability requirements to specific application economics.
Product Type:
Upgrade cycles in beverage manufacturing are pushing processors toward higher-purity puree grades that displace lower-Brix concentrates in premium formulation lines.
- Mango Pulp:Coarse-filtered extract retaining fibrous matter, typically standardized to 14–16 Brix for industrial dairy and bakery integration. Demand concentrates in Indian and Thai export channels where FSSAI-certified infrastructure qualifies for Middle Eastern foodservice procurement.
- Mango Puree:Finely homogenized product at 28–32 Brix specification, serving as the base for probiotic beverages and vitamin-fortified smoothie formulations. North American clean-label brands are specifying HPP-treated puree grades that command premium positioning against thermal-pasteurized alternatives.
- Dried Mango:Dehydrated slices or chunks with moisture content below 15%, positioned in retail snacking and trail-mix applications.
- Mango Slices:IQF or canned segments targeting foodservice dessert and garnish applications.
Mango pulp sits at the top of the volume ranking, with mango puree climbing the fastest as functional beverage formulation expands.
Packaging Type:
Cost tier differentiation separates premium aseptic formats from commodity bulk handling, with freight economics driving rapid format substitution in export-intensive supply chains.
- Glass Jar:Traditional retail format preserving visual product integrity, dominant in European and Middle Eastern premium channels where shelf presentation influences purchase decisions.
- Flexible Pouch:Multi-layer polymer construction reducing freight weight by up to sixty percent against glass equivalents. Southeast Asian exporters targeting UAE and Saudi Arabian markets are accelerating pouch adoption through e-commerce direct distribution channels.
- Plastic Container:HDPE or PET formats for foodservice bulk procurement.
- Sachet:Single-serve portions for hospitality and airline catering segments.
Glass jar retains the largest installed base among premium-positioned SKUs, with flexible pouch gaining share fastest as freight cost pressure intensifies.
Distribution Channel:
Customer-type stratification is bifurcating procurement between consolidated multi-location foodservice operators and fragmented specialty retail accounts with divergent logistics requirements.
- Supermarket:Mass retail channel commanding standardized packaging and extended shelf-life specifications. Indian organized retail expansion under FSSAI enforcement is elevating BIS-certified processor participation in domestic supermarket supply.
- Online Retail:Direct-to-consumer channel enabling specialty brands to bypass import-distributor networks. Amazon and regional grocery platforms in the UAE and Saudi Arabia are absorbing increasing mango product volumes from origin processors.
- Specialty Store:Ethnic grocery and organic retail targeting diaspora consumers.
- Wholesale:Industrial procurement channel for dairy, bakery, and beverage manufacturers.
Supermarket channels anchor current volume distribution, with online retail expanding most quickly as platform logistics mature for temperature-sensitive goods.
End Use:
Application-specific formulation requirements are concentrating demand in beverage manufacturing, where Brix standardization and aromatic preservation command technical priority over cost minimization.
- Beverage Industry:Primary demand driver for high-Brix puree and clarified concentrate grades. Mexican and Thai processing facilities are integrating HPP technology to supply North American premium juice manufacturers with clean-label positioning.
- Food Industry:Dairy, confectionery, and bakery applications utilizing lower-Brix pulp for texturization and natural sweetening. Substitution pressure from peach and apricot purees in color-tolerant applications constrains mango volume growth in this segment.
- Retail:Branded consumer products through private-label and proprietary positioning.
- Catering Services:Foodservice dessert and beverage preparation in hospitality and institutional settings.
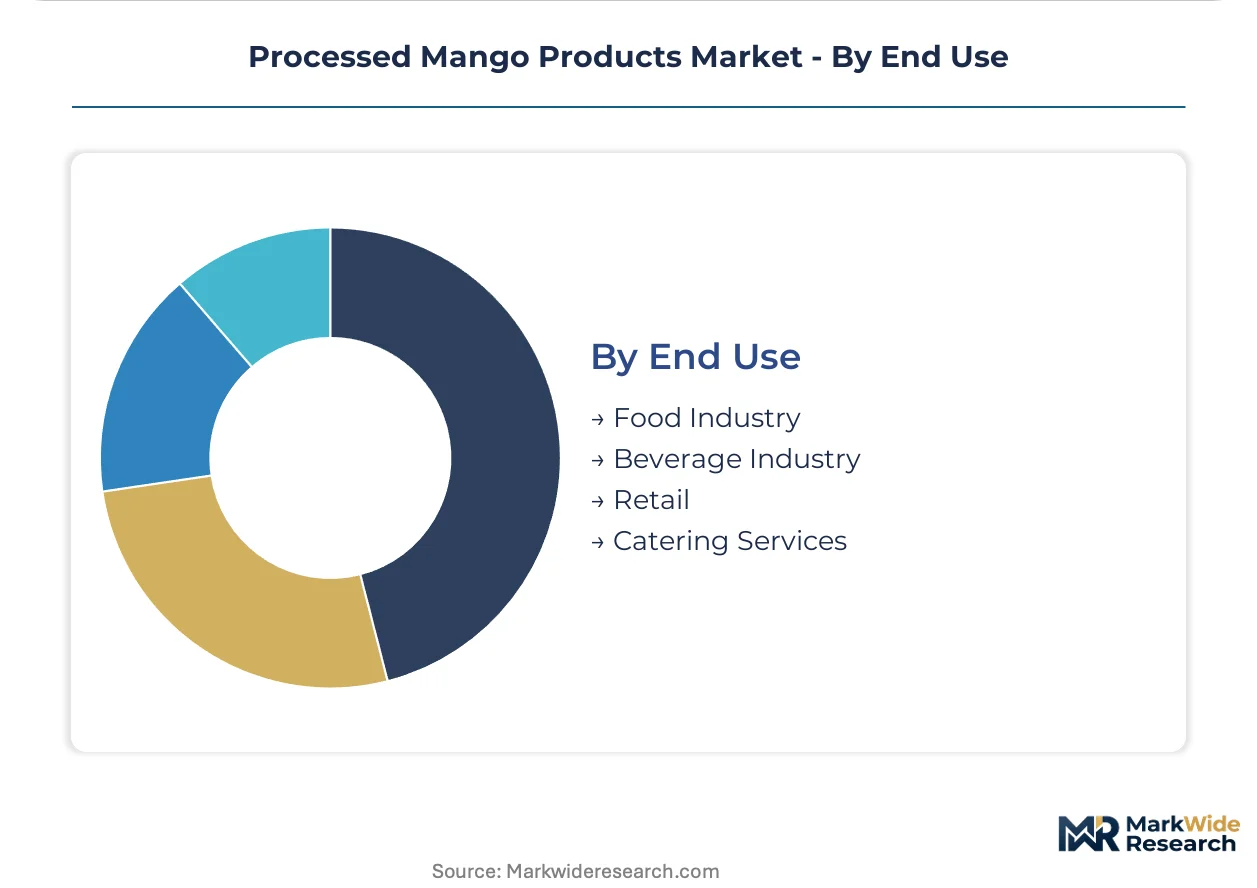
Beverage industry consumption leads by value contribution, with food industry volume holding steady amid competitive puree substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes substantially more raw mango volume than Mexico, yet Mexican exporters command higher unit values through proximity to North American beverage manufacturers.
India
FSSAI enforcement drives consolidation among Maharashtra and Gujarat processors seeking export qualification. BIS certification under IS 11683 governs domestic pulp quality benchmarks, while CDSCO oversight extends to nutraceutical-grade extracts. The Ratnagiri-Alphonso belt anchors premium puree production for Middle Eastern markets.
Mexico
Beverage manufacturers in the United States source HPP-treated puree from Chiapas and Oaxaca facilities. FDA preventive controls under FSMA shape import documentation requirements. The Soconusco region concentrates aseptic processing infrastructure serving clean-label juice brands.
Thailand
Southeast Asian exporters leverage flexible pouch formats to cut freight costs for UAE and Saudi Arabian procurement. National food safety frameworks align with ISO 22000 for EU market access. The Chanthaburi province hosts dehydration and puree facilities targeting Asian foodservice channels.
United States
Specialty distributors consolidate procurement for multi-location restaurant chains and co-manufacturers. FDA enforcement of FSMA preventive controls extends compliance burdens to imported pulp shipments. Florida's limited processing capacity relies on Central American supply partnerships.
United Arab Emirates
E-commerce platforms absorb direct distribution from Indian and Thai origin processors, bypassing traditional import networks. MOHAP food safety standards govern re-export labeling for regional markets. Dubai's Jebel Ali free zone concentrates cold storage and repackaging operations.
Processed Mango Products Market Competitive Environment
Top-tier vendors anchor plantation-to-processing infrastructure, while mid-scale operators compete on procurement network breadth. The vendor base spans integrated agricultural conglomerates, irrigation-anchored processors, and global commodity traders. Three archetypes dominate: captive orchard operators, diversified tropical fruit processors, and supply chain specialists. Competitive moves concentrate on backward integration into orchard ownership and aseptic capacity expansion.
Within the captive orchard tier, Jain Irrigation Systems Ltd. and Fresh Del Monte Produce Inc. exemplify vertical control over raw material supply. Olam International Limited occupies a position among procurement-network specialists spanning West African and Southeast Asian origins. These three entities represent distinct strategic approaches to managing mango price volatility and quality consistency.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Tate & Lyle PLC |
| Fresh Del Monte Produce Inc. |
| Food & Inns Ltd. |
| Nestlé S.A. |
| Dole Food Company, Inc. |
| Ingredion Incorporated |
| Jain Irrigation Systems Ltd. |
| Olam International Limited |
| Others |
Value Chain & Pricing Dynamics
Alphonso mango spot prices in the Ratnagiri belt cascade through three distinct pricing tiers as raw material volatility compresses margins for processors locked into annual supply contracts with beverage manufacturers.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for aseptic pulp grades as organized processors expand FSSAI-certified infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated puree for North American clean-label brands from thermal-pasteurized concentrates for commodity dairy applications. Cost compression in standard-grade concentrates is intensifying because Thai exporters are absorbing freight savings from flexible pouch adoption. Foodservice distributors operating multi-location chains exhibit the highest price sensitivity, while infant nutrition formulators prioritize aromatic preservation over unit cost.
Supply Chain Analysis
Refurbishment flows for aseptic processing equipment create secondary market capacity that mid-tier Indian processors leverage to extend equipment life cycles. Raw material sourcing draws from Maharashtra, Gujarat, and Uttar Pradesh clusters, with mango kernel and peel extract feedstock resting on Chanthaburi dehydration facilities. Single-source vulnerability concentrates in the Alphonso belt where monsoon disruption threatens premium puree supply. Distribution runs through specialized tropical ingredient distributors in the United States and e-commerce platforms in the UAE and Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Processed Mango Products Market functions as a stable compounder where functional beverage formulation drives steady industrial demand for standardized puree grades.
For Market Incumbents: Anchor quality consistency through captive orchard ownership in Maharashtra and Gujarat while expanding HPP capacity to serve North American clean-label brands. Certification investment in ISO 22000 and FSSAI compliance defends against emerging West African processors cultivating Senegalese and Ivorian supply partnerships. Backward integration into controlled-atmosphere storage infrastructure addresses margin pressure from seasonal input cost volatility.
For New Entrants and Emerging Players: Begin with nutraceutical-grade mango kernel and peel extract production targeting CDSCO-registered Ayurvedic channels where regulatory barriers filter out commodity competitors. West African supply partnerships in Senegal and Côte d'Ivoire offer the most penetrable geography given established trader cultivation networks. Direct-to-consumer positioning through Amazon and regional grocery platforms in the UAE bypasses consolidated import-distributor gatekeepers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors possessing FSSAI-certified infrastructure and established Middle Eastern foodservice relationships. Long-term viability hinges on aseptic capacity expansion and cold chain capex deployment over a multi-year horizon. Watch EU Regulation 396/2005 maximum residue limit revisions as the inflection indicator for Indian export qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Orchards | Jain Irrigation Systems and Fresh Del Monte secure Alphonso supply consistency through plantation ownership. |
| HPP Technology Deployment | Thai and Mexican facilities preserve volatile aromatics that conventional pasteurization destroys for premium juice brands. |
| Flexible Pouch Format Adoption | Southeast Asian exporters cut freight weight by sixty percent against glass jars for UAE and Saudi Arabian e-commerce channels. |
| West African Supply Base Cultivation | Olam International diversifies procurement beyond South Asian origins through Senegalese and Ivorian processing partnerships. |
| Nutraceutical Extraction Facility Registration | CDSCO-registered mango kernel and peel extract producers access India's expanding Ayurvedic ingredient channels. |
Study Parameters
Multiple input streams — processor procurement directors, beverage formulation technologists, tropical fruit import-distributors, and FSSAI regulatory affairs leads — were reconciled against customs trade records, BIS certification databases, and EFSA pesticide residue guidance documents. Bottom-up volume estimates from individual processing facility capacities were triangulated with top-down demand assessments from dairy, confectionery, and beverage manufacturing consumption patterns.
Historical volume trajectories were cross-referenced against panel input from procurement executives at North American clean-label juice brands and Middle Eastern foodservice distributors. Segmentation dimensions modeled include product type, Brix specification tier, packaging format, distribution channel, and end-use application. CAGRs were derived through regression analysis of processed mango derivative pricing against fresh fruit input cost indices and freight rate fluctuations across the analysis window.
Several conditions sit outside the modeled scope, including unforeseen EU maximum residue limit revisions, catastrophic monsoon disruption in the Ratnagiri belt, and abrupt shifts in peach and apricot puree substitution economics. Practitioners should monitor EFSA novel food application guidance, West African supply base maturation, and flexible pouch logistics platform development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Broth Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Butter Crisco Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Industrial Margarine Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Porridge Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
South America Processed Meat Market
Processed Foods
Tomato Puree Market
Processed Foods
Yogurt Dip Market