
 Ice Cream Parlor Market | 2026-2036
Ice Cream Parlor Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Parlor Market Analytics
Artisanal batch-freezing technology is reconfiguring production workflows in premium parlors, enabling on-site flavor customization with shorter churn cycles. Baskin-Robbins leverages its global franchise network to sustain market presence across diverse demographics. Cold Stone Creamery anchors its competitive stance through theatrical mixing surfaces that differentiate the in-store experience. Häagen-Dazs specializes in super-premium positioning with dense butterfat formulations that command price premiums in key urban corridors.
An ice cream parlor constitutes a specialized foodservice establishment where frozen dairy desserts are manufactured on-premises or finished from base mixes for immediate consumption, typically requiring blast freezers operating at minus twenty degrees Celsius or below to achieve optimal texture stability. The primary commercial purpose centers on delivering experiential, customizable dessert occasions that transcend retail packaged goods through sensory engagement and social ambiance. Soft serve systems dominate volume throughput in high-traffic locations due to lower labor intensity and faster service cadence, while gelato segments capture disproportionate margin pools in metropolitan markets where consumers prioritize density and authenticity. Hard ice cream maintains structural importance as the foundational format for mix-in innovation and seasonal limited offerings that drive repeat visitation.
FDA pasteurized milk ordinance standards and state-level dairy plant licensing requirements shape product safety protocols and equipment specifications across the United States, with county health departments conducting unannounced inspections that directly affect operating permits. The Food Safety Modernization Act traceability mandates impose documentation burdens on parlors sourcing from multiple dairy suppliers, particularly affecting smaller independent operators with limited administrative capacity. Stakeholders must monitor evolving clean-label expectations and alternative protein regulatory classifications as oat, coconut, and cashew bases challenge traditional dairy-centric compliance frameworks and consumer positioning strategies.
Market Dynamics
Artisanal batch-freezing systems are compressing production cycles from hours to minutes, enabling premium parlors to offer same-day flavor rotations that differentiate against packaged retail alternatives.
Growth Catalysts
- Experiential dining culture:Coastal metropolitan areas in the United States concentrate affluent millennials seeking Instagram-worthy dessert occasions with customizable mix-ins and theatrical preparation.
- FDA dairy safety modernization:Enhanced traceability mandates under the Food Safety Modernization Act favor operators with integrated supply chain documentation, indirectly consolidating market position among compliant chains.
- Alternative protein base innovation:Oat, coconut, and cashew formulations expand addressable markets beyond lactose-intolerant consumers into flexitarian and vegan segments.
Market Restraints
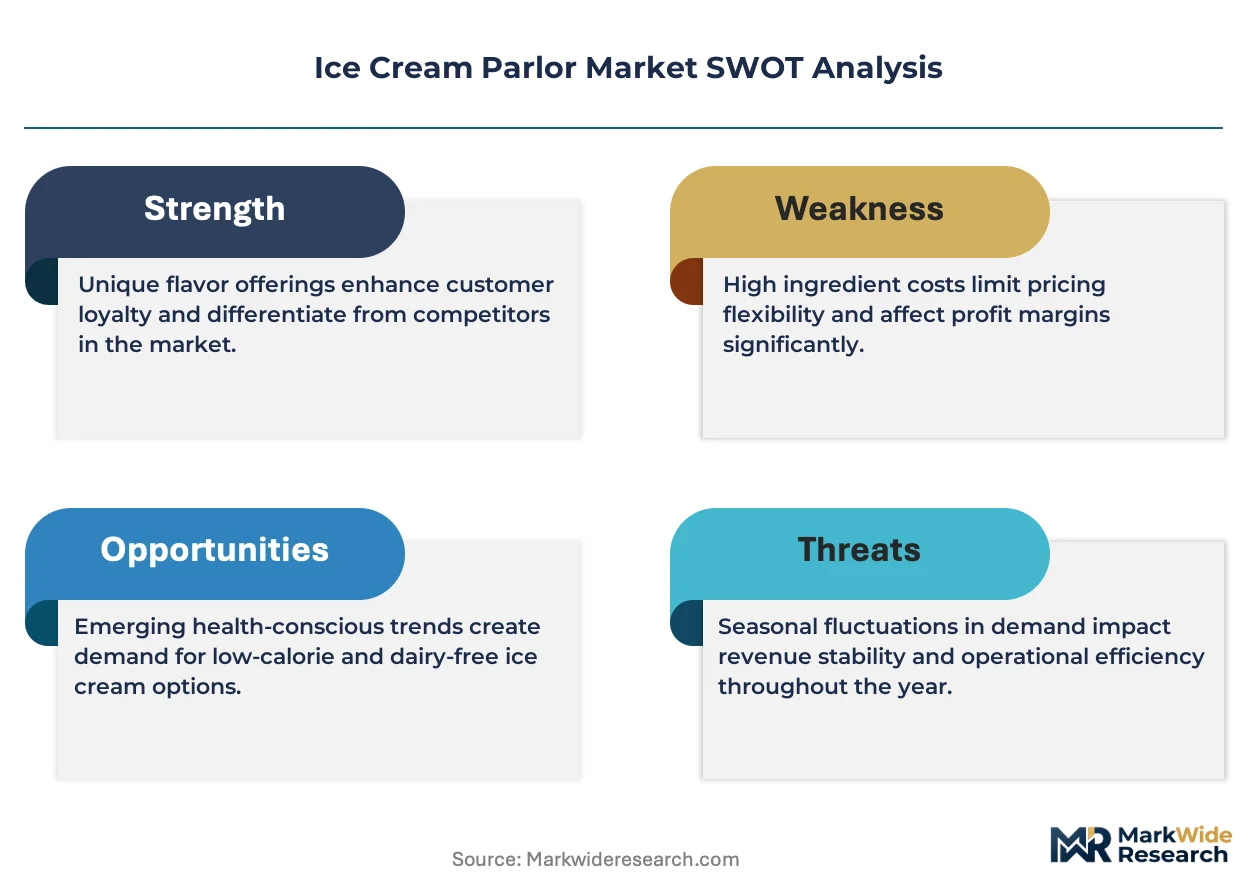
- Butterfat commodity volatility:Super-premium positioning depends on dense butterfat formulations that expose margins to dairy commodity price swings and seasonal supply tightness.
- Local health department inspection density:Unannounced county inspections create operational friction and permit suspension risks that disproportionately burden independent operators with limited compliance staff.
- Blast freezer energy intensity:Equipment operating at minus twenty degrees Celsius or below drives electricity costs that constrain site selection to markets with favorable utility rate structures.
Strategic Opportunities
- Soft serve automation:Reduced labor intensity and faster service cadence enable high-traffic location models in transportation hubs and entertainment venues previously uneconomical for full-service formats.
- State-level dairy plant licensing arbitrage:Jurisdictions with streamlined permitting pathways offer first-mover advantages for multi-unit expansion before regulatory harmonization tightens.
- Gelato authenticity positioning:Metropolitan markets with established European culinary cultures present underexploited demand for density-focused, lower-air-content formulations commanding price premiums.
Industry Challenges
- Artisanal churn technician scarcity:On-site flavor customization requires skilled operators capable of managing shorter churn cycles and texture stability across variable ambient conditions.
- Multi-supplier traceability integration:Parlors sourcing base mixes from multiple dairy suppliers face documentation burdens that strain administrative capacity, particularly during unannounced FDA audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Parlor Market |
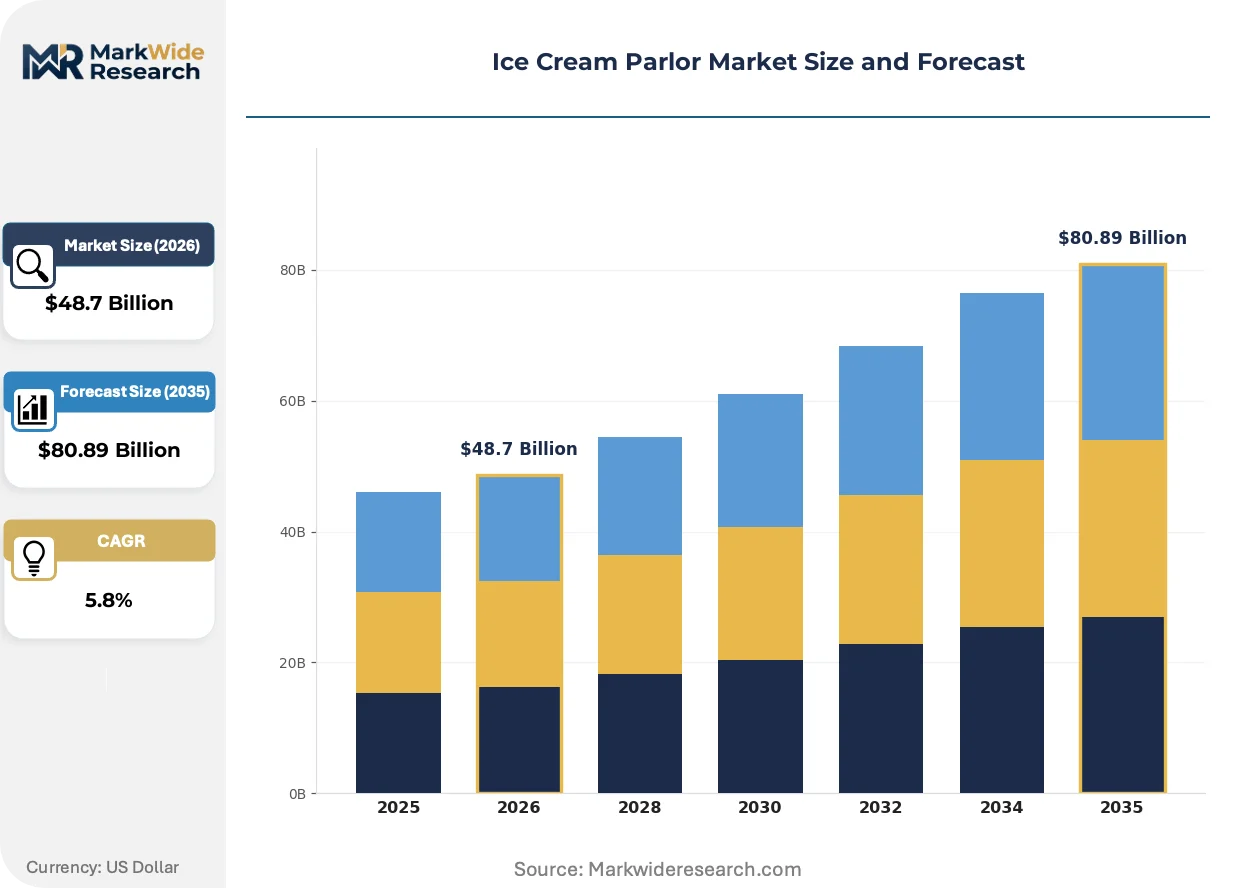
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Serve, Hard Ice Cream, Gelato, Sorbet Flavor Profile: Chocolate, Vanilla, Strawberry, Mint Chocolate Chip Serving Style: Cup, Cone, Sundae, Milkshake Customer Type: Families, Students, Tourists, Couples |
| Companies Covered | Baskin-Robbins, Cold Stone Creamery, Häagen-Dazs, Dairy Queen, Ben & Jerry's, Braum’s Ice Cream & Dairy Stores, La Michoacana, Red Mango, Amorino, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Parlor Market Evolving Landscape
Production workflows are fragmenting between high-throughput automation and hyper-local craft systems, creating divergent capital intensity models that reshape competitive positioning across price tiers.
Liquid nitrogen flash-freezing is migrating from molecular gastronomy installations into mainstream premium parlor equipment portfolios. Boutique operators in Brooklyn and San Francisco deploy these systems to achieve instant texture fixation with visible vapor effects that drive social media amplification. The technology is migrating from theatrical novelty into standard equipment specifications as lease financing models reduce upfront capital barriers.
The Food Safety Modernization Act traceability mandates are compressing supplier networks toward vertically integrated dairy processors with pre-certified documentation systems. Small-batch independent operators face disproportionate compliance burdens that favor franchise systems with centralized quality assurance infrastructure. Cold chain documentation requirements are accelerating consolidation among operators capable of investing in integrated ERP-to-supplier data linkages.
Consumer preference is rotating toward limited seasonal offerings that compress product development cycles and demand agile supply chain reconfiguration. Hard ice cream formats enable rapid mix-in innovation that drives repeat visitation patterns in metropolitan markets with high competitive density. This rotation is most visible in Los Angeles and Miami, where operators rotate menus monthly to sustain engagement among experience-seeking demographics with low brand loyalty.
Ice Cream Parlor Market Segmentation
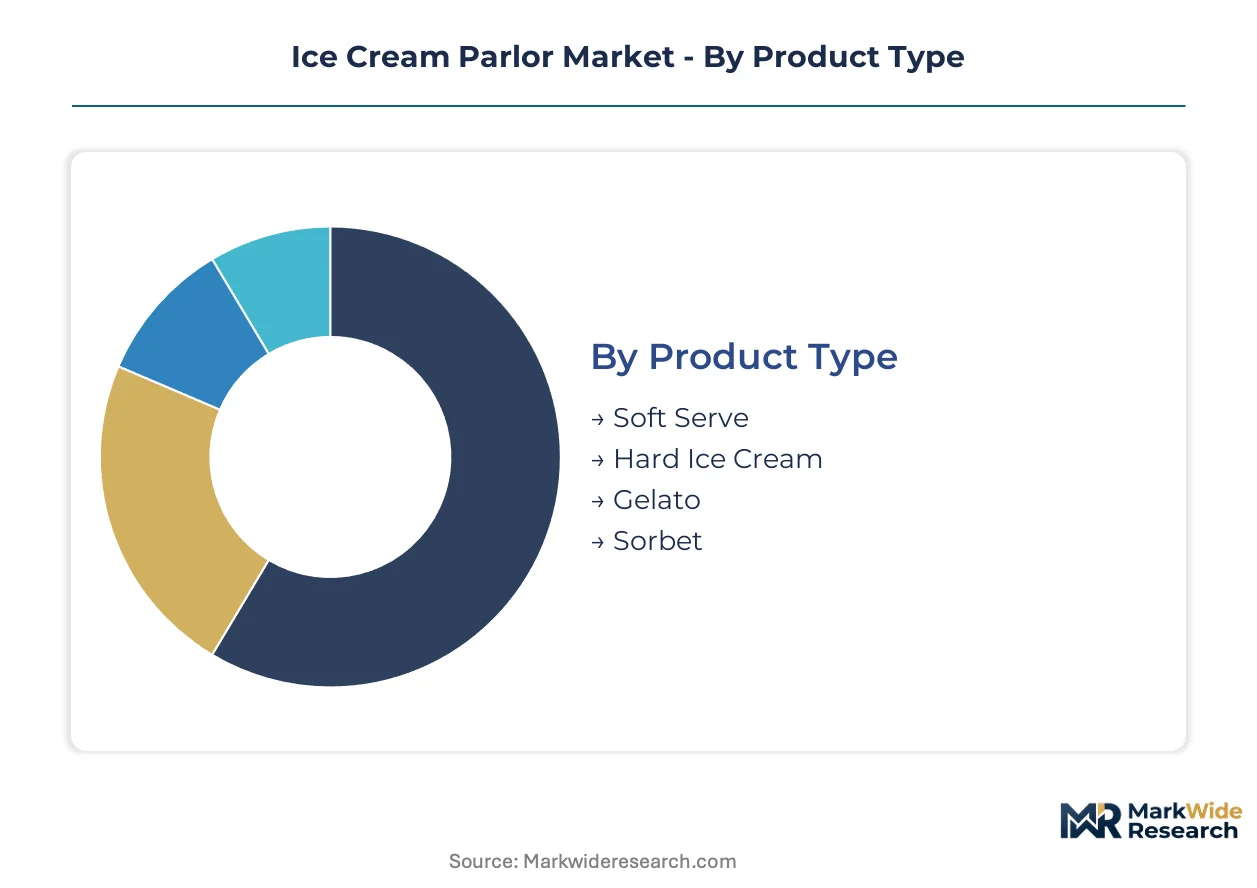
Segmentation in the ice cream parlor market reveals divergent operational economics across format types. Churn cycle duration and per-unit labor intensity vary dramatically between segments, directly shaping site selection and capital deployment strategies.
Product Type:
Soft serve compresses service intervals to under thirty seconds per order, while gelato demands extended display case tempering and artisanal finishing steps that slow throughput.
- Soft Serve:Continuous dispensing systems achieve the highest velocity in transportation hubs and entertainment venues where queue tolerance is minimal. Dairy base mixes require precise overrun control to maintain texture stability across variable ambient temperatures.
- Hard Ice Cream:Scoop-and-serve formats enable mix-in innovation and seasonal limited offerings that drive repeat visitation in metropolitan markets. Blast freezer dependency at minus twenty degrees Celsius constrains site selection to markets with favorable utility rate structures.
- Gelato:Lower air content and denser formulations command price premiums in coastal cities with established European culinary cultures.
- Sorbet:Water-based formulations expand addressable markets into vegan and dairy-restricted consumer segments without specialized dairy plant licensing.
Soft serve anchors the volume base while gelato gains share at the steepest rate.
Flavor Profile:
Core flavors concentrate procurement scale advantages while specialty rotations compress product development cycles and demand agile supply chain reconfiguration.
- Chocolate:Cocoa butter content variations enable tiered positioning from standard to super-premium density formulations. Procurement concentrates in West African and South American supply corridors with traceability documentation burdens under FDA Food Safety Modernization Act mandates.
- Vanilla:Madagascar Bourbon and Tahitian varietals differentiate premium positioning in affluent urban corridors. Vanilla bean commodity volatility exposes margin compression risks during supply tightness.
- Strawberry:Fruit-based formulations face shorter shelf-life constraints and cold chain intensity.
- Mint Chocolate Chip:Dual-component mixing complexity elevates labor intensity relative to single-flavor formats.
Vanilla and chocolate concentrate procurement volume while mint chocolate chip climbs fastest as a differentiation lever.
Serving Style:
Packaging format selection determines per-transaction revenue capture and consumption occasion targeting across on-premise versus mobile consumption contexts.
- Cup:Standardized portion control enables consistent margin management and reduced service friction in high-throughput environments. Cup formats dominate transportation hub locations where mobility constraints favor contained consumption.
- Cone:Waffle and cake cone varieties add tactile experience dimensions that support price premiums in experiential dining contexts. Cone dependency on ambient structural integrity limits operational windows in high-temperature climates.
- Sundae:Topping complexity elevates labor intensity and extends service intervals, constraining volume throughput.
- Milkshake:Blended preparation requires dedicated equipment footprint and cleaning protocols that raise capital intensity.
Cup formats anchor the transaction volume base while sundae configurations expand most quickly as occasion-based premium offerings.
Customer Type:
Demographic targeting shapes location strategy, operating hour configuration, and menu architecture across family-oriented suburban sites versus urban adult-focused formats.
- Families:Multi-generational parties drive higher per-visit ticket averages through multiple unit orders and premium sundae upsells. Family demand concentrates in suburban corridors with parking accessibility and proximity to complementary entertainment venues.
- Students:Price sensitivity and social clustering behavior favor value-tier positioning and extended evening operating hours near educational institutions. Student segments exhibit high frequency but low per-transaction value, demanding cost-optimized service models.
- Tourists:Transient demand patterns enable premium pricing with limited repeat visitation dependency in destination markets.
- Couples:Dual-adult occasions prioritize ambiance and shareable formats over throughput velocity.
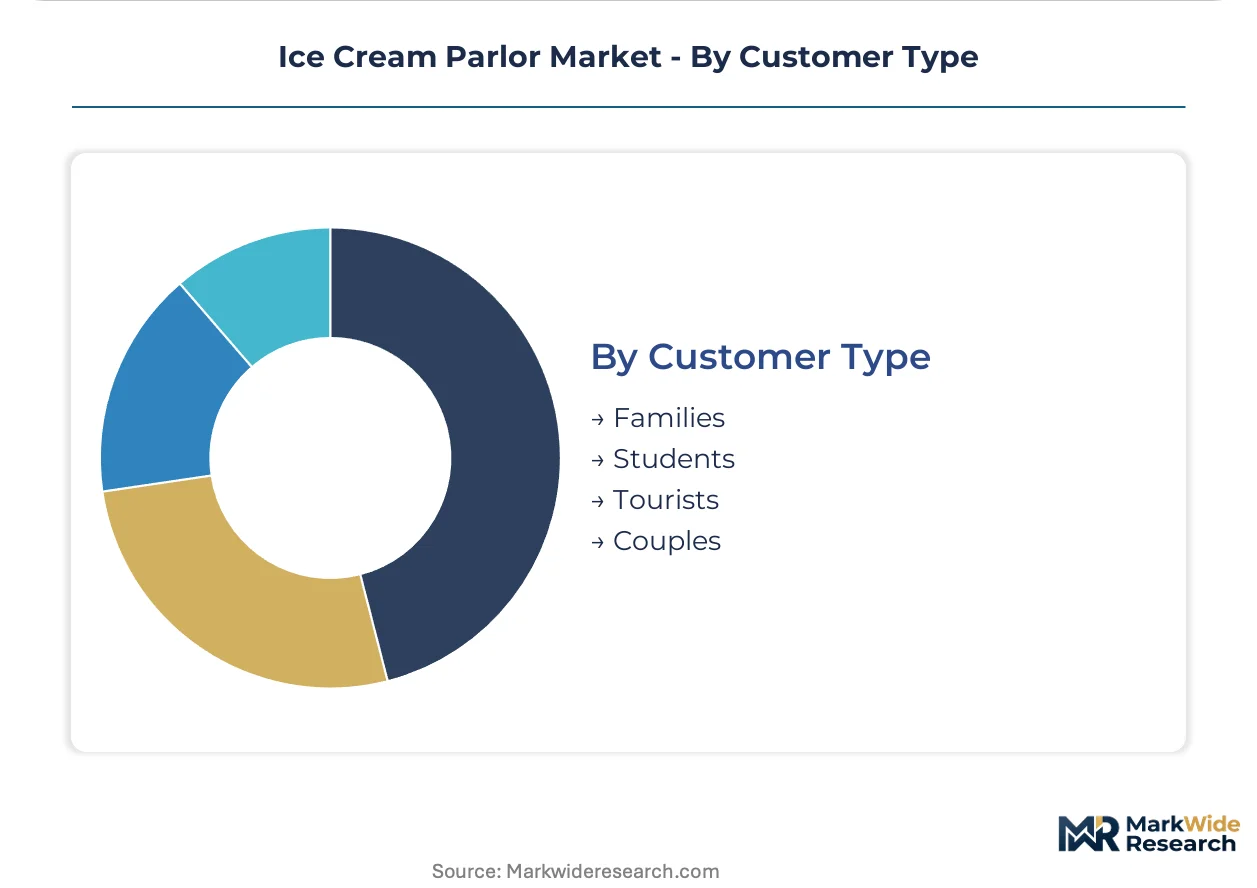
Families anchor the revenue base while couples gain share fastest as experiential dining positioning expands in metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian gelato equipment manufacturers export batch-freezing systems to premium parlor operators in the United States and Japan. Dairy base mix trade flows from New Zealand and the Netherlands supply Southeast Asian markets with standardized soft-serve formulations.
United States
Affluent urban millennials in coastal metropolitan areas drive experiential dessert demand with Instagram-worthy customization. FDA pasteurized milk ordinance standards enforce dairy safety protocols that shape equipment specifications nationwide. Los Angeles and Miami operators rotate limited seasonal menus monthly to sustain engagement among experience-seeking demographics.
Italy
Artisanal gelato authenticity commands price premiums in European culinary tourism corridors. EFSA dairy hygiene regulations govern production standards for export-oriented equipment manufacturers. Emilia-Romagna and Veneto host dense clusters of batch-freezing technology specialists supplying global premium parlor networks.
Japan
Metropolitan consumers prioritize density-focused formulations with lower air content in Tokyo and Osaka corridors. METI food safety standards mandate rigorous cold chain documentation for dairy-derived dessert operations. Kansai region operators integrate theatrical preparation elements that differentiate against standardized retail alternatives.
Germany
Flexitarian and vegan segments expand addressable markets for alternative protein bases in Berlin and Munich. ECHA chemical safety frameworks influence equipment material specifications for food-contact surfaces. Bavaria concentrates super-premium positioning specialists leveraging dense butterfat formulations in affluent urban corridors.
Australia
Extended warm climate windows sustain year-round parlor traffic in Sydney and Melbourne metropolitan areas. FSANZ dairy standards enforce traceability requirements that favor operators with integrated supply chain documentation. Queensland and Victoria host emerging soft-serve automation deployments in transportation hub locations.
Ice Cream Parlor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Franchise networks with centralized quality assurance infrastructure consolidate position against independent operators facing disproportionate compliance burdens. Three archetypes dominate: global franchise systems with integrated supply chains, regional boutique chains with experiential positioning, and independent artisanal operators with hyper-local craft systems. Competitive moves concentrate on soft-serve automation deployment and state-level dairy plant licensing arbitrage for multi-unit expansion.
Within the global franchise tier, Baskin-Robbins and Cold Stone Creamery exemplify channel-controlling archetypes with sustained market presence across diverse demographics. Häagen-Dazs occupies a super-premium positioning anchor in key urban corridors through dense butterfat formulations. These three entities represent contrasting capital intensity models that reshape competitive positioning across price tiers.
| Leading Market Players |
|---|
| Baskin-Robbins |
| Cold Stone Creamery |
| Häagen-Dazs |
| Dairy Queen |
| Ben & Jerry's |
| Braum’s Ice Cream & Dairy Stores |
| La Michoacana |
| Red Mango |
| Amorino |
| Others |
Value Network & Pricing Analysis
New Zealand and Netherlands dairy base mix exports anchor input cost structures for premium parlor operators, concentrating margin capture in coastal U.S. metropolitan markets where experiential positioning commands price premiums. FDA pasteurized milk ordinance compliance costs and butterfat commodity volatility feed directly into tiered pricing architectures across soft-serve, gelato, and super-premium formats.
Pricing Analysis
Legacy continuous-dispensing soft-erve systems, contemporary batch-freezing artisanal equipment, and emerging liquid nitrogen flash-freezing platforms stratify capital investment tiers and corresponding price positioning. Three-tier pricing structure across premium, standard, and economy levels separates Häagen-Dazs super-premium density formulations from mid-market franchise formats and value-tier student-focused locations. Cost compression in economy tiers is intensifying because of energy-intensive blast freezer operations at minus twenty degrees Celsius. Students exhibit highest price sensitivity while affluent urban millennials in experiential dining contexts show least elasticity.
Supply Chain Analysis
Tariff exposure between U.S. and European dairy equipment suppliers dominates procurement risk planning for batch-freezing system acquisitions. Manufacturing concentrates in Italy's Emilia-Romagna cluster for artisanal gelato equipment, China's industrial zones for soft-serve automation components, and Wisconsin for domestic dairy base processing. Raw material dependencies span Madagascar Bourbon vanilla beans, West African cocoa butter, and domestic butterfat supplies. Single-source vulnerability persists in Italian batch-freezing technology where specialized artisans control export volumes. Distribution runs through franchise network central commissaries for chains and direct-to-parlor relationships for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaged retail ice cream and ghost kitchen dessert delivery represent substitution threats that incumbent parlor operators must navigate through experiential differentiation and speed-to-customization advantages.
For Market Incumbents: Insulate market position by deploying soft-serve automation in transportation hubs previously uneconomical for full-service formats, reducing labor intensity against rising wage pressure. Deepen backward integration into captive dairy base processing to buffer butterfat commodity volatility and FDA traceability compliance costs. Franchise systems should consolidate supplier networks toward vertically integrated processors with pre-certified documentation systems. For New Entrants and Emerging Players: Mid-market gelato authenticity positioning in secondary U.S. metropolitan areas with emerging European culinary cultures represents the most penetrable entry point before regulatory harmonization tightens. State-level dairy plant licensing arbitrage in streamlined jurisdictions offers first-mover multi-unit expansion advantages. Go-to-market execution should emphasize theatrical preparation elements and Instagram-visible liquid nitrogen flash-freezing systems for social media amplification. For Investors and Strategic Acquirers: Capital is best deployed toward regional boutique chains with experiential positioning and integrated ERP-to-supplier data linkages that satisfy Food Safety Modernization Act mandates. Long-term viability across the analysis window hinges on compliance infrastructure scalability rather than single-location craft authenticity. The signal to watch is consolidation velocity among franchise systems capable of absorbing independent operators facing disproportionate administrative burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Artisanal Batch-Freezing Equipment Deployment | Liquid nitrogen systems in Brooklyn and San Francisco parlors achieve instant texture fixation with visible vapor effects driving social amplification. |
| Soft-Serve Automation Expansion | Reduced labor intensity enables high-traffic location models in transportation hubs and entertainment venues previously uneconomical for full-service formats. |
| Alternative Protein Base Innovation | Oat, coconut, and cashew formulations expand addressable markets beyond lactose-intolerant consumers into flexitarian and vegan segments. |
| State-Level Licensing Arbitrage | Jurisdictions with streamlined permitting pathways offer first-mover advantages for multi-unit expansion before regulatory harmonization tightens. |
| Seasonal Limited Offering Rotation | Monthly menu rotations in Los Angeles and Miami sustain engagement among experience-seeking demographics with low brand loyalty. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with ice cream parlor operators, dairy base mix procurement managers, franchise development executives, and county health department inspectors; and secondary validation through FDA pasteurized milk ordinance filings, state dairy plant licensing databases, EFSA hygiene regulation documentation, and customs trade flows for Italian gelato equipment exports. Bottom-up triangulation across operator-level operational economics and top-down market sizing anchored volume and value estimates.
Forecast inputs include product type segmentation across soft-serve, hard ice cream, gelato, and sorbet; serving style differentiation between cup, cone, sundae, and milkshake formats; and customer type targeting across families, students, tourists, and couples. CAGRs were derived through regression analysis of historical expansion patterns and forward projection of experiential dining adoption curves across coastal metropolitan markets. Industry-specific inputs span butterfat commodity price trajectories and blast freezer energy cost structures.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity prices, utility rate structures, or FDA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about experiential dining culture persistence and alternative protein regulatory classification stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Fresh Pasta Market
Processed Foods
Egg Powder Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
North America Ice Cream Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Processed Mango Products Market
Processed Foods
Processed Vegetable Market
Processed Foods
Processed Potatoes Market
Processed Foods
Processed Beef Market
Processed Foods
Noodles Market
Processed Foods
Porridge Market
Processed Foods
Instant Curry Market
Processed Foods
Yogurt Dip Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Ready to Cook Market