
 Fruit Processing Market | 2026-2036
Fruit Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Processing Market Analysis
Food processing labor availability is bifurcating the competitive landscape between automated high-volume plants and labor-intensive specialty operations. Dole Food Company leverages integrated plantation-to-packing operations across Central America to sustain cost advantages in banana and pineapple processing. Del Monte Foods anchors its North American position through controlled supply chains in Costa Rica and the Philippines. AGRANA Beteiligungs-AG specializes in fruit ingredient systems for European dairy and bakery customers, competing on technical specification breadth rather than commodity scale.
Fruit processing encompasses the mechanical and thermal transformation of raw harvested fruits into shelf-stable juices, purees, concentrates, and dried products through techniques such as enzymatic maceration at 45-55°C, evaporative concentration to 65-72°Brix, and sublimation drying at pressures below 600 Pa. The primary purpose is to extend seasonal availability, reduce perishability losses exceeding 30% in fresh distribution, and deliver standardized inputs for downstream food manufacturing. Juices and concentrates occupy the largest value share within product type segmentation, though freeze-dried fruit pieces command premium positioning in nutraceutical and premium snack applications where cold pressing preserves volatile aromatic compounds that pasteurization degrades. Vacuum concentration technology leads capital deployment in tropical processing hubs where energy costs favor efficient water removal, while freeze-drying capacity expansion tracks fastest in European and North American facilities serving functional ingredient demand.
EFSA maximum residue limits and the EU Green Deal's pesticide reduction targets are reshaping raw material sourcing protocols for processors exporting into Europe, forcing upstream orchard certification investments. FDA juice HACCP regulations and FSMA preventive controls govern US market access, with intensified FDA inspections of foreign supplier verification programs affecting import clearance timelines. India's FSSAI standards for fruit beverages and the CDSCO framework for nutraceutical claims create compliance complexity for multinational processors operating across jurisdictions. Stakeholders must monitor divergence between EU and US tolerance standards for emerging processing aids and enzymes, as regulatory misalignment threatens to fragment formulation strategies and duplicate certification costs.
Market Dynamics
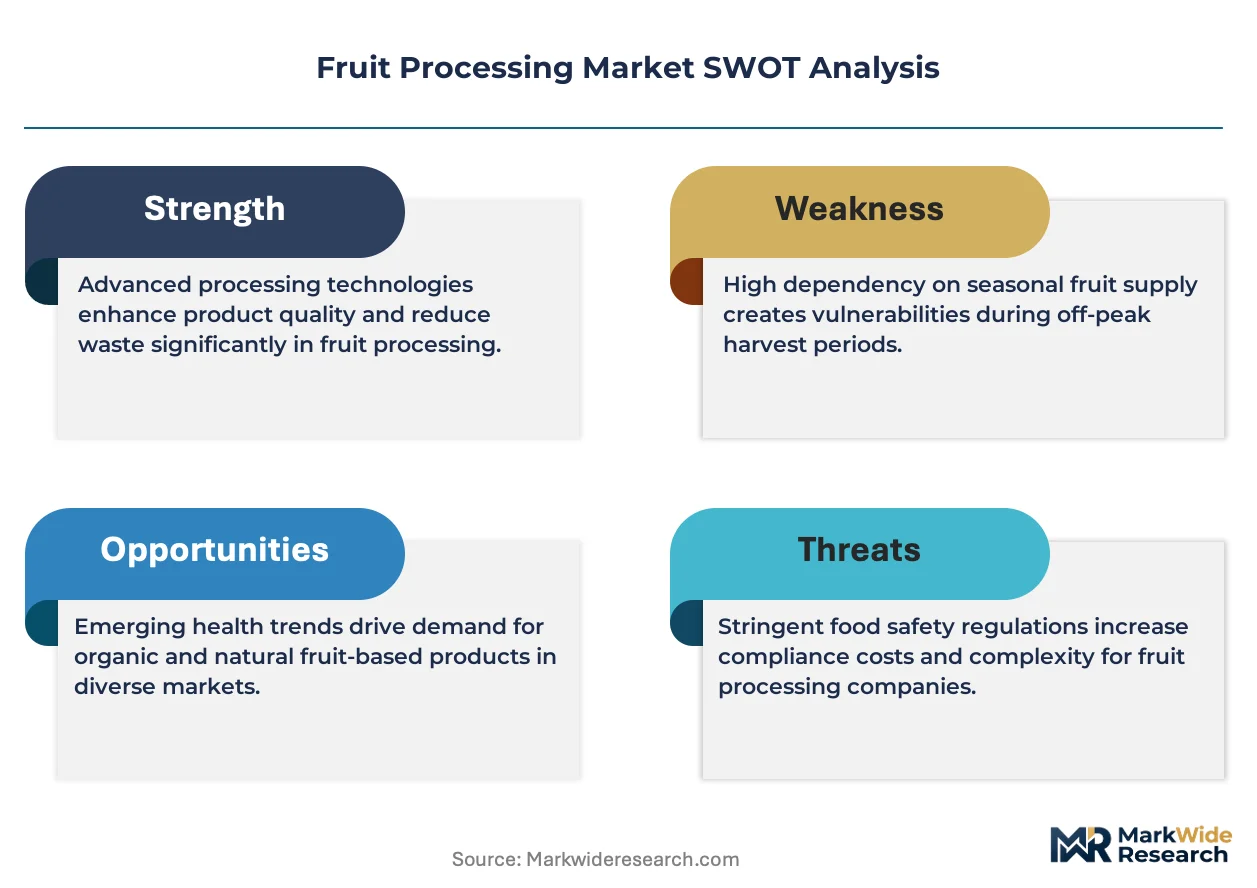
Clean-label reformulation pressure from EFSA pesticide residue limits is forcing processors to rebuild supply chains around certified orchards and enzyme-based alternatives to chemical preservatives. This regulatory compression is reshaping capital allocation toward upstream integration and traceability infrastructure.
Growth Catalysts
- EFSA Maximum Residue Limits:The EU's tightening standards for pesticide residues in processed fruit products are accelerating orchard certification programs and driving demand for biological pest control inputs across Mediterranean and tropical supply basins.
- Urban Retail Modernization:India's organized retail expansion and cold chain infrastructure buildout under PLI scheme incentives are creating new offtake capacity for aseptic purees and extended-shelf-life concentrates in South Asian markets.
- Enzymatic Maceration:Adoption of controlled-temperature enzymatic processing at 45-55°C is preserving volatile aromatic compounds that conventional thermal methods degrade, opening premium positioning in nutraceutical and functional beverage applications.
Market Restraints
- Tropical Energy Costs:Evaporative concentration to 65-72°Brix requires substantial thermal energy inputs, making operations in Southeast Asian and Central American processing hubs vulnerable to fossil fuel price volatility and grid instability.
- Raw Material Concentration:Banana and pineapple processing volumes concentrate in Costa Rican and Philippine supply chains, creating geographic risk exposure to climate events and labor disruptions in narrow sourcing corridors.
- Substitution Pressure:Synthetic flavor systems and fermentation-derived fruit compounds are capturing cost-sensitive applications in confectionery and beverage manufacturing, compressing demand for commodity-grade concentrates.
Strategic Opportunities
- Freeze-Dried Functional Ingredients:Sublimation drying capacity expansion in European facilities is capturing premium demand from nutraceutical manufacturers seeking cold-processed fruit pieces with intact bioactive compound profiles.
- CDSCO Nutraceutical Framework:India's emerging regulatory pathway for functional food claims creates first-mover positioning for processors able to validate antioxidant and fiber content through standardized analytical protocols.
- Direct-to-Manufacturer Channels:Bakery and dairy ingredient buyers are bypassing traditional distribution tiers to contract directly with puree and concentrate specialists, compressing margin extraction by intermediaries.
Industry Challenges
- Cross-Jurisdictional Compliance:Multinational processors face divergent tolerance standards for processing enzymes and emerging aids between EFSA and FDA frameworks, forcing duplicate certification investments and formulation fragmentation.
- Specialized Equipment Sourcing:Vacuum concentration and freeze-drying systems require extended procurement lead times and specialized installation expertise, constraining rapid capacity scaling in response to demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Processing Market |
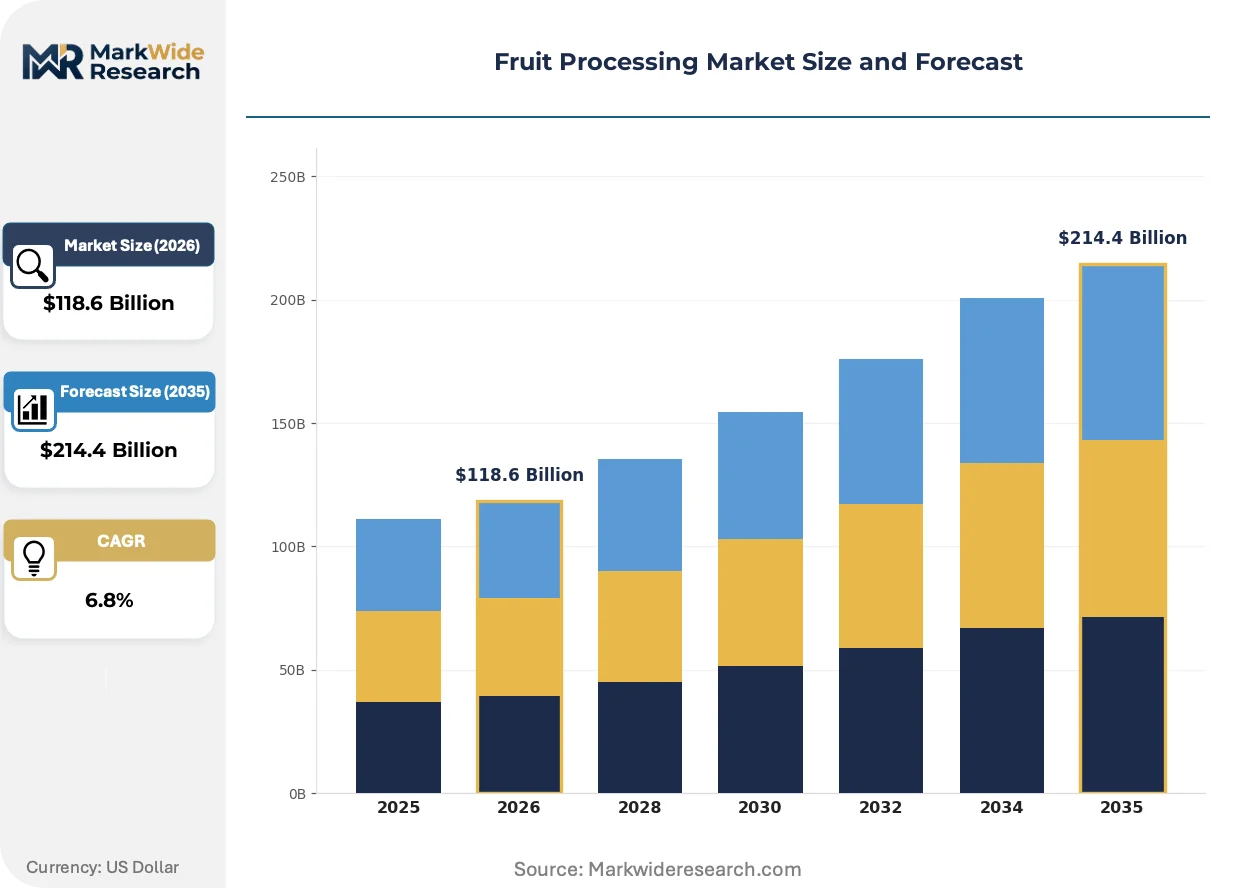
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Purees, Concentrates, Dried Fruits Technology: Cold Pressing, Pasteurization, Freeze-Drying, Vacuum Concentration End User: Food & Beverage, Bakery, Ice Cream, Nutraceuticals Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | Dole Food Company, Del Monte Foods, Chiquita Brands International, Fresh Del Monte Produce, Conagra Brands, The Kraft Heinz Company, AGRANA Beteiligungs-AG, PepsiCo, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Processing Market Emerging Trajectories
Cold-chain integrity and minimal-processing technologies are redefining value capture in fruit processing. Equipment manufacturers and ingredient specialists are converging on systems that preserve sensory quality while extending distribution reach.
Pulsed electric field pasteurization is displacing conventional thermal treatments in premium juice applications. Beverage manufacturers in Germany and the Netherlands are adopting PEF systems to retain heat-sensitive vitamins and volatile flavor compounds. This technology is displacing tunnel pasteurization lines that degrade aromatic profiles, compressing the quality gap between fresh-pressed and shelf-stable products.
The EU Green Deal's pesticide reduction targets are mandating upstream operational changes for exporters. Processors serving European markets must now verify integrated pest management compliance across entire orchard networks. Tropical suppliers in Ecuador and Colombia are responding by converting conventional acreage to certified organic production ahead of 2030 reduction milestones.
Ingredient buyers are consolidating supplier relationships around vertically integrated processors with captive orchard operations. North American dairy and bakery manufacturers are reducing their vendor counts from five to two puree suppliers, prioritizing partners with direct control over Costa Rican and Philippine fruit supply. This concentration is most visible in contract negotiations for pineapple and mango concentrates, where traceability guarantees now outweigh price differentials in sourcing decisions.
Fruit Processing Market Segmentation
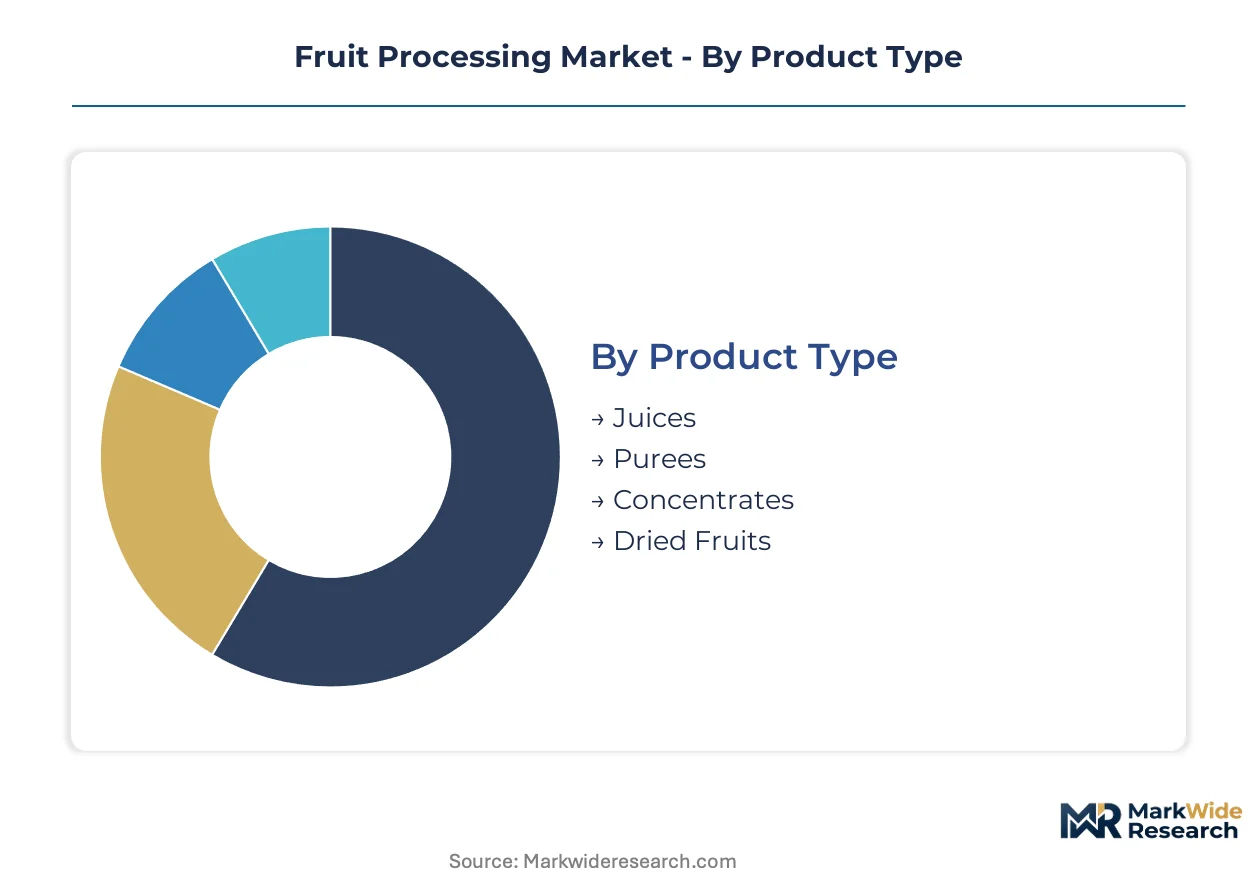
Segmentation in fruit processing reveals how value migrates across distinct technical specifications and channel requirements. Product form, processing intensity, and end-use application each create separate margin pools with divergent capital and certification demands.
Product Type:
Channel positioning varies sharply by product form—juices and concentrates flow through beverage bottlers and industrial ingredient channels, while dried fruits and purees split between retail packs and foodservice bulk.
- Juices:Single-strength and reconstituted formats dominate retail cold cases and foodservice fountain systems. German beverage manufacturers are expanding aseptic bottling capacity to capture EFSA-compliant clean-label positioning.
- Concentrates:Evaporated to 65-72°Brix for reduced transport costs and extended shelf stability. Indian processors under PLI scheme incentives are building concentrate capacity to supply domestic dairy and bakery expansion.
- Purees:Smooth, seedless fruit preparations for infant nutrition and smoothie bases.
- Dried Fruits:Dehydrated and freeze-dried pieces for snacking and cereal applications.
By volume, concentrates lead. By growth pace, purees are climbing the fastest.
Technology:
Capital deployment intensity separates these methods—freeze-drying and vacuum concentration demand specialized equipment with extended procurement timelines, while cold pressing and pasteurization scale more rapidly.
- Cold Pressing:Mechanical extraction at ambient temperatures preserves heat-sensitive vitamins and volatile aromatic compounds. Netherlands-based juice specialists are displacing tunnel pasteurization with PEF-cold press combinations for premium positioning.
- Vacuum Concentration:Low-temperature water removal at reduced pressure protects color and flavor integrity. Southeast Asian processing hubs favor this technology where energy costs dictate thermal efficiency priorities.
- Pasteurization:Thermal treatment for pathogen reduction and shelf stability.
- Freeze-Drying:Sublimation at pressures below 600 Pa for functional ingredient applications.
By installed base, pasteurization dominates. By expansion rate, freeze-drying is gaining share fastest.
End User:
Specification stringency escalates from foodservice bulk through pharmaceutical-grade nutraceutical applications, with bakery and ice cream occupying intermediate tolerance bands.
- Food & Beverage:Largest volume absorption across carbonated, still, and functional drink formulations. Costa Rican and Philippine supply chains anchor procurement for North American bottlers demanding traceability guarantees.
- Nutraceuticals:Antioxidant-standardized extracts and fiber-fortified ingredients for supplement manufacturers. India's CDSCO framework is creating first-mover positioning for processors validating bioactive content through standardized analytical protocols.
- Bakery:Fruit fillings, glazes, and inclusions for industrial and artisanal production.
- Ice Cream:Variegates and fruit bases for frozen dessert applications.
By revenue concentration, food and beverage leads. By margin expansion, nutraceuticals are pulling ahead.
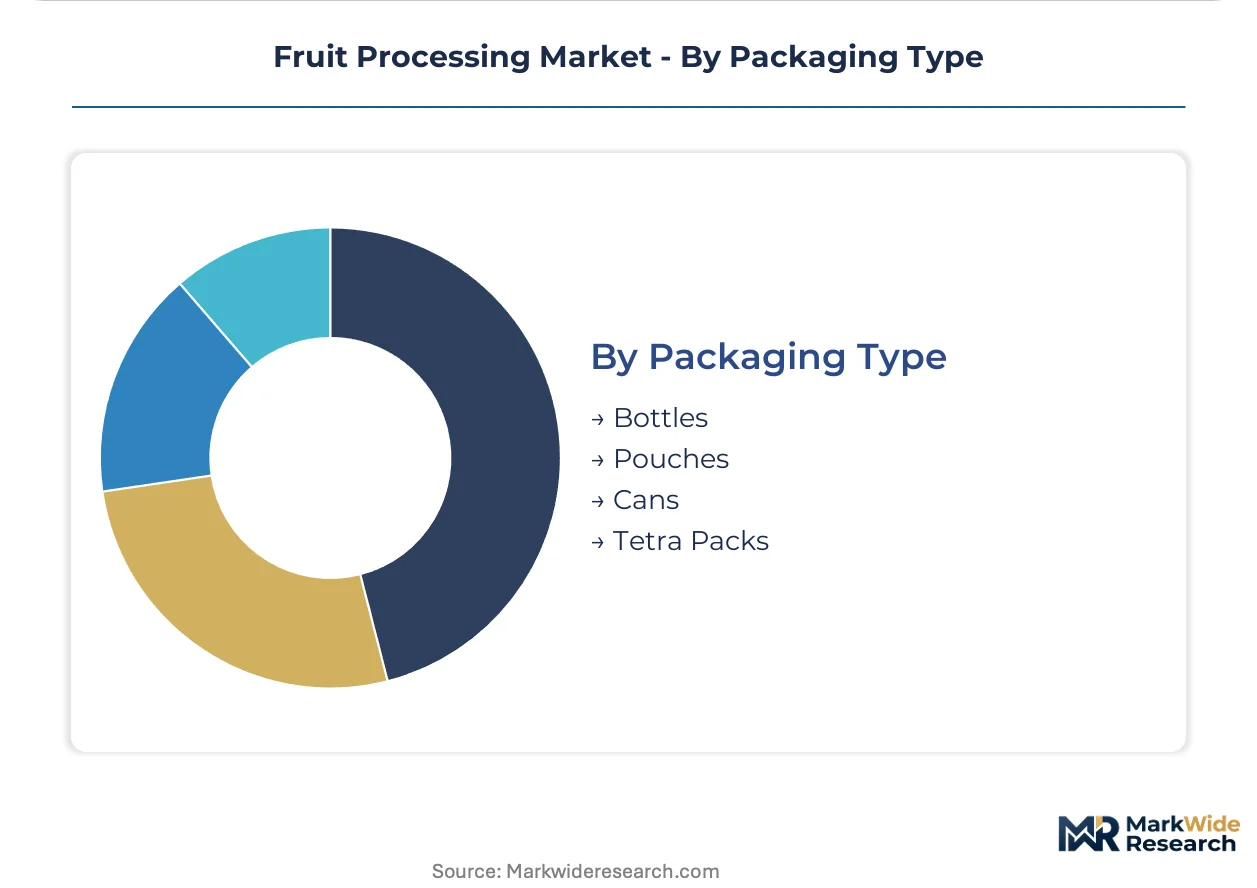
Packaging Type:
Format selection tracks distribution distance and shelf-life requirements—aseptic cartons for ambient distribution, bottles for refrigerated premium positioning, pouches for foodservice efficiency.
- Tetra Packs:Aseptic brick and gable-top cartons dominate ambient juice distribution. European retail modernization is accelerating carton filling line deployment for extended-shelf-life concentrates.
- Bottles:PET and glass formats for refrigerated premium juices and high-viscosity purees. German retailers are specifying rPET content minimums under EU Green Deal circularity mandates.
- Pouches:Flexible formats for foodservice bulk and single-serve applications.
- Cans:Metal packaging for carbonated fruit beverages and tropical juice blends.
By unit volume, Tetra Packs lead. By sustainability-driven conversion, bottles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA pesticide residue limits are reshaping procurement patterns for processors exporting into Europe, while India's PLI scheme accelerates capacity buildout across South Asian supply chains. Tropical processing hubs face energy cost pressures that favor vacuum concentration investments.
United States
Demand for cold-pressed juices and aseptic purees is climbing among beverage bottlers seeking clean-label positioning. FDA juice HACCP regulations and FSMA preventive controls govern market access, with intensified inspections of foreign supplier verification programs affecting import clearance timelines. California's Central Valley anchors domestic fruit concentrate production, where processors are retrofitting lines for extended-shelf-life formats.
Germany
Beverage manufacturers are adopting pulsed electric field pasteurization systems to preserve heat-sensitive vitamins in premium juice applications. The EU Green Deal's pesticide reduction targets mandate integrated pest management compliance across orchard networks supplying German processors. Hamburg and the Rhine-Ruhr corridor concentrate aseptic bottling capacity for EFSA-compliant clean-label distribution.
India
Urban retail modernization and cold chain infrastructure expansion under PLI scheme incentives are creating new offtake capacity for aseptic purees. FSSAI standards for fruit beverages and CDSCO frameworks for nutraceutical claims create compliance complexity for multinational operators. Maharashtra and Karnataka are accelerating processing plant construction to serve domestic dairy and bakery ingredient demand.
Costa Rica
Controlled supply chains for banana and pineapple processing sustain North American market access through traceability guarantees. EFSA maximum residue limits are forcing upstream orchard certification investments and biological pest control adoption. The Central Valley processing corridor is converting conventional acreage to certified organic production ahead of EU reduction milestones.
Philippines
Tropical fruit concentrate exports face geographic risk exposure from climate events and labor disruptions in narrow sourcing corridors. The country's national food safety regulator enforces standards aligned with FDA and EFSA frameworks for export market access. Mindanao anchors pineapple processing volumes, where energy grid instability constrains evaporative concentration scaling.
Fruit Processing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the fruit processing sector. Consolidated plantation-to-packing operations compete against specialized ingredient system providers on divergent value vectors. Three archetypes dominate: vertically integrated tropical processors with captive orchard supply, European technical specification specialists, and multinational beverage conglomerates with captive ingredient demand. Competitive moves center on backward integration into certified orchard networks and strategic partnerships with equipment manufacturers for minimal-processing technology deployment.
Within the plantation-integrated tier, Dole Food Company and Del Monte Foods exemplify scale-driven positioning through Central American and Southeast Asian supply chain control. AGRANA Beteiligungs-AG occupies the European specialist position, competing on technical specification breadth for dairy and bakery customers rather than commodity volume. These three anchors illustrate how geographic supply control, regulatory compliance depth, and end-use technical capability define separable competitive vectors in fruit processing.
| Leading Market Players |
|---|
| Dole Food Company |
| Del Monte Foods |
| Chiquita Brands International |
| Fresh Del Monte Produce |
| Conagra Brands |
| The Kraft Heinz Company |
| AGRANA Beteiligungs-AG |
| PepsiCo |
| Nestle |
| Others |
Supply Flow & Price Mechanics
Extended equipment procurement lead times of 14-18 months for vacuum concentration systems compress margin flexibility for processors, concentrating pricing power with German and Dutch equipment manufacturers while forcing tropical operators toward standardized, lower-specification alternatives.
Pricing Analysis
Geographic price spreads between European cold-pressed juice premiums and Southeast Asian commodity concentrate baselines reflect certification tier differentials. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA organic certification, conventional integrated pest management, and uncertified commodity grades. Pricing pressure stems from synthetic flavor substitution in confectionery applications, compressing demand for standard-grade concentrates. Foodservice bulk buyers exhibit highest price sensitivity, while nutraceutical contract manufacturers accept premiums for validated bioactive content.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose concentrate shipments to European bottlers, forcing inventory buffer expansion at Rotterdam and Hamburg port facilities. Raw material sourcing draws from Costa Rican pineapple corridors, Philippine banana plantations, and Indian mango orchards. Supply chain risk centers on single-source vulnerability in Mindanao processing capacity, where energy grid instability constrains evaporative concentration scaling. Distribution runs through captive plantation-to-packing operations for integrated majors, with independent processors relying on third-party cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability-as-a-service and orchard certification management represent faster-expanding revenue layers than commodity processing equipment, creating attach opportunities for data platforms and compliance verification services.
For Market Incumbents: Fortify backward integration into certified organic acreage ahead of EU Green Deal pesticide reduction milestones. Expand pulsed electric field pasteurization capacity in German and Netherlands facilities to capture premium juice positioning. Dole Food Company and Del Monte Foods demonstrate how captive Costa Rican and Philippine supply chains defend against traceability-driven procurement consolidation by North American dairy and bakery buyers.
For New Entrants and Emerging Players: Differentiate on CDSCO-compliant nutraceutical validation services for Indian functional ingredient demand. Target Maharashtra and Karnataka processing corridors where PLI scheme incentives reduce capital barriers. White-space exists in freeze-dried functional ingredient supply to European supplement manufacturers seeking cold-processed bioactive preservation.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because EFSA-FDA regulatory divergence forces duplicate certification investments and traceability technology deployment. Acquisition targets should prioritize processors with integrated orchard networks and validated enzyme-based processing protocols. The signal to watch is divergence between EU and US tolerance standards for emerging processing aids, which would accelerate formulation fragmentation and compliance service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Certification Investment | EFSA pesticide residue limits force upstream compliance verification across Mediterranean and tropical supply basins. |
| Minimal-Processing Technology Deployment | Pulsed electric field pasteurization preserves volatile aromatic compounds that German premium juice bottlers specify. |
| Cold Chain Infrastructure Expansion | India's PLI scheme incentives accelerate aseptic puree capacity buildout in Maharashtra and Karnataka corridors. |
| Direct-to-Manufacturer Channel Development | Bakery and dairy ingredient buyers bypass intermediaries to contract with puree specialists for traceability guarantees. |
| Nutraceutical Validation Capability Buildout | CDSCO framework creates first-mover positioning for processors standardizing antioxidant and fiber content protocols. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including fruit processing plant managers, procurement leads at North American dairy and bakery manufacturers, cold chain logistics coordinators, and regulatory affairs specialists navigating EFSA-FDA divergence. Secondary validation drew from FDA juice HACCP guidance documents, EFSA maximum residue limit databases, FSSAI fruit beverage standards, Indian PLI scheme policy filings, and customs trade data for concentrate and puree shipments. Bottom-up capacity assessments across Costa Rican, Philippine, and Indian processing corridors were triangulated against top-down demand modeling from beverage bottler and ingredient buyer surveys.
Across the analysis window, volume and value outputs reflect segmentation by product form, processing technology intensity, end-use application stringency, and geographic regulatory cluster. CAGRs were derived from installed capacity expansion trajectories, technology adoption curves for enzymatic and minimal-processing methods, and import demand elasticity observed in European and North American offtake markets. Forecast inputs incorporated energy cost volatility assumptions for tropical evaporative concentration, PLI scheme incentive uptake rates in India, and EFSA organic certification conversion timelines.
The analysis sits within stated boundaries; outcomes outside sustained EFSA-FDA regulatory divergence, stable tropical energy grid access, and continued PLI scheme funding would require recalibration. Forecasts reflect documented assumptions regarding certification conversion rates, technology procurement lead times, and cold chain infrastructure buildout pace. Practitioners should keep alternative scenarios live as EU Green Deal pesticide reduction milestones, Indian urban retail modernization trajectories, and synthetic flavor substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Global Pasta Market
Processed Foods
Potato Soup Market
Processed Foods
United States Ice Cream Market
Processed Foods
Soup & Broth Market
Processed Foods
Egg Powder Market
Processed Foods
United States Processed Meat Market
Processed Foods
Europe Soup Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Processed Potatoes Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Spreadable Fats Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Instant Curry Market
Processed Foods
Spray Cheese Market
Processed Foods
Asia-Pacific Soup Market