
 Global Vaginal Sling Market | 2026-2036
Global Vaginal Sling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaginal Sling Market Foresight
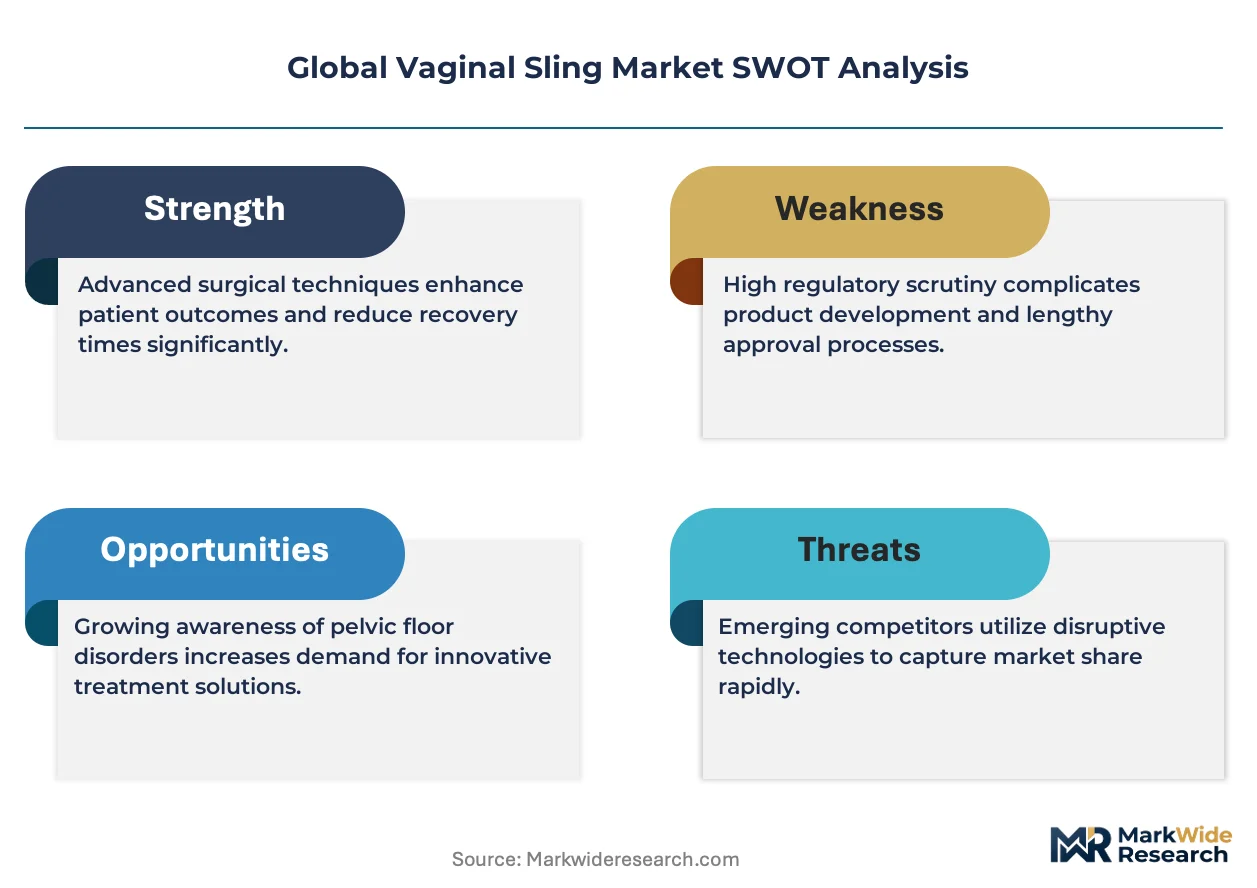
EU MDR is decoupling market access from legacy CE certificates by demanding renewed clinical validation for polypropylene mesh devices. Becton, Dickinson and Company leverages its broad urology portfolio to sustain hospital contracts across multiple sling categories. Boston Scientific Corporation anchors its position through specialized pelvic floor product lines that compete on surgeon training depth rather than price alone.
A vaginal sling is a synthetic or biologic mesh implant, typically woven from monofilament polypropylene with pore sizes exceeding 75 micrometers to permit tissue ingrowth and reduce erosion risk, designed to provide urethral support and restore continence via minimally invasive placement. Transobturator slings dominate procedural volume in Europe due to established surgeon familiarity and favorable reimbursement coding, while mini-slings represent the fastest-expanding product category as ambulatory surgery centers seek reduced operative time and faster patient turnover. Polypropylene material formulations command the largest share of manufacturing output, though biologic graft alternatives are gaining traction in revision cases where synthetic erosion has occurred.
FDA premarket notification requirements and EU MDR conformity assessments are elevating clinical data burdens for new mesh entrants, while Japan's PMDA maintains distinct biocompatibility testing protocols that filter import approvals. Health Canada and TGA alignment on ISO 10993 biological evaluation standards is creating partial regulatory harmonization for multinational manufacturers. Stakeholders must monitor evolving litigation exposure frameworks and payer coverage restrictions as these forces increasingly determine commercial viability independent of technical performance.
Market Dynamics
The vaginal sling market is undergoing structural compression as EU MDR clinical evidence requirements force manufacturers to rebuild regulatory dossiers for legacy polypropylene mesh devices, while ambulatory surgery centers simultaneously demand shorter procedure times and faster patient throughput.
Growth Catalysts
- Aging demographics in developed economies:The United States, Germany, and Japan sustain procedure volumes through established reimbursement pathways and expanding insured populations over age 65 requiring stress urinary incontinence intervention.
- EU MDR transition timeline:The regulation's 2024-2028 recertification window is accelerating hospital purchasing decisions as facilities stockpile approved inventory ahead of anticipated supply disruptions.
- Mini-sling technology maturation:Single-incision systems reduce operative time by 40% compared to transobturator approaches, enabling ambulatory surgery centers to expand daily case capacity without additional staffing.
Market Restraints
- Polypropylene raw material concentration:Medical-grade monofilament supply chains cluster in Germany and the United States, exposing manufacturers to petrochemical price volatility and single-source dependency risks.
- FDA 510(k) evidentiary burdens:New mesh entrants face expanded clinical data requirements following 2019 safety communications, extending time-to-market by 18-24 months and elevating development costs.
- Biologic graft cost premiums:Porcine dermis and human allograft alternatives cost 8-12 times synthetic equivalents, limiting adoption to revision cases where prior erosion occurred.
Strategic Opportunities
- Japan's PMDA biocompatibility pathway:Distinct testing protocols create first-mover advantages for manufacturers investing in localized ISO 10993-6 irritation studies ahead of competitor submissions.
- Ambulatory surgery center channel expansion:Mini-sling products with sub-15-minute implantation protocols unlock same-day discharge revenue models previously restricted to hospital outpatient departments.
- Health Canada-TGA regulatory harmonization:Aligned biological evaluation standards enable single dossier submissions covering two previously separate approval processes, compressing multinational launch timelines.
Industry Challenges
- Pelvic floor surgeon training pipeline constraints:Fellowship programs produce fewer than 200 qualified specialists annually in the United States, creating procedural bottlenecks that limit volume growth regardless of product availability.
- Mesh erosion litigation exposure:Product liability frameworks in California, Texas, and Illinois impose unpredictable damage awards that distort pricing models and deter market entry by mid-cap manufacturers.
- EU MDR notified body capacity shortages:Only 12 designated bodies hold pelvic floor device scope, creating 14-18 month audit queues that delay recertification regardless of dossier quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaginal Sling Market |
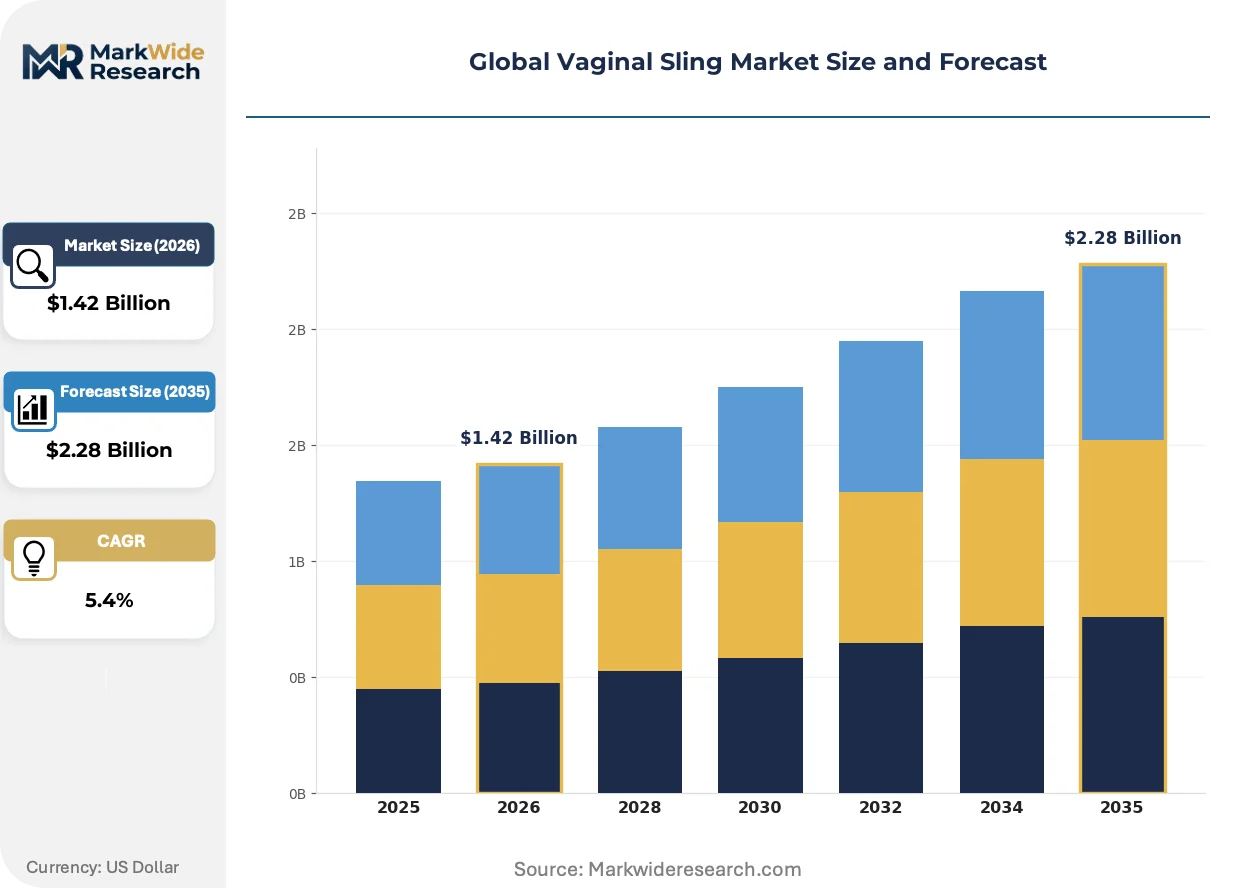
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retropubic Sling, Transobturator Sling, Mini-Sling, Adjustable Sling Material: Polypropylene, Polyethylene Terephthalate, Polytetrafluoroethylene, Biologic Graft Application: Stress Urinary Incontinence, Pelvic Organ Prolapse, Urethral Support, Post-Surgical Repair End User: Hospitals, Ambulatory Surgery Centers, Clinics, Specialty Urology Centers |
| Companies Covered | Becton, Dickinson and Company, Cook Medical LLC, Johnson & Johnson, B. Braun Melsungen AG, Caldera Medical, Inc., Boston Scientific Corporation, Endo International plc, Promedon Group, Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaginal Sling Market Shifts & Advancements
Material science advances and regulatory recalibration are converging to redefine competitive positioning in pelvic floor repair, with three distinct vectors reshaping how slings are designed, approved, and deployed across care settings.
Resorbable synthetic polymers are expanding into the revision surgery segment as an intermediate alternative between permanent mesh and biologic grafts. Tertiary referral centers in Boston and Cleveland are adopting these materials for patients with prior synthetic erosion who cannot afford allograft premiums. The technology is expanding into price-sensitive markets by enabling mid-tier pricing between economy polypropylene and premium biologics.
EU MDR Article 54 clinical evaluation requirements are forcing manufacturers to generate new post-market surveillance data for devices previously cleared under MEDDEV guidance. The regulation mandates annual safety updates and systematic literature reviews that smaller competitors cannot resource internally. Transobturator sling portfolios face the steepest compliance burden due to their higher historical implant volumes and corresponding adverse event databases.
Ambulatory surgery centers are consolidating purchasing authority through group purchasing organizations that negotiate device-procedure bundled rates. Hospital systems in Florida and Texas are transferring sling cases to freestanding facilities to capture facility fee differentials, displacing traditional hospital outpatient department volume. Germany's Klinikum sector is replicating this shift through specialized pelvic floor day-clinic networks in Bavaria and North Rhine-Westphalia.
Global Vaginal Sling Market Segmentation
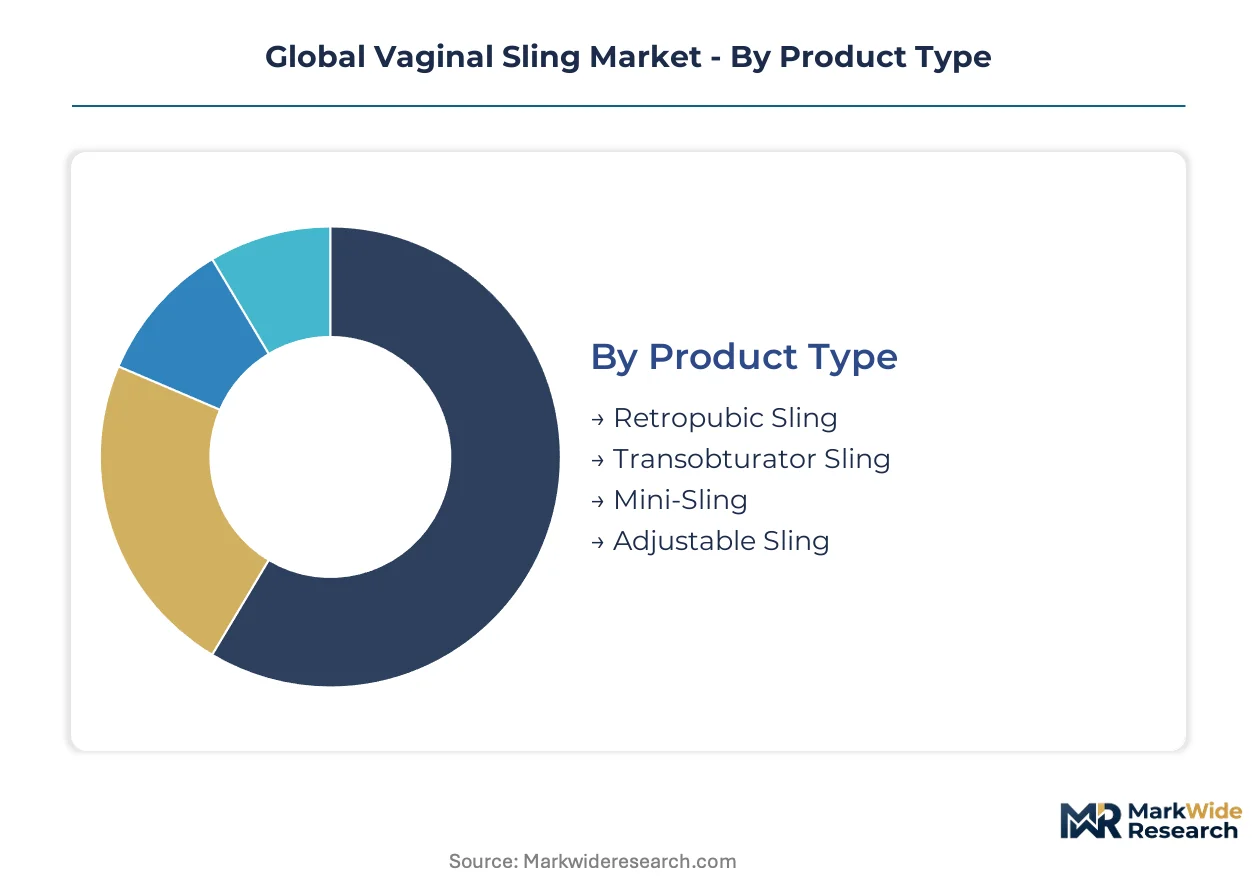
Segmentation in the vaginal sling market reflects divergent clinical priorities across care settings, from permanent mesh durability demands in tertiary hospitals to rapid-turnover requirements in ambulatory facilities. Manufacturers configure product portfolios around these distinct performance specifications rather than pursuing uniform platform strategies.
Product Type:
Technical approach to urethral support determines operative time, anesthesia requirements, and reimbursement coding eligibility across facility types.
- Transobturator Sling:Routes mesh through the obturator foramen without entering the retropubic space, eliminating bladder perforation risks that complicated earlier approaches. European hospitals in Germany and France maintain established surgeon training pathways and favorable DRG coding that sustains procedural volume.
- Mini-Sling:Single-incision systems deploy through a vaginal entry point only, eliminating groin incisions and reducing operative time to under 15 minutes. Ambulatory surgery centers in the United States and Germany are expanding daily case capacity through these streamlined protocols.
- Retropubic Sling:Passes behind the pubic bone via abdominal wall incisions, requiring general anesthesia and longer recovery windows.
- Adjustable Sling:Incorporates post-implantation tension modification mechanisms for revision cases where initial support proves insufficient.
Transobturator sling leads on scale; mini-sling leads on momentum.
Material:
Raw material selection trades off tissue integration performance against biocompatibility certification costs and litigation exposure profiles.
- Polypropylene:Monofilament woven structures with pore sizes exceeding 75 micrometers permit fibroblast infiltration while limiting bacterial colonization. The material dominates manufacturing output in the United States and Germany, though EU MDR recertification requirements are elevating clinical evidence burdens for legacy formulations.
- Biologic Graft:Porcine dermis and human allograft alternatives eliminate permanent foreign body exposure, commanding premium pricing in revision cases where prior synthetic erosion occurred. Tertiary referral centers in Boston and Cleveland are adopting these materials for patients with mesh complications who cannot tolerate re-exposure risk.
- Polyethylene Terephthalate:Polyester-based meshes offer alternative pore architecture with different tissue ingrowth kinetics.
- Polytetrafluoroethylene:Expanded PTFE formulations provide inert surface chemistry with minimal inflammatory response.
Polypropylene leads on scale; biologic graft leads on momentum.
Application:
Clinical indication determines anatomical placement, tension requirements, and concomitant procedure compatibility.
- Stress Urinary Incontinence:Mid-urethral positioning addresses hypermobility during cough or exertion, representing the predominant procedural indication across all geographies. The United States, Germany, and Japan sustain volume through aging demographics and established reimbursement pathways for this indication.
- Post-Surgical Repair:Addresses recurrent incontinence following failed prior interventions, often requiring biologic materials or adjustable systems. This segment concentrates in tertiary referral centers with specialized pelvic floor reconstruction capabilities.
- Pelvic Organ Prolapse:Sling placement augments compartment-specific repair procedures.
- Urethral Support:Targets intrinsic sphincter deficiency with higher tension requirements.
Stress urinary incontinence leads on scale; post-surgical repair leads on momentum.
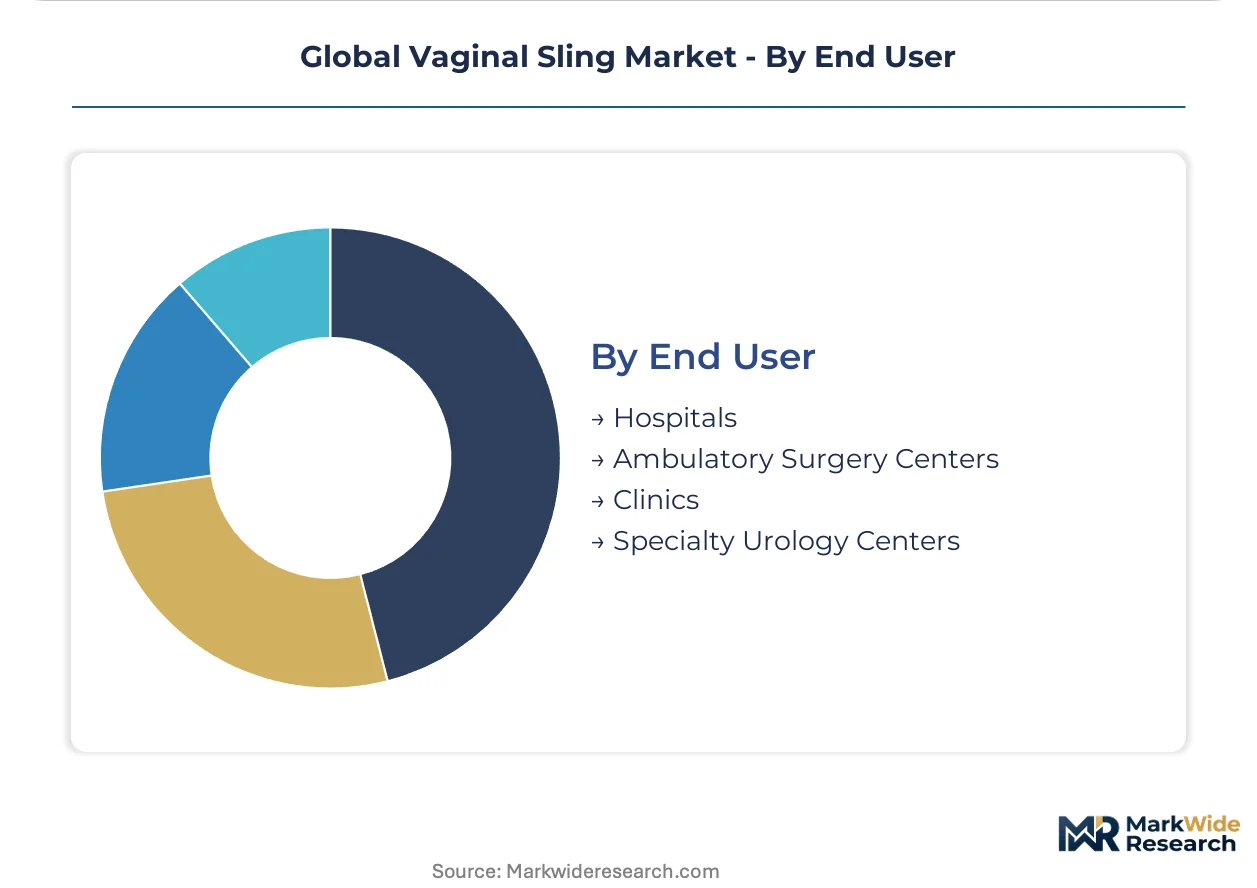
End User:
Facility type dictates purchasing authority structures, procedure volume economics, and device-procedure bundling arrangements.
- Hospitals:Maintain comprehensive pelvic floor service lines with overnight observation capabilities and complex case referral networks. German Klinikum systems and United States academic medical centers anchor volume through fellowship-trained surgeon density and established quality reporting infrastructure.
- Ambulatory Surgery Centers:Freestanding facilities in Florida and Texas are capturing sling cases from hospital outpatient departments through facility fee differentials and streamlined discharge protocols. Group purchasing organizations are consolidating device procurement authority across multi-facility networks.
- Specialty Urology Centers:Concentrate high-volume surgeons with dedicated pelvic floor expertise.
- Clinics:Limited to diagnostic and post-operative follow-up functions in most regulatory environments.
Hospitals lead on scale; ambulatory surgery centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained pelvic floor surgeons concentrate in tertiary referral centers across the United States, Germany, and Japan, anchoring procedure volume and driving technology adoption patterns. These specialized practitioners cluster within academic medical centers and high-volume community hospitals, creating geographic pockets of clinical expertise that sustain market development.
United States
Aging demographics and established Medicare reimbursement pathways sustain stress urinary incontinence procedure volumes, with over 250,000 slings performed annually. FDA 510(k) premarket notification requirements have expanded clinical data burdens for new mesh entrants following 2019 safety communications. Tertiary referral centers in Boston and Cleveland anchor adoption of biologic graft alternatives for revision cases.
Germany
The Klinikum sector maintains comprehensive pelvic floor service lines with established DRG coding for transobturator sling procedures. EU MDR recertification requirements are forcing manufacturers to rebuild regulatory dossiers for legacy polypropylene mesh devices. Specialized day-clinic networks in Bavaria and North Rhine-Westphalia are replicating US ambulatory surgery center models.
Japan
PMDA maintains distinct biocompatibility testing protocols that filter import approvals and create first-mover advantages for compliant manufacturers. Aging demographics and expanding insured populations over age 65 sustain procedure demand. Tokyo and Osaka academic medical centers concentrate fellowship-trained specialists and drive technology evaluation.
Australia
TGA alignment with Health Canada on ISO 10993 biological evaluation standards enables streamlined multinational dossier submissions. Private hospital networks in Sydney and Melbourne dominate procedural volume through specialized urogynecology units. Medicare reimbursement structures favor same-day discharge protocols that accelerate mini-sling adoption.
Canada
Provincial health authorities coordinate centralized purchasing for hospital systems, consolidating device procurement authority. Health Canada maintains stringent biocompatibility evaluation standards aligned with TGA protocols. Toronto and Vancouver academic centers anchor specialist training pipelines and complex case referral networks.
Global Vaginal Sling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the vaginal sling market, creating a tiered structure where scale-driven portfolio breadth confronts targeted clinical depth. Large medical technology conglomerates leverage hospital contracting relationships and cross-category bundling to defend position, while mid-cap specialists compete on surgeon training infrastructure and procedure-specific innovation. Three archetypes dominate: diversified urology portfolio holders, pelvic floor reconstruction specialists, and regional manufacturing champions. Consolidation through strategic acquisitions and vertical integration into medical-grade polymer supply chains represent the dominant competitive vectors reshaping vendor positioning.
Within the diversified portfolio tier, Becton, Dickinson and Company and Boston Scientific Corporation exemplify scale-driven competitors that anchor hospital system relationships across multiple urology product categories. B. Braun Melsungen AG occupies a position among European manufacturing champions with integrated supply chain control over medical-grade monofilament production. These archetypal players represent contrasting strategic postures: portfolio breadth versus manufacturing integration versus specialized clinical depth.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cook Medical LLC |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Caldera Medical, Inc. |
| Boston Scientific Corporation |
| Endo International plc |
| Promedon Group |
| Coloplast A/S |
| Others |
Supply & Pricing Matrix
Fellowship-trained pelvic floor surgeons in the United States, Germany, and Japan command premium procedural fees that compress labor-cost differentials into pricing-tier spreads across synthetic mesh, resorbable polymers, and biologic graft alternatives.
Pricing Analysis
The bundled-vs-unbundled service split separates hospital outpatient department reimbursement from ambulatory surgery center facility-fee models. Three-tier pricing structure across premium biologic grafts, standard polypropylene mesh, and economy mini-sling configurations tracks certification grade and volume scale. Pricing pressure stems from EU MDR recertification costs passing through to procurement budgets. Ambulatory surgery centers exhibit highest price sensitivity; tertiary referral centers in Boston and Cleveland show lowest sensitivity for revision-case materials.
Supply Chain Analysis
Reverse-logistics flows for explanted mesh devices require specialized biohazard handling protocols that add cost layers to tertiary center supply chains. Medical-grade monofilament polypropylene production concentrates in Germany and the United States, with porcine dermis biologics sourcing from controlled herds in Australia and New Zealand. Raw material dependencies rest on petrochemical feedstocks, pharmaceutical-grade collagen processing, and sterilization packaging. Single-source vulnerability in notified body certification capacity creates 14-18 month audit queues. Distribution runs through group purchasing organizations consolidating multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaginal sling market functions as a regulatory compounder where EU MDR Article 54 clinical evaluation requirements force demand for renewed post-market surveillance infrastructure.
For Market Incumbents: To counter EU MDR notified body capacity shortages, anchor hospital system relationships through multi-year service contracts spanning transobturator and mini-sling portfolios. Prioritize backward integration into medical-grade monofilament production to insulate margin structures from petrochemical volatility.
For New Entrants and Emerging Players: Ambulatory surgery centers in Florida and Texas represent the most penetrable buyer archetype. Capture volume through sub-15-minute implantation protocols and same-day discharge certification. Pursue Health Canada-TGA regulatory harmonization to compress multinational launch timelines.
For Investors and Strategic Acquirers: Diversified urology portfolio holders are the most active acquirer in this space, targeting mid-cap specialists with ISO 10993-6 irritation study completion. Five-to-ten year viability hinges on litigation exposure framework evolution. Monitor California, Texas, and Illinois product liability damage award trends as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Article 54 compliance unlocks continued market access for legacy polypropylene mesh devices in Germany and France. |
| Ambulatory Surgery Center Partnership | Group purchasing organization contracts in Florida and Texas consolidate device-procedure bundling authority. |
| Biocompatibility Testing Investment | PMDA-aligned ISO 10993-6 studies create first-mover advantages for Japan market entry. |
| Surgeon Training Infrastructure | Fellowship program partnerships in Boston and Cleveland anchor specialist pipeline control. |
| Biologic Graft Portfolio Expansion | Porcine dermis and human allograft alternatives capture revision-case premiums in tertiary centers. |
Research Methodology
Coverage spans the United States, Germany, Japan, Australia, and Canada, with primary inputs from each market combining interviews with pelvic floor surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA 510(k) filings, EU MDR notified body designations, PMDA approval databases, and CMS Medicare procedure data. Bottom-up and top-down triangulation cross-validates unit-volume estimates against reimbursement claims and manufacturer shipment reports.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material formulation, clinical indication, and facility type, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from logistic diffusion curves fitted to procedure penetration rates and demographic aging trajectories. Forecast inputs incorporate EU MDR transition timelines and ambulatory surgery center capacity expansion plans.
Underlying measurement precision varies by segment; stress urinary incontinence applications carry tighter precision than post-surgical repair given established reimbursement coding. Forecasts reflect assumptions about notified body audit queue resolution and litigation exposure framework stability. Practitioners should monitor EU MDR designated body capacity expansion and pelvic floor surgeon fellowship graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laryngoscopes Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Rectal Catheters Market
Medical Devices
3D Printed Implants Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Blood Warmers Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Medical Device Coating Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Medical Hydrophilic Coatings Market