
 Global Blood Warmer Devices Market | 2026-2036
Global Blood Warmer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Warmer Devices Market Foresight
Aluminum is hardening its position as the preferred heat-exchange substrate in portable blood warmer housings, displacing legacy polymer composites that suffer from thermal fatigue under repeated sterilization cycles. Barkey GmbH & Co. KG leverages its German manufacturing base to dominate European hospital procurement channels for cabinet warming systems. Gentherm Medical anchors North American demand through intensive R&D programs targeting battery-powered field units for military and emergency applications. Stryker Corporation competes across the full technology spectrum, integrating warming modules into broader perioperative workflow platforms.
Blood warmer devices are electromechanical systems designed to raise refrigerated blood products from storage temperature to physiologic range through controlled heat transfer, typically maintaining output temperature between 33°C and 42°C with ±0.5°C precision to prevent hemolysis or thermal injury. Their primary purpose is eliminating hypothermia risk during massive transfusion protocols, surgical blood administration, and neonatal exchange transfusion. Portable warmers command premium positioning in pre-hospital and military segments where mobility constraints override unit economics, while inline warmers sustain higher utilization rates in fixed surgical suites due to seamless integration with infusion pumps. Dry heat technology leads installed base metrics but electrical heating architectures are gaining fastest in new procurement cycles as hospitals prioritize energy efficiency and reduced maintenance overhead.
FDA 510(k) clearance pathways and EU MDR Class IIa designation govern market access, with both frameworks intensifying validation requirements for temperature uniformity across the full flow-rate range. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards add compliance layers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving battlefield medicine protocols and civilian mass-casualty preparedness mandates, as these policy vectors will determine whether procurement prioritizes disposable warming circuits or durable capital equipment with multi-year service contracts.
Market Dynamics
EU MDR Class IIa designation and FDA 510(k) clearance pathways are tightening validation thresholds for temperature uniformity, forcing manufacturers to restructure quality systems and accelerate electrical safety documentation. These dual regulatory pressures are compressing time-to-market for new entrants while rewarding incumbents with dedicated regulatory infrastructure.
Growth Catalysts
- Massive transfusion protocols:Trauma centers and combat support hospitals in the United States are mandating inline warming systems for hemorrhagic shock management, expanding installed base requirements.
- EU MDR compliance deadlines:German and French hospital procurement channels are prioritizing certified warming systems with validated biocompatibility per ISO 10993, creating replacement demand for legacy units.
- Aluminum heat-exchange substrates:Portable warming housings are adopting aluminum cores that withstand repeated autoclave cycles, extending equipment service life in ambulatory surgical settings.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for heat-exchange metals compress margin structures for mid-tier manufacturers without captive supply agreements.
- Supply concentration in German precision machining:Cabinet warming system chassis production clusters in Bavaria and Baden-Württemberg, creating geographic vulnerability to energy cost shocks.
- Disposable circuit substitution threat:Single-use warming sets with integrated heating elements are capturing low-acuity cases, eroding capital equipment attach rates in outpatient clinics.
Strategic Opportunities
- Japan's hospital infrastructure modernization:METI-funded renovation programs in Tokyo and Osaka prefectures are specifying battery-powered field warmers for disaster preparedness stockpiles.
- Convergence of warming and infusion pump control:Integration of thermal regulation software with smart pump architectures is enabling closed-loop transfusion management in high-volume surgical suites.
- Direct-to-hospital digital procurement:Group purchasing organizations in the United States are piloting outcome-based equipment leasing models that unbundle capital expenditure from maintenance contracts.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in IEC 60601-1 electrical safety validation and thermal modeling is concentrating at established manufacturers, constraining R&D expansion.
- Legacy system integration complexity:Retrofitting dry heat warmers into existing perioperative workflows requires custom interface development with proprietary pump communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Warmer Devices Market |
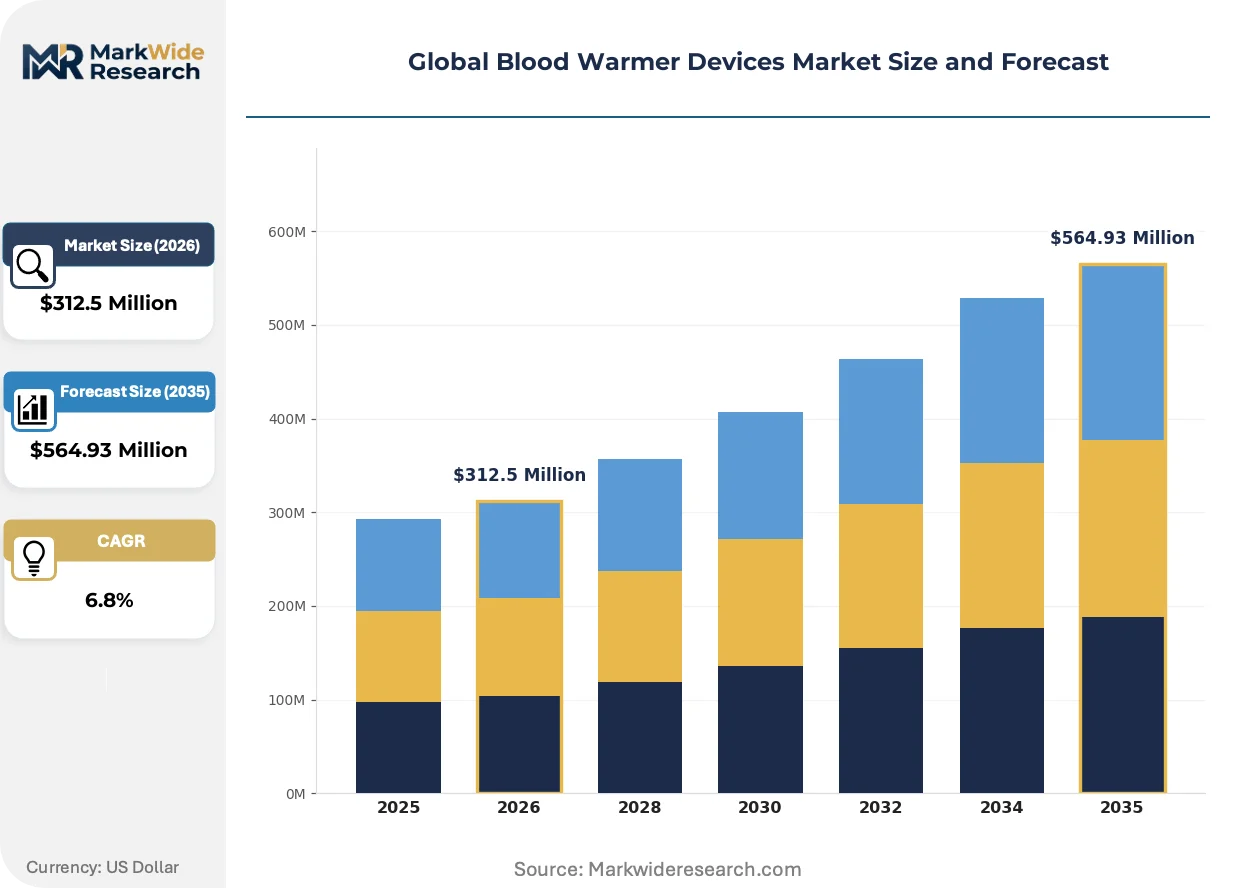
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Warmers, Inline Warmers, Insulated Warmers, Cabinet Warmers, Disposable Warmers Technology: Dry Heat, Water Bath, Electrical Heating, Microwave Heating Application: Emergency Care, Surgical Procedures, Trauma Centers, Neonatal Care End User: Blood Banks, Specialty Clinics, Critical Care Centers, Military Hospitals |
| Companies Covered | Barkey GmbH & Co. KG, Gentherm Medical, 3M, Geratherm Medical, The 37Company, Stryker Corporation, Belmont Medical Technologies, Estill Medical Technologies Inc., ICU Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Warmer Devices Market Shifts & Advancements
Electrical heating architectures are displacing dry heat systems as hospitals prioritize energy efficiency and reduced sterilization maintenance. This transition is reshaping supplier R&D roadmaps and procurement evaluation criteria across surgical, emergency, and military end-use segments.
Electrical heating elements with embedded thermocouple feedback loops are overtaking resistive dry heat coils in new hospital procurements. Surgical suites in Germany and the United States are specifying these systems for their reduced thermal mass and faster ramp-to-temperature performance. The technology is compressing preventive maintenance intervals from quarterly to annual cycles, altering service contract economics for equipment lessors.
EU MDR technical documentation requirements for Class IIa devices are mandating expanded clinical evidence for temperature accuracy claims across full flow-rate ranges. Manufacturers must now submit flow validation data from 10 mL/hour to 500 mL/hour, extending premarket submission timelines. Japanese PMDA is observing these EU developments and tightening alignment inspections for imported warming systems.
Hospital materials management departments are consolidating vendor relationships through integrated perioperative platform contracts rather than standalone equipment purchases. Stryker and Gentherm Medical are capturing these bundled awards by embedding warming modules into broader surgical workflow systems. This concentration is most visible in United States academic medical centers and German university hospital networks.
Global Blood Warmer Devices Market Segmentation
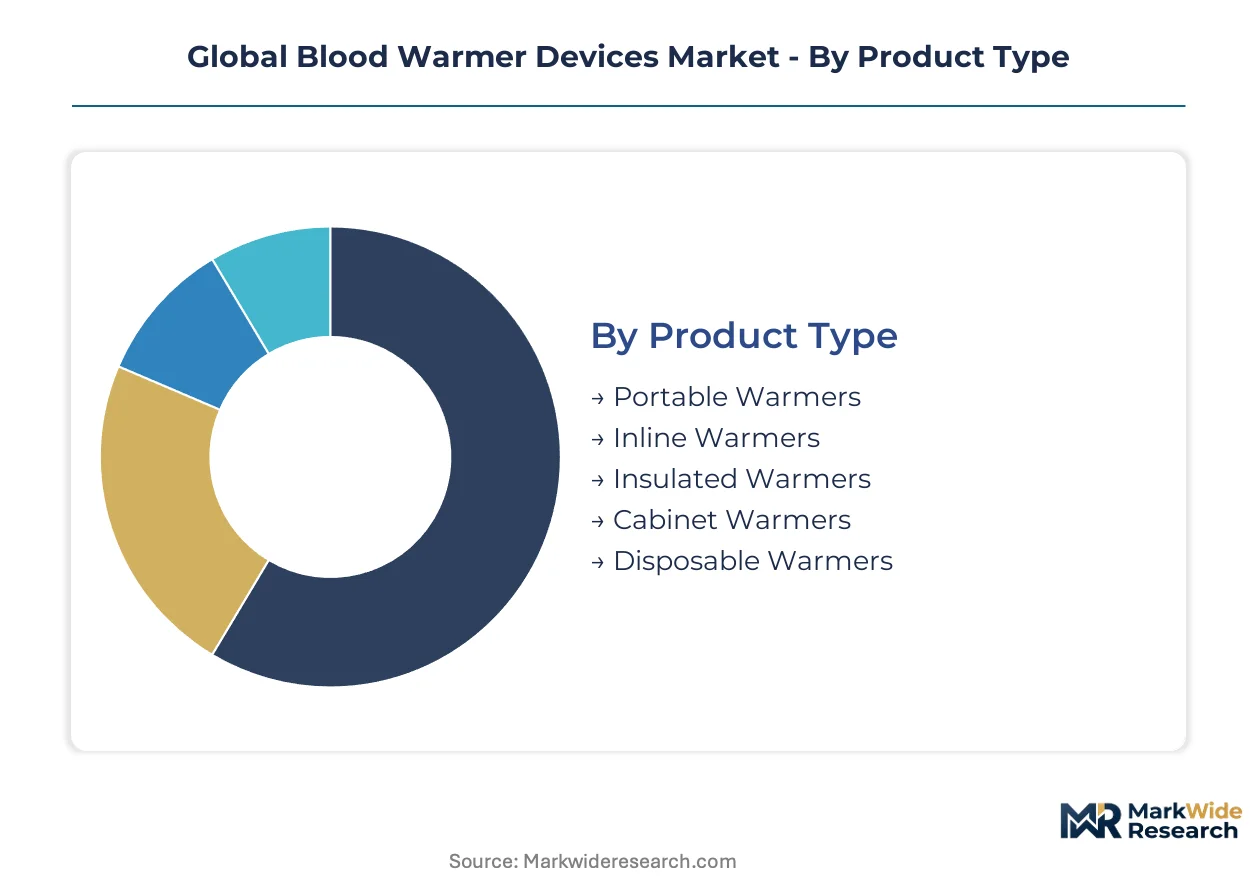
Procurement patterns in blood warmer devices diverge sharply across clinical settings, with mobility requirements and integration depth driving fundamentally different equipment specifications. Hospital materials managers evaluate thermal performance, sterilization durability, and workflow compatibility through distinct lenses depending on whether capital budgets prioritize field deployment or fixed-suite throughput.
Product Type:
Capital allocation cycles determine whether facilities prioritize disposable convenience against multi-year equipment depreciation.
- Portable Warmers:Battery-powered field units with aluminum heat-exchange cores withstand autoclave cycles and repeated transport shock. Military hospitals in the United States and disaster preparedness stockpiles in Japan concentrate procurement for these systems, with METI-funded programs in Tokyo specifying lithium-ion architectures for grid-independent operation.
- Inline Warmers:Seamless infusion pump integration enables closed-loop temperature control across variable flow rates from 10 mL/hour to 500 mL/hour. Trauma centers in Germany and academic medical centers in the United States anchor installed base expansion, driven by massive transfusion protocol mandates for hemorrhagic shock management.
- Insulated Warmers:Passive thermal retention systems suit short-duration transport of refrigerated units to satellite clinics.
- Cabinet Warmers:High-capacity storage systems with precision chamber regulation serve blood bank inventory management.
- Disposable Warmers:Single-use circuits with integrated heating elements capture outpatient clinic cases where capital equipment economics prove unfavorable.
Volume sits with Inline Warmers; growth tilts toward Portable Warmers.
Technology:
Energy efficiency benchmarks and preventive maintenance burdens are restructuring competitive positioning among heating architectures.
- Dry Heat:Resistive coil systems with substantial thermal mass dominate legacy installed bases but require quarterly preventive maintenance cycles. German university hospital networks and United States academic medical centers face replacement pressure as electrical alternatives demonstrate reduced sterilization overhead.
- Electrical Heating:Embedded thermocouple feedback loops deliver faster ramp-to-temperature performance and compress service intervals to annual cycles. Surgical suites in Bavaria and Baden-Württemberg specify these systems for reduced energy consumption, with procurement evaluation criteria prioritizing IEC 60601-1 electrical safety validation.
- Water Bath:Immersion-based systems maintain temperature uniformity through conductive fluid media but impose contamination control protocols.
- Microwave Heating:Electromagnetic energy transfer enables rapid warming but requires precise field control to prevent hemolysis risk.
Installed base concentrates in Dry Heat; expansion tilts toward Electrical Heating.
Application:
Clinical acuity levels determine whether warming systems serve episodic intervention or continuous perioperative integration.
- Emergency Care:Pre-hospital and ambulance-based deployment demands ruggedized housings with rapid battery recharge capability. Emergency medical services in the United States and field medicine protocols for combat support hospitals specify portable architectures with validated performance across environmental temperature extremes.
- Surgical Procedures:Operating room integration requires seamless compatibility with anesthesia workstations and smart pump communication protocols. High-volume surgical suites in German university hospitals and United States academic medical centers prioritize closed-loop thermal regulation software embedded within broader perioperative workflow platforms.
- Trauma Centers:Level I facilities mandate inline warming for massive transfusion protocols with validated flow-rate uniformity.
- Neonatal Care:Exchange transfusion procedures demand precision temperature control within narrow physiologic ranges for vulnerable patient populations.
Utilization concentrates in Surgical Procedures; capability investment tilts toward Trauma Centers.
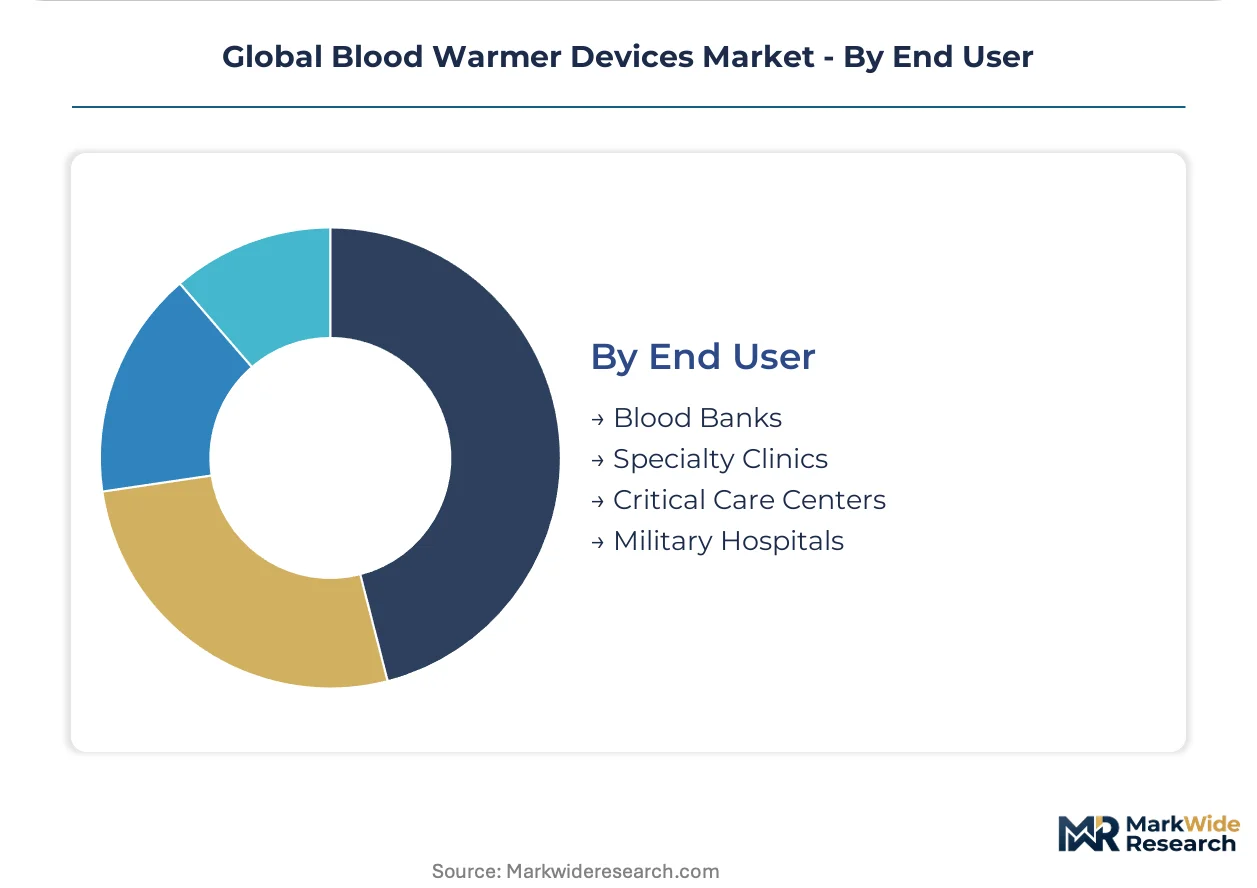
End User:
Procurement authority structures and reimbursement frameworks produce divergent equipment specifications across institutional categories.
- Blood Banks:Inventory management operations prioritize cabinet warming systems with multi-unit chamber capacity and continuous temperature logging for regulatory compliance. German hospital networks and United States regional blood centers specify systems with validated biocompatibility per ISO 10993 and EU MDR Class IIa technical documentation.
- Critical Care Centers:Intensive care units demand inline warming with seamless integration to existing infusion infrastructure. Academic medical centers in the United States and university hospital networks in Germany concentrate procurement for systems with proprietary pump communication protocol compatibility.
- Specialty Clinics:Outpatient settings favor disposable warming circuits to avoid capital expenditure and sterilization infrastructure.
- Military Hospitals:Defense medical treatment facilities specify field-portable units with battery-powered operation and ruggedized transport cases.
Procurement volume concentrates in Blood Banks; capability requirements expand fastest in Military Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Bavaria and Baden-Württemberg concentrate precision machining capacity for cabinet warming system chassis. Hospital infrastructure modernization programs across three continents are accelerating procurement timelines for certified devices.
United States
Level I trauma centers and combat support hospitals mandate inline warming systems for massive transfusion protocols. FDA 510(k) clearance pathways intensify validation requirements for temperature uniformity across full flow-rate ranges. Manufacturing clusters in Minnesota and Massachusetts supply precision thermocouple assemblies to domestic equipment fabricators.
Germany
University hospital networks in Bavaria and Baden-Württemberg specify electrical heating architectures with annual maintenance cycles. EU MDR Class IIa technical documentation requirements compress time-to-market for new entrants. Stuttgart-based precision machining facilities dominate cabinet warming system chassis production for European procurement channels.
Japan
METI-funded hospital renovation programs in Tokyo and Osaka prefectures specify battery-powered field warmers for disaster preparedness stockpiles. PMDA alignment inspections tighten for imported warming systems following EU MDR developments. Nagoya-area electronics manufacturers supply embedded thermocouple feedback components to regional equipment assemblers.
United Kingdom
NHS procurement frameworks prioritize validated biocompatibility per ISO 10993 for blood bank inventory management systems. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. Cambridge biomedical engineering clusters develop thermal regulation software for closed-loop transfusion management platforms.
Global Blood Warmer Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated perioperative platform vendors capturing bundled awards from academic medical centers. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with warming module integration capabilities, German precision engineering specialists dominating European hospital procurement, and North American innovators targeting battery-powered field applications. Competitive dynamics center on regulatory infrastructure scale and M&A activity consolidating perioperative workflow platforms.
Among German precision engineering specialists, Barkey GmbH & Co. KG exemplifies the European hospital procurement anchor archetype through its manufacturing base in North Rhine-Westphalia. Gentherm Medical occupies a position within the North American innovation tier for portable architectures. Stryker Corporation represents the diversified conglomerate archetype integrating warming modules into broader surgical workflow systems. These three entities collectively illustrate how geographic specialization and platform breadth determine competitive positioning across emergency, surgical, and military end-use segments.
| Leading Market Players |
|---|
| Barkey GmbH & Co. KG |
| Gentherm Medical |
| 3M |
| Geratherm Medical |
| The 37Company |
| Stryker Corporation |
| Belmont Medical Technologies |
| Estill Medical Technologies Inc. |
| ICU Medical Inc. |
| Others |
Supply & Pricing Matrix
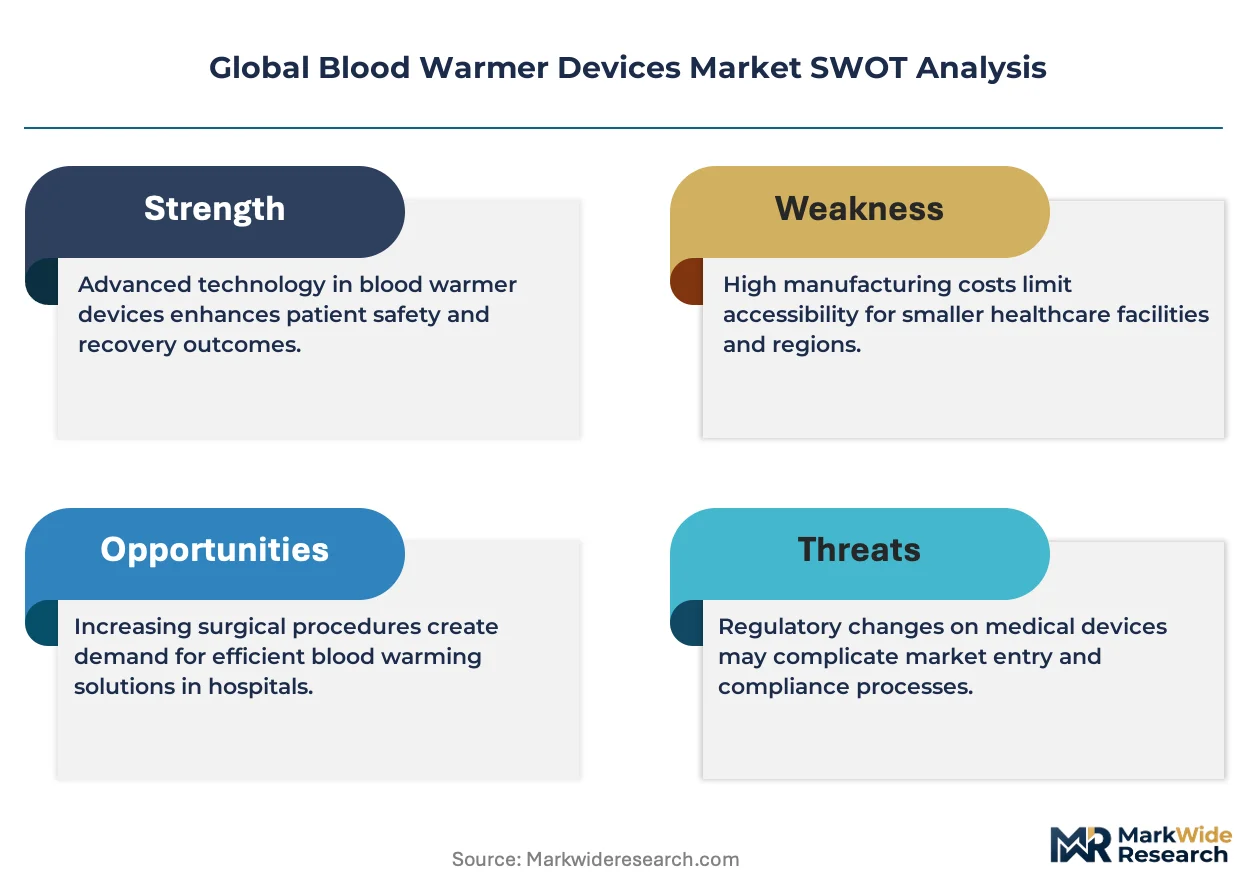
EU MDR Class IIa technical documentation requirements gate qualified supply access and premium-tier pricing power, forcing hospitals to pay compliance premiums for validated warming systems while excluding uncertified manufacturers from procurement channels. This regulatory filter concentrates pricing leverage among established vendors with dedicated regulatory infrastructure, compressing margins for mid-tier competitors without captive certification resources.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with EU MDR-validated inventory ready for immediate deployment, while spot-market units without current certification trade at structural discounts. Three-tier pricing structure across premium, standard, and economy levels differentiates by IEC 60601-1 electrical safety validation depth and ISO 10993 biocompatibility documentation completeness. Cost compression in the economy tier intensifies as disposable warming circuits capture outpatient clinic volume. Blood banks and Level I trauma centers exhibit lowest price sensitivity, prioritizing temperature uniformity guarantees over unit economics.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Bavaria and Baden-Württemberg for cabinet warming system chassis, with regional distribution centers feeding German university hospital networks and re-export channels. Supply draws from precision machining clusters in Germany, thermocouple assembly operations in Minnesota and Massachusetts, and embedded electronics manufacturing in Nagoya-area facilities. Single-source vulnerability concentrates in Stuttgart-based chassis production exposed to energy cost volatility. Distribution runs through hospital group purchasing organizations in the United States and centralized procurement frameworks in German hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR Class IIa designation creates a barrier-to-entry moat, rewarding incumbents with validated quality systems while forcing new entrants to absorb extended premarket submission timelines and clinical evidence costs.
For Market Incumbents: Lock in procurement channel control through multi-year service contracts bundling preventive maintenance with equipment leasing, neutralizing the disposable circuit substitution threat in outpatient settings. Deepen backward integration into aluminum heat-exchange substrate production to insulate margin structures from raw material volatility. Prioritize R&D investment in battery-powered field architectures to capture METI-funded Japanese disaster preparedness programs before competitors establish installed base presence. For New Entrants and Emerging Players: Capture white-space opportunity in military hospital procurement channels where ruggedized portable specifications and rapid battery recharge capability command premium positioning absent entrenched competition. Target pre-hospital emergency medical services in the United States with validated performance across environmental temperature extremes, a segment underserved by fixed-suite-focused incumbents. Pursue direct-to-hospital digital procurement bypassing traditional GPO intermediaries to accelerate customer acquisition. For Investors and Strategic Acquirers: FDA 510(k) clearance backlog expansion is the leading indicator that regulatory infrastructure scale will determine competitive survival, favoring acquisition targets with dedicated quality affairs teams and established 510(k) submission track records. Long-term viability over the next decade rests on convergence capabilities integrating warming modules with smart infusion pump architectures. Monitor PMDA alignment inspection tightening for imported systems as the signal for Japanese market access difficulty inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Validates temperature uniformity claims across 10-500 mL/hour flow rates for German hospital procurement. |
| Battery-Powered Field Architecture Development | Captures METI-funded disaster preparedness stockpiles in Tokyo and Osaka prefectures. |
| Infusion Pump Protocol Integration | Enables closed-loop transfusion management in high-volume surgical suites at academic medical centers. |
| Aluminum Heat-Exchange Substrate Backward Integration | Insulates margin structures from copper and aluminum price volatility compressing mid-tier manufacturers. |
| Direct-to-Hospital Digital Procurement Pilot | Unbundles capital expenditure from maintenance contracts through outcome-based equipment leasing models. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR technical documentation submission volumes, and hospital procurement database entries anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at warming device manufacturers. Secondary validation drew from FDA 510(k) database records, EUDAMED device registrations, hospital capital expenditure disclosures, and ISO 10993 biocompatibility testing documentation. Bottom-up equipment shipment tracking and top-down hospital infrastructure spending analysis provided cross-referenced triangulation.
Input-output matrices modeled demand drivers including massive transfusion protocol adoption rates, ambulatory surgical center expansion, and military field medicine modernization budgets against supply-side constraints in precision machining capacity and thermocouple component availability. Segmentation dimensions spanned product type, heating technology architecture, clinical application setting, and end-user institutional category. CAGRs were derived from slope-log analysis of historical shipment trajectories projected through assumption-weighted scenario modeling. Forecast inputs incorporated EU MDR compliance deadline acceleration effects and Japanese PMDA inspection tightening patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battlefield medicine protocol revisions, civilian mass-casualty preparedness mandate shifts, and raw material price volatility in heat-exchange metals. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Thrombectomy System Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Pectus Bar System Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Robotic Surgical Procedures Market