
 Small Bowel Enteroscopes Market | 2026-2036
Small Bowel Enteroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Small Bowel Enteroscopes Market Analytics
Gastroenterology departments in tertiary hospitals are restructuring their endoscopy suites around single-use and hybrid reusable platforms. Olympus Corporation leverages its dominant installed base of processor towers to sustain recurring consumable revenue across balloon-assisted systems. FUJIFILM Holdings Corporation anchors its position through advanced imaging sensors that differentiate diagnostic yield in obscure gastrointestinal bleeding cases. Medtronic competes via integrated navigation platforms that pair enteroscopy with companion capsule data streams.
Small bowel enteroscopes are elongated flexible endoscopic instruments, typically 200-250 cm in working length with 2.0-2.8 mm instrument channels, designed for diagnostic visualization and therapeutic intervention proximal to the ligament of Treitz. Balloon enteroscopes command the largest revenue pool due to their therapeutic versatility in stricture dilation and polypectomy, while capsule endoscopes represent the fastest-expanding segment driven by ambulatory settings seeking non-sedated alternatives. Wireless capsule endoscopy technology is displacing conventional push enteroscopy in initial diagnostic workups across European and North American outpatient networks.
FDA 510(k) pathways and EU MDR technical documentation requirements are elevating validation costs for reusable instrument channels, pushing manufacturers toward disposable designs. ISO 13485 quality management systems and IEC 60601 electrical safety standards form the baseline compliance architecture for all commercialized systems. Stakeholders must monitor reimbursement parity between capsule and device-assisted enteroscopy as payer formularies increasingly tie coverage to proven therapeutic yield rather than diagnostic completeness alone.
Market Dynamics
Single-use enteroscope platforms are compressing the reusable equipment service cycle, forcing manufacturers to reconfigure revenue models around consumable streams rather than capital equipment leases.
Growth Catalysts
- Aging demographics in Japan and Germany:Crohn's disease prevalence and obscure gastrointestinal bleeding cases sustain procedural volumes in tertiary hospitals.
- FDA 510(k) clearance streamlining:Expedited pathways for disposable instrument channels accelerate time-to-market for novel single-use designs.
- Balloon-assisted therapeutic versatility:Stricture dilation and polypectomy capabilities expand addressable procedures beyond pure diagnostics.
Market Restraints
- EU MDR technical documentation burden:Validation costs for reusable instrument channels have risen substantially, compressing margins for legacy platform holders.
- Supply concentration in Japanese sensor manufacturing:Advanced imaging component sourcing creates vulnerability for non-integrated competitors.
- Wireless capsule substitution:Non-sedated capsule endoscopy displaces conventional push enteroscopy in initial diagnostic workups across outpatient networks.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:United States outpatient facilities seek hybrid reusable-disposable platforms to optimize capital efficiency.
- Navigation-capsule convergence:Integrated platforms pairing device-assisted enteroscopy with companion capsule data streams create differentiated value propositions.
- Japan's reimbursement parity expansion:Payer formulary evolution toward therapeutic yield-based coverage rewards intervention-capable systems.
Industry Challenges
- Gastroenterologist training pipeline constraints:Deep enteroscopy procedural expertise requires specialized fellowship exposure that academic medical centers struggle to scale.
- ISO 13485 quality system maintenance:Disposable platform transitions demand complete revalidation of manufacturing processes and supplier audits.
- Legacy processor tower integration:New single-use designs must maintain backward compatibility with installed visualization infrastructure.
Report Scope
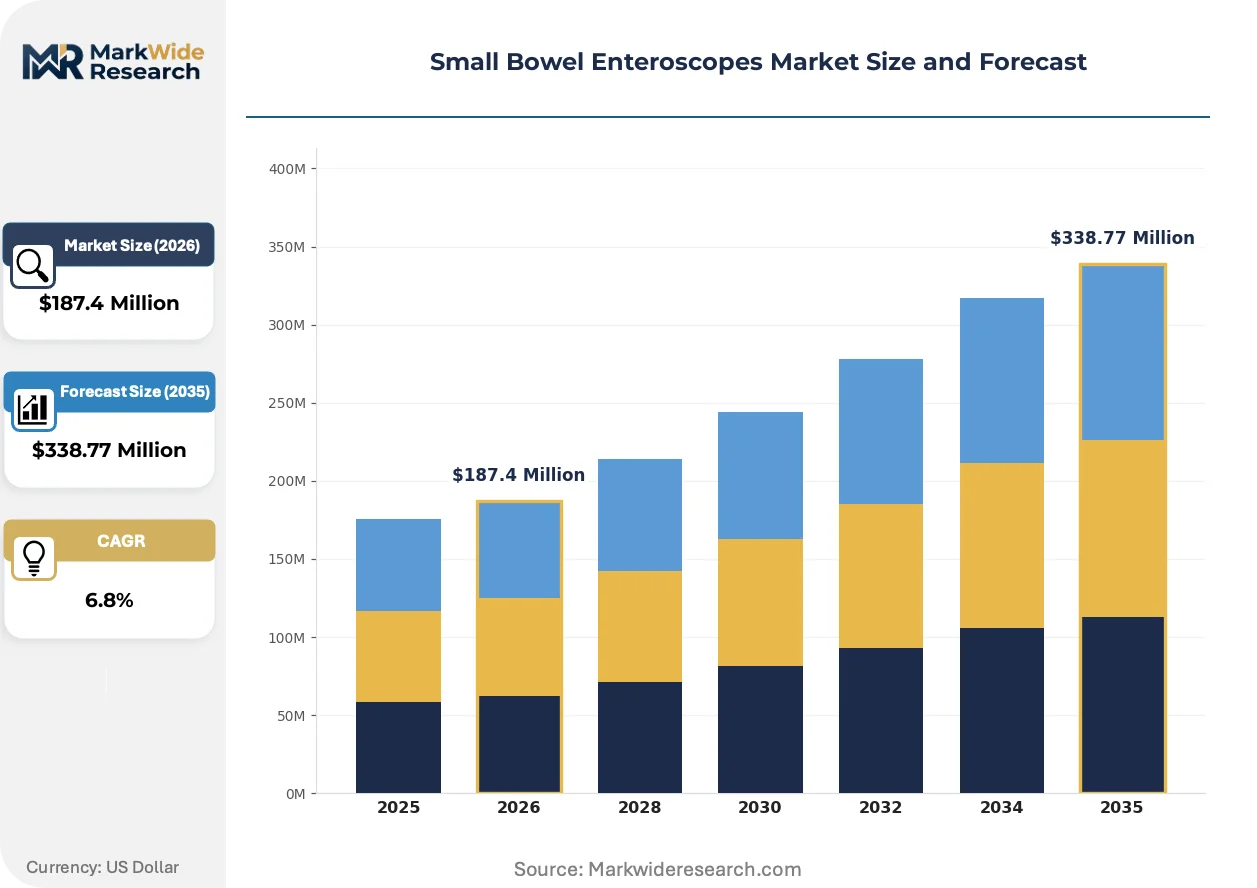
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Bowel Enteroscopes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Enteroscopes, Balloon Enteroscopes, Capsule Endoscopes, Single-Balloon Enteroscopes Technology: Video Endoscopy, Wireless Capsule Endoscopy, Conventional Endoscopy, Digital Endoscopy End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Diagnosis, Therapeutic Procedures, Surveillance, Biopsy |
| Companies Covered | Olympus Corporation, FUJIFILM Holdings Corporation, Medtronic, Pentax Medical, CapsoVision, Inc., IntroMedic Co., Ltd., Chongqing Jinshan Science & Technology (Group) Co., Ltd., AnX Robotica, RF System Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Bowel Enteroscopes Market Evolving Landscape
Disposable platform architectures are rewriting competitive economics across the enteroscopy value chain, compressing traditional capital equipment cycles while elevating sensor and material science differentiation.
Single-use balloon enteroscope systems are electrifying the shift from capital-intensive reusable suites to per-procedure consumable models. Tertiary hospital gastroenterology departments in the United States and Germany are adopting these platforms at accelerating pace to eliminate reprocessing liability and sterilization validation overhead. This transition is electrifying vendor revenue concentration toward high-margin disposable cartridges and away from depreciated equipment leasing arrangements.
EU MDR conformity assessment requirements for reusable instrument channels have tightened biocompatibility and sterility benchmarks beyond prior medical device directive thresholds. Manufacturers now face extended notified body review timelines and enhanced clinical evidence demands for legacy platform renewals. European tertiary hospitals are responding by accelerating procurement evaluations of single-use alternatives that sidestep MDR's reusable channel validation burden entirely.
Hospital purchasing committees are unbundling after-sales service contracts from capital equipment agreements, demanding transparent per-procedure costing and flexible volume commitments. This behavior disrupts traditional multi-year lease structures with comprehensive maintenance inclusion. The pattern is most visible in United States integrated delivery networks seeking to align endoscopy supply costs with value-based reimbursement contracts.
Small Bowel Enteroscopes Market Segmentation
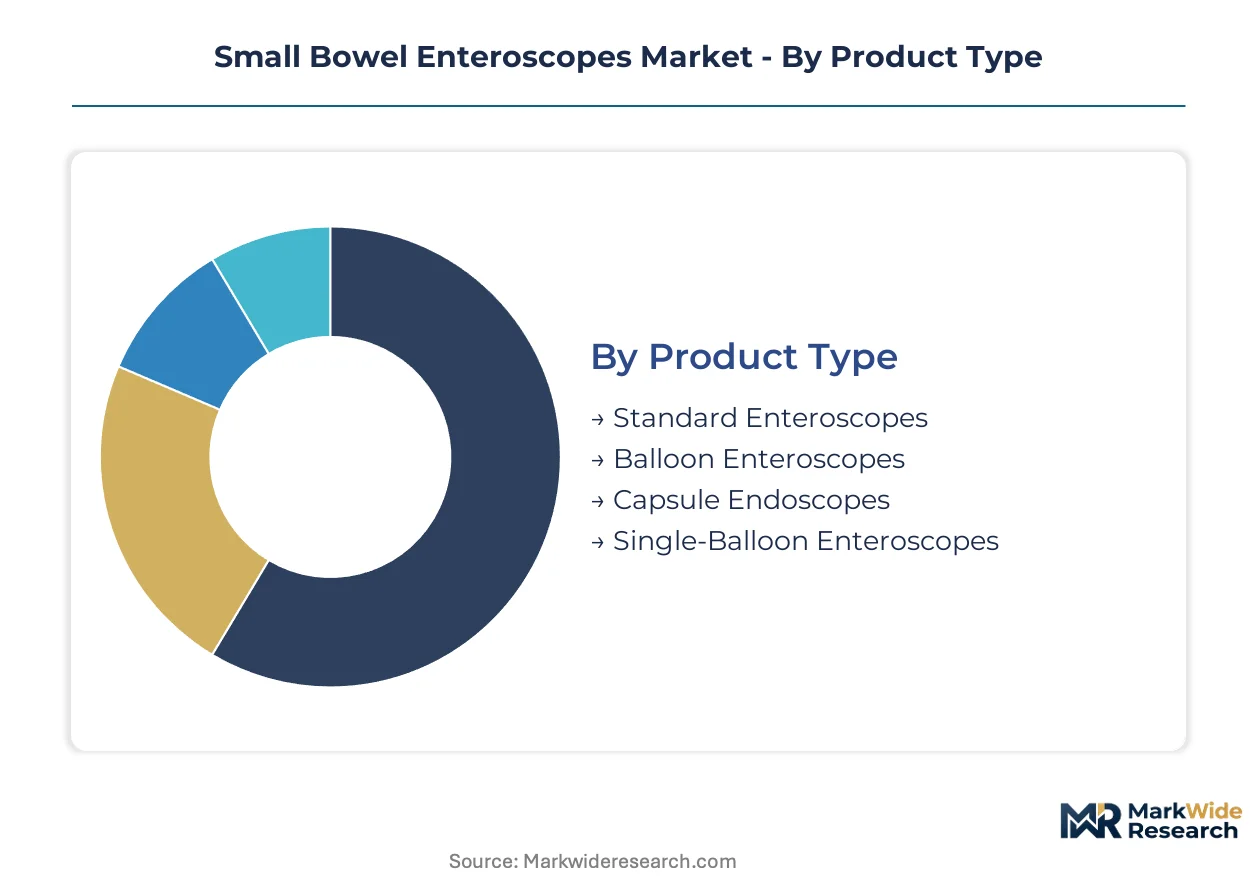
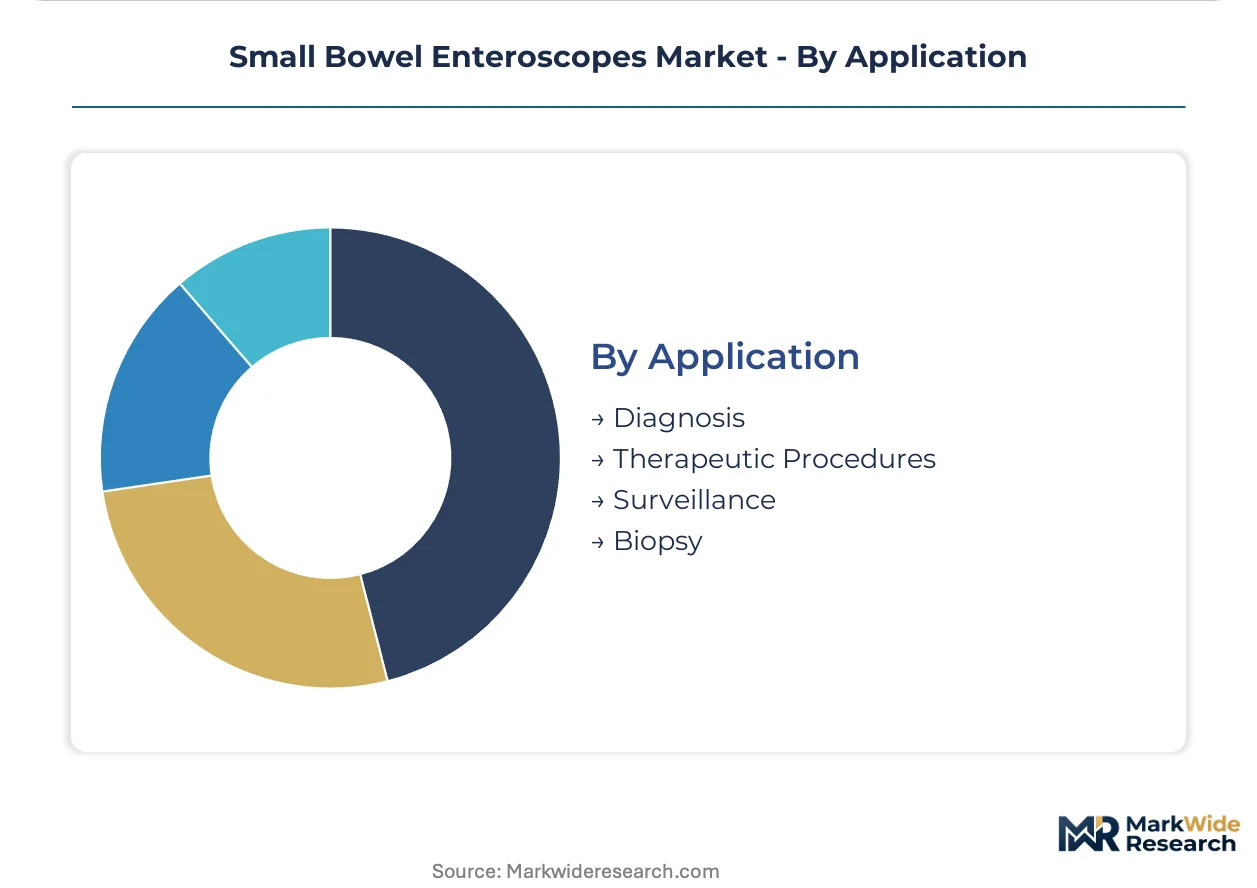
Small bowel enteroscopes fragment across four distinct axes that determine procurement priorities, reimbursement pathways, and vendor competitive intensity. Product type and technology specifications govern capital versus consumable economics, while end-user setting and application dictate workflow integration requirements.
Product Type:
Working length, balloon configuration, and channel diameter specifications separate therapeutic capability from diagnostic-only deployment.
- Balloon Enteroscopes:Dual-balloon and single-balloon systems feature 200-250 cm insertion tubes with 2.0-2.8 mm instrument channels enabling stricture dilation and polypectomy. Tertiary hospitals in Germany and Japan concentrate procurement here due to Crohn's disease procedural volumes and therapeutic reimbursement parity.
- Capsule Endoscopes:Wireless ingestible platforms with CMOS imaging sensors and battery-limited transit capture eliminate sedation requirements entirely. Ambulatory surgery centers across the United States are expanding deployment fastest as outpatient networks seek non-sedated alternatives to conventional push enteroscopy.
- Standard Enteroscopes:Conventional push-type instruments without balloon assistance rely on manual torque and patient position manipulation for ileal intubation.
- Single-Balloon Enteroscopes:Simplified balloon-overtube systems reduce equipment complexity while maintaining therapeutic access compared to dual-balloon architectures.
Mature deployment sits with Balloon Enteroscopes. Newer deployment is concentrated in Capsule Endoscopes.
Technology:
Image acquisition and transmission architectures separate integrated processor-dependent systems from autonomous capsule platforms.
- Wireless Capsule Endoscopy:Self-contained imaging and telemetry systems transmit data to external receivers during natural transit. Diagnostic centers in the United States and European outpatient networks favor this technology for obscure gastrointestinal bleeding workups where sedation avoidance accelerates throughput.
- Video Endoscopy:CCD and CMOS sensor-based platforms deliver high-definition visualization through fiber-optic or digital transmission to processor towers. Japanese tertiary hospitals maintain concentrated installed bases here due to PMDA reimbursement structures favoring therapeutic yield documentation.
- Digital Endoscopy:Fully digital signal processing with enhanced chromoendoscopy and narrow-band imaging capabilities.
- Conventional Endoscopy:Fiber-optic bundles without electronic sensor integration, now largely displaced except in cost-constrained procurement environments.
Procurement committees in integrated delivery networks are unbundling technology selection from processor tower loyalty, elevating standalone platform evaluation.
End User:
Capital intensity, case volume, and regulatory liability exposure separate institutional procurement priorities.
- Hospitals:Tertiary academic medical centers with fellowship-trained gastroenterologists perform complex therapeutic interventions requiring balloon assistance and anesthesia support. These institutions in Japan and Germany sustain the highest per-facility procedural volumes for Crohn's disease and obscure bleeding.
- Diagnostic Centers:Focused outpatient facilities prioritize rapid throughput and capital efficiency. United States ambulatory networks are expanding capsule endoscopy deployment fastest to align with value-based reimbursement contracts.
- Clinics:Community-based practices with limited anesthesia infrastructure concentrate on initial diagnostic workups and referral coordination.
- Research Institutions:Academic centers with NIH or equivalent funding pursue novel imaging modalities and artificial intelligence integration studies.
Revenue concentration remains with Hospitals. Fastest volume expansion is occurring in Diagnostic Centers.
Application:
Reimbursement coding and clinical evidence requirements separate diagnostic from interventional economics.
- Therapeutic Procedures:Balloon dilation, polypectomy, and hemostasis interventions command premium reimbursement tied to therapeutic yield documentation. Japanese payer formulary evolution toward outcome-based coverage specifically rewards these applications.
- Diagnosis:Initial visualization and lesion detection for obscure gastrointestinal bleeding, Crohn's disease staging, and small bowel tumor identification. Capsule endoscopy is displacing conventional push enteroscopy here across European and North American outpatient networks.
- Surveillance:Scheduled monitoring for polyposis syndromes and post-surgical Crohn's disease recurrence detection.
- Biopsy:Tissue acquisition for histopathological confirmation, increasingly paired with advanced imaging for targeted sampling.
Therapeutic yield documentation now determines coverage parity more than diagnostic completeness alone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Special Zones for Structural Reform concentrate tertiary hospital gastroenterology departments, attracting accelerated PMDA reimbursement pathway approvals for therapeutic enteroscopy systems.
United States
Ambulatory surgery centers in Texas and Florida drive fastest capsule endoscopy deployment as value-based reimbursement contracts align outpatient costs with procedural throughput. FDA 510(k) clearance streamlining for disposable instrument channels accelerates single-use platform adoption. The Cleveland Clinic and Mayo Clinic anchor therapeutic balloon enteroscopy training pipelines.
Germany
Crohn's disease prevalence in North Rhine-Westphalia and Bavaria sustains highest European per-capita procedural volumes for stricture dilation interventions. EU MDR technical documentation requirements compress margins for reusable channel manufacturers. Heidelberg and Berlin academic medical centers concentrate deep enteroscopy fellowship programs.
Japan
Aging demographics in Kanto and Kansai regions sustain obscure gastrointestinal bleeding case volumes exceeding other developed markets. PMDA reimbursement parity expansion toward therapeutic yield-based coverage rewards intervention-capable balloon systems. Tokyo and Osaka tertiary hospitals maintain concentrated installed bases of processor-tower-dependent platforms.
China
Domestic CMOS sensor manufacturing in Shenzhen and Shanghai reduces imaging component import dependency for capsule endoscope producers. NMPA regulatory harmonization with international standards accelerates local platform commercialization. Beijing and Guangzhou academic centers pioneer artificial intelligence integration for lesion detection.
Small Bowel Enteroscopes Market Competitive Landscape
Top-tier vendors anchor processor-tower ecosystems, while mid-tier specialists concentrate on disposable cartridge architectures and regional service networks. The competitive structure rewards installed base leverage in Japan and Germany, where hospital purchasing committees prioritize backward compatibility. Three archetypes dominate: integrated imaging conglomerates, single-use platform pure-plays, and navigation-technology integrators. Capacity expansion in Chinese sensor manufacturing and strategic partnerships for capsule-data convergence represent the dominant competitive vectors.
Among Japanese imaging conglomerates, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions exemplifying processor-tower ecosystem dominance, leveraging recurring consumable revenue across balloon-assisted installations. Medtronic anchors the navigation-technology integration archetype, representing convergence strategies pairing device-assisted enteroscopy with companion data streams. These three entities collectively illustrate how competitive positioning stratifies across capital equipment loyalty, disposable platform economics, and software-hardware integration.
| Leading Market Players |
|---|
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| Medtronic |
| Pentax Medical |
| CapsoVision, Inc. |
| IntroMedic Co., Ltd. |
| Chongqing Jinshan Science & Technology (Group) Co., Ltd. |
| AnX Robotica |
| RF System Lab |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up sensor specialists in Japan and South Korea concentrate CMOS imaging component supply, translating into disciplined pricing power for balloon enteroscope manufacturers while forcing non-integrated competitors to absorb premium procurement costs or surrender margin.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to disposable balloon catheter assemblies for United States hospital systems facing urgent case backlogs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapeutic systems from CE-marked diagnostic-only platforms and unbranded refurbished equipment. Pricing pressure stems from EU MDR compliance costs compressing reusable channel margins and forcing legacy vendors toward consumable models. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while Japanese tertiary hospitals prioritize backward compatibility over unit cost.
Supply Chain Analysis
Freight cost volatility from Japanese sensor hubs to German assembly plants has prompted regional buffer inventory strategies among balloon enteroscope manufacturers. Supply concentrates in Japan for CMOS imaging sensors, Germany for precision balloon catheter extrusion, and China for capsule endoscope plastic housings and battery cells. Raw material dependencies include medical-grade silicone for balloon membranes, optical glass fibers for illumination channels, and lithium polymer cells for capsule power systems. Single-source vulnerability sits with Japanese CMOS foundries serving Olympus and FUJIFILM processor-tower ecosystems. Distribution runs through GPO contracts for United States hospital systems, direct sales for Japanese academic medical centers, and regional distributors for European outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained CMOS sensor capacity props pricing discipline across balloon-assisted platforms, with Japanese foundry output limits creating procurement queues that favor incumbents with long-term supply agreements.
For Market Incumbents: Lock in multi-year sensor supply contracts with Japanese CMOS foundries before capacity allocation tightens further. Secure backward compatibility certifications for disposable platforms against installed processor towers to neutralize emerging single-use pure-plays. Defensive priority rests on eliminating reprocessing liability exposure through rapid single-use transition. For New Entrants and Emerging Players: Launch via direct-to-ambulatory-surgery-center distribution models bypassing GPO contract lock-in by incumbent vendors. Target United States diagnostic centers in Florida and Texas where value-based reimbursement contracts reward rapid capsule deployment. White-space concentration sits with AI-integrated lesion detection software companions for existing hardware platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor single-use platform pure-plays with FDA 510(k) clearance momentum but constrained working capital for commercial scale-up, particularly in United States coastal markets. Long-term viability over a five-to-ten year window hinges on reimbursement parity expansion for therapeutic yield documentation. Signal to monitor: PMDA formulary evolution toward outcome-based coverage for intervention-capable systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Expedited pathways for disposable designs accelerate time-to-market for novel single-use balloon platforms. |
| Hospital System Partnership | Integrated delivery networks in Texas demand transparent per-procedure costing and flexible volume commitments. |
| Software Companion Development | AI lesion detection algorithms paired with capsule data streams create differentiated diagnostic yield propositions. |
| Reimbursement Strategy | Payer formulary evolution toward therapeutic yield-based coverage rewards intervention-capable balloon systems in Japan. |
| CE Marking Pathway | EU MDR technical documentation requirements compress margins for reusable channel manufacturers seeking legacy renewals. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contract databases, and FDA 510(k) filing records underwrites the qualitative findings on procurement pattern shifts. Primary fieldwork engaged gastroenterology department heads, biomedical engineering directors, and ambulatory surgery center administrators across tertiary hospitals in Japan, Germany, and the United States. Secondary validation drew from CMS Medicare reimbursement data, PMDA formulary bulletins, and EU MDR notified body guidance documents. Bottom-up procedural volume estimates triangulated against top-down equipment shipment data from Japanese and German trade associations.
Rate-of-change decomposition across product type, technology architecture, end-user setting, and application separates volume growth from price-mix effects over the projection horizon. Segmentation modeling incorporated working length specifications, balloon configuration, channel diameter, and regional reimbursement cluster variations. CAGRs were derived from fitted trend extrapolation adjusted for regulatory approval timelines and hospital capital budget cycles. Forecast inputs included Crohn's disease prevalence trajectories, ambulatory surgery center expansion rates, and EU MDR transition compliance deadlines.
Regulatory approval delays, reimbursement parity reversals, and CMOS sensor supply disruptions are the dominant revision risks that could compress or extend modeled growth trajectories. Forecasts reflect documented assumptions about procedural volume sustainability and vendor transition timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Nurse Call Systems Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Contact Lenses Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Asia-Pacific Medical Suction Device Market