
 Adult Water Flosser Market | 2026-2036
Adult Water Flosser Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Water Flosser Market Insights
The capital-intensity divergence between countertop and cordless specialists is unwinding as scale advantages consolidate among full-line producers. Koninklijke Philips N.V. leverages integrated manufacturing across personal care divisions to sustain margin resilience in pulsating technology variants. Waterpik anchors its position through deep channel control in professional dental settings, while Panasonic Holdings Corporation competes on miniaturization expertise for travel-format devices.
An adult water flosser is a powered oral hygiene device that directs a pressurized stream of pulsated water between teeth and below the gumline, typically operating at 10–100 psi with flow rates of 300–800 mL per minute to disrupt plaque biofilm and reduce gingival inflammation. Countertop units with reservoir capacities exceeding 600 mL dominate volume sales in North American households, while cordless formats with lithium-ion batteries are capturing faster expansion in European and Asian urban apartments where counter space constrains adoption. The orthodontic patient end-user segment concentrates premium pricing power, as bracket-specific tip designs command higher attachment rates than standard jet tips.
The FDA regulates adult water flossers as Class I medical devices in the United States, requiring establishment registration and device listing without premarket notification for most configurations, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for claims related to periodontal disease prevention. ISO 9001 quality management and IEC 60335 electrical safety standards shape supplier qualification criteria for retail pharmacy channels. Stakeholders must monitor how evolving dental professional society guidelines on adjunctive mechanical plaque control influence reimbursement positioning and direct-to-consumer marketing claims.
Market Dynamics
Orthodontic patient protocols are consolidating purchase authority into dental clinics, redirecting consumer-grade demand toward professional-channel specifications and compressing direct-to-consumer margin structures.
Growth Catalysts
- Post-treatment protocol integration:Dental clinics in Germany embed water flossers into orthodontic discharge procedures, creating institutional pull-through for prescription-grade devices.
- Preventive reimbursement alignment:German statutory health insurance frameworks classify certain oral care devices as reimbursable preventive expenditures, reducing out-of-pocket friction for patients.
- Lithium-ion miniaturization:Advances in battery energy density enable cordless units to achieve countertop-equivalent pressure outputs, expanding adoption in space-constrained urban apartments.
Market Restraints
- Pump motor cost volatility:Rare earth magnet price fluctuations in Chinese processing facilities squeeze margins for pulsation mechanism manufacturers.
- Reservoir polymer supply concentration:Medical-grade ABS and polycarbonate production clusters in East Asia create single-source vulnerability for European device assemblers.
- Water pressure standard fragmentation:Divergent psi ceiling requirements between FDA Class I guidelines and EU MDR clinical evidence thresholds force dual-SKU strategies.
Strategic Opportunities
- Travel-format white space:Japanese business travelers and compact-living urbanites in Seoul demonstrate unmet demand for sub-200-gram cordless units with USB-C charging.
- Periodontal disease prevention claims:EU MDR Article 10 clinical evidence pathways, if successfully navigated, would unlock pharmacy channel placement and professional endorsement.
- Subscription tip replenishment:Direct-to-patient consumable models bypass retail margin extraction while capturing lifetime value from orthodontic patient cohorts.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for new tip materials extends product development cycles by 14-18 months.
- Cross-border warranty fulfillment:Divergent electrical safety certifications (IEC 60335 variants) complicate unified inventory pools for multi-market distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Water Flosser Market |
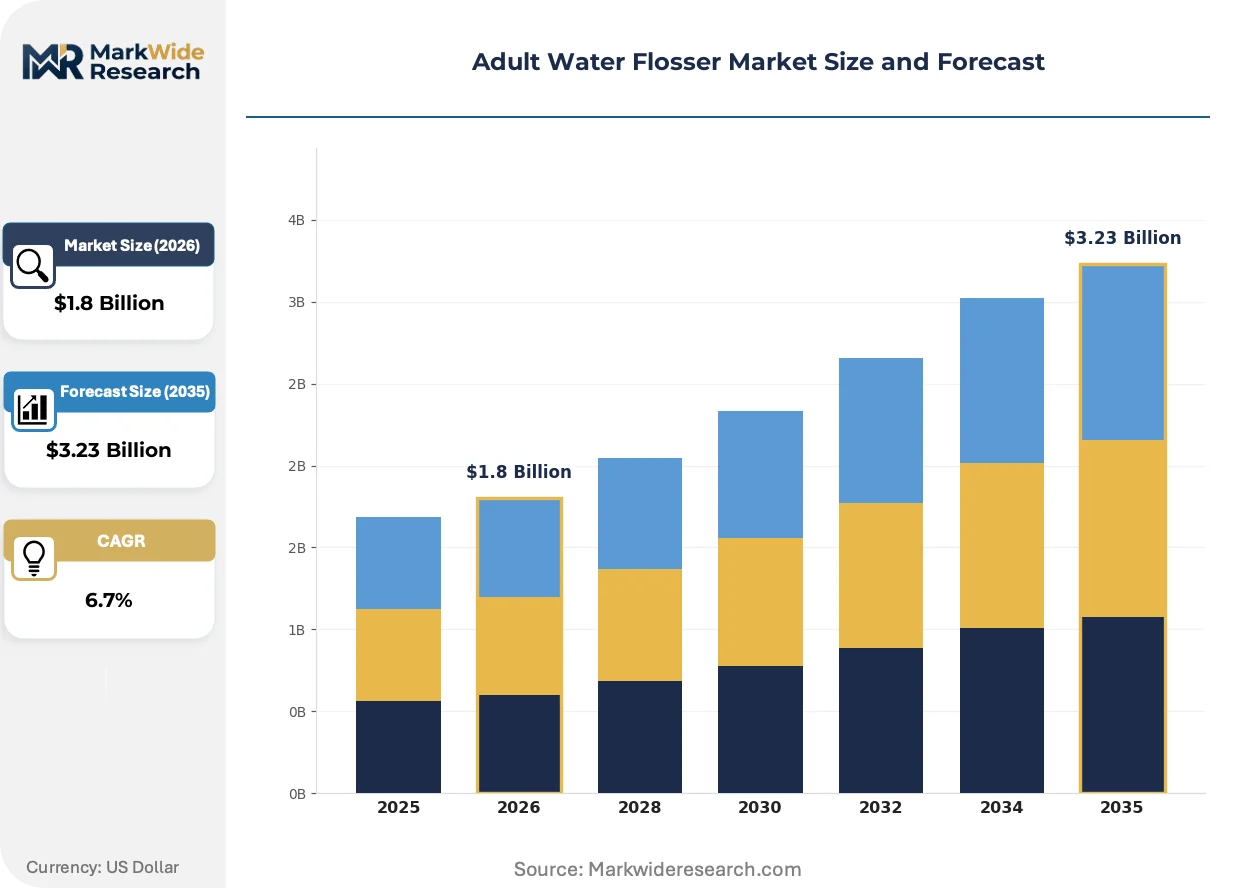
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Cordless, Travel, Shower Technology: Pulsating, Oscillating, Dual Function, LED End User: Adults, Seniors, Orthodontic Patients, Diabetics Distribution Channel: Retail Stores, E-commerce, Pharmacies, Direct Sales |
| Companies Covered | Church & Dwight Co., Inc., Koninklijke Philips N.V., Panasonic Holdings Corporation, The Procter & Gamble Company, Conair LLC, Waterpik, Oratec Corp., Jetpik Global, Inc., Oral-B, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Water Flosser Market Trends and Innovations
Miniaturization pressure from urban housing constraints is compressing form factor preferences while regulatory divergence between major markets forces parallel development tracks.
Magnetic levitation pump mechanisms are displacing traditional piston-driven architectures in premium cordless segments. Orthodontic practices in Seoul and Tokyo specify these units for patient home-care kits due to noise reduction below 55 decibels. The technology is displacing legacy diaphragm pumps across the 75-100 psi performance tier, collapsing the historical trade-off between portability and clinical efficacy.
The EU Medical Device Regulation's Article 10 clinical evidence requirements for periodontal disease prevention claims impose stricter substantiation thresholds than FDA Class I listing procedures. Manufacturers targeting European pharmacy channels must commission prospective studies with gingival index endpoints, adding €200,000-400,000 to market entry costs. German and French distributors now demand pre-submitted MDR technical documentation before listing negotiations.
Subscription-based tip replenishment models are capturing orthodontic patient cohorts who prioritize compliance over upfront cost. Dental clinics in Munich and Hamburg bundle 12-month consumable plans with device dispensing, replacing retail pharmacy purchases. This pattern concentrates most visibly in Germany's statutory insurance reimbursement corridors, where preventive device budgets reduce patient price sensitivity.
Adult Water Flosser Market Segmentation
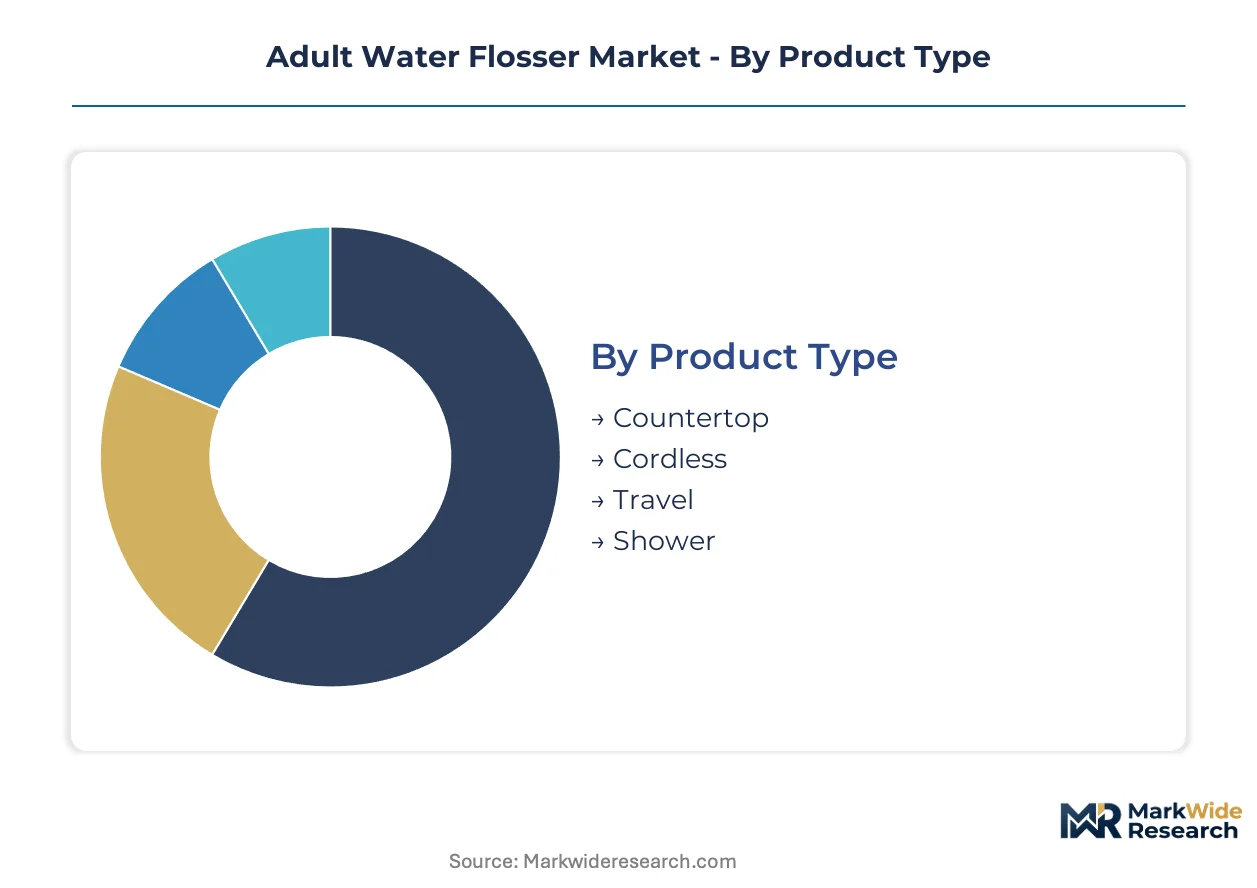
Orthodontic discharge protocols and urban housing constraints create divergent demand profiles across product formats. Each segment faces distinct substitution pressures from traditional string floss, interdental brushes, and professional cleaning services.
Product Type:
Countertop units face the strongest substitution threat from cordless alternatives as lithium-ion energy density closes the pressure-output gap.
- Countertop:Reservoir capacities exceeding 600 mL deliver sustained 10-100 psi output for multi-user households. Demand concentrates in US suburban homes where counter space is abundant and family-size reservoirs reduce refill frequency.
- Cordless:Lithium-ion battery architectures now achieve countertop-equivalent pressure in sub-500-gram form factors. German and South Korean urban apartments drive fastest adoption where bathroom square footage constrains permanent fixture installation.
- Travel:Sub-200-gram units with USB-C charging target Japanese business travelers and Seoul compact-living demographics.
- Shower:Waterproof housings with wall-mount brackets integrate into existing plumbing fixtures for wet-environment usage.
Countertop retains volume leadership; cordless holds the steepest expansion curve.
Technology:
Cost-tier stratification separates premium magnetic levitation mechanisms from commodity piston-driven alternatives.
- Pulsating:Pressure modulation at 1,200-1,600 pulses per minute disrupts subgingival biofilm with documented gingival index improvement. FDA Class I and EU MDR pathways both recognize this mechanism for preventive claims.
- Oscillating:Rotating jet streams sweep across broader surface areas for full-mouth coverage in reduced time. European pharmacy channels favor these units for patient compliance in periodontal maintenance protocols.
- Dual Function:Switchable pulsation-oscillation modes command premium positioning in orthodontic practice dispensing.
- LED:Integrated illumination assists visibility for posterior tooth targeting in aging user demographics.
Pulsating technology dominates installed base; oscillating gains share fastest in professional-channel specifications.
End User:
Application-specific requirements fragment procurement authority between retail self-selection and clinical prescription.
- Adults:General preventive use represents the broadest addressable population with lowest per-unit pricing tolerance.
- Seniors:Arthritis-friendly grip designs and reduced dexterity requirements drive demand in Japan's aging demographic clusters.
- Orthodontic Patients:Bracket-specific tip geometries with tapered filament arrays command premium attachment rates. Munich and Hamburg dental clinics bundle these with 12-month consumable subscriptions under German statutory insurance preventive budgets.
- Diabetics:Periodontal disease prevention claims carry elevated clinical evidence requirements under EU MDR Article 10 for this risk population.
Adults retain volume leadership; orthodontic patients hold the steepest expansion curve.
Distribution Channel:
Channel margin structures compress as institutional procurement consolidates purchase authority.
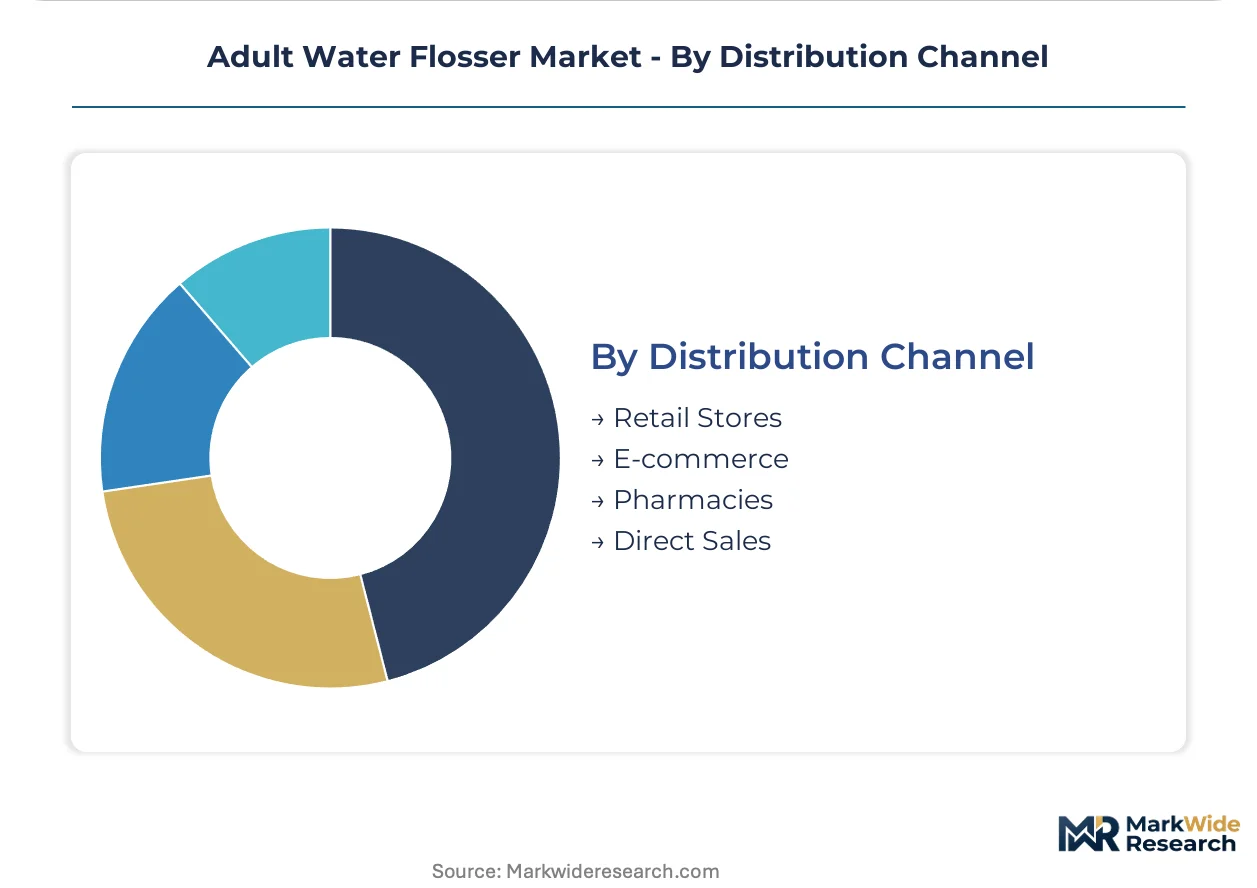
- Retail Stores:Mass merchandisers and specialty oral care chains stock standard jet-tip configurations with highest inventory turnover velocity.
- E-commerce:Direct-to-consumer platforms capture price-sensitive comparison shoppers with subscription tip replenishment attachment.
- Pharmacies:German and French pharmacy channels demand pre-submitted EU MDR technical documentation before listing negotiations for periodontal prevention claims.
- Direct Sales:Dental clinic dispensing bypasses retail margin extraction while capturing lifetime consumable value from orthodontic patient cohorts.
Retail stores retain volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's statutory insurance corridors while cost-sensitive volume accumulates in China's manufacturing clusters. This asymmetry redirects investment toward reimbursement-aligned product specifications in Western Europe and efficiency-optimized production in East Asia. The divergence shapes regional go-to-market strategies across the forecast window.
United States
Suburban household density and multi-user reservoir demand sustain countertop unit dominance. FDA Class I medical device registration requirements elevate compliance costs for new entrants. Dallas-Fort Worth distribution clusters handle bulk retail channel fulfillment for mass merchandisers.
Germany
Statutory health insurance preventive device budgets reduce patient price sensitivity for prescription-grade units. EU Medical Device Regulation Article 10 clinical evidence thresholds filter pharmacy channel access. Munich and Hamburg dental clinics bundle subscription tip replenishment with orthodontic discharge protocols.
China
Urban apartment space constraints accelerate cordless format adoption in tier-one cities. NMPA medical device classification aligns with international safety benchmarks for export-oriented manufacturers. Shenzhen electronics clusters supply magnetic levitation pump components to premium cordless assemblers.
Japan
Aging demographic arthritis limitations drive ergonomic grip design specifications. METI energy efficiency guidelines shape lithium-ion battery selection for domestic market units. Tokyo and Osaka metropolitan dental associations specify noise-reduced units for patient home-care compliance.
South Korea
Compact urban bathroom dimensions favor miniaturized cordless architectures. MFDS medical device quality management requirements parallel EU MDR documentation standards. Seoul orthodontic practices specify magnetic levitation mechanisms for premium patient kit dispensing.
Adult Water Flosser Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated personal care conglomerates commanding premium positioning and specialized oral hygiene firms anchoring professional-channel penetration. The market structure stratifies across three tiers: full-line manufacturers with cross-divisional manufacturing scale, dental-focused specialists with clinic dispensing relationships, and component-assembly specialists serving private-label retailers. Archetypes include pulsation technology innovators, miniaturization-focused cordless developers, and professional-channel protocol integrators. Competitive moves concentrate on M&A to secure pump mechanism suppliers and strategic partnerships with orthodontic practice networks.
Among integrated personal care conglomerates, Koninklijke Philips N.V. and Panasonic Holdings Corporation occupy positions spanning consumer electronics and oral hygiene divisions, representing scale-driven archetypes with cross-category manufacturing infrastructure. Waterpik sits within the dental-specialist tier, exemplifying professional-channel anchoring through clinic protocol integration. These three companies illustrate the competitive structure's divergence between diversified technology platforms and focused clinical positioning.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Koninklijke Philips N.V. |
| Panasonic Holdings Corporation |
| The Procter & Gamble Company |
| Conair LLC |
| Waterpik |
| Oratec Corp. |
| Jetpik Global, Inc. |
| Oral-B |
| Others |
Pricing and Supply Chain Analysis
FDA Class I medical device registration requirements in the United States simultaneously gate supplier qualification and stratify price tiers, as manufacturers absorbing compliance costs extract premiums for prescription-grade configurations while commodity assemblers compete on standard jet-tip variants with thinner margins.
Pricing Analysis
Configured-to-order pricing for orthodontic-specific tip geometries commands spreads exceeding standard countertop units by significant multiples, with bracket-specific filament arrays and subscription bundling as primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade stratification, where EU MDR Article 10 clinical evidence thresholds filter pharmacy channel access at the top tier. Cost compression in cordless segments is intensifying because lithium-ion battery commoditization collapses performance premiums. Orthodontic patient cohorts under German statutory insurance coverage exhibit lowest price sensitivity, while direct-to-consumer retail shoppers demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpiling of medical-grade ABS and polycarbonate resins dominates European assembler preferences, whereas East Asian manufacturers favor just-in-time component flows from Shenzhen electronics clusters. Pump mechanism production concentrates in China, South Korea, and Japan, with rare earth magnet processing facilities in Chinese industrial zones feeding magnetic levitation architectures. Supply chain risk rests on single-source vulnerability for pulsation mechanism subassemblies, as qualified secondary sources require ISO 9001 and IEC 60335 recertification cycles. Distribution runs through Dallas-Fort Worth logistics hubs for North American retail fulfillment and Munich-Hamburg corridors for European pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA Class I and EU MDR certification timelines erect barriers that incumbent specialists exploit against unqualified entrants.
For Market Incumbents: Secure captive supply arrangements for rare earth magnet processing to insulate margin structures from Chinese facility price volatility. Deepen channel control through orthodontic practice dispensing relationships in Germany's statutory insurance corridors, preempting retail margin erosion from direct-to-consumer platforms.
For New Entrants and Emerging Players: Lead with travel-format miniaturization targeting Japanese business travelers and Seoul compact-living demographics, where sub-200-gram USB-C architectures face minimal incumbent saturation. Pursue white-label pharmacy channel placement in France and Germany by pre-submitting MDR technical documentation before listing negotiations.
For Investors and Strategic Acquirers: EU MDR Article 10 clinical evidence pathway completion reshapes the acquisition landscape toward premium-positioned targets with pharmacy channel access. Long-term viability favors device-assemblers with backward integration into pump mechanism production. Watch magnetic levitation patent portfolio depth as inflection indicator for technology leadership consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Clinical Evidence Investment | Unlocks pharmacy channel placement in Germany and France for periodontal prevention claims. |
| Orthodontic Practice Dispensing Partnership | Bypasses retail margin extraction while capturing lifetime consumable subscription value. |
| Magnetic Levitation Pump Mechanism Development | Displaces legacy diaphragm architectures in premium cordless segments below 55 decibels. |
| Subscription Tip Replenishment Model | Concentrates patient compliance value in Munich and Hamburg clinic networks. |
| Rare Earth Magnet Supply Security | Insulates margin structures from Chinese processing facility price volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dental clinic procurement managers, orthodontic practice owners, biomedical engineers at device manufacturers, and GPO contracts administrators; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for pump mechanism components. Bottom-up unit economics triangulated against top-down market sizing across product format, technology mechanism, end-user application, and distribution channel dimensions.
Across the analysis window, growth trajectories derived from orthodontic patient cohort expansion, urban housing constraint penetration rates, and reimbursement policy alignment in target geographies. Segmentation modeling incorporated product type, pulsation technology tier, end-user clinical indication, and channel procurement authority. Forecast inputs included lithium-ion energy density improvement curves, dental professional society guideline evolution, and statutory insurance preventive device budget allocations.
Forecasts assume regulatory continuity in FDA Class I and EU MDR regimes; material policy shifts would require re-modeling. Revision becomes warranted when rare earth magnet supply disruptions or MDR clinical evidence threshold modifications cross material impact thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Organ Care Market
Medical Devices
Global Veress Needle Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Global Disposable Medical Sensors Market