
 US Assisted Living Facility and Neurorehabilitation Market | 2026-2036
US Assisted Living Facility and Neurorehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
US Assisted Living Facility and Neurorehabilitation Market Intelligence
CMS Five-Star Quality Rating System certification is bifurcating the competitive landscape into operators that meet federal staffing and clinical thresholds versus those falling behind. Brookdale Senior Living leverages its national footprint to sustain occupancy rates across diverse facility types. NeuroRestorative anchors its position through specialized post-acute brain injury programs that differentiate it from generalist competitors. Moody Neurorehabilitation Institute dominates the Texas corridor with physician-led rehabilitation protocols.
US assisted living and neurorehabilitation encompasses residential care settings combined with therapeutic interventions for neurological recovery, typically integrating licensed nursing oversight with individualized therapy plans targeting functional independence. These facilities operate under state-level licensure requirements that mandate minimum staffing ratios, clinical documentation standards, and building safety codes for vulnerable populations. Memory Care and Skilled Nursing segments capture the deepest margin pools due to higher acuity care needs and specialized staffing requirements. Cognitive Rehabilitation within neurorehabilitation methods shows the fastest trajectory as payers recognize cost offsets from reduced hospital readmissions. Independent Living remains the most mature segment with compressed margins and consolidation pressure.
FDA oversight of neurorehabilitation medical devices intersects with CMS reimbursement policies and state Department of Health facility inspections to create a multi-layered compliance environment. OSHA workplace safety standards and HIPAA privacy requirements add operational complexity that favors scaled operators with dedicated compliance infrastructure. Stakeholders must monitor evolving Medicaid waiver programs and Medicare Advantage penetration rates to anticipate reimbursement shifts that will reshape site-of-care economics.
Market Dynamics
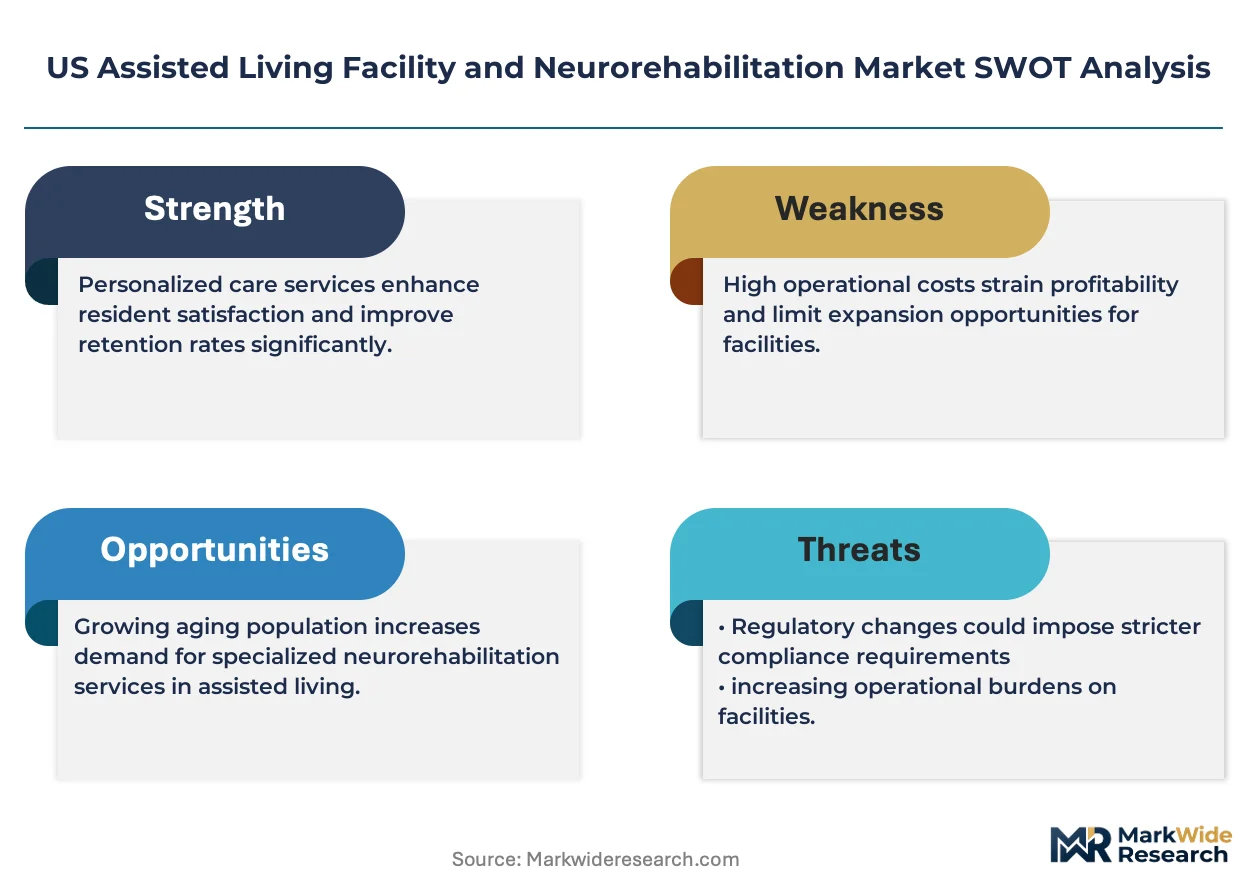
CMS value-based bundled payment mandates are compressing site-of-care economics and forcing post-acute providers to integrate neurorehabilitation services directly into assisted living campuses rather than referring out to acute hospitals.
Growth Catalysts
- Medicaid 1915(c) Waivers:State-level home and community-based services waivers now cover assisted living costs for neurorehabilitation patients, expanding addressable populations beyond private-pay seniors.
- Robotic Gait Training:FDA-cleared exoskeleton systems for stroke recovery are reducing therapist labor intensity while improving functional outcomes, accelerating adoption in Texas and Florida corridors.
- Sun Belt Migration:Retiree relocation to Arizona, Texas, and Florida is concentrating demand for facilities combining residential care with on-site neurological therapy.
Market Restraints
- Registered Nurse Labor Scarcity:Persistent shortages of licensed RNs with neurorehabilitation specialization are inflating wage costs and capping bed expansion timelines.
- Medicaid Reimbursement Compression:State budget pressures are freezing or cutting per-diem rates for assisted living services, squeezing margin pools in lower-acuity segments.
- Real Estate Cost Escalation:Construction and land acquisition expenses in metropolitan Sun Belt markets are extending facility payback periods beyond investor thresholds.
Strategic Opportunities
- Medicare Advantage Penetration:MA plans covering 50%+ of Medicare beneficiaries in Florida and Arizona are creating bundled payment contracts that reward integrated post-acute networks.
- Telehealth-Enabled Remote Monitoring:HIPAA-compliant video platforms are allowing neurorehabilitation specialists to serve rural assisted living facilities without on-site presence.
- Memory Care-Neurorehabilitation Hybrid Models:Co-locating dementia care with stroke recovery programs captures higher-acuity patients and commands premium pricing from private-pay families.
Industry Challenges
- Interstate Licensure Barriers:Physical therapists and speech-language pathologists face state-specific credentialing requirements that block rapid staffing scale-ups across multi-state operators.
- EHR Interoperability Gaps:Fragmented electronic health record systems between acute hospitals, skilled nursing facilities, and assisted living operators impede care coordination and bundled payment reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Assisted Living Facility and Neurorehabilitation Market |
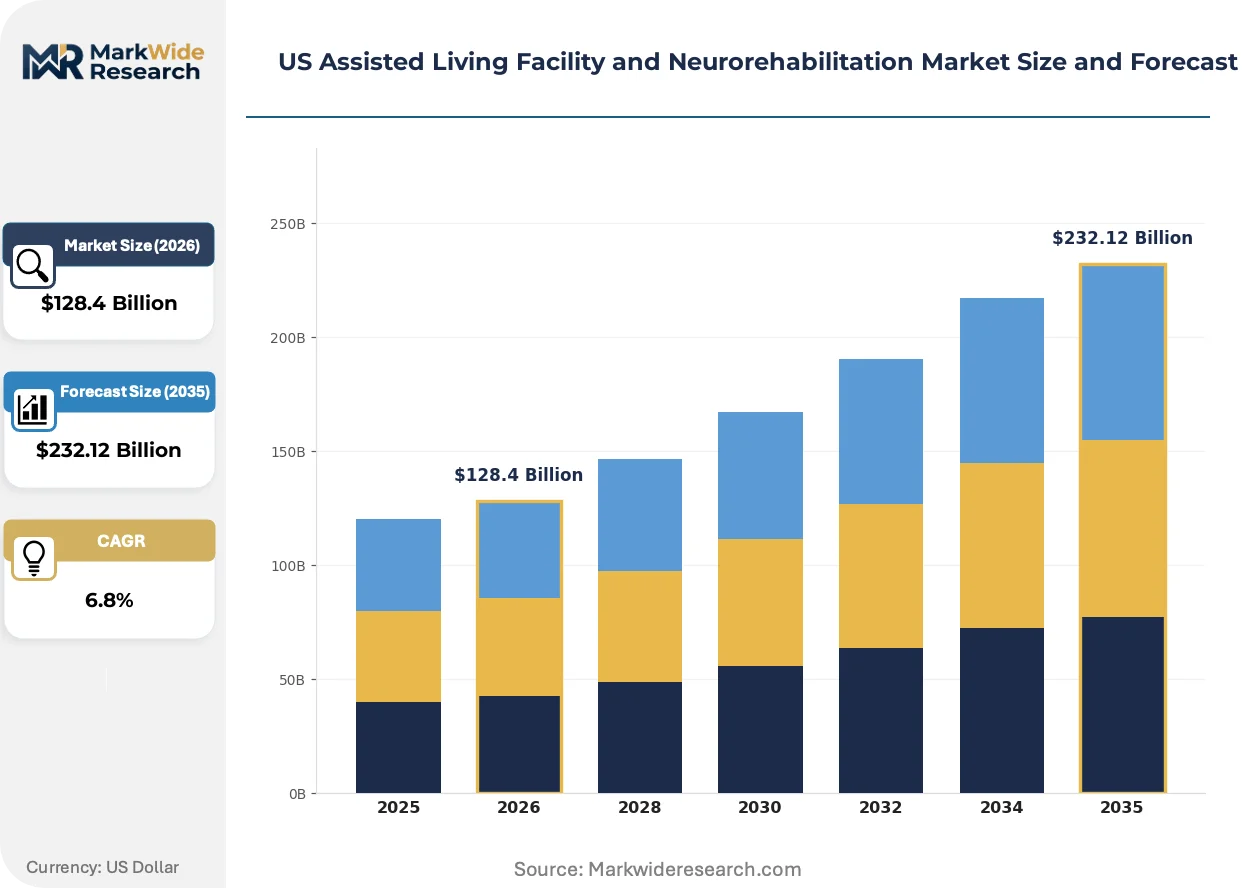
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $232.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Independent Living, Memory Care, Skilled Nursing, Long-Term Care Neurorehabilitation Method: Occupational Therapy, Physical Therapy, Speech Therapy, Cognitive Rehabilitation Service Duration: Short-Term, Long-Term, Respite Care, Transitional Support Client Focus: Elderly, Stroke Survivors, Alzheimer's Patients, Traumatic Brain Injury |
| Companies Covered | Centre For Neuro Skills, Mary Lee Foundation, NeuroRestorative, The MENTOR Network, Pate Rehabilitation, ResCare, Inc., Texas NeuroRehab Center, Moody Neurorehabilitation Institute, Brookdale Senior Living, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Assisted Living Facility and Neurorehabilitation Market Strategic Shifts & Innovations
Technology convergence and reimbursement redesign are dismantling traditional boundaries between residential care and clinical rehabilitation, creating new operational models that blur facility types.
Non-invasive brain stimulation devices using transcranial magnetic stimulation protocols are fragmenting the neurorehabilitation service delivery model. Post-acute providers in Texas and Florida are deploying portable TMS units within assisted living common areas, enabling daily therapy sessions without transporting residents to hospital outpatient departments. This decentralization is compressing the addressable market for traditional hospital-based neurorehabilitation clinics while expanding margin capture for integrated residential operators.
CMS Five-Star Quality Rating System recalibration is elevating staffing transparency requirements and tying Medicare Advantage contract eligibility to published nurse-to-resident ratios. Facilities in the US must now report daily staffing hours by credential type, with sub-4-star ratings triggering exclusion from preferred provider networks. Memory care and skilled nursing segments are responding by accelerating licensed nurse recruitment and deploying scheduling optimization software to maintain threshold compliance.
Family decision-making for post-acute placement is migrating from physician referral dependence toward direct consumer research and Medicare Advantage plan directory navigation. Adult children in Sun Belt states are comparing CMS star ratings, state inspection reports, and neurorehabilitation outcome claims through online platforms before contacting facilities. This channel shift is elevating reputation management and digital transparency investments above traditional hospital discharge coordinator relationship-building for census growth.
US Assisted Living Facility and Neurorehabilitation Market Segmentation
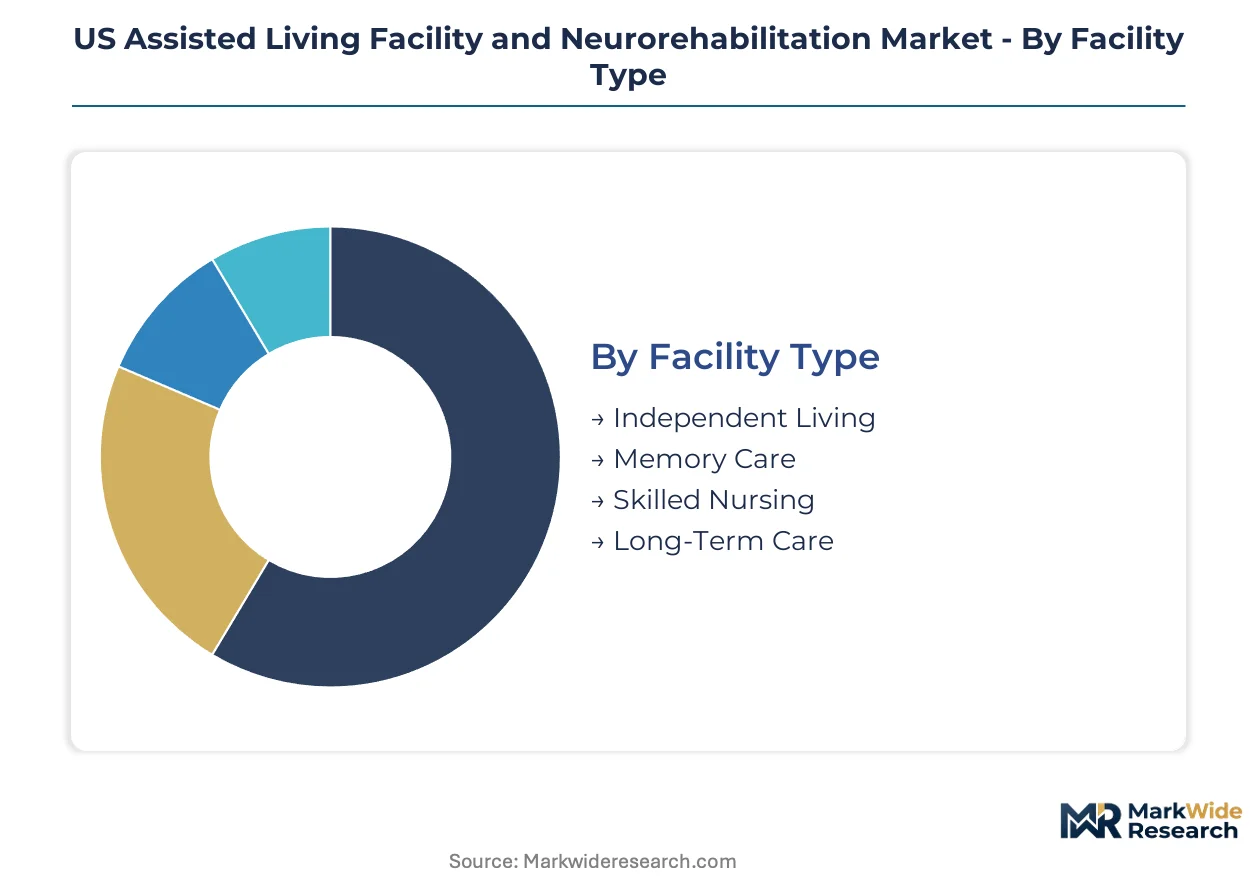
Segmentation in the US assisted living and neurorehabilitation market reveals how substitution pressures from home-based care and hospital outpatient services reshape competitive boundaries across facility types and therapeutic modalities. Understanding these divisions exposes where integrated operators capture margin premiums versus where fragmentation erodes pricing power.
Facility Type:
Home health agencies and hospital-at-home programs pose the most acute substitution threat to lower-acuity facility types, forcing residential operators to embed clinical services that justify premium pricing over domiciliary alternatives.
- Independent Living:Residential settings without licensed nursing oversight target functionally independent seniors seeking community amenities and maintenance-free housing. Demand concentrates in Arizona and Florida metropolitan corridors where retirees prioritize lifestyle amenities over clinical proximity, though compressed margins from property tax escalations and amenity inflation pressure operator economics.
- Memory Care:Secured environments with specialized staffing ratios and environmental design for dementia progression management command the deepest margin pools across facility types. Texas and Florida operators report strongest census growth as Alzheimer's prevalence climbs among aging Sun Belt migrants, with private-pay families absorbing 40-60% cost premiums over standard assisted living.
- Skilled Nursing:Medicare-certified facilities delivering 24-hour licensed nursing care and post-acute rehabilitation occupy the highest regulatory scrutiny tier. CMS Five-Star thresholds and staffing transparency mandates favor scaled operators with compliance infrastructure.
- Long-Term Care:Medicaid-dominant settings for chronic medical needs face persistent reimbursement compression from state budget pressures, constraining capital renewal cycles and quality investments.
Skilled Nursing retains volume leadership across institutional bed counts; Memory Care holds the steepest expansion curve as acuity thresholds rise and private-pay capacity deepens.
Neurorehabilitation Method:
Cost tier differentiation separates labor-intensive manual therapies from technology-augmented modalities that reduce per-session therapist hours while improving outcome metrics.
- Physical Therapy:Gait training, balance restoration, and mobility recovery protocols constitute the highest-volume neurorehabilitation service line. Robotic exoskeleton deployment in Texas corridor facilities reduces therapist labor intensity by 30-40% for stroke survivors while accelerating functional milestone achievement.
- Cognitive Rehabilitation:Structured interventions targeting memory, attention, and executive function recovery show the fastest trajectory as Medicare Advantage plans recognize hospital readmission reduction value. Florida operators integrating computerized cognitive training with therapist oversight report strongest payer contract differentiation.
- Occupational Therapy:Activities of daily living retraining focuses on functional independence in self-care and home management tasks. Demand correlates with stroke survivor discharge volumes from regional acute hospital networks.
- Speech Therapy:Swallowing and communication rehabilitation addresses aphasia and dysphagia post-neurological injury. SLP staffing scarcity across Sun Belt states limits service expansion despite clinical need concentration.
Physical Therapy retains volume leadership across neurorehabilitation encounters; Cognitive Rehabilitation is climbing the fastest as value-based contracts reward outcome efficiency.
Service Duration:
Customer type stratification separates episodic post-acute recovery from chronic disease management, with distinct reimbursement mechanics and margin profiles governing each duration band.
- Short-Term:Post-acute rehabilitation episodes spanning 20-100 days align with Medicare Part A skilled nursing benefits and bundled payment windows. Arizona and Texas facilities with hospital discharge coordinator relationships capture preferred placement status for orthopedic and stroke recovery cases.
- Long-Term:Chronic residential care extending beyond 100 days transitions to Medicaid or private-pay funding mechanisms. Florida operators report longest average lengths of stay among Sun Belt states due to retiree migration patterns and family proximity decisions.
- Respite Care:Temporary relief services for family caregivers operate on per-diem private-pay basis with limited insurance penetration. Demand spikes correlate with holiday periods and family caregiver burnout cycles.
- Transitional Support:Bridge services between acute discharge and permanent placement placement coordinate home modifications and community resource linkage. Medicare Advantage plans in Florida and Arizona are piloting expanded coverage for these services to reduce institutional readmissions.
Long-Term retains volume leadership across resident-days; Transitional Support is gaining share fastest as Medicare Advantage penetration deepens and site-of-care economics shift.
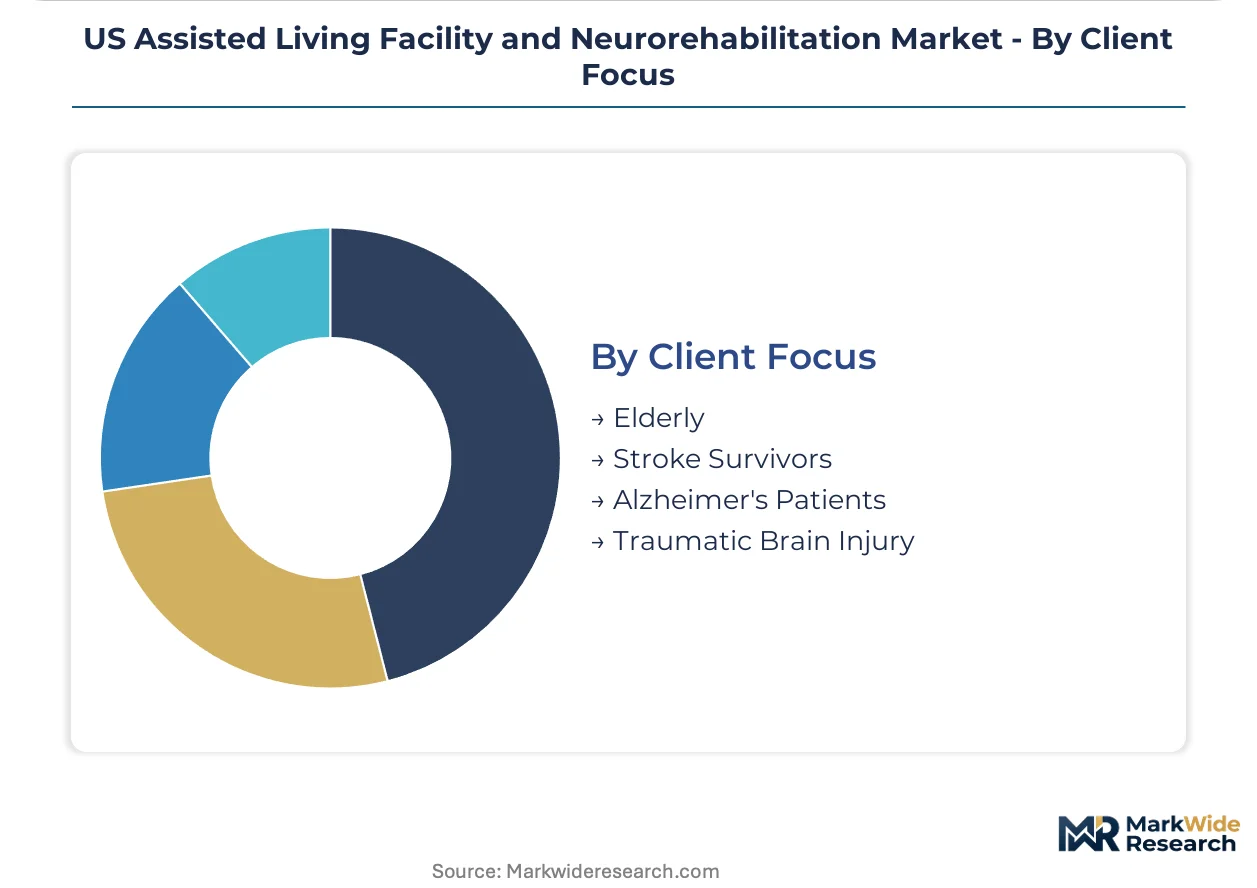
Client Focus:
Application-specific acuity levels determine staffing ratios, regulatory oversight intensity, and pricing power across client populations.
- Elderly:General geriatric population with functional decline but without specific neurological diagnosis represents the broadest addressable base. Independent living and standard assisted living settings in Arizona retirement corridors concentrate this demand.
- Stroke Survivors:Ischemic and hemorrhagic stroke recovery patients require intensive multidisciplinary rehabilitation during 90-day post-event windows. Texas medical center adjacency drives concentration of specialized neurorehabilitation capacity for this population.
- Alzheimer's Patients:Progressive dementia care demands secured environments and behavioral management specialization. Memory care construction in Florida exceeds all other Sun Belt states as prevalence rates climb among relocated retirees.
- Traumatic Brain Injury:Acquired brain injury from falls, vehicle accidents, and assaults requires specialized post-acute programs with neurobehavioral expertise. NeuroRestorative and similar specialized operators dominate this niche with dedicated TBI program infrastructure.
Elderly retains volume leadership across resident census; Stroke Survivors is expanding most quickly as population aging and cardiovascular disease prevalence drive incidence rates higher.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway system and Texas Medical Center rail spurs underpin patient transport corridors linking acute hospitals to post-acute facilities across Sun Belt states. State Medicaid waiver expansions and Medicare Advantage penetration rates vary sharply by sub-region, creating divergent site-of-care economics.
Texas
Stroke survivor volumes from Houston's medical center cluster drive neurorehabilitation bed demand. CMS Five-Star staffing transparency mandates accelerate licensed nurse recruitment in Dallas-Fort Worth corridors. Moody Neurorehabilitation Institute anchors physician-led rehabilitation protocols in the Austin-San Antonio corridor.
Florida
Retiree migration concentrates demand for memory care-neurorehabilitation hybrid facilities in Tampa and Orlando metros. State Medicaid 1915(c) waiver expansions broaden assisted living eligibility for neurorehabilitation patients. Brookdale Senior Living sustains occupancy rates across diverse facility types in Southeast Florida.
Arizona
Independent living construction in Phoenix and Tucson retirement corridors faces compressed margins from property tax escalations. Medicare Advantage plans covering over half of beneficiaries create bundled payment contract opportunities. NeuroRestorative positions specialized post-acute brain injury programs to capture higher-acuity patients.
California
OSHA workplace safety standards and HIPAA privacy requirements add operational complexity favoring scaled operators with compliance infrastructure. Real estate cost escalation in metropolitan markets extends facility payback periods. Interstate licensure barriers for physical therapists block rapid staffing scale-ups across multi-state operators.
US Assisted Living Facility and Neurorehabilitation Market Key Industry Players
Listed leaders compete with private specialists across reimbursement contract access and compliance infrastructure scale. The competitive landscape bifurcates between operators meeting federal staffing and clinical thresholds versus those falling behind. Three archetypes dominate: national footprint diversified operators, specialized neurorehabilitation program operators, and regional physician-led rehabilitation institutes. Dominant competitive moves include Medicare Advantage network contracting and robotic gait training technology deployment.
Among specialized program operators, NeuroRestorative and Moody Neurorehabilitation Institute exemplify differentiated positioning through dedicated post-acute brain injury infrastructure. Brookdale Senior Living represents the national footprint archetype leveraging scale for compliance infrastructure and occupancy stability. These three anchors illustrate how reimbursement rule shifts toward value-based bundled payments reward integrated service line expansion.
| Leading Market Players |
|---|
| Centre For Neuro Skills |
| Mary Lee Foundation |
| NeuroRestorative |
| The MENTOR Network |
| Pate Rehabilitation |
| ResCare, Inc. |
| Texas NeuroRehab Center |
| Moody Neurorehabilitation Institute |
| Brookdale Senior Living |
| Others |
Cost & Logistics Intelligence
Ninety-day staffing pipeline lead-times for licensed neurorehabilitation nurses now dictate both occupancy economics and payer contract eligibility across Sun Belt facilities, binding supply chain fragility directly to pricing power compression in Medicare Advantage negotiations.
Pricing Analysis
Volume-discount tiering structures separate CMS Five-Star rated operators from sub-threshold competitors, with premium tiers commanding 15-25% rate multiples through bundled payment contracts. Price differentiation hinges on staffing ratio transparency and robotic therapy deployment scale. Pricing pressure stems from Medicaid per-diem rate freezes in Texas and Florida, squeezing margin pools in lower-acuity segments. Private-pay families in memory care show lowest price sensitivity, while Medicaid-dependent long-term care residents face constrained choice sets.
Supply Chain Analysis
Domestic RN pipeline bottlenecks constitute the critical chokepoint, with Texas and Florida nursing schools producing insufficient neurorehabilitation specialists to match bed expansion timelines. Equipment sourcing draws from German exoskeleton manufacturers, Japanese robotic gait trainers, and domestic FDA-cleared TMS device fabricators. Single-source vulnerability concentrates in specialized SLP staffing agencies across Arizona metropolitan corridors. Distribution runs through regional GPO contracts linking hospital discharge coordinators to preferred post-acute networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed neurorehabilitation nurse scarcity now exceeds robotic therapy technician gaps as the binding constraint on census growth, forcing operators to compete on compensation premiums rather than capital deployment alone.
For Market Incumbents: Fortify Medicare Advantage network positioning through CMS Five-Star rating maintenance and robotic gait training deployment in Texas corridor facilities. Acquire specialized SLP staffing capabilities to preempt service line gaps as stroke survivor volumes climb. Channel control through hospital discharge coordinator relationships remains the critical defensive lever against home health substitution. For New Entrants and Emerging Players: CMS certification fast-track programs in Arizona and Florida offer lowest regulatory barrier entry for memory care-neurorehabilitation hybrid models. White-space concentrates in rural telehealth-enabled remote monitoring services where specialist scarcity blocks incumbent coverage. Go-to-market angle should target Medicare Advantage plan direct contracting rather than hospital referral dependence. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-capture play because Sun Belt retiree in-migration trends show structural persistence independent of cyclical factors. Acquisition targets should display physician-led rehabilitation protocols and existing bundled payment contracts. Watch Medicaid 1915(c) waiver expansion velocity as the signal for addressable market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Gait Training Deployment | FDA-cleared exoskeleton systems reduce therapist labor intensity while accelerating stroke survivor functional milestone achievement. |
| CMS Five-Star Rating Investment | Staffing transparency compliance secures Medicare Advantage preferred provider network eligibility and bundled payment access. |
| Telehealth Platform Integration | HIPAA-compliant video systems extend neurorehabilitation specialist reach to rural facilities without on-site presence requirements. |
| Memory Care-Neurorehabilitation Hybrid Development | Co-located dementia and stroke recovery programs capture higher-acuity patients and command private-pay premium pricing. |
| SLP Staffing Pipeline Construction | Speech-language pathologist recruitment programs address Sun Belt scarcity that limits service expansion despite clinical need concentration. |
Research Approach
Findings reconcile primary fieldwork against secondary review of CMS Medicare cost reports, state Department of Health facility inspection databases, and GPO contract filings, combining interviews with post-acute care executives, licensed nursing directors, Medicare Advantage plan contracting officers, and neurorehabilitation device procurement managers. Bottom-up bed count and encounter volume estimates triangulate against top-down reimbursement flow analysis.
Segmentation dimensions modeled encompass facility type, neurorehabilitation method, service duration, and client acuity level across the projection horizon. CAGRs derive from trend extrapolation of CMS reimbursement rule shifts, Medicaid waiver expansion trajectories, and Sun Belt demographic migration patterns. Forecast inputs incorporate robotic therapy adoption curves and staffing ratio compliance thresholds.
Underlying assumptions cover Medicare Advantage penetration ceilings and state Medicaid waiver stability, with deviation risk concentrated in RN labor supply shocks and construction cost escalation in metropolitan Sun Belt markets. Practitioners should keep alternative scenarios live as CMS value-based payment recalibration and interstate licensure harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market