
 Germany Artificial Organs and Bionics Market | 2026-2036
Germany Artificial Organs and Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Artificial Organs and Bionics Market Foresight
Leasing arrangements for high-cost cardiac assist devices is fragmenting the competitive landscape for capital-constrained providers. Medtronic PLC leverages its Berlin-based European headquarters to sustain close relationships with German cardiac centers. Berlin Heart GmbH anchors its position through specialized ventricular assist device manufacturing within Germany.
Artificial organs and bionics encompass electromechanical and biohybrid systems designed to replace or augment impaired physiological functions, with cardiac assist devices typically incorporating magnetically levitated rotors and biocompatible polymers to achieve hemocompatibility thresholds below 10 mg/dL plasma-free hemoglobin. These technologies serve critical therapeutic purposes in heart failure treatment, renal failure support, and hearing restoration where biological function has deteriorated beyond pharmaceutical intervention. Cardiac assist devices occupy the largest value pool given procedural reimbursement density, while neural interfaces represent the fastest-expanding technology segment as brain-computer interface research accelerates. Biohybrid devices concentrate margin capture at the premium tier due to cell-seeding complexity and extended development timelines.
Germany's Federal Institute for Drugs and Medical Devices (BfArM) and the notified body TÜV SÜD enforce MDR compliance for active implantable devices, raising documentation burdens that favor established manufacturers with regulatory infrastructure. The Federal Joint Committee (G-BA) determines reimbursement levels for artificial heart and cochlear implant procedures, directly shaping hospital procurement willingness and patient access thresholds. Stakeholders must monitor evolving HTA methodologies and regional hospital consolidation patterns to anticipate shifts in device commissioning authority.
Market Dynamics
Magnetically levitated rotor technology in ventricular assist devices is compressing device failure rates below legacy mechanical bearing systems, forcing manufacturers to retool production lines and hospital procurement committees to rewrite technical specifications around hemocompatibility thresholds.
Growth Catalysts
- MDR compliance acceleration:Germany's BfArM and notified bodies like TÜV SÜD have streamlined documentation pathways for active implantable devices, reducing time-to-market for established manufacturers with regulatory infrastructure already in place.
- Heart failure procedural density:University hospitals in North Rhine-Westphalia and Bavaria are expanding ventricular assist device implant volumes as cardiac surgery referrals concentrate in these regional clusters.
- Leasing model penetration:Capital-constrained cardiac centers are adopting equipment leasing arrangements for high-cost cardiac assist devices, expanding addressable provider base beyond well-capitalized academic medical centers.
Market Restraints
- Biohybrid manufacturing complexity:Cell-seeding protocols and extended development timelines for biohybrid organs concentrate production in a handful of specialized facilities, limiting supply elasticity.
- Biocompatible polymer input volatility:Specialized polymer feedstocks for hemocompatible device surfaces face concentrated supplier bases in European chemical manufacturing corridors.
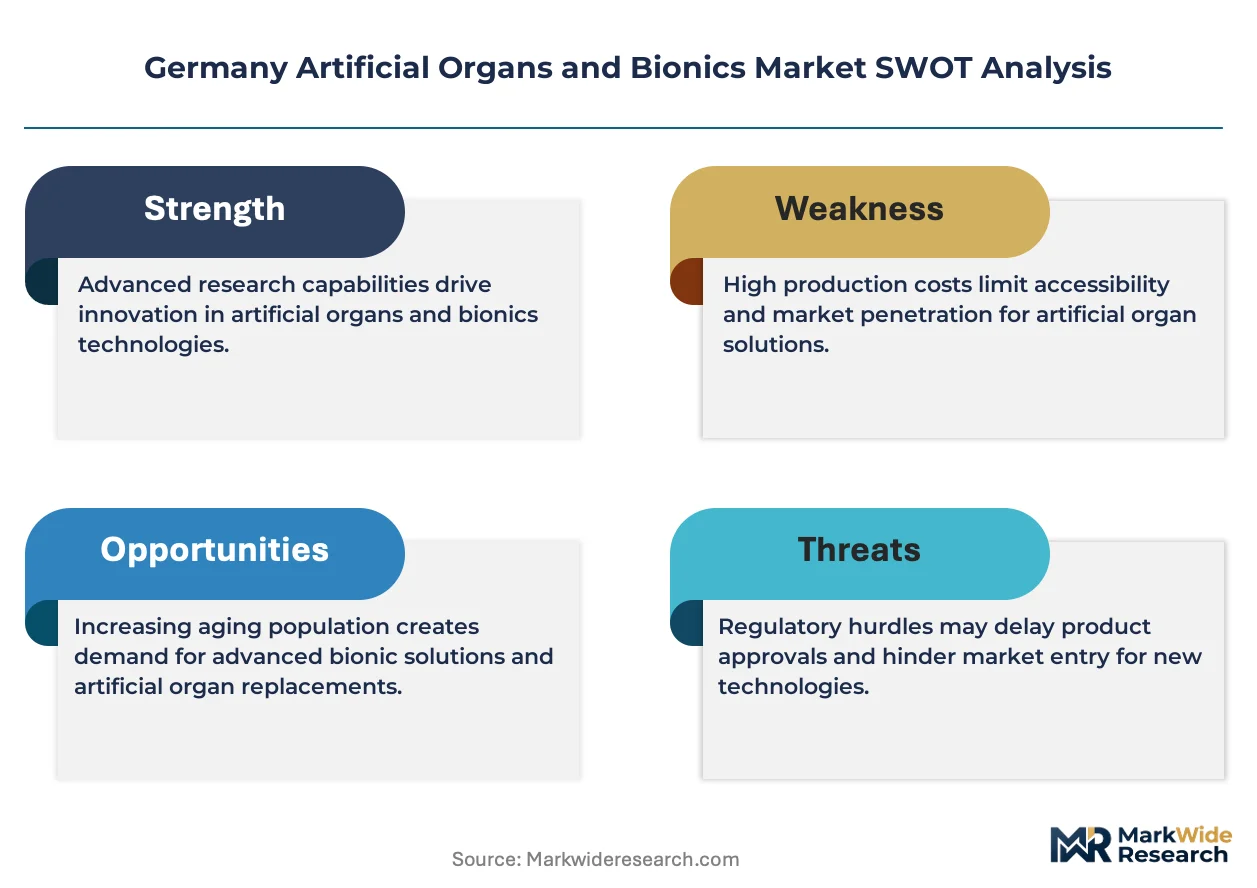
- G-BA reimbursement compression:Federal Joint Committee pricing determinations for artificial heart procedures create margin pressure that constrains R&D reinvestment capacity across the manufacturer base.
Strategic Opportunities
- Neural interface white space:Brain-computer interface research acceleration creates demand for implantable neural prosthetics that remains underserved by current product portfolios focused on cardiac and renal applications.
- Cochlear implant regional expansion:Hearing restoration procedures show penetration gaps in eastern German states relative to western university hospital clusters.
- EU MDR mutual recognition leverage:German manufacturers with BfArM approvals can access parallel European markets through streamlined conformity assessment reciprocity.
Industry Challenges
- Regulatory documentation talent scarcity:MDR technical file preparation requires specialized regulatory affairs expertise that outpaces current training pipeline output in German medical device hubs.
- Active implantable certification timelines:Notified body capacity constraints extend CE marking durations for novel cardiac assist device iterations, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Artificial Organs and Bionics Market |
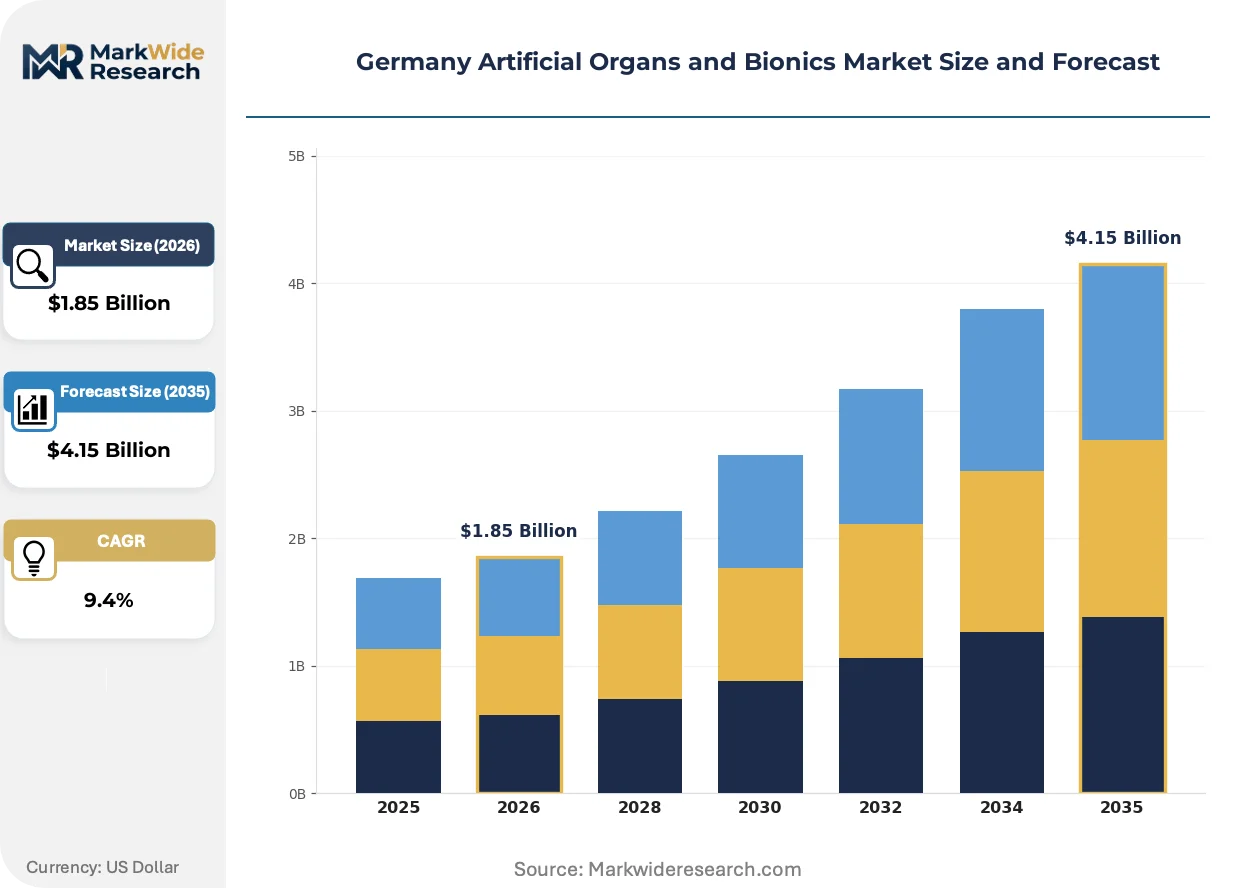
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Assist Devices, Dialysis Machines, Cochlear Implants, Retinal Prostheses, Bionic Limbs Technology: Electromechanical Systems, Biohybrid Devices, Neural Interfaces, Microelectromechanical Systems, Nanomaterials Application: Heart Failure Treatment, Renal Failure Support, Hearing Restoration, Vision Impairment Assistance, Limb Mobility Enhancement End User: Hospitals, Specialized Clinics, Rehabilitation Centers, Research Institutes, Long-term Care Facilities |
| Companies Covered | Boston Scientific Corporation, Medtronic PLC, Ossur, Berlin Heart GmbH, Asahi Kasei Medical Co Ltd, Abiomed Inc, Näder Holding GmbH & Co KG, LivaNova PLC, Esko Bionics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Artificial Organs and Bionics Market Shifts & Advancements
Three intersecting developments are restructuring how artificial organs reach patients: rotor technology advancement, regulatory process digitization, and procurement model diversification. Each trend carries distinct implications for manufacturer positioning and provider economics.
Magnetically levitated centrifugal flow pumps eliminate mechanical bearing wear as a failure mode in ventricular assist devices. German cardiac centers are prioritizing these systems in replacement procurement cycles, with university hospitals in Berlin and Munich setting technical standards that community hospitals follow. This technology is rendering obsolete first-generation axial flow devices with contact-bearing architectures, compressing the viable product lifecycle for legacy platform manufacturers.
Europe's Medical Device Regulation enforcement through BfArM and TÜV SÜD has digitized post-market surveillance requirements for active implantables. Manufacturers must now maintain electronic systems for traceability and adverse event reporting that integrate with European databases. Cardiac assist device producers face the steepest compliance burden given implant duration and patient mobility across borders, driving consolidation toward firms with dedicated regulatory technology infrastructure.
Hospital procurement committees are unbundling device acquisition from implant service contracts, separating capital equipment decisions from physician preference item negotiations. This pattern disrupts traditional bundled pricing models that manufacturers used to defend account relationships. The shift is most visible in North Rhine-Westphalia, where hospital network consolidation has centralized procurement authority for multiple cardiac centers under single contracting entities.
Germany Artificial Organs and Bionics Market Segmentation
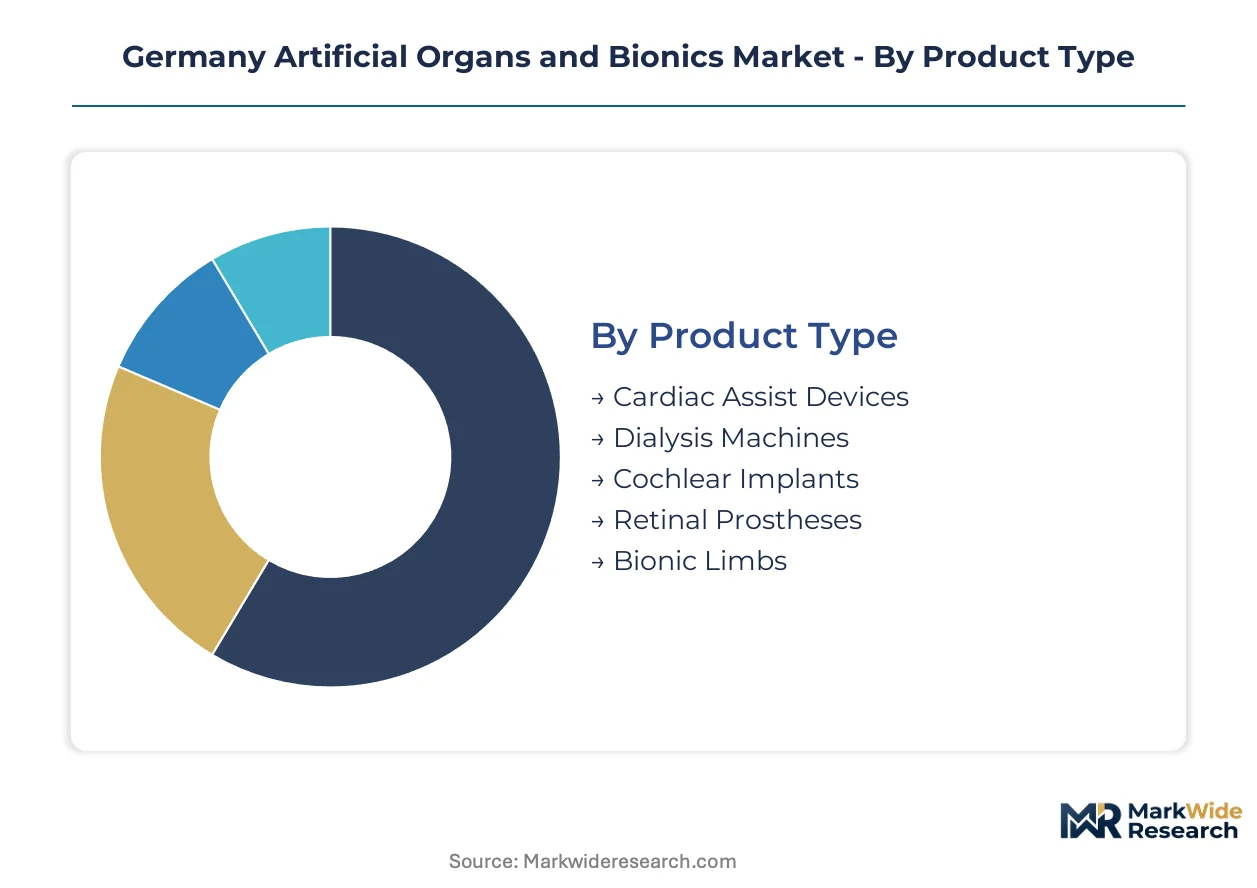
Segmentation reveals how procurement patterns and clinical workflows fragment the German market across device complexity tiers. Service intensity varies dramatically—from cardiac assist devices requiring 24/7 technical support to cochlear implants with scheduled maintenance protocols—shaping manufacturer go-to-market economics.
Product Type:
After-sales service intensity escalates with device invasiveness and patient dependency, creating divergent margin structures across product categories.
- Cardiac Assist Devices:Magnetically levitated centrifugal pumps with biocompatible polymer surfaces achieve hemocompatibility thresholds below 10 mg/dL plasma-free hemoglobin. University hospitals in North Rhine-Westphalia and Bavaria anchor implant volumes as heart failure procedural density concentrates in these regional clusters.
- Dialysis Machines:Hemodialysis and peritoneal systems incorporate ultrafiltration controllers and bicarbonate mixing modules for solute clearance. Demand concentrates in hospital-based renal units across Germany, with reimbursement density from the Federal Joint Committee sustaining procurement cycles.
- Cochlear Implants:Multichannel electrode arrays with speech processor integration for severe-to-profound sensorineural hearing loss.
- Retinal Prostheses:Epiretinal and subretinal electrode arrays targeting photoreceptor degeneration conditions.
- Bionic Limbs:Myoelectric and osseointegrated prosthetic systems with sensory feedback capabilities.
Cardiac Assist Devices hold the largest share; momentum sits with Cochlear Implants as hearing restoration gaps persist in eastern German states.
Technology:
Manufacturing complexity stratifies across technology tiers, with biohybrid devices demanding cell-seeding protocols that extend development timelines and concentrate production in specialized facilities.
- Electromechanical Systems:Motor-driven pumps, valves, and actuators with titanium and polymer housings for mechanical circulatory support. Established manufacturers with MDR regulatory infrastructure capture volume as BfArM compliance accelerates market access.
- Neural Interfaces:Implantable electrode arrays and brain-computer interface hardware for motor and sensory restoration. Research institutes in Berlin and Munich drive experimental demand as clinical translation accelerates.
- Biohybrid Devices:Cell-seeded scaffolds combining synthetic matrices with living tissue for organ function replacement.
- Microelectromechanical Systems:Miniaturized sensors and actuators fabricated through semiconductor processes.
- Nanomaterials:Surface-modified nanoparticles and nanostructured coatings for hemocompatibility enhancement.
Electromechanical Systems dominate current revenue; Neural Interfaces are climbing the fastest as brain-computer interface research expands.
Application:
Procedural reimbursement density from the G-BA shapes hospital willingness to commission devices across therapeutic areas.
- Heart Failure Treatment:Bridge-to-transplant and destination therapy protocols using ventricular assist devices. Specialized cardiac centers in Berlin and Munich set technical standards that community hospitals follow.
- Renal Failure Support:Hemodialysis, peritoneal dialysis, and wearable artificial kidney development. Dialysis chains concentrate procurement authority as hospital network consolidation proceeds.
- Hearing Restoration:Cochlear implantation and auditory brainstem implant procedures for severe hearing loss.
- Vision Impairment Assistance:Retinal prostheses and cortical implants for degenerative eye conditions.
- Limb Mobility Enhancement:Prosthetic fitting and neuroprosthetic integration for amputation and paralysis.
Heart Failure Treatment captures premium pricing; Hearing Restoration shows steepest expansion trajectory as cochlear implant penetration gaps narrow.
End User:
Procurement authority centralization varies by care setting, with hospital network consolidation rewriting contracting dynamics.
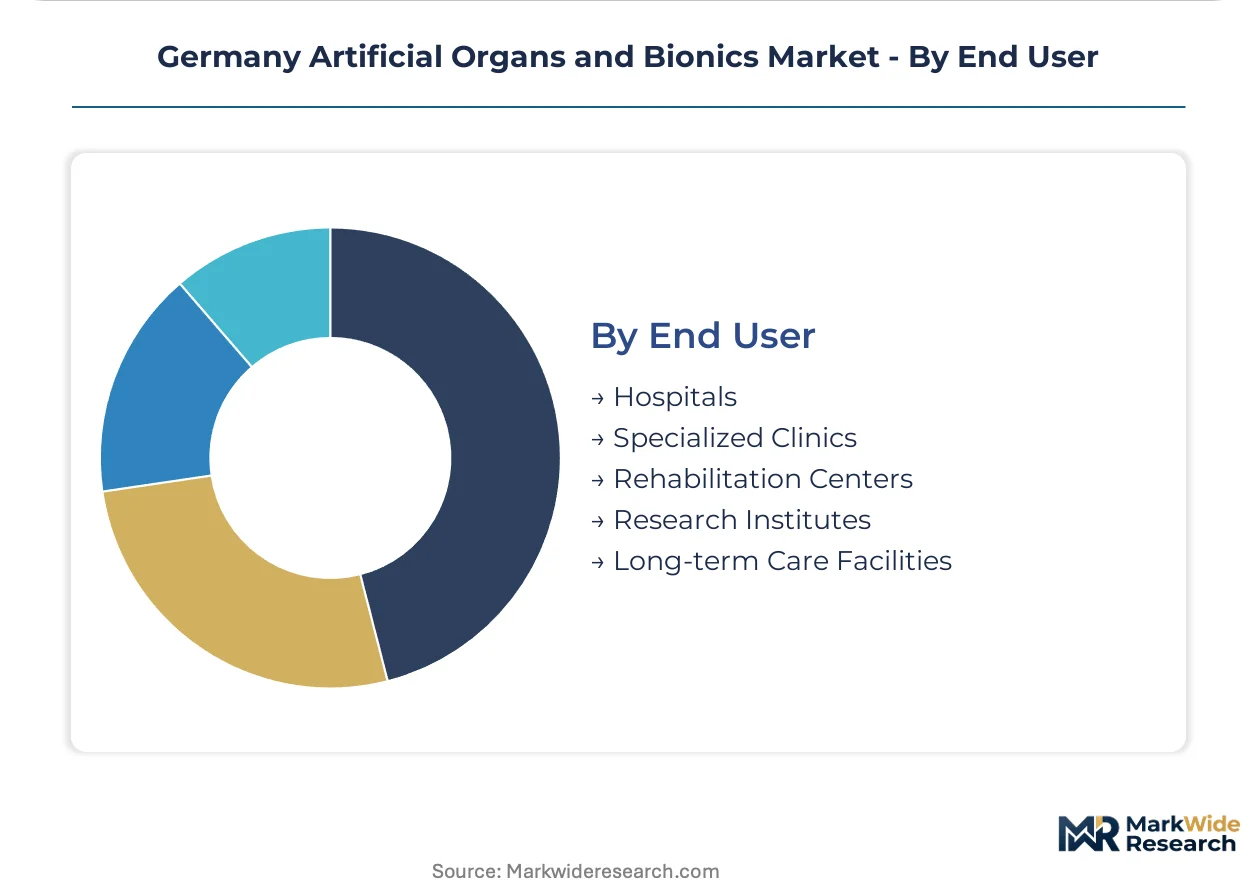
- Hospitals:University medical centers and community hospitals with cardiac surgery, nephrology, and ENT departments. North Rhine-Westphalia hospital networks centralize device commissioning for multiple cardiac centers under single contracting entities.
- Specialized Clinics:Cardiac, renal, and otology centers with focused implant programs and direct manufacturer relationships.
- Rehabilitation Centers:Post-acute facilities for prosthetic fitting and functional training.
- Research Institutes:Academic and clinical research organizations conducting device trials and translational studies.
- Long-term Care Facilities:Skilled nursing settings for chronic device management and patient monitoring.
Hospitals command the largest procurement volume; Research Institutes are gaining share fastest as clinical trial activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospitals and specialized cardiac centers concentrate procurement authority for high-cost implantable devices. Regional clustering follows reimbursement density and surgical volume concentration.
North Rhine-Westphalia
Hospital network consolidation centralizes contracting for multiple cardiac centers under single entities. The Federal Joint Committee's procedural reimbursement determinations sustain ventricular assist device commissioning. University hospitals in Cologne and Düsseldorf anchor implant volumes as heart failure referrals concentrate regionally.
Bavaria
Munich-based university medical centers set technical standards for magnetically levitated pump specifications. BfArM's MDR compliance pathways accelerate market access for established manufacturers with regulatory infrastructure. The Nuremberg-Erlangen medical technology corridor hosts specialized polymer suppliers for hemocompatible device surfaces.
Baden-Württemberg
Research institutes in Heidelberg and Tübingen drive experimental demand for neural interface technologies. TÜV SÜD's notified body operations streamline CE marking for active implantable devices. The Stuttgart region concentrates precision engineering capabilities for microelectromechanical system fabrication.
Berlin-Brandenburg
Capital-region cardiac centers prioritize next-generation ventricular assist device procurement cycles. Medtronic PLC's European headquarters sustains close relationships with implanting physicians. Berlin Heart GmbH maintains specialized manufacturing operations for magnetically levitated cardiac support systems.
Hesse
Frankfurt's hospital networks expand leasing arrangements for capital-constrained cardiac centers. The Federal Institute for Drugs and Medical Devices monitors post-market surveillance for cross-border patient mobility. Giessen's university hospital anchors renal failure support device volumes in central Germany.
Germany Artificial Organs and Bionics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. Established manufacturers with MDR regulatory infrastructure capture volume as compliance burdens filter smaller competitors. Three archetypes dominate: diversified medical technology conglomerates with European headquarters, specialized cardiac device manufacturers with domestic production, and prosthetic specialists with rehabilitation channel relationships. Consolidation proceeds through hospital network contracting centralization and notified body capacity constraints extending certification timelines.
Among diversified technology conglomerates, Medtronic PLC and Boston Scientific Corporation occupy positions shaped by regulatory infrastructure scale and hospital procurement committee relationships. Berlin Heart GmbH exemplifies the specialized domestic manufacturer archetype, leveraging proximity to German cardiac centers. Within the prosthetic and bionic limb segment, Ossur represents rehabilitation channel-focused positioning. These three anchors illustrate how competitive advantage fragments across regulatory compliance capability, manufacturing specialization, and clinical relationship depth.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic PLC |
| Ossur |
| Berlin Heart GmbH |
| Asahi Kasei Medical Co Ltd |
| Abiomed Inc |
| Näder Holding GmbH & Co KG |
| LivaNova PLC |
| Esko Bionics |
| Others |
Supply & Pricing Matrix
Single-source dependency on magnetically levitated rotor assemblies from Swiss and German precision engineering clusters determines both the three-tier pricing structure across premium, standard, and economy certification levels and the geographic concentration of final device assembly. G-BA reimbursement compression feeds directly into procurement committee leverage, forcing manufacturers to absorb polymer feedstock volatility rather than pass through costs.
Pricing Analysis
Cost-plus contracts with biocompatible polymer indexation dominate procurement agreements between cardiac centers and device manufacturers. Price differentiation rests on MDR certification tier and after-sales service bundling intensity. Pricing pressure stems from G-BA margin compression that constrains R&D reinvestment capacity. Community hospitals exhibit highest price sensitivity due to capital constraints, while university medical centers prioritize hemocompatibility performance over acquisition cost.
Supply Chain Analysis
EU dual-use export controls on precision magnetic bearing technology limit rotor component flows to non-European assembly facilities. Manufacturing concentrates in Germany, Switzerland, and Austria. Supply chains draw from specialized polymer feedstocks, titanium housings, and semiconductor-grade sensor arrays. Single-source vulnerability sits with magnet wire suppliers in the Nuremberg-Erlangen corridor. Distribution runs through hospital network procurement entities that centralize contracting authority across multiple implant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital network consolidation in North Rhine-Westphalia and Bavaria, fragmenting manufacturer pricing leverage across fewer contracting entities with standardized technical specifications.
For Market Incumbents: Pre-empt regulatory documentation talent scarcity by captive training partnerships with German medical device regulatory programs. Anchor polymer supply security through backward integration into specialized hemocompatible coating production. Defend against leasing model disruption by unbundling device acquisition from service contracts to maintain account control. For New Entrants and Emerging Players: Build out neural interface white space in Berlin and Munich research corridors where brain-computer interface demand outpaces current product portfolios. Target eastern German cochlear implant penetration gaps where hearing restoration procedural density lags western university hospital clusters. Enter through research institute partnerships that bypass hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: The market sits at a reimbursement-reform phase that favors manufacturers with established MDR regulatory infrastructure and G-BA relationship depth. Long-term viability over the next decade hinges on biohybrid manufacturing capability that extends development timelines but captures premium tier margins. Watch G-BA HTA methodology evolution as the inflection signal for procedural reimbursement density shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Digitization | BfArM electronic submission pathways compress CE marking timelines for active implantables. |
| Hospital System Partnership | North Rhine-Westphalia network consolidation centralizes procurement authority for multiple cardiac centers. |
| Reimbursement Strategy | G-BA pricing determinations directly shape commissioning willingness for artificial heart procedures. |
| Software Companion Development | Remote monitoring platforms satisfy BfArM post-market surveillance digitization requirements. |
| CE Marking Pathway | TÜV SÜD notified body capacity constraints favor established manufacturers with regulatory infrastructure. |
Research Methodology
Operator-level perspectives from cardiac surgeons, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from BfArM device registrations, G-BA reimbursement determinations, hospital procurement databases, and European notified body certification records. Bottom-up implant volume modeling triangulated against top-down market sizing across electromechanical, neural interface, and biohybrid technology tiers.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, technology tier, application area, and end-user setting. CAGRs derived from procedural density trajectories, reimbursement evolution assumptions, and technology substitution elasticities. Forecast inputs incorporated MDR compliance acceleration timelines and regional hospital consolidation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich technology conglomerates or biohybrid specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Smart Stairlift Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Global Pessary Market