
 Global Amniocentesis Needle Market | 2026-2036
Global Amniocentesis Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amniocentesis Needle Market Foresight
The maternal-fetal medicine unit segment is restructuring demand patterns across obstetric instrument procurement. Cook Medical leverages its specialty needle portfolio to sustain leadership in echogenic tip configurations. Becton Dickinson and Company anchors North American supply chains through integrated manufacturing of stainless steel prenatal instruments. Smiths Medical differentiates via European distribution density for disposable amniocentesis sets.
An amniocentesis needle is a hollow, beveled instrument typically 20–22 gauge in diameter, designed to penetrate the abdominal wall and uterus for transabdominal amniotic fluid aspiration under ultrasound guidance. Stainless steel construction dominates current production due to tensile strength and echogenic visibility requirements, though titanium alloy variants gain traction for magnetic resonance compatibility. Echogenic needle configurations command premium positioning because enhanced ultrasound reflectivity reduces procedural risk. Genetic testing applications represent the fastest-expanding demand pool as non-invasive prenatal screening triage protocols expand. Disposable needle formats now occupy the majority volume share while reusable formats retain niche presence in cost-constrained research settings.
The FDA governs 510(k) clearance pathways for amniocentesis devices while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements across European member states. Japan's PMDA maintains distinct sterility validation protocols that shape export compliance burdens for Western manufacturers. Stakeholders must monitor evolving harmonization between ISO 13485 quality management standards and national post-market surveillance mandates to anticipate certification cost trajectories.
Market Dynamics
Echogenic needle configurations are restructuring competitive positioning across maternal-fetal medicine procurement, as ultrasound visibility requirements displace standard stainless steel formats in high-acuity settings.
Growth Catalysts
- EMA Medical Device Regulation:Stricter clinical evidence mandates for Class IIa obstetric instruments are accelerating hospital upgrades to validated disposable needle sets.
- Genetic testing triage protocols:Expanded non-invasive prenatal screening referral pathways in tertiary care centers are pulling demand for amniocentesis confirmation procedures.
- Titanium alloy adoption:Magnetic resonance compatibility requirements in Japan's university hospitals are creating premium demand pools for non-ferrous needle variants.
Market Restraints
- Stainless steel supply concentration:German and Japanese specialty steel mills control high-purity medical-grade feedstock, exposing manufacturers to input cost volatility.
- Non-invasive prenatal testing substitution:Cell-free DNA screening sensitivity improvements above 99% for trisomy detection are compressing invasive procedure volumes in routine-risk pregnancies.
- Japan PMDA sterility validation:Distinct endotoxin and bioburden protocols create export compliance friction for Western manufacturers seeking market entry.
Strategic Opportunities
- India's tertiary care expansion:Government-funded maternal health infrastructure under the National Health Mission is creating first-time demand for disposable amniocentesis sets in previously underserved states.
- ISO 13485 harmonization:Convergence between international quality management standards and national post-market surveillance mandates is reducing multi-jurisdiction certification costs for compliant manufacturers.
- Telemedicine-integrated guidance:Remote ultrasound interpretation partnerships are enabling amniocentesis service extension into secondary hospitals lacking on-site maternal-fetal medicine specialists.
Industry Challenges
- ISO 13485 auditor capacity:Shortage of notified body personnel qualified for obstetric device quality system certification is extending time-to-market for new needle configurations.
- Legacy reusable instrument decontamination:Research institutions maintaining sterilizable needle formats face escalating compliance costs under evolving steam sterilization validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amniocentesis Needle Market |
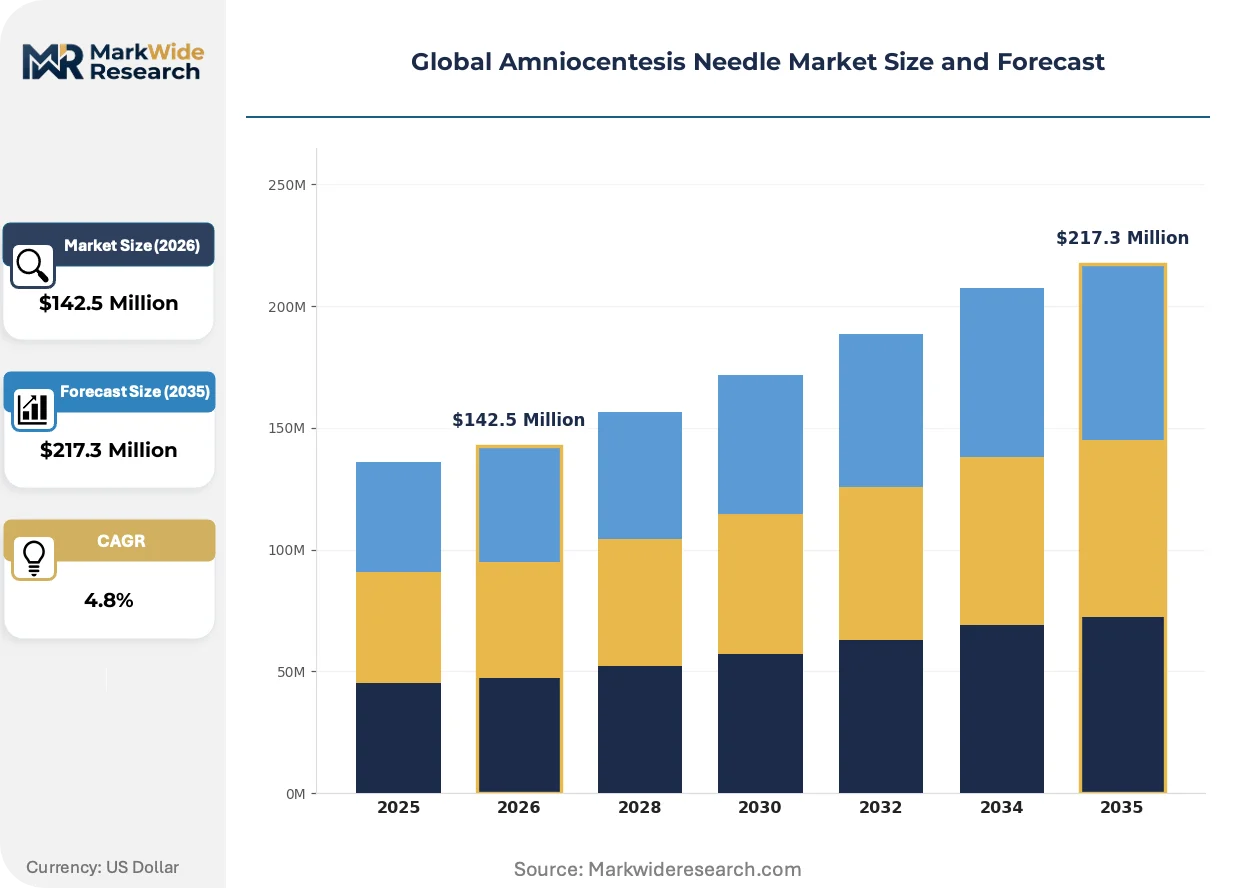
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needle, Echogenic Needle, Spinal Needle, Disposable Needle, Reusable Needle Material: Stainless Steel, Titanium Alloy, Plastic Composite, Polycarbonate, Medical Grade Polymer Application: Prenatal Diagnosis, Genetic Testing, Fetal Therapy, Chromosomal Analysis, Infection Detection End User: Diagnostic Laboratories, Maternal-Fetal Medicine Units, Research Institutes, Specialty Clinics, Genetic Counseling Centers |
| Companies Covered | Cardinal Health, Cook Medical, Becton Dickinson and Company, Integra LifeSciences, Smiths Medical, The Cooper Companies, McKesson Corporation, Biopsybell, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amniocentesis Needle Market Shifts & Advancements
Needle design architectures are fragmenting across echogenic coating technologies, disposable-versus-reusable format debates, and compatibility requirements for multimodal imaging environments.
Echogenic surface patterning is modularizing across tip geometries and shaft configurations to match specific ultrasound transducer frequencies. Maternal-fetal medicine units in the United States and Germany are standardizing on depth-marked variants with integrated stylet systems. This modularization is compressing procurement timelines by allowing component-level vendor qualification rather than full-system validation.
The FDA's updated 510(k) premarket notification pathway for obstetric instruments is tightening sterility assurance level documentation requirements. Manufacturers must now submit enhanced biocompatibility data for needle lubricants and hub materials. Disposable format suppliers with established quality management systems are absorbing compliance costs more efficiently than entrants targeting niche reusable segments.
Hospital procurement committees are consolidating vendor relationships to reduce qualification overhead for high-volume disposable sets. Group purchasing organizations in the United States are displacing direct manufacturer contracts for standardized needle specifications. This concentration is most visible in integrated delivery networks where maternal-fetal medicine services span multiple affiliated birth centers.
Global Amniocentesis Needle Market Segmentation
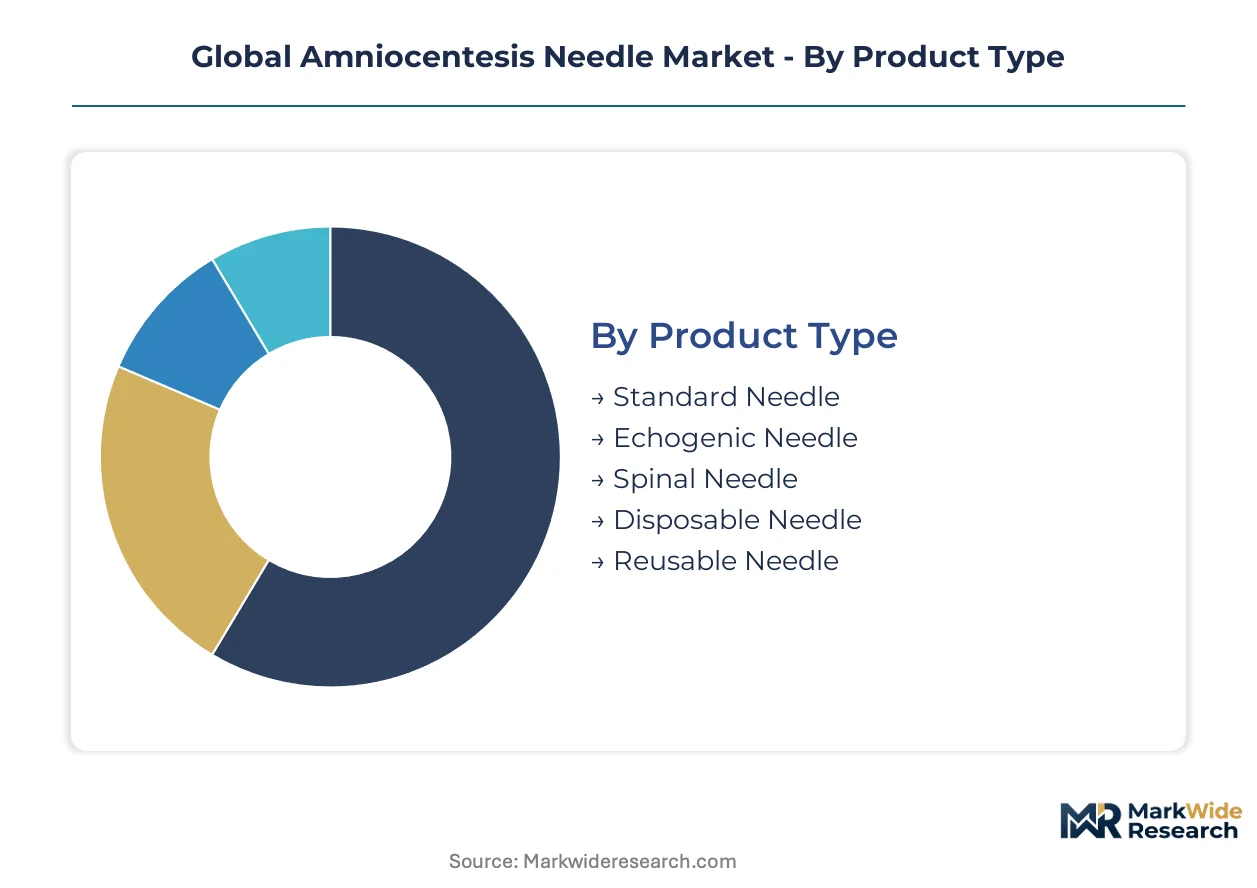
Needle specification choices directly determine ultrasound visibility, magnetic resonance compatibility, and sterility assurance levels across maternal-fetal medicine workflows. Procurement committees segment demand by procedural acuity, imaging environment constraints, and regulatory validation requirements rather than unit cost alone.
Product Type:
Echogenic surface patterning and disposable sterilization formats are restructuring procurement specifications across tertiary care centers.
- Echogenic Needle:Enhanced ultrasound reflectivity derives from sandblasted or polymer-coated stainless steel surfaces that reduce needle-tip visualization errors during amniotic fluid aspiration. Maternal-fetal medicine units in the United States and Germany prioritize these configurations for high-risk pregnancies where precise placental positioning is critical. Premium positioning reflects reduced procedural risk and shorter operative times.
- Disposable Needle:Pre-sterilized single-use sets eliminate steam sterilization validation burdens and cross-contamination liability in high-throughput diagnostic laboratories. Demand concentrates in integrated delivery networks where group purchasing organizations consolidate vendor relationships for standardized specifications. Compliance cost absorption favors established quality management systems over niche reusable entrants.
- Standard Needle:Unmodified stainless steel bevel designs retain presence in cost-constrained secondary hospitals with basic ultrasound guidance capabilities.
- Spinal Needle:Pencil-point or Quincke tip geometries adapted for amniocentesis access fetal therapy applications requiring reduced dural puncture risk profiles.
- Reusable Needle:Sterilizable formats persist in research institutes maintaining legacy instrument inventories under evolving steam sterilization validation requirements.
Disposable formats lead on scale; echogenic configurations lead on momentum.
Material:
Feedstock selection balances tensile strength requirements against multimodal imaging compatibility and endotoxin control specifications.
- Stainless Steel:Medical-grade austenitic alloys dominate current production due to established echogenic visibility, corrosion resistance, and supply chain maturity from German and Japanese specialty mills. High-purity feedstock concentration exposes manufacturers to input cost volatility from concentrated mill capacity.
- Titanium Alloy:Non-ferrous composition enables magnetic resonance imaging compatibility without artifact generation, creating premium demand pools in Japan's university hospitals where multimodal fetal assessment protocols are standard. Biocompatibility profile supports extended indwelling applications in complex fetal therapy procedures.
- Plastic Composite:Polymer-ceramic hybrid formulations reduce manufacturing cost for single-use economies but sacrifice ultrasound reflectivity precision.
- Polycarbonate:Transparent hub materials facilitate flashback confirmation during amniotic fluid aspiration in resource-limited settings.
- Medical Grade Polymer:Specialized thermoplastics address niche applications requiring radiolucency for concurrent fluoroscopic guidance.
Stainless steel leads on scale; titanium alloy leads on momentum.
Application:
Clinical indication severity determines needle specification tier and procedural setting requirements.
- Genetic Testing:Karyotyping and microarray analysis applications require precise amniotic fluid volumes with minimal blood contamination, driving specification for echogenic tips with integrated stylet systems in tertiary referral centers. Expanded non-invasive prenatal screening triage protocols are pulling confirmatory procedure volumes.
- Prenatal Diagnosis:Routine aneuploidy screening and neural tube defect assessment constitute the baseline volume pool across maternal-fetal medicine units in the United States, Germany, and Japan where advanced infrastructure exists.
- Fetal Therapy:Therapeutic amniocentesis for twin-to-twin transfusion syndrome or amnioreduction demands specialized needle gauges and lengths adapted to interventional ultrasound platforms.
- Chromosomal Analysis:Cell culture viability requirements prioritize atraumatic tip designs reducing amniocyte trauma during aspiration.
- Infection Detection:Polymerase chain reaction sample integrity protocols specify sterile disposable formats with validated endotoxin thresholds.
Prenatal diagnosis leads on scale; genetic testing leads on momentum.
End User:
Facility type determines procurement consolidation patterns and regulatory validation burden tolerance.
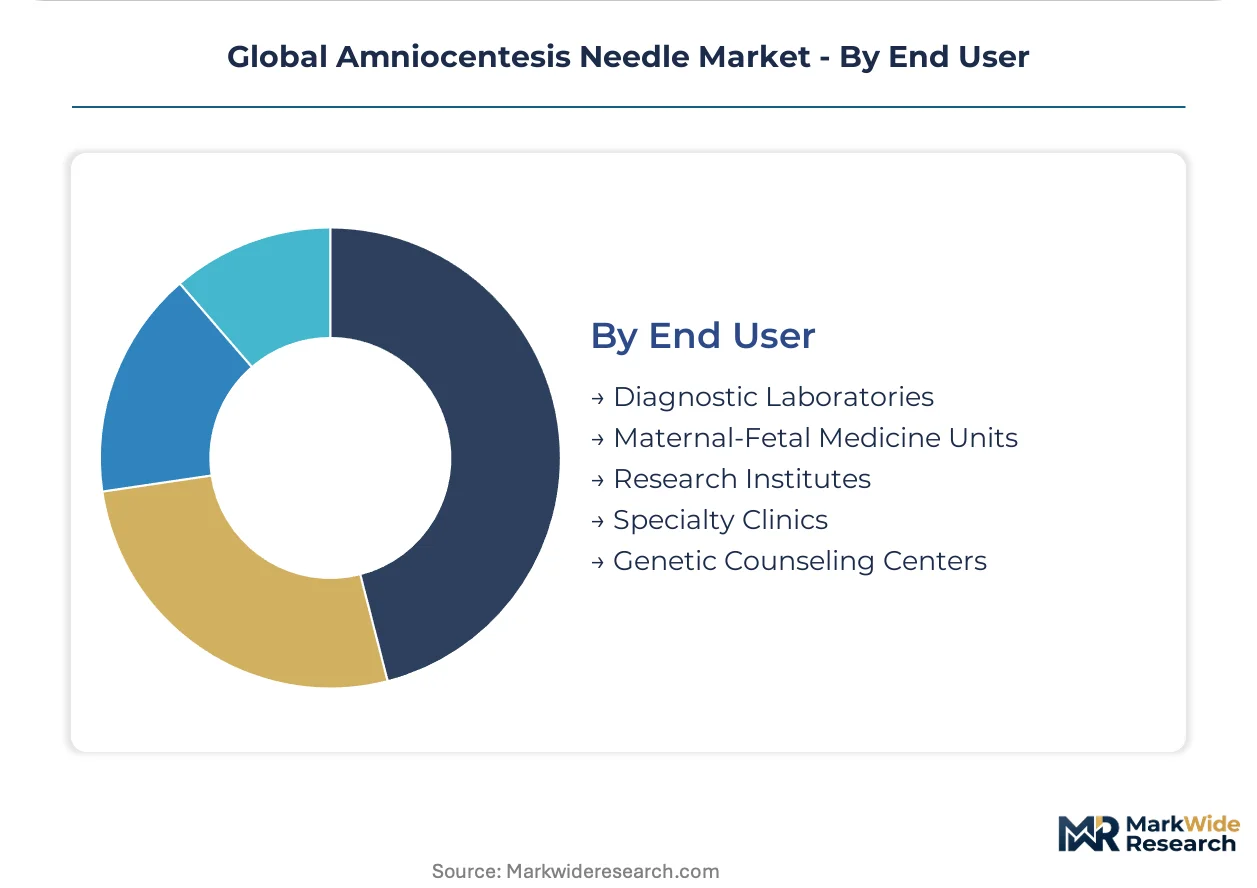
- Maternal-Fetal Medicine Units:Tertiary care centers with dedicated perinatology services standardize on echogenic, depth-marked variants with established vendor qualification systems. These units anchor demand concentration in the United States, Germany, and Japan.
- Diagnostic Laboratories:High-volume centralized testing facilities prioritize disposable format standardization to minimize instrument qualification overhead and maximize throughput efficiency.
- Research Institutes:Academic medical centers maintain mixed inventories balancing reusable legacy instruments against disposable formats for clinical trial protocols.
- Specialty Clinics:Private perinatal practices select mid-tier specifications balancing cost constraints against liability exposure.
- Genetic Counseling Centers:Pre-procedure consultation facilities influence referral patterns but do not directly procure invasive instruments.
Diagnostic laboratories lead on scale; maternal-fetal medicine units lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs by routing production through jurisdictions with streamlined quality management certification. The FDA's 510(k) pathway and Japan's PMDA protocols create divergent cost structures that reshape sourcing decisions.
United States
Maternal-fetal medicine units at tertiary centers drive specification upgrades toward echogenic needle formats. The FDA's tightened sterility assurance documentation under updated 510(k) guidance extends time-to-market for new entrants. Boston and New York metropolitan clusters concentrate procurement decision-making for integrated delivery networks negotiating group purchasing contracts.
Germany
Specialty steel mills in the Ruhr and Bavaria supply high-purity medical-grade feedstock for stainless steel needle production. The EMA's Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa obstetric instruments than FDA equivalents. Frankfurt and Munich anchor distribution networks serving consolidated hospital procurement across Central Europe.
Japan
University hospitals in Tokyo and Osaka generate premium demand for titanium alloy variants compatible with multimodal fetal imaging protocols. PMDA maintains distinct endotoxin and bioburden validation standards that create export friction for Western manufacturers. The Kanto region concentrates domestic production of magnetic resonance-compatible prenatal instruments.
India
Government-funded maternal health infrastructure under the National Health Mission creates first-time demand for disposable amniocentesis sets in previously underserved states. CDSCO regulates medical device imports through a notification system that is converging toward MDR harmonization. Maharashtra and Karnataka host emerging distribution hubs for tertiary care expansion in Western and Southern regions.
United Kingdom
Genetic testing referral networks through the National Health Service concentrate confirmatory amniocentesis procedures at designated regional genetics centers. MHRA operates under retained EU MDR alignment with post-Brexit divergence risk for future sterility standards. London and the Southeast concentrate specialist maternal-fetal medicine capacity and associated instrument procurement.
Global Amniocentesis Needle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies controlling North American supply chains and European firms anchoring distribution density. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with obstetric portfolios, specialty needle manufacturers with echogenic coating capabilities, and regional disposable set suppliers. Competitive moves center on group purchasing organization contract consolidation and backward integration into high-purity steel feedstock sourcing.
Within the diversified medtech tier, Becton Dickinson and Company and Cardinal Health exemplify scale-driven positioning through integrated manufacturing and distribution infrastructure. Cook Medical occupies a specialist position representing focused portfolio depth in echogenic tip configurations. Smiths Medical anchors European market presence through density in disposable set distribution networks. These three entities collectively illustrate how geographic manufacturing footprint and regulatory pre-clearance history determine competitive access to hospital procurement committees.
| Leading Market Players |
|---|
| Cardinal Health |
| Cook Medical |
| Becton Dickinson and Company |
| Integra LifeSciences |
| Smiths Medical |
| The Cooper Companies |
| McKesson Corporation |
| Biopsybell |
| Medline Industries |
| Others |
Supply & Pricing Matrix
Specialized needle-coating technicians in Bavaria and Osaka command wage premiums that propagate through echogenic needle pricing tiers, compressing margins for manufacturers without captive surface-patterning capabilities while widening spreads between premium ultrasound-visible configurations and standard stainless steel alternatives.
Pricing Analysis
Distributor markups on disposable amniocentesis sets compress manufacturer margins by 18-25 percentage points across European and North American channels. Three-tier pricing structure across premium, standard, and economy levels separates echogenic titanium alloy variants from depth-marked stainless steel formats from unmodified standard needles. Pricing pressure stems from group purchasing organization consolidation in United States integrated delivery networks, which standardize specifications and squeeze vendor premiums. Diagnostic laboratories exhibit highest price sensitivity due to throughput-driven procurement committees, while Japan's university hospitals demonstrate lowest sensitivity given multimodal imaging compatibility requirements.
Supply Chain Analysis
India's phased domestic-content mandates under the National Health Mission are reshaping sourcing patterns for disposable sets destined for government-funded maternal health infrastructure. High-purity medical-grade stainless steel feedstock concentrates in German Ruhr Valley and Japanese Kansai region specialty mills, with titanium sponge processing anchored in China and Russia. Supply chain risk centers on single-source vulnerability for echogenic coating chemistries held by three European specialty chemical suppliers. Distribution runs through hospital group purchasing organizations in North America, regional medical device distributors in Europe, and government procurement portals in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Amniocentesis Needle Market functions as a regulatory compounder, with the FDA's updated 510(k) sterility documentation requirements accelerating hospital upgrades to validated disposable formats and compressing time-to-market for non-compliant entrants.
For Market Incumbents: Hedge against non-invasive prenatal testing substitution by deepening echogenic coating capabilities and securing long-term offtake agreements with German and Japanese specialty steel mills. Cell-free DNA screening sensitivity improvements above 99% threaten routine-risk procedure volumes; vertical integration into high-purity feedstock sourcing defends margin position against input cost volatility from concentrated mill capacity. For New Entrants and Emerging Players: Regional distributors serving India's National Health Mission-funded tertiary care expansion represent the most accessible channel partner type for first-time market entry. Maharashtra and Karnataka's emerging distribution hubs offer white-space access for disposable set suppliers; CDSCO notification system convergence toward MDR harmonization reduces multi-jurisdiction certification burdens. Target government procurement portals with validated endotoxin documentation and competitive unit economics. For Investors and Strategic Acquirers: Diversified medtech conglomerates with underdeveloped obstetric portfolios are the most active acquirer in this space, seeking echogenic coating specialists to fill portfolio gaps. Long-term viability hinges on regulatory pre-clearance history and established quality management systems rather than manufacturing scale alone. ISO 13485 auditor capacity shortages extending time-to-market for new configurations signal consolidation pressure on smaller entrants lacking compliant infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR clinical evidence requirements for Class IIa obstetric instruments accelerate hospital upgrades to validated disposable sets. |
| Backward Integration into Feedstock | Captive supply of high-purity medical-grade stainless steel from German and Japanese mills reduces input cost volatility exposure. |
| Hospital System Partnership | Integrated delivery network group purchasing contracts consolidate vendor relationships and lock out non-qualified competitors. |
| Software Companion Development | Telemedicine-integrated ultrasound guidance platforms extend amniocentesis service into secondary hospitals lacking on-site specialists. |
| Reimbursement Strategy | Genetic testing triage protocol expansion in tertiary care centers pulls confirmatory procedure volumes and sustains premium pricing. |
Research Methodology
Bottom-up maternal-fetal medicine unit procurement modeling reconciled against top-down specialty needle manufacturing tracking forms the analytical core of this study. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and maternal-fetal medicine specialists were cross-validated against secondary sources including FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and ISO 13485 certification registries.
Historical trendline analysis of needle specification adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, material grade tier, clinical application severity, and end-user facility classification. CAGRs were derived from elasticity-adjusted demand curves incorporating procedure volume trajectories, regulatory compliance cost absorption rates, and supply-side capacity constraints from specialty steel mill utilization data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to non-invasive prenatal testing substitution thresholds, ISO 13485 auditor capacity expansion, and harmonization progress between national post-market surveillance mandates. Forecasts reflect documented assumptions regarding sterility validation protocol evolution and group purchasing organization consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elbow Fixators Market
Medical Devices
Europe C-Arms Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Alpha Emitter Market