
 Syndesmosis Repair System Market | 2026-2036
Syndesmosis Repair System Market Size, Share, and Industry Trends Forecast 2026-2036
Syndesmosis Repair System Market Analytics
The capital-intensity gap between integrated manufacturers and component assemblers is collapsing as suture-button systems commoditize. Arthrex, Inc. leverages captive manufacturing of high-tensile polyethylene sutures to sustain margin structures. Zimmer Biomet anchors its position through dense hospital GPO contracts across North American trauma centers.
A syndesmosis repair system comprises implants and instruments designed to restore the distal tibiofibular syndesmotic joint using suture-button constructs, metal screws, or plate fixation with titanium or cobalt-chrome compositions rated for cyclic loading. These systems enable anatomic reduction and dynamic stabilization during weight-bearing recovery in traumatic ankle injuries. Internal fixation devices dominate procedural volume due to biomechanical reliability, while minimally invasive surgery delivery modes represent the fastest-expanding access route as arthroscopic techniques reduce soft-tissue morbidity. Sports medicine facilities command premium pricing through specialized surgeon concentration and bundled care pathways.
FDA 510(k) premarket notification requirements govern implant biocompatibility and mechanical testing standards in the United States, while the EU MDR mandates clinical evidence and notified-body oversight for CE-marked devices in European markets. Japan's PMDA enforces QMS conformity and foreign manufacturer registration for imported orthopedic implants. Stakeholders must monitor regulatory divergence between accelerated FDA breakthrough pathways and lengthening EU conformity assessment timelines when allocating R&D and registration budgets.
Market Dynamics
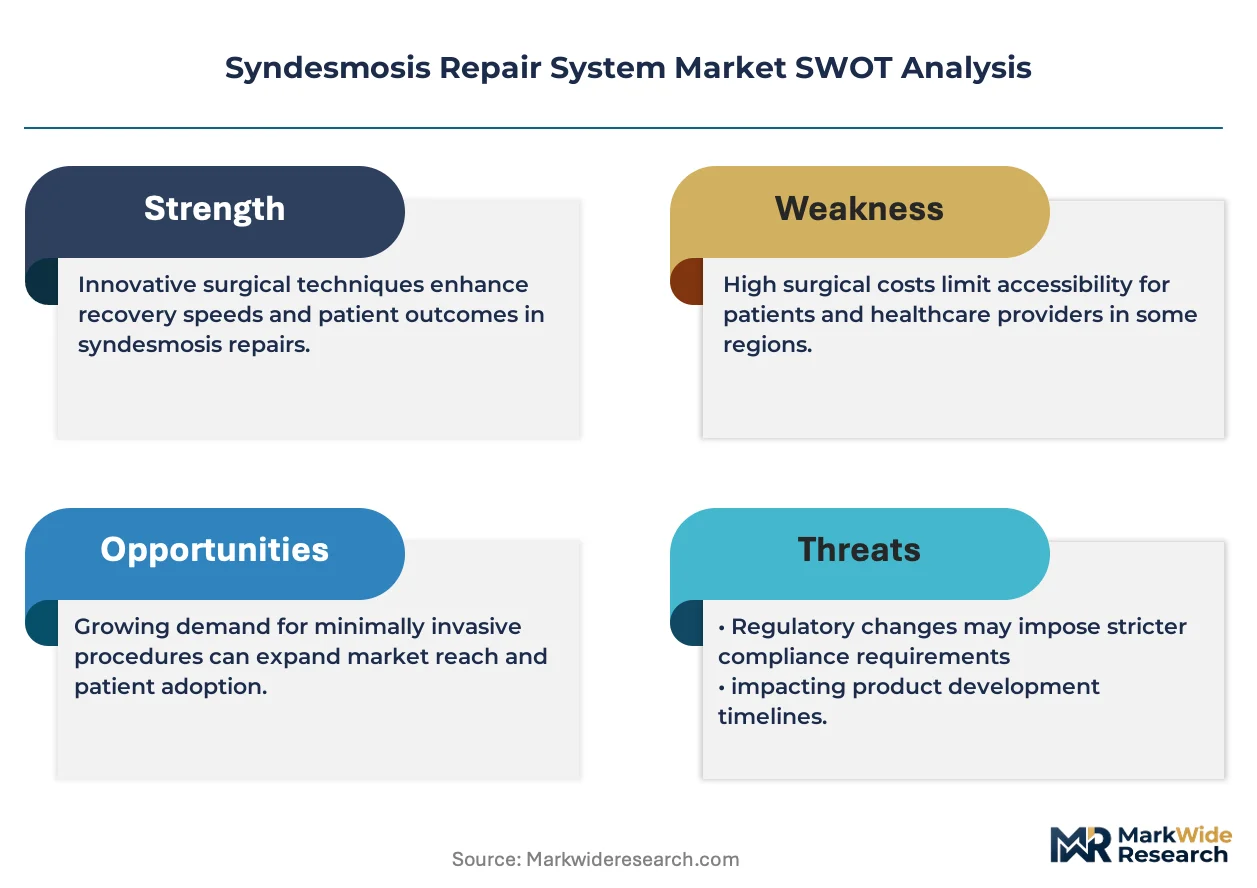
Arthroscopic delivery modes are compressing open-surgery procedural volumes as sports medicine facilities reconfigure operating room workflows around minimally invasive ankle fixation. This modality shift is redistributing capital equipment budgets and surgeon training investments across orthopedic service lines.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for suture-button constructs accelerates product registration timelines relative to EU MDR conformity assessments. Device sponsors leverage predicate device strategies to compress regulatory lead times.
- Polyethylene Suture Material Advances:High-tensile braided polyethylene fibers enable dynamic stabilization with reduced implant failure rates. Biomechanical testing protocols validate cyclic loading performance under weight-bearing rehabilitation protocols.
- Athlete Injury Volume Concentration:Professional and collegiate sports medicine centers in the United States, Germany, and Japan generate disproportionate procedural demand. Specialized orthopedic infrastructure supports complex syndesmotic injury management.
Market Restraints
- Titanium Input Cost Volatility:Spot price fluctuations for implant-grade titanium sponge compress margin structures for screw and plate manufacturers. Supply contract renegotiations absorb quarterly raw material swings.
- EU MDR Clinical Evidence Burden:Lengthening notified-body review timelines and post-market surveillance requirements delay CE-marked product launches. Small-device sponsors face disproportionate compliance resource constraints.
- Metal Screw Substitution Pressure:Suture-button systems displace traditional screw fixation in select indications, eroding addressable volume for rigid internal fixation portfolios. Biomechanical equivalence studies drive surgeon conversion.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:United States outpatient migration creates white space for disposable instrument kits and streamlined implant configurations. CMS reimbursement alignment supports site-of-service shift.
- Arthroscopic Technique Convergence:Integration of 4K visualization with radiofrequency ablation tools enables all-inside syndesmosis repair. Dual-technology platforms differentiate premium system offerings.
- Japan PMDA QMS Harmonization:Foreign manufacturer registration pathway simplification reduces import friction for established orthopedic portfolios. METI industrial policy prioritizes trauma device availability.
Industry Challenges
- Arthroscopic Skill Acquisition Bottleneck:Fellowship-trained foot and ankle surgeons remain concentrated in academic medical centers. Community hospital credentialing timelines constrain technique diffusion.
- MDR Technical Documentation Burden:Clinical evaluation report preparation consumes 18-24 month regulatory cycles for legacy device families. Notified-body capacity constraints extend queue durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syndesmosis Repair System Market |
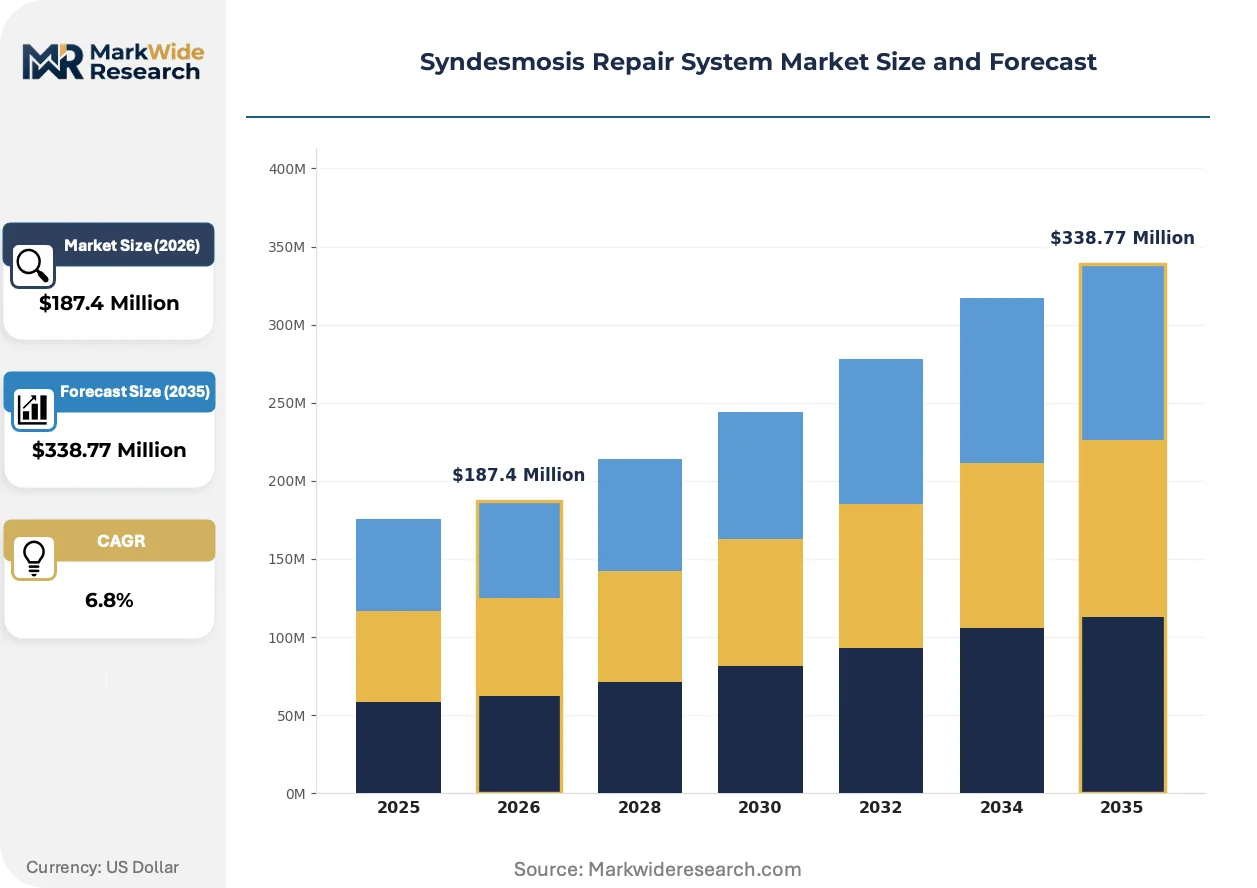
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Fixation Devices, External Fixation Devices, Screws, Plates End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Application: Trauma Surgery, Sports Injuries, Reconstruction Surgery, General Surgery Delivery Mode: Open Surgery, Minimally Invasive Surgery, Arthroscopic Surgery, Hybrid Techniques |
| Companies Covered | Arthrex, Inc., Zimmer Biomet, Smith & Nephew, Stryker Corporation, Acumed LLC, DePuy Synthes, Paragon 28, Inc., CONMED Corporation, Medacta International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syndesmosis Repair System Market Evolving Landscape
Bioresorbable materials, digital surgical planning, and value-based procurement models are simultaneously reshaping implant design, operative workflow, and commercial contracting structures in ankle fixation.
Suture-button constructs utilizing ultra-high-molecular-weight polyethylene tape are decomposing the historical dominance of metal screw fixation in acute syndesmotic injuries. Sports medicine surgeons at high-volume trauma centers are adopting these dynamic stabilization systems for select patient cohorts. The technology is decomposing rigid fixation market share by enabling early weight-bearing protocols without implant removal surgery.
EU MDR post-market clinical follow-up requirements are extending surveillance obligations for CE-marked syndesmosis implants across their commercial lifecycle. Manufacturers must now generate proactive clinical evidence rather than reactive vigilance reporting. Small-to-mid portfolio sponsors face disproportionate resource allocation pressures to maintain market access.
Hospital GPO consolidation is compressing vendor negotiation leverage and standardizing implant selection around contracted portfolios. Orthopedic service line managers at integrated delivery networks are consolidating supplier relationships to administrative simplicity. The United States exhibits the most pronounced buyer concentration, with three national GPOs controlling procurement for a majority of trauma center beds.
Syndesmosis Repair System Market Segmentation
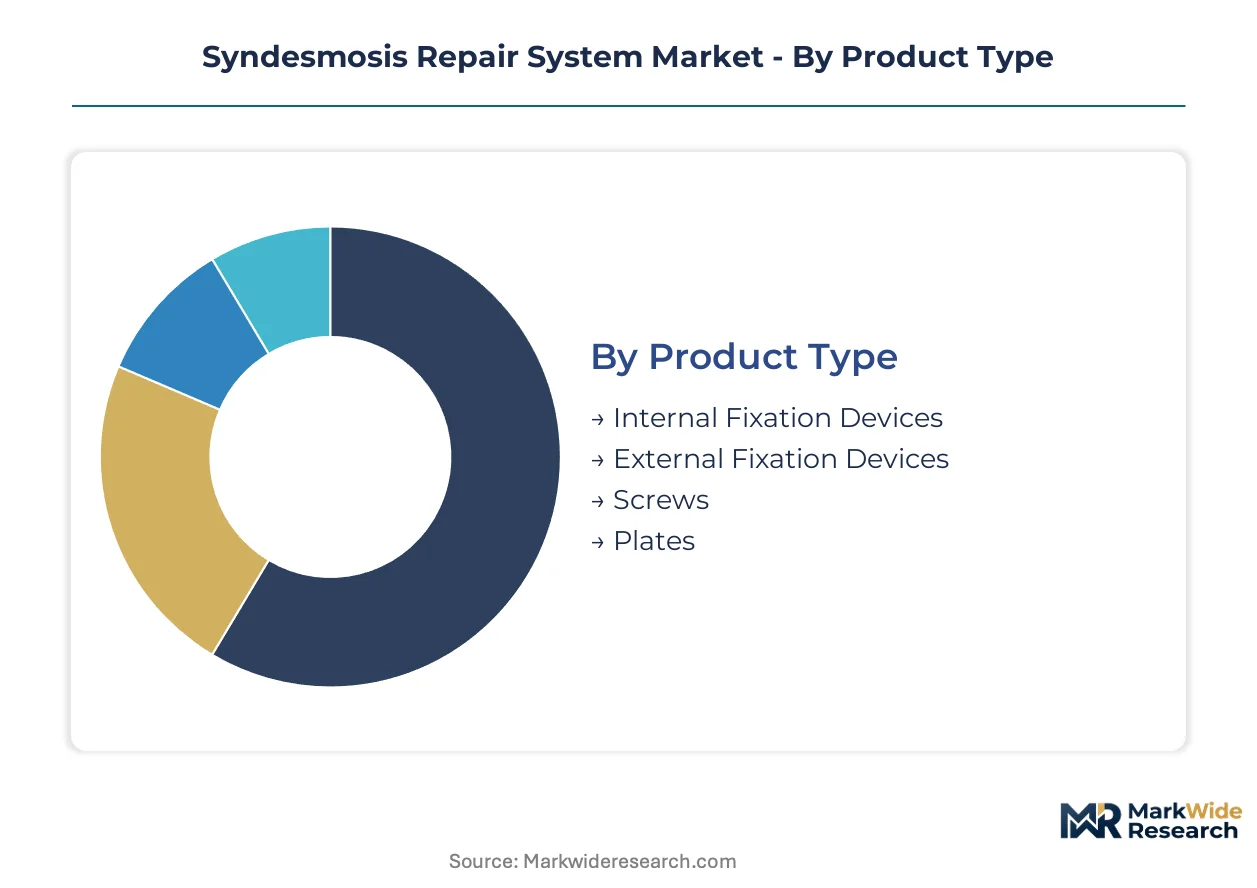
Product configuration and delivery mode selection directly determine reimbursement pathways and site-of-service economics in syndesmotic repair. Surgeons, facilities, and payors each impose distinct technical and commercial requirements that segment demand across implant categories and procedural approaches.
Product Type:
Channel mix varies sharply by fixation rigidity, with dynamic systems flowing through sports medicine distributors while rigid hardware concentrates in hospital GPO contracts.
- Internal Fixation Devices:Suture-button constructs utilizing ultra-high-molecular-weight polyethylene tape enable dynamic stabilization with retained physiologic motion. Trauma centers in the United States and Germany deploy these systems for athlete cohorts requiring accelerated return-to-play protocols.
- Screws:Titanium and cobalt-chrome cortical screws provide rigid syndesmotic compression with established biomechanical validation. Metal screw demand concentrates in community hospitals where surgeon familiarity and instrument availability outweigh dynamic fixation advantages.
- External Fixation Devices:Temporary spanning frames stabilize grossly unstable ankle fractures pending definitive internal fixation.
- Plates:Anterior and posterior tibiofibular plates address complex fracture-dislocation patterns with multiplanar stability.
Internal fixation devices dominate installed base. Suture-button systems are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive hospital systems from outpatient clinics operating on procedure-based reimbursement.
- Hospitals:Academic medical centers and trauma-designated facilities manage complex polytrauma with hybrid fixation approaches. These institutions command premium implant pricing through bundled payment structures and specialized surgeon concentration.
- Sports Medicine Facilities:Dedicated orthopedic centers serving professional and collegiate athletes generate disproportionate procedural volume for dynamic stabilization systems. Early weight-bearing protocols and implant removal avoidance drive technology preference in this segment.
- Orthopedic Clinics:Ambulatory settings perform select syndesmotic repairs under local or regional anesthesia protocols.
- Rehabilitation Centers:Post-acute facilities coordinate weight-bearing progression following surgical fixation.
Hospitals anchor procedure volume. Sports medicine facilities are climbing the fastest.
Application:
Volume concentration tracks injury mechanism, with high-energy trauma generating hardware-intensive cases and sports injuries favoring motion-preserving constructs.
- Trauma Surgery:High-energy ankle fracture-dislocations with syndesmotic disruption require anatomic reduction and stable fixation. Level I trauma centers in Japan and Germany manage these cases through multidisciplinary orthopedic teams.
- Sports Injuries:Low-velocity external rotation injuries in athletes drive demand for suture-button systems enabling early rehabilitation. Collegiate and professional sports medicine programs in the United States prioritize implant systems supporting accelerated return-to-competition timelines.
- Reconstruction Surgery:Revision fixation and delayed syndesmotic stabilization address failed initial repairs or chronic instability.
- General Surgery:Emergency department consultations and polytrauma protocols incorporate syndesmotic assessment.
Trauma surgery commands hardware expenditure. Sports injuries are gaining share fastest.
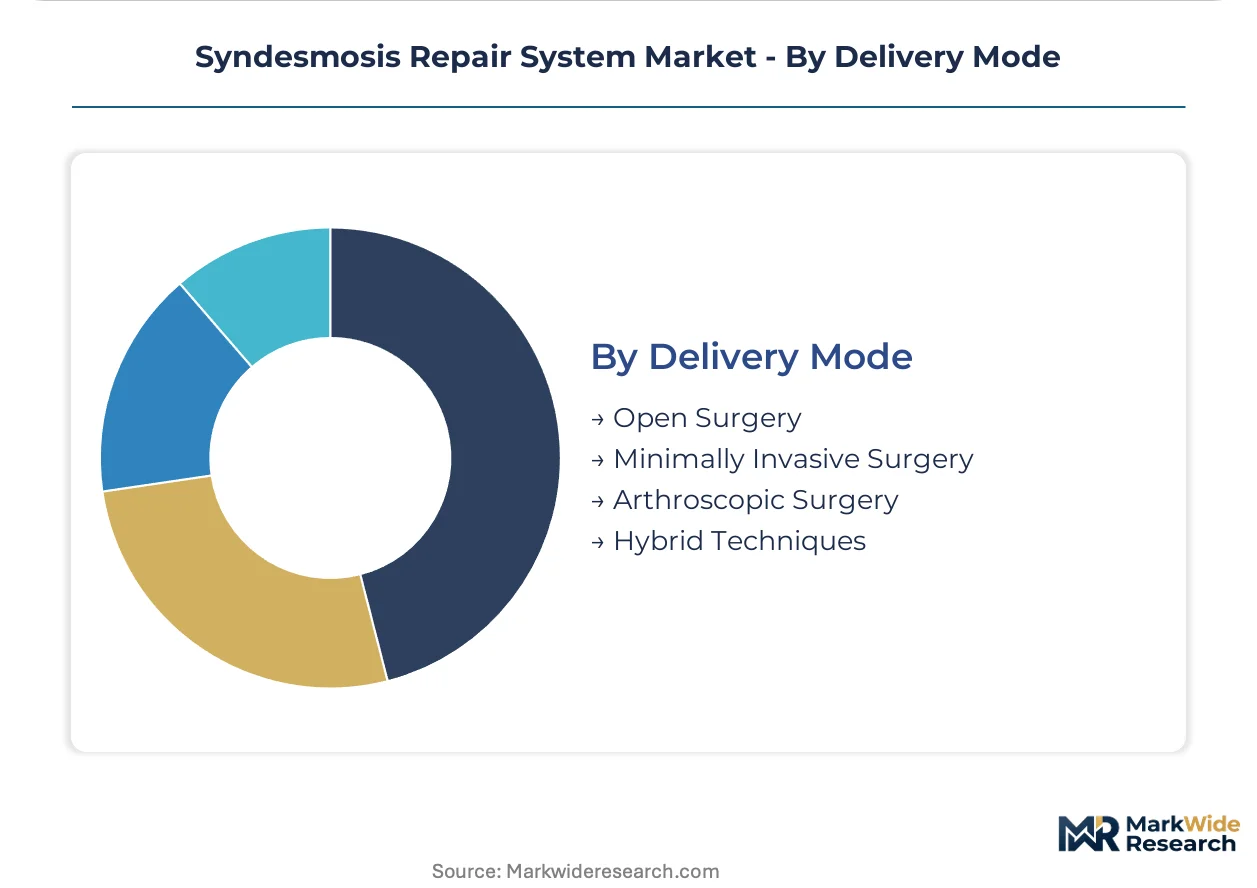
Delivery Mode:
Margin structure varies by procedural invasiveness, with arthroscopic techniques commanding premium pricing for visualization equipment and disposable instrument kits.
- Minimally Invasive Surgery:Percutaneous fixation techniques reduce soft-tissue morbidity and support outpatient migration. Ambulatory surgery centers in the United States deploy these approaches under CMS reimbursement alignment for site-of-service shift.
- Arthroscopic Surgery:All-inside syndesmosis repair with 4K visualization and radiofrequency ablation enables direct syndesmotic visualization. Fellowship-trained foot and ankle surgeons at academic medical centers pioneer these techniques.
- Open Surgery:Traditional anterior or posterior approaches to the distal tibiofibular joint remain standard for complex fracture patterns.
- Hybrid Techniques:Combined arthroscopic assessment with open reduction and internal fixation addresses multifocal ankle pathology.
Open surgery retains procedural dominance. Arthroscopic surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes syndesmosis repair systems through sports medicine channels at higher per-capita rates than trauma-heavy markets, while Japan and Germany concentrate volume in academic orthopedic centers with distinct reimbursement mechanics.
United States
Professional and collegiate athletic programs drive disproportionate demand for dynamic suture-button systems. FDA 510(k) premarket notification pathways compress registration timelines relative to European counterparts. Level I trauma centers in Texas and California anchor hardware-intensive procedural volumes for complex fracture-dislocation patterns.
Germany
Specialized foot and ankle surgery fellowships at university hospitals concentrate expertise and implant procurement authority. EU MDR notified-body oversight lengthens conformity assessment timelines for new product introductions. The Rhine-Ruhr and Bavarian industrial clusters host orthopedic distributor networks serving trauma-designated facilities across Central Europe.
Japan
Aging demographics and high-energy trauma in industrial workplaces sustain rigid fixation demand alongside emerging dynamic stabilization preferences. PMDA QMS conformity and foreign manufacturer registration requirements structure import pathways for multinational device sponsors. The Kanto region around Tokyo concentrates fellowship-trained surgeons and specialized orthopedic infrastructure.
United Kingdom
NHS England bundled payment structures and specialized commissioning frameworks concentrate syndesmotic repair volume in designated trauma centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining national market access. The Oxford and London academic hospital networks pioneer arthroscopic technique adoption for athlete cohorts.
Australia
TGA medical device registration and sponsor obligations govern import and distribution of orthopedic implants across public and private hospital systems. Rugby and Australian rules football injury patterns generate concentrated demand for motion-preserving fixation in athlete populations. Sydney and Melbourne metropolitan trauma networks anchor procedural volume and surgeon training pipelines.
Syndesmosis Repair System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the syndesmosis repair system market. Arthrex, Inc. and Zimmer Biomet occupy positions of scale through captive manufacturing and dense hospital contracting respectively, while mid-tier players compete on arthroscopic technique specialization and regional distributor relationships. Three archetypes define competitive positioning: vertically integrated suture manufacturers, trauma-focused hardware suppliers, and sports medicine specialists with visualization platform integration. M&A activity targets arthroscopic instrument portfolios, and strategic partnerships with academic medical centers secure surgeon training commitments.
Among the integrated leaders, Arthrex, Inc. and Zimmer Biomet exemplify divergent scale strategies—Arthrex through in-house polyethylene suture production and Zimmer Biomet through GPO contract density across North American trauma centers. Smith & Nephew occupies a position within the sports medicine specialist tier, representing the archetype of visualization-integrated system suppliers. These three companies anchor the competitive structure through which pricing, procurement, and technique adoption flow to downstream facilities.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Zimmer Biomet |
| Smith & Nephew |
| Stryker Corporation |
| Acumed LLC |
| DePuy Synthes |
| Paragon 28, Inc. |
| CONMED Corporation |
| Medacta International |
| Others |
Value Network & Pricing Analysis
Ninety-to-one-hundred-day EU MDR notified-body review queues compress pricing power for CE-marked device sponsors while concentrating procurement leverage among hospital GPOs with inventory buffer capacity. This lead-time asymmetry between regulatory jurisdictions feeds directly into contract-structure choices and supplier selection criteria across orthopedic implant distribution.
Pricing Analysis
Long-term offtake agreements with integrated delivery networks anchor premium pricing for suture-button systems, while spot purchasing dominates titanium screw procurement at community hospitals. Price differentiation hinges on FDA 510(k) predicate pathway efficiency and polyethylene suture tensile certification grades. Pricing pressure stems from metal screw substitution by dynamic fixation systems in athlete cohorts. Community hospital procurement committees exhibit highest price sensitivity; sports medicine facilities prioritize biomechanical performance over unit cost.
Supply Chain Analysis
The United States and Germany anchor high-tensile polyethylene suture braiding capacity, while Japan concentrates precision titanium forging for cortical screw production. Implant-grade titanium sponge and ultra-high-molecular-weight polyethylene fiber constitute critical input dependencies. Single-source vulnerability in EU MDR notified-body capacity creates regulatory chokepoint risk for CE-marked product launches. Distribution runs through orthopedic distributor networks serving trauma-designated facilities and sports medicine centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Suture-button dynamic stabilization represents a high-growth disruption in ankle fixation, with EU MDR clinical evidence requirements accelerating consolidation among sponsors with proactive post-market surveillance infrastructure.
For Market Incumbents: Secure GPO contract renewal cycles ahead of metal screw portfolio erosion by suture-button substitutes. Invest in captive polyethylene suture manufacturing to defend margin structures against component commoditization. Prioritize FDA 510(k) predicate device strategies to compress registration timelines relative to EU MDR conformity assessments. For New Entrants and Emerging Players: FDA 510(k) breakthrough pathway eligibility offers fastest regulatory entry for novel suture-button constructs with biomechanical equivalence data. Target ambulatory surgery center penetration in United States outpatient migration corridors. Lead with disposable instrument kits and streamlined implant configurations aligned with CMS site-of-service reimbursement. For Investors and Strategic Acquirers: Long-term, this sits as a sports medicine specialization play because athlete injury volume concentration and early weight-bearing protocol adoption create durable preference moats. Acquisition targets should demonstrate arthroscopic technique training infrastructure and academic medical center surgeon relationships. Monitor EU MDR notified-body queue duration as inflection indicator for CE-marked product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Predicate device strategies compress regulatory lead times relative to EU MDR conformity assessments. |
| Polyethylene Suture Backward Integration | Captive fiber braiding capacity insulates margin structures from component commoditization pressure. |
| Ambulatory Surgery Center Partnership | CMS reimbursement alignment for site-of-service shift creates white space for disposable instrument kits. |
| Arthroscopic Technique Training Infrastructure | Fellowship-trained surgeon pipelines differentiate premium system offerings in academic medical centers. |
| EU MDR Clinical Evidence Investment | Proactive post-market surveillance capabilities maintain CE-marked market access amid lengthening notified-body timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and sports medicine facility administrators. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified-body public reports, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up procedural volume estimates and top-down implant shipment data were triangulated to anchor market sizing.
Across the analysis window, forecasts were derived through segmented modeling across product type, delivery mode, end user, and application dimensions. CAGRs were computed from annualized growth trajectory analysis. Key inputs included athlete injury volume projections, arthroscopic technique adoption curves, and regulatory pathway efficiency differentials between FDA and EU MDR jurisdictions.
Decision-makers should treat outputs as directional under base assumptions of sustained sports medicine infrastructure investment and stable titanium input pricing; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in EU MDR notified-body capacity and CMS outpatient reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Polysomnography Devices Market