
 Facial Pumps Market | 2026-2036
Facial Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Pumps Market Foresight
Prestige skincare brands are unwinding legacy reliance on basic squeeze tubes and jars, redirecting formulation investments toward precision-dose dispensing systems. Aptar Group leverages its airless pump portfolio to capture premium positioning across North American and European cosmetic houses. Albéa S.A. anchors European supply chains through vertically integrated plastic and aluminum manufacturing in France and Poland. Lumson S.p.A. specializes in glass-compatible pump systems that serve fragrance and high-end skincare houses seeking material differentiation.
Facial pumps are precision-engineered dispensing mechanisms designed to meter controlled volumes of liquid, emulsion, or foam formulations through mechanical actuation, typically achieving dosage accuracy within 0.1–0.5 milliliters per stroke. These devices incorporate piston, spring, and valve assemblies molded from polypropylene or polyethylene to ensure chemical compatibility with active cosmetic ingredients. Airless pump systems command the strongest margin pools due to their oxygen-exclusion function that extends preservative-free product shelf life. Lotion pumps retain the largest volume footprint across mass-market skincare applications where cost efficiency outweighs advanced barrier requirements. Foaming pumps represent the fastest-expanding category as facial cleansers and whipped moisturizers gain formulation share in Asian and North American markets.
FDA cosmetic labeling requirements and EU REACH chemical restrictions jointly determine material eligibility for pump components contacting skin products. ECHA substance evaluations on microplastic additives are accelerating industry migration toward mono-material pump designs that simplify end-of-life recycling. ISO 8317 child-resistant standards and EU MDR-adjacent cosmetic safety frameworks add compliance layers that favor established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility schemes across European member states and pending US state-level packaging legislation that will reshape cost structures and supplier qualification timelines.
Market Dynamics
Prestige skincare houses are abandoning jars and squeeze tubes for precision-dose airless systems that extend preservative-free shelf life while satisfying EU microplastic restrictions. This format migration is compressing supplier margins on legacy lotion pumps while rewarding engineered barrier technologies.
Growth Catalysts
- EU REACH microplastic restrictions:ECHA substance evaluations are forcing rapid reformulation of pump seals and valve components toward mono-material polypropylene designs that simplify end-of-life recycling streams.
- Airless oxygen-exclusion technology:Premium cosmetic houses in Germany and France are specifying piston-based vacuum systems for retinol and vitamin C formulations that degrade upon air contact.
- Foaming cleanser formulation share:whipped texture facial cleansers across South Korean and North American markets are accelerating demand for mesh-foam pump mechanisms that aerate liquid into dense micro-bubbles.
Market Restraints
- Aluminum and polymer input volatility:pump housing production faces margin pressure from fluctuating polypropylene resin and aluminum billet pricing that compresses fixed-contract manufacturer profitability.
- European supply concentration:airless pump diaphragm and spring assembly production clusters heavily in northeastern France and southern Poland, creating single-source vulnerability for brands qualifying alternative suppliers.
- Technical limitation in glass compatibility:precision thread tolerance matching between metal pumps and molded glass fragrance bottles remains unresolved for small-batch artisan houses.
Strategic Opportunities
- Underpenetrated Indian prestige skincare:domestic cosmetic houses in Mumbai and Delhi are beginning to specify airless formats for ayurvedic actives previously packaged in basic jars, opening white-space for technical pump suppliers.
- Regulatory tailwind from EU Green Deal packaging mandates:extended producer responsibility schemes across German and Italian member states are creating preferential procurement channels for recyclable mono-material pump systems.
- Technology convergence of connected dispensing:Bluetooth-enabled dose-counters integrated into premium serum pumps are enabling refill-subscription models that lock in recurring formulation revenue for cosmetic brands.
Industry Challenges
- Regulatory affairs talent scarcity:qualified professionals capable of navigating simultaneous FDA cosmetic labeling and EU REACH substance dossier requirements command premium compensation that strains mid-tier pump manufacturer overhead.
- Capex intensity of cleanroom molding:medical-grade cosmetic pump production requires ISO 14644 Class 7 injection molding environments that demand seven-figure facility investments.
- ISO 8317 child-resistant certification timelines:multi-month testing protocols for push-and-turn locking mechanisms delay new product launches and freeze working capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Pumps Market |
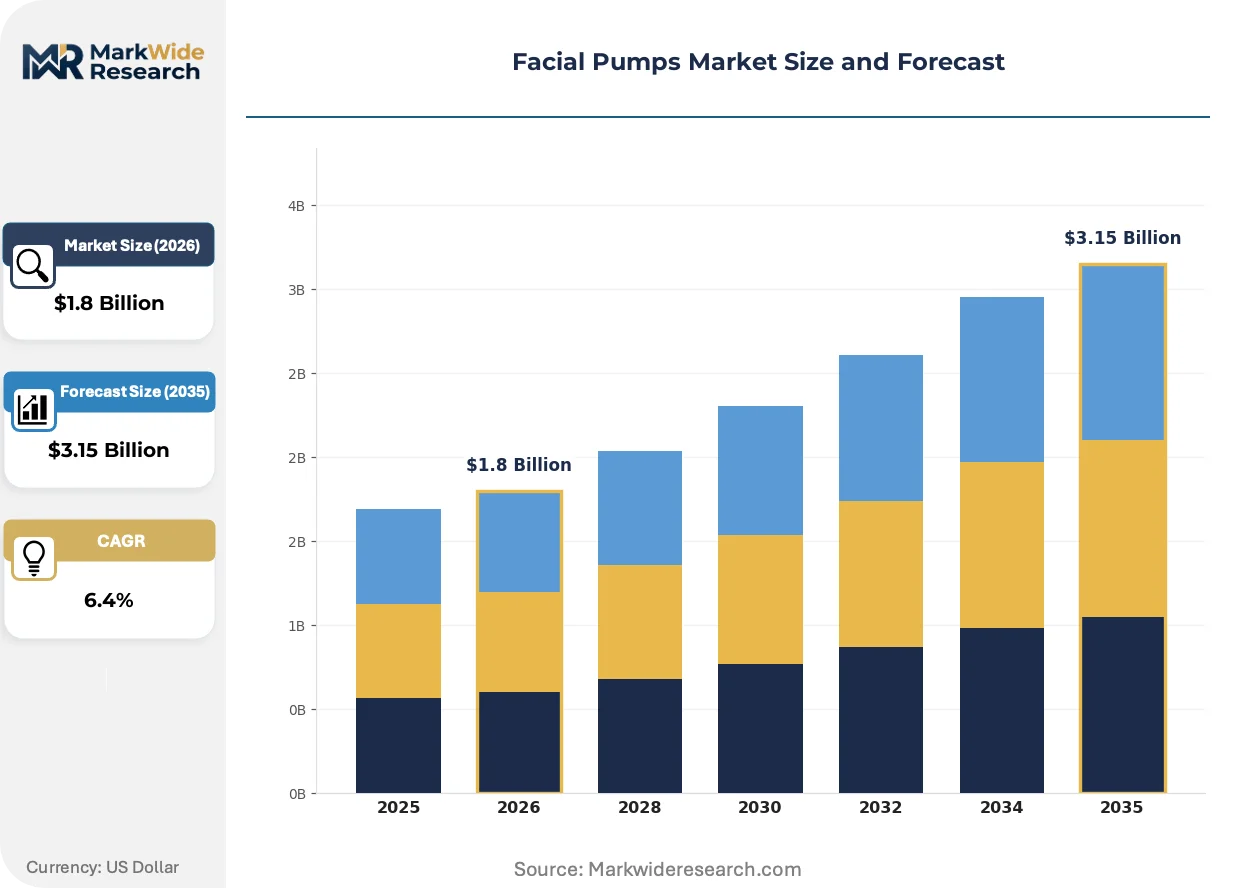
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foaming Pumps, Lotion Pumps, Airless Pumps, Spray Pumps Material: Plastic, Glass, Metal, Aluminum Application: Cosmetics, Skincare, Fragrance, Sunscreen End User: Retail Stores, Online Retailers, Salons, Spa Centers |
| Companies Covered | Aptar Group, Inc., Albéa S.A., Lumson S.p.A., Silgan Dispensing Systems, Rieke Corporation, APackaging Group, Berry Global Group, Frapak Packaging, Quadpack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Pumps Market Shifts & Advancements
Active cosmetic ingredient instability is driving rapid format experimentation. Suppliers are engineering mechanical solutions that replace chemical preservation while regulatory pressure accelerates material transparency requirements.
Silicone-free pump diaphragm elastomers are miniaturizing. These fluoropolymer alternatives eliminate peroxide-cure residues that contaminate clean beauty formulations. Korean skincare OEMs are specifying them for centella and propolis serums. The technology is miniaturizing component footprints while maintaining barrier integrity, enabling sleeker packaging profiles that differentiate shelf presence.
EU ECHA microplastic restriction amendments are tightening additive prohibitions. Industrial consequence includes accelerated phase-out of glitter and microbead carriers previously used in decorative pump-dispensed products. Color cosmetic segments targeting German and French teenagers are most affected, responding with cellulose-based replacement particles that require redesigned valve clearances.
Direct-to-consumer refill subscriptions are fragmenting traditional wholesale procurement. Prestige skincare houses are bypassing retail distributors to ship concentrated refill pouches paired with permanent airless pumps. This pattern is most visible in North American urban markets where Sephora and Ulta shelf access no longer determines brand viability.
Facial Pumps Market Segmentation
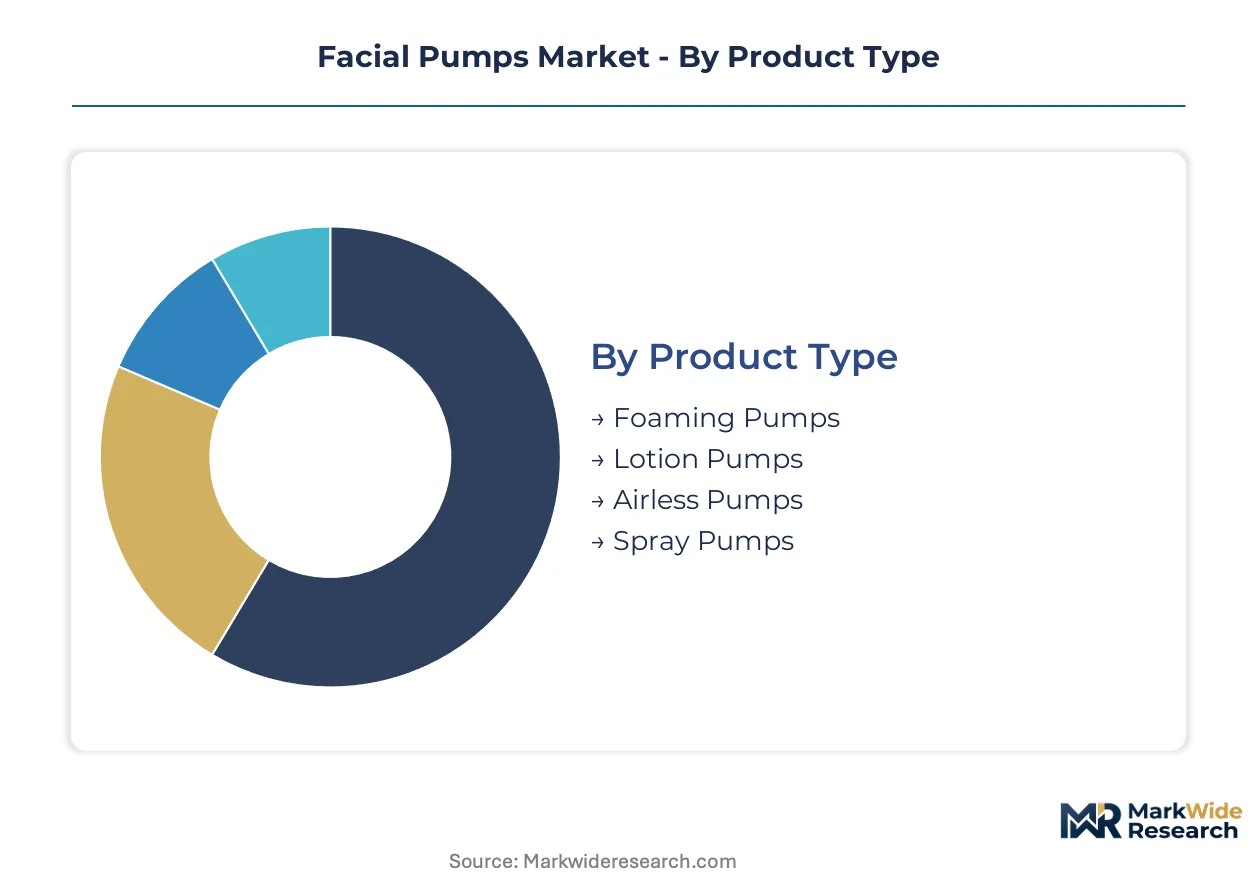
Facial pump procurement decisions diverge sharply across end-use contexts. Brand houses select formats based on formulation chemistry, shelf-life requirements, and regulatory pressure rather than unit cost alone.
Product Type:
Substitution pressure from airless systems is compressing legacy pump margins as preservative-free formulations displace conventional packaging across European and North American prestige markets.
- Foaming Pumps:Mesh-foam mechanisms aerate liquid cleansers into dense micro-bubbles through mechanical agitation without propellants. South Korean and North American skincare houses specify these for whipped facial cleansers and cloud-texture moisturizers as texture innovation drives format preference.
- Lotion Pumps:Standard piston-spring assemblies deliver 0.5–2.0 milliliter doses through dip-tube configurations. Mass-market skincare applications in Germany and France continue absorbing the highest unit volumes despite margin compression from commodity resin pricing.
- Airless Pumps:Vacuum-sealed piston systems exclude oxygen to extend retinol and vitamin C stability without synthetic preservatives. Premium cosmetic specifications are climbing fastest across German dermocosmetic houses.
- Spray Pumps:Fine-mist actuators deliver atomized application for toners and thermal waters. Fragrance houses in Italy and France favor these for alcohol-based formulations requiring even dispersion patterns.
Lotion pumps retain volume leadership; foaming pumps hold the steepest expansion curve.
Material:
EU REACH substance evaluations are forcing rapid material transitions as ECHA restrictions eliminate legacy polymer additives from cosmetic-contact components.
- Plastic:Polypropylene and polyethylene dominate pump housing and piston production due to chemical inertness with acidic and alkaline formulations. German and Polish injection molders are consolidating supply as mono-material designs simplify recycling compliance.
- Aluminum:Lightweight metal housings and actuator collars serve premium positioning requirements across French fragrance houses. Italian suppliers are expanding extrusion capacity to capture refill-system demand.
- Glass:Molded fragrance bottles require precision thread tolerances for metal pump attachment. Technical limitations in small-batch artisan production constrain adoption outside established luxury houses.
- Metal:Stainless steel springs and valve components provide mechanical durability in high-actuation environments. Cost premiums limit deployment to professional salon formats.
Plastic retains volume leadership; aluminum holds the steepest expansion curve.
Application:
Formulation chemistry determines barrier requirements, with oxygen-sensitive actives driving specification upgrades across prestige segments.
- Skincare:Retinol, vitamin C, and peptide formulations require airless oxygen-exclusion to prevent oxidation degradation. German dermocosmetic brands are mandating piston-based vacuum systems for preservative-free product lines.
- Cosmetics:Color formulations and primers utilize standard lotion pumps where chemical stability concerns are minimal. Mass-market volume concentrates in French and Italian manufacturing clusters.
- Fragrance:Fine-mist spray pumps deliver controlled atomization for alcohol-based perfumes. Glass compatibility requirements favor established European suppliers with precision threading expertise.
- Sunscreen:High-viscosity emulsions demand reinforced spring mechanisms to maintain dose consistency. Seasonal demand patterns in Mediterranean markets create inventory management complexity.
Skincare retains volume leadership; sunscreen holds the steepest expansion curve.
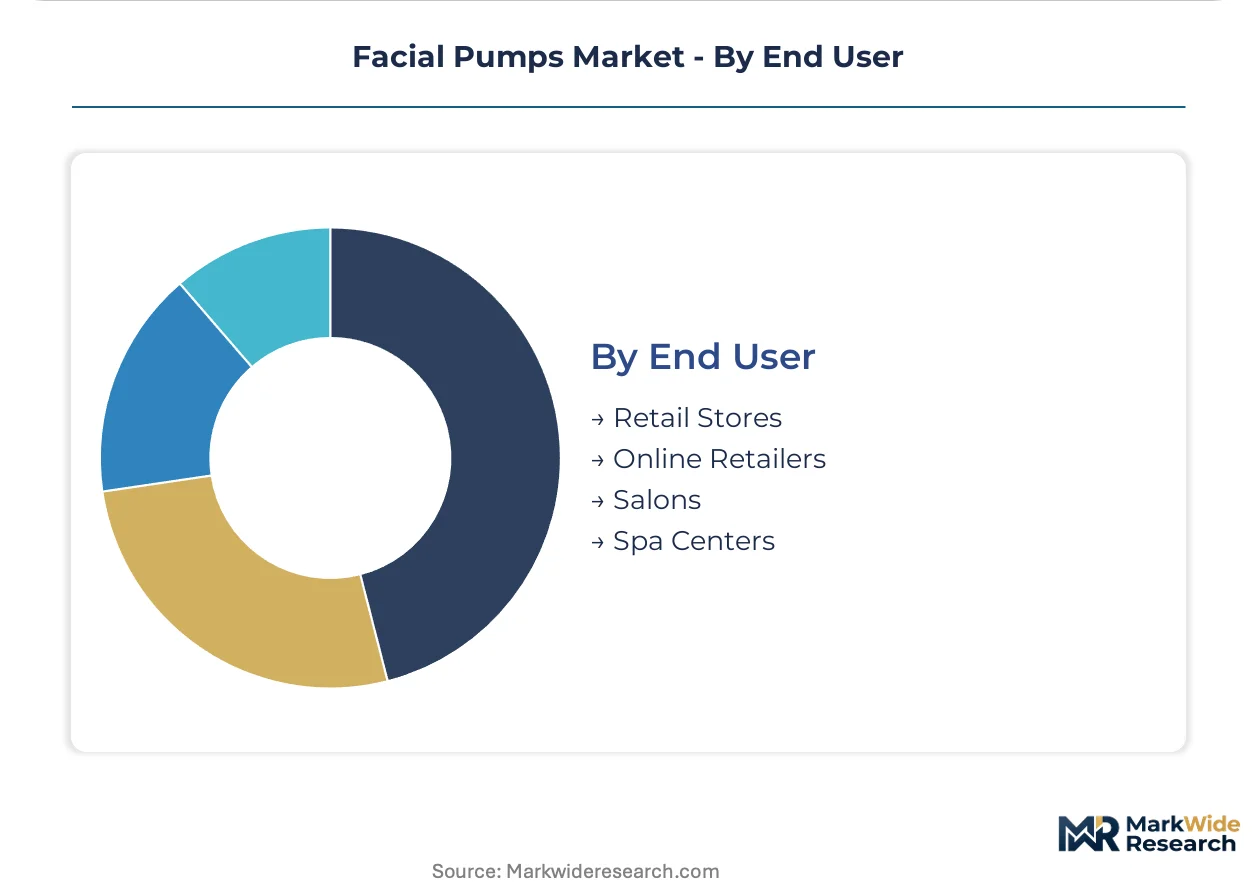
End User:
Channel structure is fragmenting as direct-to-consumer refill subscriptions bypass traditional wholesale procurement across North American urban markets.
- Online Retailers:E-commerce fulfillment requires damage-resistant pump designs that survive individual parcel shipping. Subscription refill models are concentrating demand for permanent airless pumps paired with concentrate pouches.
- Retail Stores:Sephora and Ulta shelf placement still determines mass-market brand viability. Tester pump durability requirements favor metal-spring mechanisms over all-plastic alternatives.
- Salons:Professional back-bar formats demand high-actuation durability and bulk refill compatibility. Italian professional skincare distributors specify reinforced commercial-grade pumps.
- Spa Centers:Treatment-room applications favor hygienic single-use or sanitized pump systems. Premium positioning supports higher unit economics for engineered barrier technologies.
Retail stores retain volume leadership; online retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European cosmetic packaging distribution, while the Trans-Siberian Railway link enables polymer resin flows into Central European injection molding clusters. These infrastructure assets shape regional supply configurations for precision dispensing systems.
United States
FDA cosmetic labeling requirements and Sephora's clean beauty standards drive specification upgrades for preservative-free formulations. State-level extended producer responsibility legislation in California and New York is accelerating mono-material pump procurement. New Jersey's pharmaceutical corridor hosts compounding facilities that source medical-grade dispensing systems for dermocosmetic crossover products.
Germany
ECHA REACH substance evaluations are eliminating silicone-based pump diaphragm elastomers from cosmetic-contact components. The EU Green Deal packaging mandates create preferential procurement channels for recyclable mono-material systems. Baden-Württemberg's precision engineering cluster around Stuttgart concentrates airless pump spring assembly production for dermocosmetic houses.
France
ANSM cosmetic safety frameworks add compliance layers favoring established manufacturers with dedicated regulatory affairs capacity. The country's national packaging regulator enforces strict extended producer responsibility schemes through Citeo. Grasse's fragrance manufacturing tradition anchors demand for fine-mist spray pumps with precision glass threading.
Italy
Lombardy's cosmetic manufacturing belt around Milan specifies glass-compatible pump systems for fragrance and high-end skincare houses seeking material differentiation. ECHA microplastic restriction amendments are tightening additive prohibitions on decorative pump-dispensed products. Bologna's professional salon distributors source reinforced commercial-grade pumps for back-bar formats.
South Korea
MFDS cosmetic safety standards and K-beauty texture innovation accelerate mesh-foam pump adoption for whipped facial cleansers. Seoul's skincare OEMs specify silicone-free fluoropolymer diaphragm alternatives for centella and propolis serums. Incheon's port infrastructure enables rapid formulation-to-packaging turnaround for trend-responsive beauty brands.
Facial Pumps Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and cleanroom manufacturing scale. The vendor base stratifies into three tiers: multinational packaging conglomerates with full regulatory affairs departments, mid-cap European specialists with captive molding capacity, and Asian contract manufacturers serving cost-sensitive volume segments. Dominant competitive moves include backward integration into polymer resin compounding and technology licensing agreements for connected dispensing systems.
Within the multinational tier, Aptar Group, Inc. exemplifies the listed leader archetype with its airless pump portfolio positioning across North American and European cosmetic houses. Albéa S.A. and Lumson S.p.A. represent private specialist anchors, with the former's vertically integrated plastic and aluminum manufacturing in France and Poland and the latter's glass-compatible specialization serving fragrance and high-end skincare differentiation requirements. These three occupy positions that reflect divergent scale-regulation tradeoffs in precision dispensing.
| Leading Market Players |
|---|
| Aptar Group, Inc. |
| Albéa S.A. |
| Lumson S.p.A. |
| Silgan Dispensing Systems |
| Rieke Corporation |
| APackaging Group |
| Berry Global Group |
| Frapak Packaging |
| Quadpack |
| Others |
Supply & Pricing Matrix
EU REACH substance dossier requirements gate both supplier qualification timelines and price differentiation tiers simultaneously, compressing mid-tier manufacturers unable to absorb regulatory affairs overhead while rewarding certified incumbents with premium positioning power across German and French procurement channels.
Pricing Analysis
Volume-discount tiering separates medical-grade cleanroom-certified pumps from standard cosmetic-grade and economy mass-market alternatives across European supply contracts. Price differentiation hinges on ISO 14644 Class 7 certification status and captive resin compounding capabilities that insulate against polypropylene input volatility. Pricing pressure intensifies in the standard tier as Asian contract manufacturers undercut Polish and French molders on basic lotion pump assemblies. Mass-market skincare houses exhibit highest price sensitivity, while German dermocosmetic brands prioritize barrier performance over unit cost.
Supply Chain Analysis
Inventory lead times for precision spring assemblies extend disproportionately during ECHA evaluation windows as northeastern French and southern Polish suppliers freeze production pending material requalification. Manufacturing concentrates in Germany, France, and Poland for airless pump diaphragms, with Italian extruders expanding aluminum collar capacity for refill systems. Raw material flows draw from Saudi polypropylene resin and Russian aluminum billet sources vulnerable to tariff exposure. Distribution runs through Rotterdam port consolidation and Trans-Siberian rail links into Central European molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from connected dispensing systems and mono-material pump architectures that displace legacy multi-component designs across EU Green Deal procurement mandates.
For Market Incumbents: Fortify regulatory affairs capacity to navigate simultaneous FDA cosmetic labeling and EU REACH substance dossier requirements, compressing qualification timelines that freeze working capital. Deepen backward integration into polypropylene resin compounding to capture margin pools eroded by commodity pricing volatility. Defend against Asian contract manufacturer encroachment by leveraging existing ISO 8317 child-resistant certification relationships with Sephora and Ulta procurement teams. For New Entrants and Emerging Players: Connected-dispensing technical service layers remain underdeveloped by established pump manufacturers focused on mechanical rather than electronic integration. Target Indian prestige skincare houses in Mumbai and Delhi specifying airless formats for ayurvedic actives previously packaged in basic jars. Pursue white-label partnerships with Seoul-based OEMs seeking silicone-free fluoropolymer diaphragm alternatives for centella and propolis serums. For Investors and Strategic Acquirers: EU ECHA microplastic restriction amendments reshape the acquisition landscape toward mono-material pump specialists with established recycling compliance documentation. Long-term viability centers on suppliers capable of serving both preservative-free formulation trends and extended producer responsibility scheme mandates across German and Italian member states. Target mid-cap European specialists with captive cleanroom molding capacity and dedicated regulatory affairs departments. Monitor ECHA substance evaluation timelines as inflection indicators for supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates German molders from commodity price volatility compressing fixed-contract margins. |
| Cleanroom Capacity Expansion | ISO 14644 Class 7 injection molding environments qualify suppliers for medical-grade cosmetic pump specifications at premium tiers. |
| Connected Dispensing Technology Licensing | Bluetooth-enabled dose-counters enable refill-subscription revenue models for North American prestige skincare houses. |
| Mono-Material Design Requalification | Single-polypropylene pump architectures satisfy EU Green Deal recycling mandates across French and Italian procurement channels. |
| Regulatory Affairs Talent Acquisition | Dedicated compliance teams accelerate ECHA dossier preparation and FDA cosmetic labeling approval timelines. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic packaging procurement managers, regulatory affairs directors at pump manufacturers, formulation chemists at prestige skincare houses, and injection molding operations leads, then refined through secondary validation against ECHA substance evaluation databases, FDA cosmetic labeling guidance documents, EU Green Deal packaging mandate texts, and customs trade flow records for polypropylene resin and aluminum billet movements. Bottom-up unit economics from individual pump specifications were triangulated against top-down market sizing from regional manufacturing cluster outputs.
Variance decomposition across product type, material composition, application chemistry, and end-user channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating formulation shift patterns toward preservative-free and oxygen-sensitive actives. Industry-specific inputs included ECHA microplastic restriction implementation timelines and MFDS cosmetic safety standard evolution patterns across South Korean skincare OEMs.
Underlying assumptions cover sustained EU REACH enforcement intensity and stable Trans-Siberian rail freight capacity, with deviation risk concentrated in polypropylene resin tariff escalations and accelerated ECHA additive prohibition schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wheelchair and Components Market
Medical Devices
Organ Preservation Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Walking Aids Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Sialendoscopes Market
Medical Devices
Global Cosmetic Contact Lens Market