
 Asia-Pacific Radiotherapy Market | 2026-2036
Asia-Pacific Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Radiotherapy Market Insights
Patient referral patterns is shifting toward dedicated cancer clinics across Southeast Asia and Oceania. Varian Medical Systems dominates linear accelerator installations through extensive service networks. Elekta AB anchors proton therapy development with specialized research partnerships. Siemens Healthineers leverages imaging-radiotherapy integration to differentiate its portfolio.
Radiotherapy encompasses external beam radiation, brachytherapy, and systemic radioisotope therapy delivered via linear accelerators generating 6-25 MV photon beams to destroy malignant tissue while sparing adjacent organs. Linear accelerators command the largest installed base, while proton therapy segments attract premium investment despite higher capital requirements. Intensity Modulated Radiation Therapy leads technology adoption in mature markets, whereas stereotactic radiotherapy grows fastest in neuro-oncology applications across Japan and Australia.
Japan's PMDA and Australia's TGA enforce stringent device approval pathways that extend market entry timelines for imported equipment. India's CDSCO and China's NMPA are streamlining clinical trial requirements for domestically manufactured radiotherapy systems. South Korea's MFDS accelerates novel technology assessment through priority review tracks. Stakeholders must monitor reimbursement harmonization across national health insurance schemes as treatment protocols standardize regionally.
Market Dynamics
Linear accelerator supply concentration among three dominant vendors is reshaping procurement leverage for oncology departments across tertiary hospitals in China, Japan, and South Korea. Equipment vendors now bundle software upgrades and service contracts into multi-year agreements, locking in hospital budgets and limiting competitive substitution.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturing incentives accelerate local production of linear accelerators, reducing import dependency and shortening deployment timelines for government-funded cancer centers.
- Intensity Modulated Radiation Therapy protocols:Clinical standardization across Australia's TGA-approved facilities drives replacement cycles for aging cobalt-60 units with modern linear accelerator systems.
- Neuro-oncology specialization:Stereotactic radiotherapy applications expand rapidly in Japanese academic medical centers, creating dedicated installation demand separate from general external beam capacity.
Market Restraints
- Capital intensity barriers:Proton therapy systems require USD 100 million-plus facility investments, restricting deployment to single national referral centers in Australia, Japan, and South Korea.
- Extended regulatory pathways:Japan's PMDA enforces lengthy clinical evidence requirements for imported linear accelerator software updates, delaying feature parity with Western installations.
- Specialized physicist scarcity:Treatment planning system complexity outpaces training program output across Southeast Asia, capping utilization rates at installed capacity.
Strategic Opportunities
- Vietnam and Indonesia hospital buildouts:Greenfield oncology wing construction in Ho Chi Minh City and Jakarta creates first-mover positioning for linear accelerator vendors before competitor saturation.
- Imaging-radiotherapy convergence:MRI-guided linear accelerator integration enables real-time adaptive therapy, commanding premium pricing from high-volume centers in Seoul and Tokyo.
- CDSCO streamlined trials:India's revised clinical investigation rules for domestically manufactured radiotherapy equipment accelerate market authorization versus imported device pathways.
Industry Challenges
- Medical physicist training pipeline gaps:Australia's TGA-mandated credentialing requirements exceed university program graduation rates, forcing centers to recruit from UK and Canadian markets.
- Legacy cobalt-60 unit interoperability:Brachytherapy afterloader systems from the 1990s lack digital connectivity with contemporary oncology information systems, complicating unified patient record management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Radiotherapy Market |
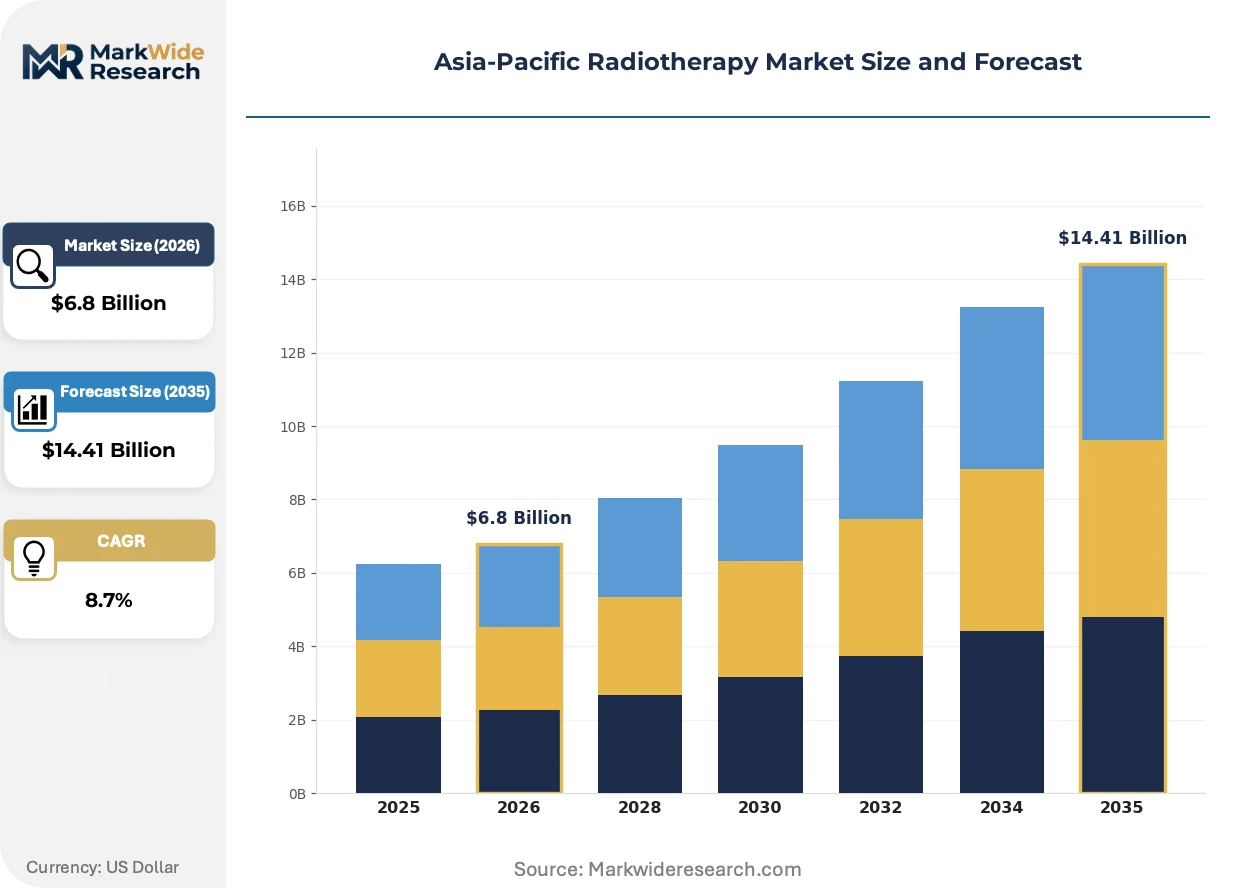
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Imaging Systems, Treatment Planning Systems End User: Hospitals, Cancer Clinics, Research Institutions, Medical Centers Technology: 3D Conformal Radiation Therapy, Intensity Modulated Radiation Therapy, Stereotactic Radiotherapy, Proton Therapy Application: Oncology, Cardiovascular Diseases, Pediatrics, Gynecology |
| Companies Covered | Varian Medical Systems Inc., Elekta AB, Accuray Incorporated, RaySearch Laboratories AB, Ion Beam Applications SA, Mevion Medical Systems Inc., Siemens Healthineers GmbH, IBA Worldwide, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Radiotherapy Market Trends and Innovations
Artificial intelligence is embedding into treatment planning workflows across Asia-Pacific radiotherapy departments, compressing planning time from days to hours while raising software dependency on vendor-specific platforms. This shift reconfigures staffing models and creates new vendor lock-in dynamics.
Adaptive radiotherapy software powered by on-board imaging is consolidating treatment margins around moving tumors, particularly in lung and prostate applications. Major cancer centers in Osaka and Sydney deploy these systems for daily plan recalculation. The technology is consolidating vendor market share toward integrated hardware-software providers capable of real-time dose reconstruction.
South Korea's MFDS operates priority review tracks for novel radiotherapy technologies including FLASH therapy and carbon-ion systems, compressing approval timelines versus standard device pathways. Domestic manufacturers Samsung and VUNO leverage this framework to accelerate market entry. High-acuity centers in Seoul and Busan respond by establishing early-adopter partnerships with prioritized vendors.
Hospital procurement committees now unbundle linear accelerator hardware from multi-year service agreements, soliciting independent physics support contracts and third-party software subscriptions. This pattern disrupts traditional vendor-captive service models. The behavior is most visible in Australia's public hospital networks, where state-level purchasing consortia standardize equipment specifications while fragmenting maintenance vendor selection.
Asia-Pacific Radiotherapy Market Segmentation
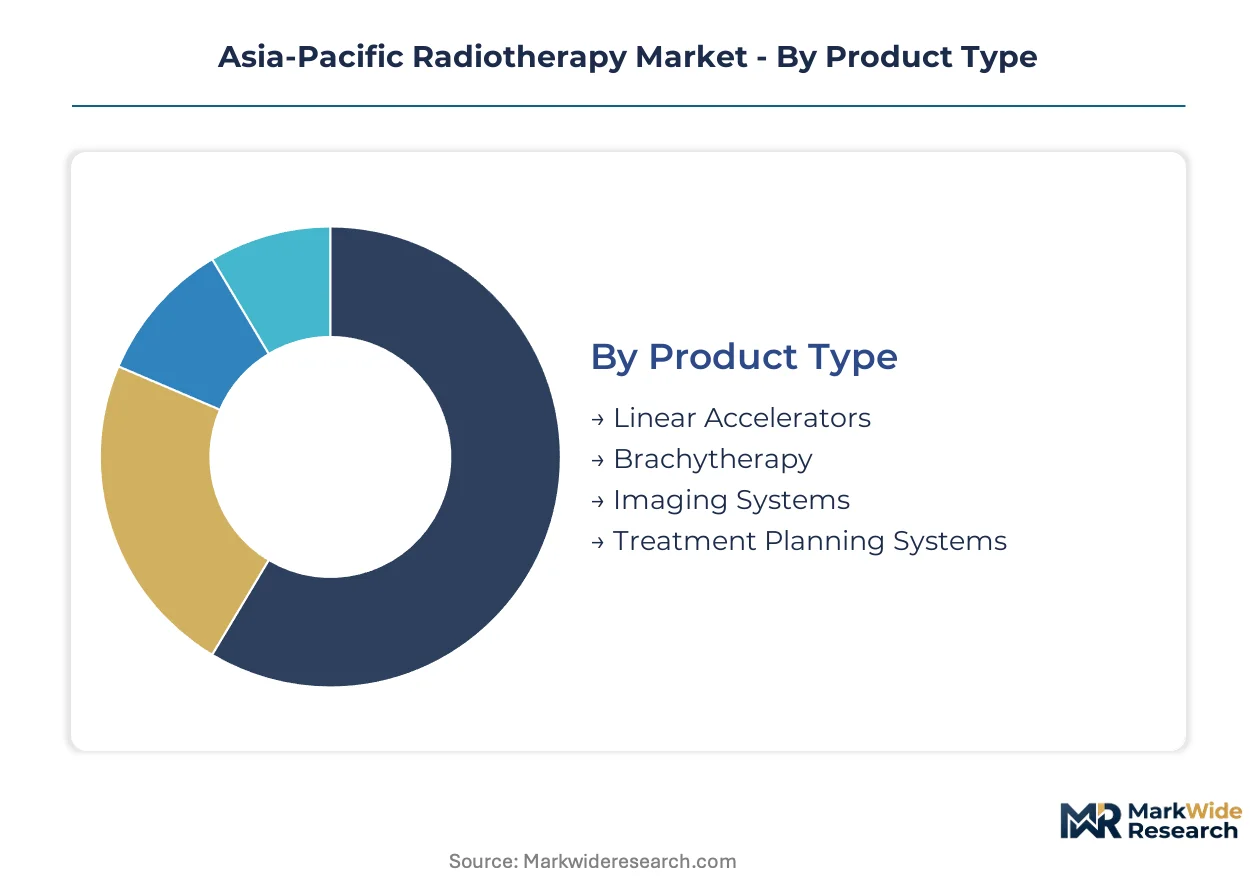
Radiotherapy market segmentation reveals how technology specialization, clinical application, and care delivery setting interact to shape procurement patterns across Asia-Pacific cancer centers. Understanding these intersecting dimensions enables vendors to align product portfolios with specific capacity-building priorities in government-funded hospital networks.
Product Type:
Equipment specifications determine capital deployment scale and service revenue potential for oncology infrastructure projects.
- Linear Accelerators:These systems generate 6-25 MV photon beams for external beam radiation, forming the backbone of radiation oncology departments across tertiary hospitals in China, Japan, and South Korea. China's NMPA streamlined approval pathways for domestically manufactured units are accelerating replacement cycles for aging cobalt-60 installations in provincial cancer centers.
- Brachytherapy:Internal radiation delivery via implanted radioactive sources targets cervical, prostate, and breast malignancies with precision dosing. Demand concentrates in India's government-funded cancer centers where CDSCO regulatory clarity on afterloader systems is shortening procurement timelines for public hospital networks.
- Imaging Systems:On-board CT and MRI integration enables real-time tumor visualization during treatment delivery.
- Treatment Planning Systems:Software platforms calculate beam angles and dose distributions, with AI-embedded workflows gaining traction in Japanese academic medical centers.
Linear accelerators lead on scale; imaging systems lead on momentum as MRI-guided adaptive therapy gains clinical adoption.
End User:
Facility type dictates equipment configuration complexity and reimbursement pathway structure.
- Hospitals:Tertiary oncology departments in China, Japan, and South Korea house the majority of installed linear accelerator capacity, with China's 13th Five-Year Cancer Control Plan driving equipment standardization across provincial hospital networks. India's PLI scheme for medical devices is redirecting procurement toward domestically manufactured systems in public hospital settings.
- Cancer Clinics:Dedicated radiation therapy facilities in Vietnam and Indonesia are emerging as first-mover opportunities for vendors before competitor saturation in Ho Chi Minh City and Jakarta greenfield developments.
- Research Institutions:Academic medical centers in Osaka and Seoul pilot FLASH therapy and carbon-ion systems through South Korea's MFDS priority review tracks.
- Medical Centers:Multi-specialty facilities integrate radiotherapy with surgical and medical oncology services.
Hospitals dominate installed base volume; cancer clinics are climbing the fastest as referral patterns shift toward dedicated radiation therapy facilities.
Technology:
Clinical protocol standardization drives replacement cycles and software upgrade trajectories across mature versus emerging markets.
- Intensity Modulated Radiation Therapy:Beam intensity modulation sculpts radiation dose to tumor contours while sparing adjacent organs, now standard-of-care across Australia's TGA-approved facilities. Australia's public hospital purchasing consortia are unbundling hardware procurement from service agreements as IMRT protocol standardization enables vendor substitution.
- Stereotactic Radiotherapy:High-precision, high-dose fractionation targets intracranial and extracranial lesions with sub-millimeter accuracy. Japanese academic medical centers are expanding dedicated neuro-oncology installations separate from general external beam capacity, with PMDA regulatory pathways shaping software feature parity timelines.
- 3D Conformal Radiation Therapy:CT-based planning enables geometric beam shaping for simpler treatment geometries.
- Proton Therapy:Charged particle beams deposit dose at Bragg peak depths, requiring USD 100 million-plus facility investments restricted to single national referral centers in Australia, Japan, and South Korea.
Intensity modulated radiation therapy leads on scale; stereotactic radiotherapy is gaining share fastest in neuro-oncology specialization.
Application:
Disease-specific treatment protocols determine equipment configuration requirements and physicist specialization needs.
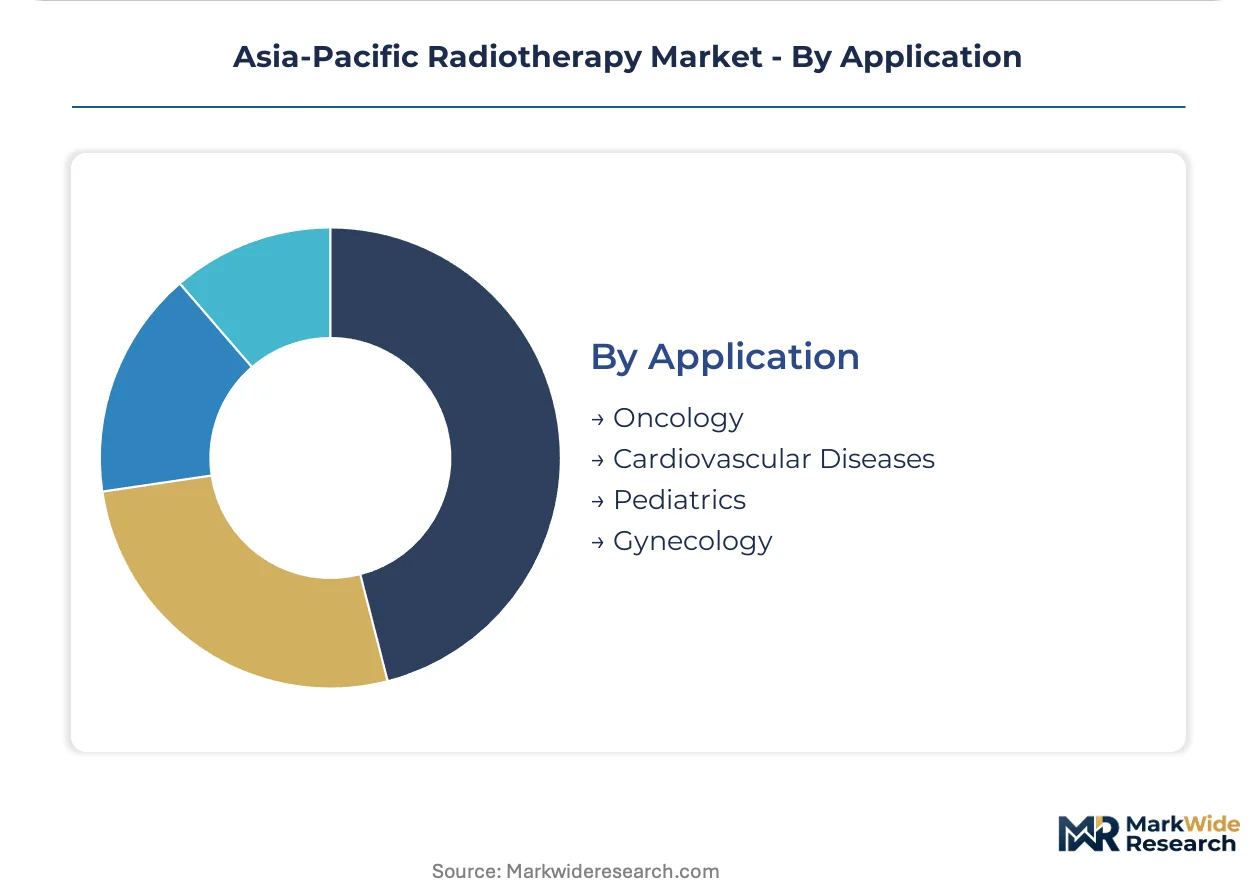
- Oncology:Solid tumor and hematologic malignancy treatment consumes the overwhelming majority of radiotherapy capacity across Asia-Pacific, with lung, prostate, and breast applications driving linear accelerator utilization rates. China's NMPA and India's CDSCO are streamlining clinical trial requirements for domestically manufactured systems targeting high-volume oncology indications.
- Pediatrics:Age-appropriate dosing protocols and long-term toxicity monitoring requirements shape equipment selection in specialized children's hospitals across Japan and Australia.
- Gynecology:Cervical and endometrial malignancy brachytherapy applications concentrate in Southeast Asian hospital networks.
- Cardiovascular Diseases:Emerging applications in arrhythmia and vascular malformation treatment remain investigational across most Asia-Pacific markets.
Oncology dominates absolute treatment volume; pediatrics shows the steepest expansion trajectory as proton therapy enables reduced late-effect dosing in growing patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting radiotherapy equipment manufacturing toward jurisdictions with streamlined clinical trial frameworks. India's CDSCO and China's NMPA now offer faster market authorization pathways than Japan's PMDA for domestically produced linear accelerators. This compliance-cost gap accelerates capacity buildout across South and East Asia.
China
Provincial cancer centers under the 13th Five-Year Cancer Control Plan are replacing aging cobalt-60 units with modern linear accelerator systems. NMPA streamlined approval pathways for domestically manufactured equipment shorten deployment timelines versus imported device pathways. The Yangtze River Delta cluster around Shanghai houses the highest concentration of radiotherapy installations, with municipal hospitals expanding dedicated oncology wings.
Japan
Academic medical centers in Osaka and Tokyo are establishing separate neuro-oncology installations for stereotactic radiotherapy applications. PMDA enforces lengthy clinical evidence requirements for imported linear accelerator software updates, delaying feature parity with Western installations. The Kansai region anchors proton therapy development through specialized research partnerships with domestic heavy industry manufacturers.
India
Government-funded cancer centers are redirecting procurement toward domestically manufactured systems under the PLI scheme for medical devices. CDSCO revised clinical investigation rules accelerate market authorization for locally produced radiotherapy equipment versus imported alternatives. Maharashtra's tertiary hospital networks in Mumbai and Pune are expanding radiotherapy capacity through public-private partnership models.
South Korea
High-acuity centers in Seoul and Busan are establishing early-adopter partnerships for FLASH therapy and carbon-ion systems. MFDS operates priority review tracks for novel radiotherapy technologies, compressing approval timelines versus standard device pathways. The Seoul Capital Area concentrates the majority of installed proton therapy capacity, with Samsung and VUNO leveraging domestic manufacturing advantages.
Australia
State-level purchasing consortia are unbundling linear accelerator hardware procurement from multi-year service agreements. TGA-mandated credentialing requirements for medical physicists exceed university program graduation rates, forcing centers to recruit from UK and Canadian markets. New South Wales and Victoria house the majority of IMRT-standardized facilities, with Sydney's cancer centers deploying MRI-guided adaptive therapy systems.
Asia-Pacific Radiotherapy Market Competitive Landscape
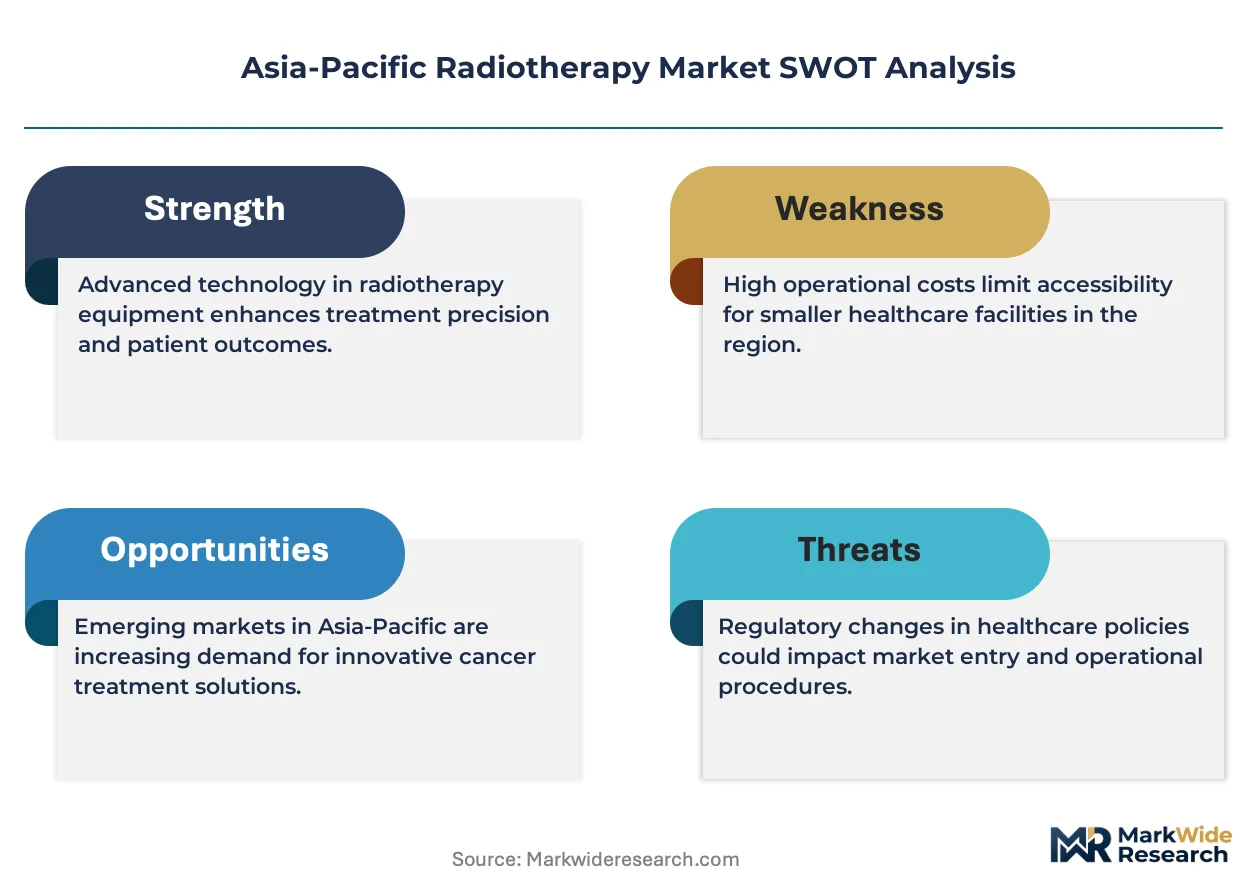
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software providers commanding premium positioning in high-acuity centers while regional assemblers capture provincial hospital procurement. The vendor landscape concentrates around three dominant linear accelerator suppliers whose bundled service contracts lock in hospital budgets. Strategic archetypes include imaging-therapy convergence specialists, proton therapy system developers, and AI-embedded treatment planning software vendors. Competitive moves center on multi-year service agreement bundling and adaptive therapy software integration.
Among the established equipment manufacturers, Varian Medical Systems Inc. and Elekta AB occupy positions as archetypal linear accelerator specialists with extensive installed base footprints across tertiary hospital networks. Siemens Healthineers GmbH represents the imaging-radiotherapy convergence archetype, leveraging diagnostic modality integration to differentiate portfolio positioning in high-volume centers. These three entities anchor the competitive structure, with their respective strategic postures shaping procurement committee evaluation criteria across public hospital networks and academic medical centers.
| Leading Market Players |
|---|
| Varian Medical Systems Inc. |
| Elekta AB |
| Accuray Incorporated |
| RaySearch Laboratories AB |
| Ion Beam Applications SA |
| Mevion Medical Systems Inc. |
| Siemens Healthineers GmbH |
| IBA Worldwide |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Magnetron and klystron tube costs flow from specialized Japanese and German component suppliers through linear accelerator OEMs, with India's PLI scheme for medical devices compressing landed costs for domestically assembled systems versus fully imported units across government-funded cancer centers.
Pricing Analysis
Distributor margins on linear accelerators typically range from 12-18 percent for imported systems, while direct-to-hospital procurement of domestically manufactured equipment under India's CDSCO streamlined pathways eliminates this layer entirely. Three-tier pricing structure across premium, standard, and economy levels separates MRI-guided adaptive therapy systems in Seoul and Tokyo from basic external-beam units in provincial Chinese hospitals and refurbished cobalt-60 replacements in Southeast Asia. Cost compression in the standard tier is intensifying because China's NMPA approval acceleration for local manufacturers is forcing incumbent vendors to unbundle software and service contracts. Government hospital networks in India and Indonesia exhibit highest price sensitivity, whereas Japanese academic medical centers prioritize feature parity over procurement cost.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme are reshaping sourcing patterns for linear accelerator assemblies, with local value-add requirements pushing foreign OEMs to establish component finishing operations in Maharashtra and Karnataka. Supply concentration centers on Japan for precision magnetron manufacturing, Germany for klystron tube production, and China for gantry structural components and power supply modules. Raw material dependencies include high-purity copper for RF cavities, rare-earth magnets for beam steering, and specialized tungsten alloys for collimator fabrication. Single-source vulnerability runs through Japanese magnetron suppliers, where PMDA-mandated quality certifications create switching friction. Distribution runs through regional service hubs in Singapore for Southeast Asia, Dubai for Middle Eastern re-export markets, and direct OEM field engineering teams for large hospital network accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific radiotherapy equipment hinges on software-as-a-service conversion of treatment planning systems, with AI-embedded workflows commanding recurring revenue premiums that offset hardware commoditization pressures.
For Market Incumbents: Lock in hospital budgets through multi-year service agreements that bundle predictive maintenance, software upgrades, and physicist training credits, neutralizing emerging domestic manufacturers in India and China who compete on upfront equipment cost but lack integrated service infrastructure. Deepen backward integration into magnetron refurbishment capabilities to reduce dependency on Japanese component suppliers and compress replacement part lead times.
For New Entrants and Emerging Players: Independent physics support contractors represent the most penetrable channel partner type for unbundling maintenance relationships at Australian public hospitals and Indian state-level purchasing consortia. Target Vietnam and Indonesia greenfield oncology wing construction with lease-to-own financing structures that circumvent capital budget approval cycles, positioning before Varian and Elekta establish service network density.
For Investors and Strategic Acquirers: Consolidation pressure builds where AI-embedded treatment planning software vendors lack hardware integration capabilities and face displacement by integrated platform providers. The 5-10 year viability window favors acquisition of adaptive radiotherapy software specialists with regulatory clearance in South Korea's MFDS priority review track or Australia's TGA pathways. Monitor CDSCO and NMPA approval velocity for domestically manufactured linear accelerators as the inflection signal for when import-dependent business models face structural margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Service Conversion | Transforms one-time treatment planning license sales into recurring revenue streams across Japanese academic medical centers. |
| Domestic Manufacturing Localization | India's PLI scheme accelerates CDSCO approval timelines and reduces landed cost disadvantage versus imported systems. |
| Imaging-Radiotherapy Integration | MRI-guided adaptive therapy commands premium positioning in Seoul and Tokyo high-volume centers. |
| Service Network Unbundling | Third-party physics support contracts disrupt traditional vendor-captive maintenance models in Australian public hospitals. |
| Priority Regulatory Track Navigation | South Korea's MFDS fast-track for FLASH therapy enables first-mover partnerships with domestic manufacturers Samsung and VUNO. |
Research Methodology
Bottom-up oncology department capacity modeling reconciled against top-down linear accelerator shipment tracking forms the analytical core of this study. Primary interviews with radiation oncology department heads, hospital procurement committee chairs, biomedical equipment engineers, and GPO contracts managers across China, Japan, India, South Korea, and Australia were validated against secondary sources including NMPA and CDSCO device registration databases, hospital procurement disclosure filings, and national cancer control plan implementation reports.
Historical trendline analysis of installed base replacement cycles, technology adoption curves for IMRT and stereotactic protocols, and regulatory approval velocity by jurisdiction informed the projection framework. Segmentation dimensions modeled include product type, end-user facility category, technology protocol, and disease application, with CAGRs derived from slope analysis of capacity expansion trajectories across the analysis window. Forecast inputs incorporated physicist training pipeline graduation rates and government-funded cancer center budget allocation patterns.
Revisions become necessary when regulatory harmonization across national health insurance schemes accelerates or when domestic manufacturing incentives in India and China trigger faster import substitution than modeled. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Quadripodal Implants Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Catheter Coatings Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Australia and New Zealand Diabetes Devices Market