
 Automated CPR Devices Market | 2026-2036
Automated CPR Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Automated CPR Devices Market Intelligence
The European Union's Medical Device Regulation (MDR) is shifting the cost-of-entry calculus for device manufacturers, demanding more extensive clinical data. ZOLL Medical Corporation leverages its extensive distribution network and integration with its defibrillator platforms. Stryker Corporation competes through its broad portfolio of emergency medical equipment, offering bundled solutions to hospitals. Medtronic positions its devices within a larger ecosystem of cardiac care technologies.
Automated CPR devices are portable, battery-powered systems that deliver consistent, high-quality chest compressions during cardiac arrest. These machines provide compressions at a fixed rate and depth, often conforming to American Heart Association guidelines, to sustain vital organ perfusion. Mechanical chest compressors represent the core technology segment, seeing primary use in demanding environments. Within applications, hospital-based deployments and emergency medical services constitute the largest revenue sources for manufacturers.
Market access is governed by stringent regulatory bodies, including the US Food and Drug Administration (FDA) through its premarket approval process. The CE marking framework under the EU's MDR and approvals from Japan's Pharmaceuticals and Medical Devices Agency (PMDA) dictate design and quality system requirements. Future device differentiation will depend on demonstrating superior patient outcomes and seamless integration with emergency response data systems.
Market Dynamics
The increasing stringency of regulatory frameworks, demanding robust clinical evidence of improved patient outcomes, is the central structural force shaping the automated CPR devices market. This pressure from bodies like the FDA and under the EU's MDR is compelling manufacturers to move beyond simple mechanical efficacy.
Growth Catalysts
- Guidelines and Protocols:Adherence to American Heart Association (AHA) guidelines, which emphasize consistent, high-quality chest compressions, encourages adoption by Emergency Medical Services to standardize care and reduce rescuer fatigue.
- EMS Modernization:Investment in advanced pre-hospital care infrastructure, particularly in the United States and parts of Western Europe, drives the deployment of automated devices in ambulances and first responder vehicles.
- Technology Maturation:Mechanical chest compressors deliver consistent rate and depth, proving essential in challenging environments such as moving ambulances or during prolonged resuscitation efforts where manual CPR quality degrades.
Market Restraints
- High Capital Cost:The significant upfront investment required to purchase automated CPR devices presents a substantial barrier for budget-constrained healthcare facilities, smaller hospitals, and volunteer-based emergency services.
- Clinical Debate:A lack of definitive, large-scale clinical trial data conclusively proving superiority over high-quality manual CPR for all cardiac arrest scenarios creates hesitation among some clinical decision-makers.
- Device Limitations:Physical constraints, including device weight, bulk, and battery life during extended field use, can limit practicality in certain rescue situations, particularly in austere or remote environments.
Strategic Opportunities
- Data Integration:Developing devices that seamlessly integrate with emergency response data systems, defibrillators, and hospital electronic health records offers a significant opportunity to provide a holistic view of resuscitation efforts.
- Expanded Applications:There is an opportunity to expand deployment into non-traditional settings such as public access venues, industrial worksites, and for use by specialized in-hospital cardiac arrest teams.
- Emerging Economies:Targeting middle-income countries in regions like Southeast Asia and Latin America that are actively upgrading their emergency medical infrastructure presents a key geographic growth vector.
Industry Challenges
- Training and Skill Gaps:Ensuring consistent and effective training for a diverse range of users, from paramedics to hospital staff, is a persistent operational challenge required to maximize device efficacy and user confidence.
- Logistical Hurdles:Managing the logistics of device maintenance, battery replacement cycles, and post-use sterilization across a distributed fleet of devices poses a significant challenge for large EMS agencies and hospitals.
- Demonstrating Value:The operational difficulty of conducting rigorous clinical studies to prove improved neurological outcomes, not just return of spontaneous circulation, complicates reimbursement and procurement justifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated CPR Devices Market |
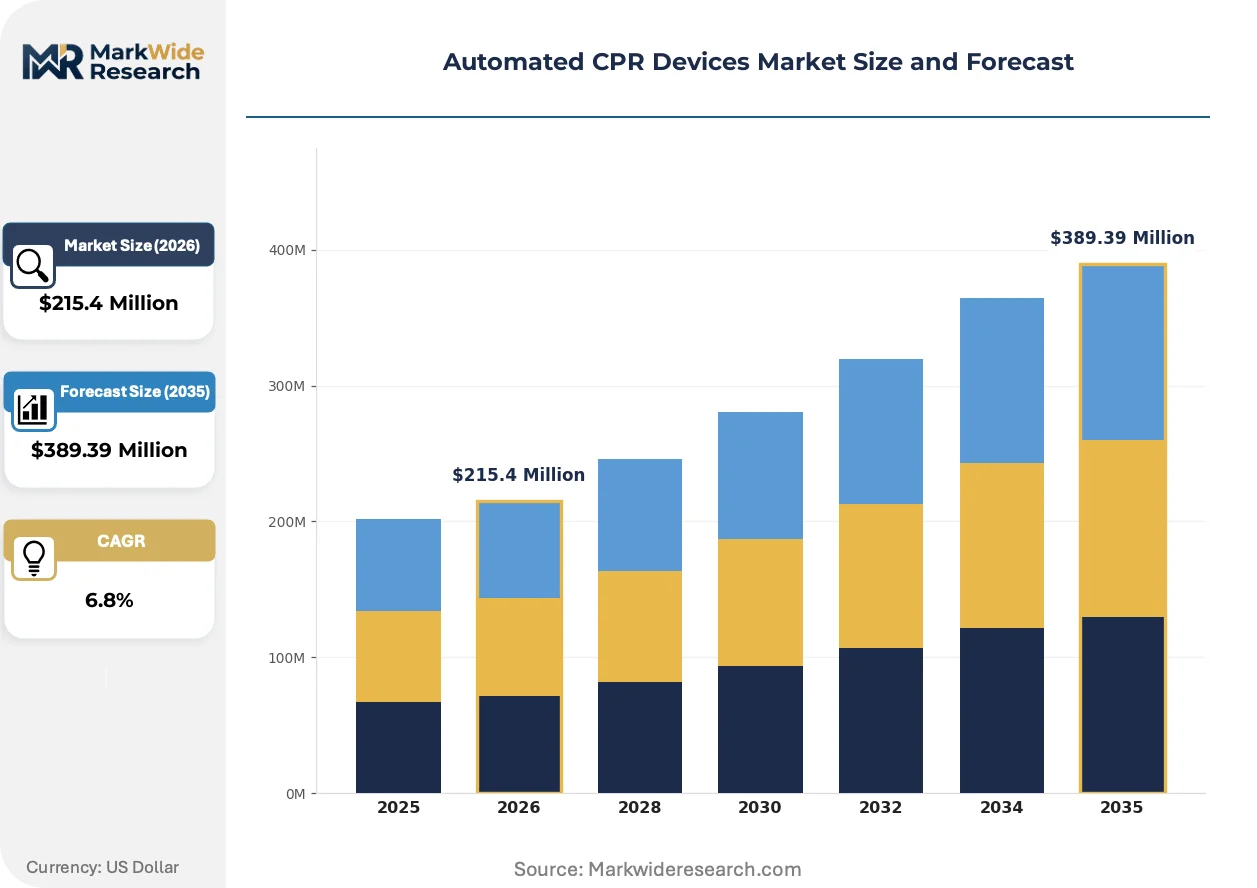
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Automated External Defibrillator, Mechanical Chest Compressor, CPR Feedback Device, Portable Resuscitator Application: Emergency Medical Services, Hospitals, Home Care, Sports Facilities End User: Healthcare Providers, First Responders, Training Centers, Educational Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Equipment Suppliers |
| Companies Covered | Brunswick Biomedical Technologies, SCHILLER AG, ZOLL Medical Corporation, Defibtech, CPR Medical Devices, Stryker Corporation, Laerdal Medical, Medtronic, Michigan Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated CPR Devices Market Strategic Shifts & Innovations
Device evolution is shifting focus from purely mechanical performance to data-centric integration and demonstrated clinical value. This transition is driven by the demands of more sophisticated healthcare purchasers and stricter regulatory bodies seeking evidence of improved patient outcomes.
Load-distributing band technology, which delivers circumferential chest compressions, is a key product evolution. Emergency medical services and specialized cardiac care centers are adopting this for specific patient scenarios requiring prolonged resuscitation. This approach is overtaking traditional piston-based mechanical systems in applications where maximizing hemodynamic support is the primary clinical objective.
The European Union's Medical Device Regulation (MDR) represents a significant regulatory shift. It imposes stricter requirements for clinical evaluation and post-market surveillance on manufacturers. Device makers targeting the European market are most impacted, now needing to generate a higher level of clinical data to obtain and maintain CE marking for their products.
A shift toward value-based procurement models is altering purchasing behavior within large hospital systems. Standalone device acquisitions are giving way to bundled solutions that pair automated CPR machines with defibrillators, data management software, and long-term service agreements. This trend is most visible in the United States, where integrated delivery networks seek to standardize equipment and optimize total cost of ownership across their facilities.
Automated CPR Devices Market Segmentation
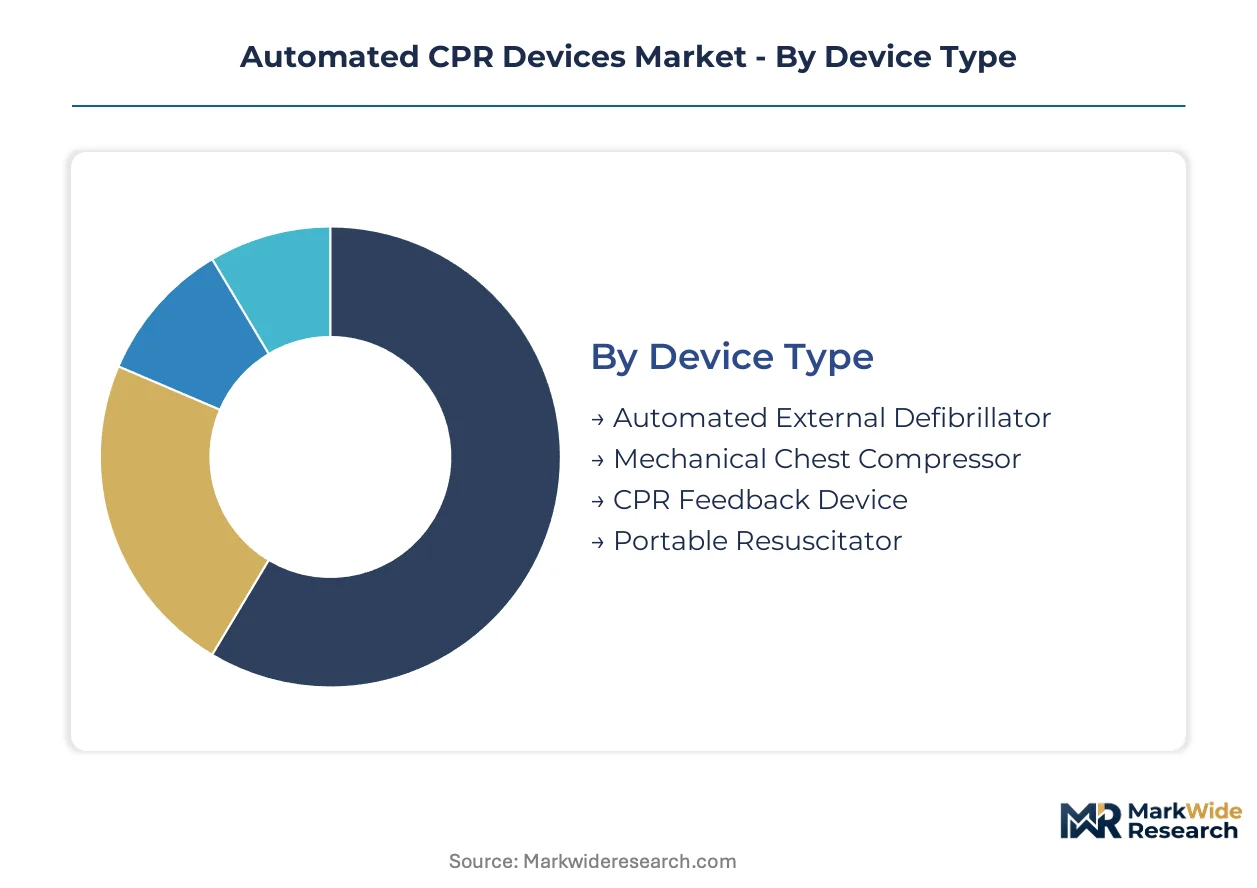
Understanding the automated CPR devices market through its segmentation highlights where investment priorities lie and how manufacturers tailor their market access strategies. Each segment presents distinct operational requirements, technological demands, and regulatory considerations for device developers.
Device Type:
The capital-intensity of automated CPR devices varies significantly across different types, dictating the upfront investment required by healthcare facilities and emergency services.
- Mechanical Chest Compressor:These devices deliver consistent, high-quality chest compressions at a fixed rate and depth, proving essential during prolonged resuscitation efforts or in demanding environments like moving ambulances. Demand concentrates within Emergency Medical Services and specialized cardiac care units in the United States, driven by the need to reduce rescuer fatigue and standardize care.
- Automated External Defibrillator:These portable electronic devices automatically diagnose life-threatening cardiac arrhythmias and treat them through defibrillation, often integrating with CPR feedback mechanisms. Widespread deployment in public access venues and pre-hospital settings across Western Europe is driven by increasing public health initiatives and first responder protocols.
- CPR Feedback Device:These smaller, often handheld devices provide real-time audio or visual feedback on compression rate and depth during manual CPR. First responders and training centers utilize these tools to improve the quality of manual resuscitation efforts.
- Portable Resuscitator:These devices assist ventilation during resuscitation, often used in conjunction with chest compressors, ensuring adequate oxygenation for patients. Emergency Medical Services in regions with advanced pre-hospital care infrastructure deploy these for critical patient transport.
Mechanical Chest Compressor absorbs the bulk of installed capacity; Portable Resuscitator is expanding most quickly.
Application:
Application-specific operational challenges influence device design and deployment strategies for automated CPR technology across diverse clinical and pre-hospital settings.
- Emergency Medical Services:Automated CPR devices are deployed in ambulances and first responder vehicles to provide consistent chest compressions, particularly during patient transport or prolonged resuscitation, reducing rescuer fatigue. Demand is significant in the United States and parts of Western Europe, where investment in advanced pre-hospital care infrastructure is high.
- Hospitals:These devices are used in emergency departments, intensive care units, and during inter-hospital transfers to maintain high-quality CPR, especially during complex procedures or staff shortages. Integration with existing cardiac care technologies and electronic health records is a key requirement for hospital procurement.
- Home Care:Automated CPR devices see limited but specialized use in home care settings for patients with specific cardiac conditions, requiring specialized training for caregivers. The practicality is constrained by device weight and bulk for non-professional users.
- Sports Facilities:Public access defibrillation programs at sports venues sometimes include automated CPR devices to provide immediate, high-quality resuscitation in case of sudden cardiac arrest. Ease of use and portability are important factors for these deployments.
User training and device integration remain paramount for Hospitals deployments.
End User:
Regulatory compliance and procurement pathways significantly differ among the end-user segments, impacting market access and sales strategies for automated CPR device manufacturers.
- Healthcare Providers:This segment includes hospitals, clinics, and specialized cardiac centers that utilize automated CPR devices for patient care, driven by clinical protocols and evidence of improved outcomes. Procurement often involves rigorous clinical evaluation and adherence to regulations like the EU's MDR and US FDA guidelines.
- First Responders:Police, fire departments, and ambulance services deploy automated CPR devices to standardize care and mitigate rescuer fatigue during pre-hospital emergencies. Adoption is driven by American Heart Association guidelines and government funding for emergency medical infrastructure.
- Training Centers:These institutions utilize automated CPR devices for teaching and certification programs, providing hands-on experience with mechanical compression technology. Device durability and ease of simulation are important for these educational environments.
- Educational Institutions:Universities and medical schools incorporate automated CPR devices into their curricula for medical and nursing students, familiarizing future healthcare professionals with advanced resuscitation techniques. Budget constraints often influence procurement decisions in this segment.
Effective deployment hinges on addressing the specific operational needs of Healthcare Providers and First Responders.
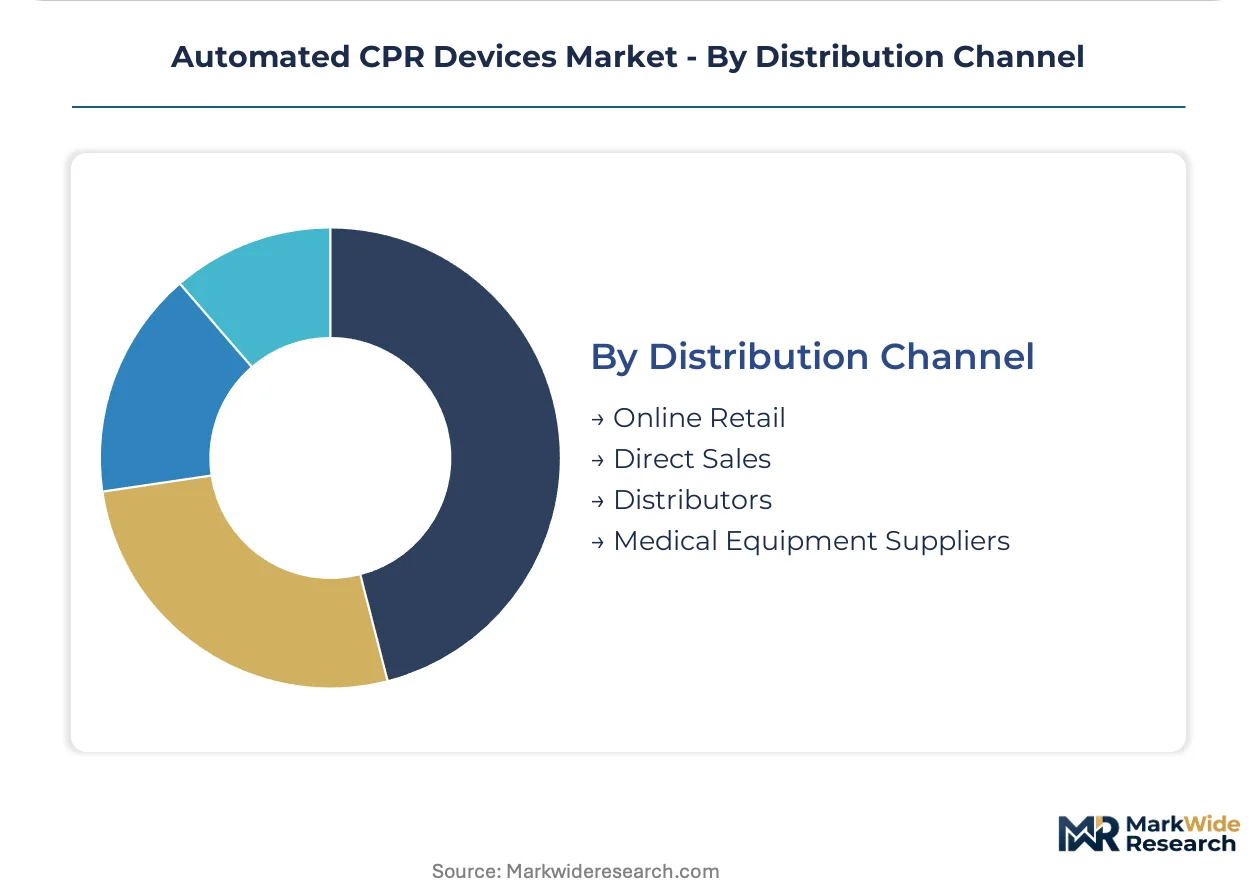
Distribution Channel:
Logistical complexity and market reach define the effectiveness of different distribution channels for automated CPR devices, influencing how products reach their end-users.
- Direct Sales:Manufacturers engage in direct sales for high-value, complex automated CPR devices to large hospital systems and major EMS agencies, often including installation, training, and long-term service agreements. This channel allows for direct customer relationships and tailored solutions.
- Distributors:Independent distributors provide broader market penetration, particularly for reaching smaller healthcare facilities, regional EMS providers, and international markets. They manage local logistics, regulatory compliance, and provide regional support.
- Online Retail:This channel primarily serves individual buyers or smaller organizations seeking CPR feedback devices or less complex portable resuscitators, often for training or personal emergency preparedness. Product specifications and user reviews influence purchasing decisions.
- Medical Equipment Suppliers:These companies offer a wide range of medical devices, including automated CPR systems, often bundling them with other emergency medical equipment for hospitals and clinics. Their established procurement relationships are valuable for market access.
Optimizing the supply chain for Direct Sales channels is crucial for market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The established zone of advanced pre-hospital care in the United States drives significant market concentration for automated CPR devices. This regional focus is further shaped by stringent regulatory landscapes and national investment in emergency medical infrastructure. Device adoption varies based on local healthcare priorities and economic capacity.
United States
Demand for automated CPR devices in the United States stems from advanced pre-hospital care protocols and widespread first responder deployment. The US Food and Drug Administration (FDA) premarket approval process dictates market entry for new devices. Major metropolitan areas, such as New York and Los Angeles, see high deployment rates due to dense populations and well-funded Emergency Medical Services.
Germany
Germany's market for automated CPR devices benefits from substantial investment in advanced pre-hospital care infrastructure. Devices must secure CE marking under the EU's Medical Device Regulation (MDR) for market access. Medical technology hubs in Bavaria and Baden-Württemberg actively develop and manufacture high-quality resuscitation devices for both domestic and international markets.
Japan
Modernization of emergency medical infrastructure and emphasis on consistent, high-quality chest compressions drive demand in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) dictates stringent design and quality system requirements for market approval. The Tokyo and Osaka regions lead in hospital-based deployments and advanced emergency services adoption across the country.
United Kingdom
The United Kingdom's market is influenced by NHS investment in emergency services and efforts to standardize care. Devices must generally meet EU MDR standards for market entry, even post-Brexit, ensuring high quality. London and other large urban centers prioritize automated devices for their extensive ambulance services and major hospital networks.
Automated CPR Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure. Large medical technology providers leverage their extensive portfolios to offer integrated solutions and bundled offerings. Strategic archetypes include comprehensive emergency medical equipment suppliers, niche CPR device innovators, and cardiac care ecosystem builders. Portfolio diversification, strategic partnerships for data integration, and M&A for technology acquisition represent dominant competitive moves.
Among diversified medical technology providers, ZOLL Medical Corporation exemplifies an integrated solutions approach, leveraging its extensive distribution network and defibrillator platforms. Stryker Corporation, also a significant player, anchors its market presence through a broad portfolio of emergency medical equipment and bundled solutions for hospitals. Medtronic, a global medical technology company, positions its devices within a larger ecosystem of cardiac care technologies, emphasizing comprehensive patient management and integration capabilities. These companies collectively demonstrate the trend towards holistic offerings in the market.
| Leading Market Players |
|---|
| Brunswick Biomedical Technologies |
| SCHILLER AG |
| ZOLL Medical Corporation |
| Defibtech |
| CPR Medical Devices |
| Stryker Corporation |
| Laerdal Medical |
| Medtronic |
| Michigan Instruments |
| Others |
Cost & Logistics Intelligence
A clear performance gap between advanced mechanical chest compressors and basic CPR feedback devices drives divergent pricing and supply chain configurations. Premium devices demand high-tech components, sourced globally, while simpler tools rely on more localized supply chains.
Pricing Analysis
Premium pricing for advanced automated CPR devices reflects their stringent regulatory approvals and integrated software capabilities. Value-based procurement models are increasingly common for hospital systems, bundling devices with long-term service agreements. Price differentiation stems from CE marking or FDA premarket approval, alongside after-sales support. Pricing softness emerges from clinical debate regarding superiority over manual CPR, particularly impacting smaller healthcare facilities and volunteer EMS, which are most price-sensitive.
Supply Chain Analysis
Skilled workforce availability in medical device manufacturing hubs like Germany and the United States underpins complex automated CPR device supply. Specialized electronics, medical-grade plastics, and high-capacity battery cells constitute critical component dependencies. Regulatory hurdles, particularly under the EU's MDR, represent a significant supply chain risk, increasing lead times for market access. Distribution runs through a hybrid model, combining direct sales for large contracts with distributors for broader regional reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is navigating a technology-transition phase, moving from purely mechanical devices to data-integrated systems. Load-distributing band technology is displacing traditional piston-based mechanical compressors in advanced applications.
For Market Incumbents: Hedge against clinical data gaps by investing in large-scale, outcome-focused clinical trials for automated CPR devices. Expand integration capabilities with existing defibrillator platforms and electronic health records to counter emerging data-centric competitors. Strengthen distribution networks in emerging economies to mitigate revenue concentration in mature markets.
For New Entrants and Emerging Players: Enter via niche applications, such as specialized in-hospital cardiac arrest teams, where device integration and advanced features are highly valued. Target middle-income countries in Southeast Asia and Latin America, which are actively upgrading emergency medical infrastructure. A go-to-market angle focusing on demonstrating superior patient outcomes through real-world data offers a clear differentiation strategy.
For Investors and Strategic Acquirers: Re-rating potential sits with agile specialists demonstrating clear patient outcome improvements, given the increasing regulatory demand for clinical evidence. Long-term viability favors companies able to integrate devices into comprehensive cardiac care ecosystems. Focus on firms with robust IP portfolios in data analytics and sensor technology. A signal to watch is the widespread adoption of value-based procurement models by major hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Clinical Outcome Studies | Demonstrates device efficacy to satisfy EU MDR and FDA requirements, justifying higher procurement costs. |
| Develop Integrated Data Platforms | Enhances interoperability with hospital systems and defibrillators, crucial for Medtronic's ecosystem strategy. |
| Expand into Emerging Economies | Captures new market share in regions like Southeast Asia with upgrading emergency medical infrastructure. |
| Form Strategic Partnerships for Software | Accelerates development of advanced analytics and real-time feedback mechanisms for ZOLL Medical Corporation. |
| Acquire Niche Technology Innovators | Boosts product differentiation and intellectual property, particularly in load-distributing band technology. |
Research Approach
Document review covered industry reports, regulatory filings (FDA, EU MDR, PMDA), and American Heart Association guidelines, complemented by interviews with emergency medical services directors, hospital procurement managers, R&D engineers, and regulatory specialists. This approach combined primary insights with secondary validation, utilizing both bottom-up and top-down triangulation methods.
Historical market data was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation dimensions including device type, application, end-user, distribution channel, and key regulatory regions. Compound annual growth rates were derived from projected market shifts and anticipated investment in pre-hospital care infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in clinical trial results or healthcare budget allocations. These forecasts reflect inherent assumptions regarding technological adoption and regulatory stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Neurostimulation Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Europe C-Arms Market
Medical Devices
Organ Preservation Market
Medical Devices
Bariatric Beds Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Global Bowel Management System Market