
 Global Sternal Closure Systems Market | 2026-2036
Global Sternal Closure Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sternal Closure Systems Market Foresight
Germany is narrowing its manufacturing capacity for titanium sternal implants through specialized foundries in the Baden-Württemberg medical technology cluster. Zimmer Biomet leverages its European distribution infrastructure to sustain direct hospital contracting across the continent. Stryker anchors its competitive position through backward integration into precision-machined sternal plates. KLS Martin Group differentiates via polymer strap innovations targeting pediatric cardiac centers.
Sternal closure systems are mechanical fixation devices engineered from titanium alloys, stainless steel, or resorbable polymers, designed to stabilize the sternum following median sternotomy with tensile strength exceeding 400 N in axial loading; their primary purpose is to prevent dehiscence while enabling osseous union during the six-to-twelve-week healing window. Plate fixation systems command premium pricing in complex redo procedures where wire cerclage demonstrates elevated failure rates. Cable closure techniques are displacing traditional stainless steel wires in high-risk obese patient cohorts across North American teaching hospitals. Suture-based systems occupy niche positions in cost-sensitive outpatient surgical units where procedure volume remains constrained.
The FDA's 510(k) clearance framework governs titanium clip introductions, while the EU MDR's clinical evaluation requirements extend scrutiny to long-term biocompatibility data for polymer straps. Japan's PMDA enforces JIS-compliant fatigue testing protocols that limit market entry for non-domestic manufacturers. Stakeholders must monitor evolving reimbursement thresholds for biodegradable clips as health technology assessment bodies in France and England recalibrate cost-effectiveness benchmarks for sternal fixation modalities.
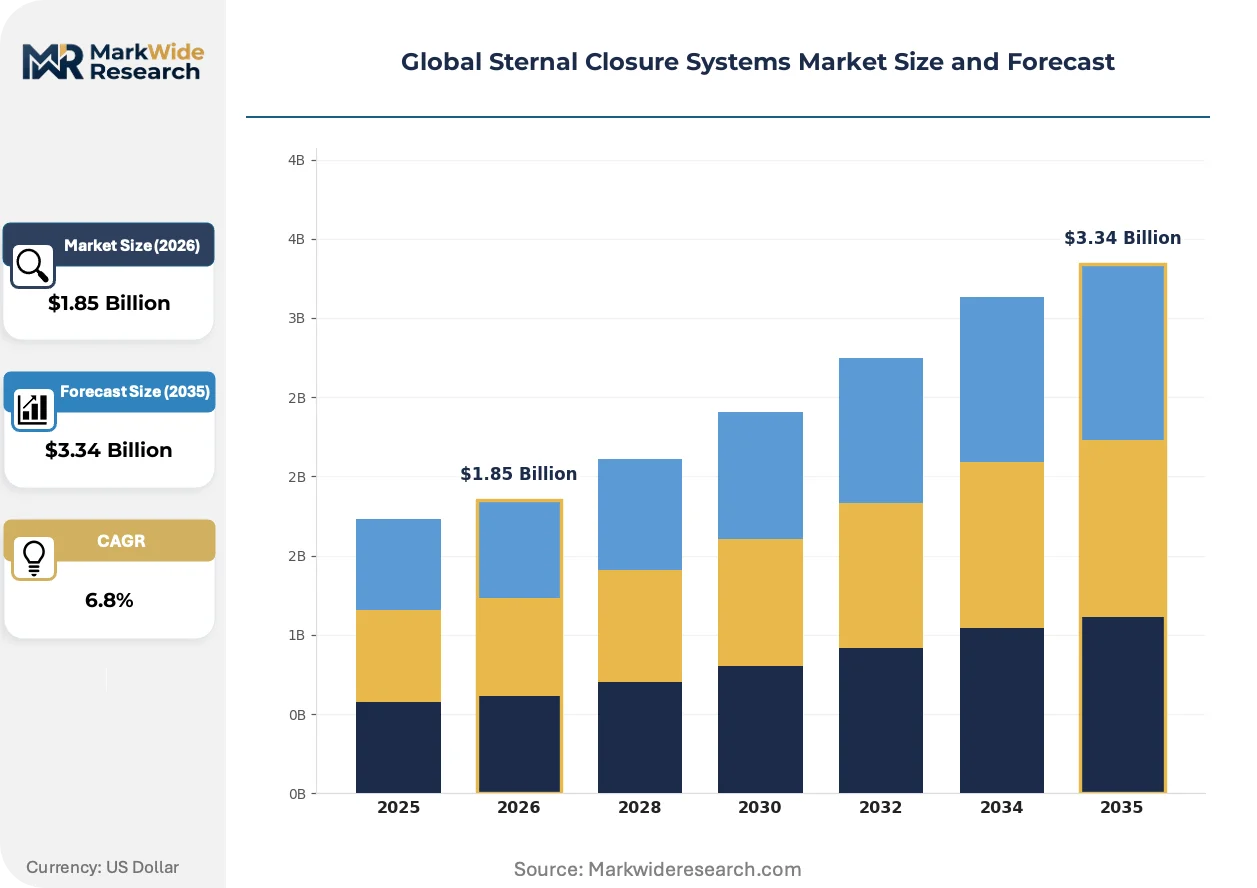
Market Dynamics
EU MDR's strengthened post-market surveillance requirements are compressing product development cycles while forcing manufacturers to rebuild clinical evidence portfolios for legacy titanium implants already on the market.
Growth Catalysts
- Wire cerclage failure in redo sternotomy:Complex cardiac reconstruction cases in German university hospitals are accelerating uptake of rigid plate fixation systems that withstand axial loads exceeding 400 N.
- PMDA fatigue testing harmonization:Japan's adoption of JIS-compliant protocols for titanium implants is streamlining technical documentation for manufacturers seeking simultaneous US-Japan regulatory submissions.
- Obesity-driven cable adoption:North American teaching hospitals are replacing stainless steel wires with titanium cable systems in patients with BMI thresholds above 35 kg/m² where wire fracture rates spike.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have tightened availability of aerospace-grade titanium alloys for medical device foundries in Baden-Württemberg.
- Polymer biocompatibility data gaps:EU MDR's extended clinical evaluation timelines for resorbable sternal straps are delaying market entry by 18-24 months versus predicate titanium devices.
- Stainless steel wire substitution economics:Cost-sensitive outpatient surgical units in Southern Europe continue defaulting to wire cerclage despite documented failure risks in high-risk patient cohorts.
Strategic Opportunities
- Pediatric polymer innovation:Resorbable sternal straps that eliminate secondary removal surgery are capturing preference in congenital cardiac centers across France and England where growth-plate considerations dominate.
- Direct hospital contracting:Manufacturers with European distribution infrastructure are bypassing distributor markups through frame contracts with integrated cardiothoracic networks in the Netherlands and Belgium.
- Biodegradable reimbursement recalibration:Health technology assessment bodies in England are revising NICE guidance to incorporate long-term cost offsets from avoided reoperation in polymer strap evaluations.
Industry Challenges
- Precision machining talent scarcity:German medical technology clusters face recruitment gaps for CNC operators capable of micron-tolerance sternal plate production.
- Legacy wire inventory amortization:Distributors with substantial stainless steel wire stockpiles are resisting portfolio transitions to cable systems that cannibalize existing SKU investments.
- 510(k) predicate erosion:FDA's narrowing acceptance of titanium clip predicates is forcing novel mechanical designs into costlier De Novo pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sternal Closure Systems Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sternal Plates, Stainless Steel Wires, Sternal Bands, Polymer Straps, Titanium Clips Closure Technique: Wire Cerclage, Plate Fixation, Biodegradable Clips, Cable Closure, Suture-Based Systems Application: Coronary Artery Bypass, Thoracic Surgery, Valve Replacement, Congenital Heart Defects Repair, Trauma Surgery End User: Cardiothoracic Centers, Specialty Clinics, Research Hospitals, Outpatient Surgical Units |
| Companies Covered | Johnson & Johnson Services, Inc., Zimmer Biomet, KLS Martin Group, B. Braun SE, Stryker, Kinamed Incorporated, Acumed LLC, IDEAR S.R.L, Abyrx, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sternal Closure Systems Market Shifts & Advancements
Digital preoperative planning tools are compressing device selection cycles while polymer degradation modeling software is enabling patient-specific healing predictions that reshape surgeon preference formation.
Resorbable polymer sternal fixation is virtualizing the postoperative care pathway by eliminating hardware removal procedures. Pediatric cardiac centers in Paris and London are adopting these systems for patients under 12 years where growth-plate preservation is paramount. The technology is virtualizing revenue models away from implant-plus-removal bundles toward single-intervention pricing that health technology assessors in France are beginning to recognize.
EU MDR's Article 120 transition deadlines are forcing systematic clinical data regeneration for titanium implants cleared under the Medical Devices Directive. Manufacturers with legacy portfolios face parallel documentation burdens for devices already implanted in thousands of patients. German notified bodies are prioritizing sternal closure system reviews due to high-risk classification, creating queue compression that disadvantages smaller applicants.
Surgeon preference is consolidating around procedure-specific kits that bundle plates, cables, and emergency conversion wires in sterile configurations. Integrated delivery networks in the United States are mandating these kits through value-analysis committees that disfavor à la carte purchasing. The shift is most pronounced in high-volume coronary artery bypass programs where standardization reduces operating room turnover variance.
Global Sternal Closure Systems Market Segmentation
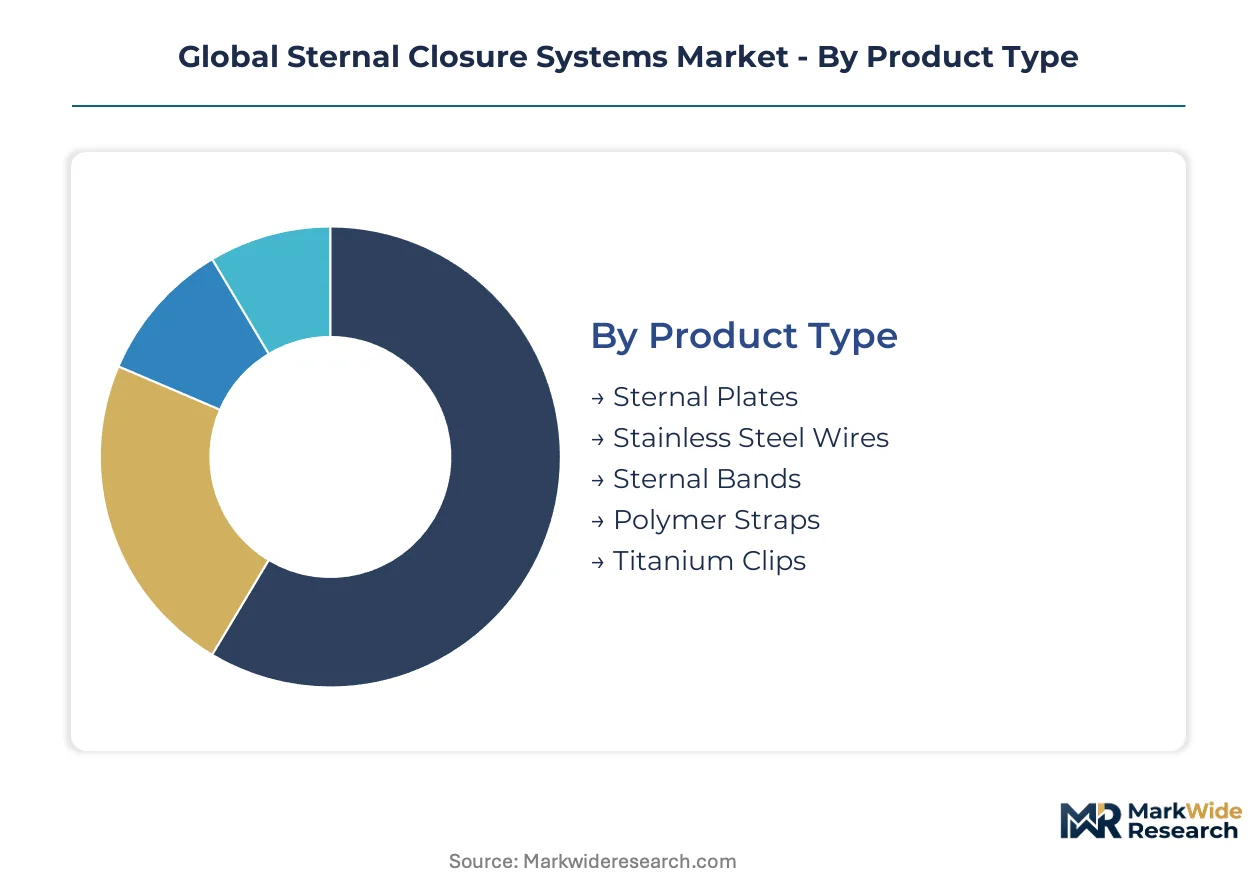
Sternal closure systems fragment across four dimensions that shape procurement patterns and clinical utility. Product type and closure technique dominate purchasing decisions, while application specificity and end-user scale determine pricing tolerance and service requirements.
Product Type:
Inventory turnover varies sharply across product categories, with consumable wires cycling fastest and capital-intensive plate systems anchoring long sales cycles.
- Sternal Plates:Titanium alloy constructs machined to micron tolerances for rigid fixation in complex redo procedures. German university hospitals in Baden-Württemberg concentrate demand where axial load requirements exceed 400 N and wire failure rates prove unacceptable.
- Stainless Steel Wires:Braided 316L stainless steel configurations remain the default closure method in cost-sensitive settings. Southern European outpatient surgical units default to this modality despite documented failure risks in high-risk patient cohorts.
- Sternal Bands:Flat metallic straps distributing force across broader sternal surface area than round wires.
- Polymer Straps:Resorbable lactide-glycolide copolymers eliminating secondary removal surgery in pediatric applications.
- Titanium Clips:Miniature fixation devices for sternal edge approximation in minimally invasive approaches.
Stainless steel wires anchor the volume base while polymer straps gain share at the steepest rate.
Closure Technique:
Cost tier stratification separates emergency conversion capabilities from premium rigid fixation, with reimbursement bandwidth determining accessible options.
- Wire Cerclage:Traditional circumferential wiring using stainless steel or titanium alloys. Cost-sensitive outpatient surgical units in Southern Europe continue defaulting to this modality despite elevated failure rates in obese patient cohorts.
- Plate Fixation:Rigid screw-plate constructs engineered for axial load bearing in complex cardiac reconstruction. North American teaching hospitals drive preference where redo sternotomy cases concentrate and cerclage failure rates spike.
- Biodegradable Clips:Resorbable fixation eliminating hardware removal procedures in pediatric populations.
- Cable Closure:Multifilament titanium cables replacing wires in high-risk obese cohorts across North American teaching hospitals where BMI thresholds exceed 35 kg/m².
- Suture-Based Systems:Non-metallic closure for cost-constrained environments with constrained procedure volume.
Wire cerclage dominates procedure count while cable closure expands most quickly in high-risk patient segments.
Application:
Procedure volume concentrates in coronary revascularization, with specialized cardiac interventions commanding premium device specifications.
- Coronary Artery Bypass:Median sternotomy for multi-vessel revascularization representing the highest-volume application. Integrated delivery networks in the United States mandate procedure-specific kits through value-analysis committees.
- Valve Replacement:Aortic and mitral valve procedures requiring stable sternal fixation during prolonged cardiopulmonary bypass runs.
- Thoracic Surgery:Non-cardiac mediastinal procedures with variable fixation requirements.
- Congenital Heart Defects Repair:Pediatric procedures where growth-plate preservation drives resorbable polymer adoption in Paris and London cardiac centers.
- Trauma Surgery:Emergency sternal stabilization following blunt chest injury with unpredictable bone quality.
Coronary artery bypass generates the installed base while congenital repair shows the steepest technology upgrade trajectory.
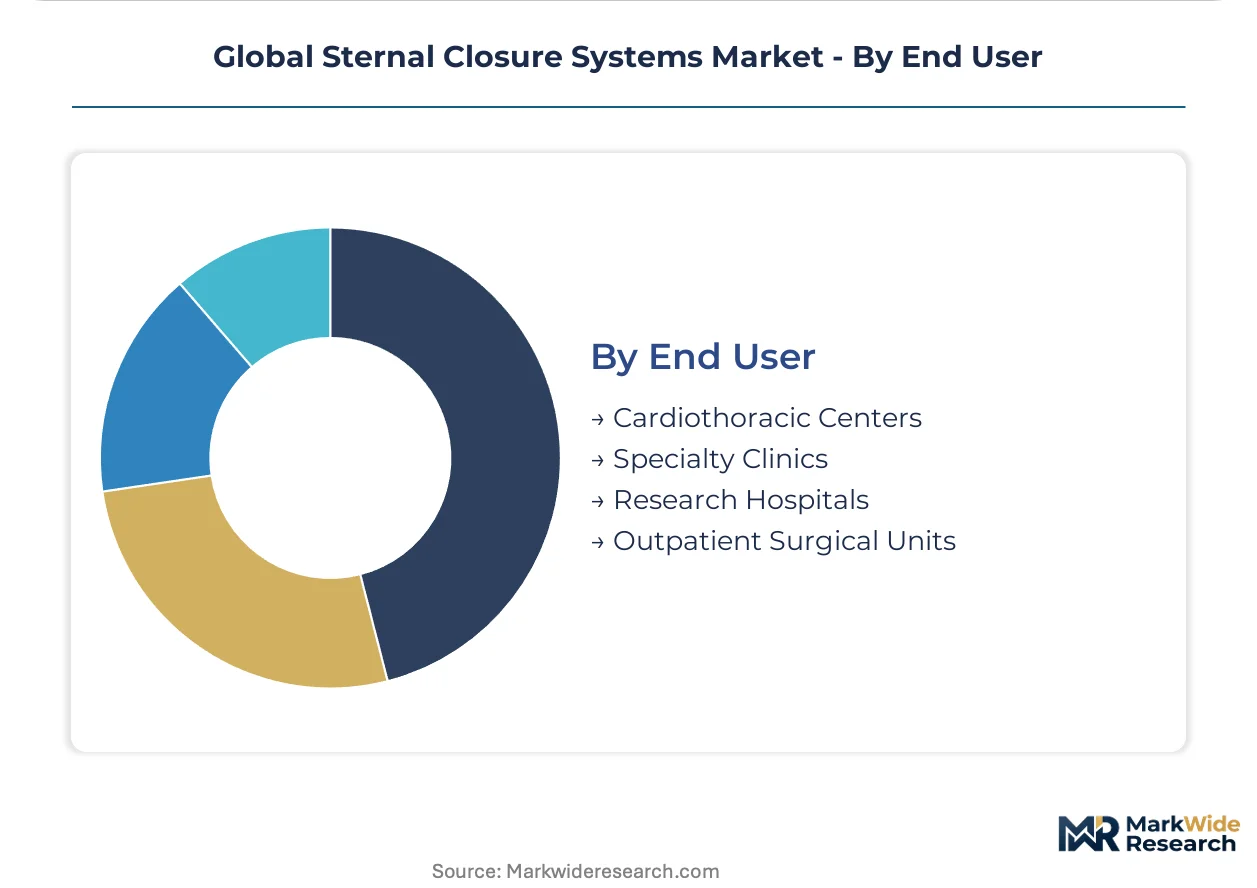
End User:
Customer scale and specialization determine service intensity, with academic medical centers demanding technical support that outpatient units forego.
- Cardiothoracic Centers:High-volume dedicated cardiac surgery units performing complex reconstruction. German university hospitals drive preference for plate fixation systems in redo sternotomy cases.
- Research Hospitals:Academic medical centers with clinical trial infrastructure and protocol-driven device selection.
- Specialty Clinics:Focused cardiac surgery facilities with standardized procedure portfolios.
- Outpatient Surgical Units:Ambulatory settings with cost-constrained procurement and limited emergency conversion capabilities.
Cardiothoracic centers command the revenue concentration while research hospitals drive the steepest adoption of novel fixation modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge supply constraints have compressed manufacturing capacity at specialized foundries in southwestern Germany, while regulatory divergence between FDA 510(k) pathways and EU MDR clinical evaluation timelines fragments product launch sequencing across Atlantic markets.
United States
Integrated delivery networks in the Midwest and Southeast are mandating procedure-specific sternal closure kits through value-analysis committees, consolidating procurement around standardized configurations. FDA's narrowing acceptance of titanium clip predicates is pushing novel mechanical designs toward costlier De Novo regulatory pathways. The Cleveland Clinic and Mayo Clinic anchor demand concentration for rigid plate systems in complex redo sternotomy cases.
Germany
University hospitals in Baden-Württemberg are driving preference for titanium plate fixation systems where axial load requirements exceed 400 N in cardiac reconstruction. EU MDR's Article 120 transition deadlines are forcing systematic clinical data regeneration for legacy implants previously cleared under the Medical Devices Directive. Precision-machining foundries in the Tuttlingen medical technology cluster face recruitment gaps for CNC operators capable of micron-tolerance sternal plate production.
Japan
Tokyo and Osaka cardiothoracic centers are adopting titanium cable systems for high-risk patient cohorts where wire fracture rates prove unacceptable. PMDA enforces JIS-compliant fatigue testing protocols that limit market entry for non-domestic manufacturers lacking localized technical documentation. METI's harmonization initiatives are streamlining simultaneous US-Japan regulatory submissions for titanium implantables.
France
Pediatric cardiac centers in Paris are capturing preference for resorbable polymer sternal straps that eliminate secondary removal surgery in congenital defect repair. ANSM's strengthened post-market surveillance aligns with EU MDR biocompatibility requirements for resorbable devices. Health technology assessment bodies are revising cost-effectiveness benchmarks to incorporate long-term offsets from avoided reoperation in polymer strap evaluations.
United Kingdom
London teaching hospitals are consolidating surgeon preference around cable closure techniques in obese patient cohorts with BMI thresholds above 35 kg/m². NICE guidance recalibration is incorporating long-term cost offsets from biodegradable fixation systems into reimbursement thresholds. Research hospitals in the Oxford-Cambridge corridor are driving adoption of digital preoperative planning tools that compress device selection cycles.
Global Sternal Closure Systems Market Competitive Landscape
Integrated orthopedic conglomerates and specialized cardiovascular device manufacturers split the market between scale-driven distribution infrastructure and focused clinical application expertise. The vendor base concentrates around three strategic archetypes: diversified implant manufacturers with backward integration into precision machining, mid-cap specialists with polymer material science capabilities, and regional fabricators serving cost-constrained procurement environments. Dominant competitive moves include direct hospital contracting frameworks that bypass distributor markups, and portfolio diversification into resorbable materials to capture pediatric segment preference.
Among diversified orthopedic manufacturers, Zimmer Biomet and Stryker occupy positions anchored by European distribution infrastructure and in-house production capabilities respectively. KLS Martin Group exemplifies the specialized cardiovascular archetype with focused expertise in sternal fixation applications. These three entities represent the competitive tension between scale-driven procurement consolidation and clinical-specialization differentiation that defines current market positioning.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Zimmer Biomet |
| KLS Martin Group |
| B. Braun SE |
| Stryker |
| Kinamed Incorporated |
| Acumed LLC |
| IDEAR S.R.L |
| Abyrx, Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity at Baden-Württemberg precision-machining foundries is compressing titanium plate availability while elevating supplier pricing power across European cardiothoracic networks. This utilization squeeze feeds directly into procurement posture, as integrated delivery networks accelerate long-term contracting to lock capacity ahead of competing hospital systems.
Pricing Analysis
EU MDR dictates the pricing tier structure across sternal closure systems, separating legacy titanium wire products facing recertification cost burdens from premium plate systems commanding higher margins through complex redo procedure indications. Price differentiation rests on axial load certification thresholds and JIS-compliant fatigue testing documentation for Japanese market access. Cost compression in stainless steel wire segments is intensifying because Southern European outpatient surgical units resist upgrade cycles despite documented failure risks. Research hospitals demonstrate the lowest price sensitivity, prioritizing mechanical performance specifications over per-unit procurement economics.
Supply Chain Analysis
Specialized foundries in Germany, Switzerland, and Japan hold contract-manufacturing concentration for aerospace-grade titanium alloy sternal plates. Raw material feeds draw from Russian and Ukrainian titanium sponge sources, with secondary reliance on Japanese and Chinese alloy processors. Single-source vulnerability runs through Baden-Württemberg micron-tolerance machining capacity, where CNC operator scarcity constrains output expansion. Distribution runs through direct hospital contracting frameworks that displace traditional distributor markups in the Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sternal closure systems market sits in early-cycle expansion, with polymer resorbable technology penetration in pediatric cardiac centers representing the most visible adoption tailwind reshaping procedure economics.
For Market Incumbents: Insulate titanium plate margins through captive supply agreements with Baden-Württemberg foundries, locking capacity ahead of EU MDR-driven demand spikes. Accelerate backward integration into polymer material science to defend against resorbable strap substitution in congenital cardiac centers. Precision-machining talent acquisition in southwestern Germany represents the critical capacity lever. For New Entrants and Emerging Players: Mid-tier cardiothoracic centers in Southern Europe represent the most penetrable entry point, where cost-constrained procurement defaults to wire cerclage despite failure risk documentation. Pediatric polymer innovation in France and England offers secondary white-space, with health technology assessment recalibration creating reimbursement pathway opportunities. Go-to-market execution should anchor on GPO contract penetration rather than direct hospital sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with European distribution infrastructure capable of frame contracting across integrated cardiothoracic networks. Long-term viability over the next decade favors specialized cardiovascular device archetypes with polymer material science capabilities over diversified orthopedic conglomerates facing portfolio rationalization pressure. The signal to watch is NICE guidance revision timing for biodegradable fixation reimbursement benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Data Regeneration | Legacy titanium implant portfolios require systematic evidence rebuilding for Article 120 compliance. |
| Pediatric Polymer R&D Expansion | Resorbable strap development captures preference in Paris and London congenital cardiac centers. |
| Direct Hospital Contracting Frameworks | Frame agreements with Dutch and Belgian networks bypass distributor margin extraction. |
| Precision-Machining Talent Acquisition | CNC operator recruitment in Tuttlingen cluster alleviates micron-tolerance production bottlenecks. |
| JIS-Compliant Fatigue Testing Investment | PMDA protocol alignment streamlines simultaneous US-Japan regulatory submissions. |
Research Methodology
Cross-validation between surgeon preference surveys and hospital procurement database analysis anchors the qualitative findings in documented purchasing behavior. Primary interviews with cardiothoracic surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs specialists combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement records, and PMDA submission databases. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation ensure segmentation consistency.
Calibration against historical adoption curves for rigid fixation technologies shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, closure technique, application specificity, and end-user scale, with regional regulatory cluster differentiation as an additional modeled layer. CAGRs derive from installed base expansion rates and technology substitution dynamics, incorporating titanium sponge supply constraints and EU MDR transition timelines as industry-specific forecast inputs.
Practitioners should monitor EU MDR notified body queue compression and PMDA harmonization progress for early signals of competitive entry timing shifts. Forecasts reflect assumptions about polymer biocompatibility data generation timelines and health technology assessment recalibration velocity. Quarterly review of titanium alloy spot pricing and German CNC labor market indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Ileostomy Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Global Microcatheter Market
Medical Devices
Japan Hemostats Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Morcellators Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
ETCO2 Masks Market