
 Global Endovascular Aneurysm Repair Devices Market | 2026-2036
Global Endovascular Aneurysm Repair Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endovascular Aneurysm Repair Devices Market Foresight
European nitinol wire drawing capacity is decoupling from Asian polymer sheeting supply, creating regional sourcing asymmetries for stent graft manufacturers. Medtronic leverages its integrated cobalt chromium foundry network to sustain margin resilience across its CoreValve and Endovascular franchises. Cook Medical anchors its competitive position through physician training infrastructure and specialized sales coverage in vascular surgery suites. W. L. Gore & Associates differentiates via proprietary expanded polytetrafluoroethylene lamination technology that commands premium positioning in complex anatomies.
Endovascular aneurysm repair devices comprise catheter-delivered stent graft systems, balloon-expandable or self-expanding metal frameworks covered with biocompatible polymers, designed to exclude aneurysmal sacs from arterial pressure while preserving distal perfusion through branch vessel patency. These systems typically deploy through 14–24 French delivery sheaths under fluoroscopic guidance, with primary commercial purpose of reducing perioperative mortality and hospital length of stay relative to open surgical repair. Stent grafts capture the dominant value pool given their per-procedure cost concentration and recurring replacement revenue from endoleak revisions, while balloon catheters represent the fastest-growing adjacent category as operators adopt more aggressive intraoperative angioplasty for seal zone optimization. Nitinol-based technology leads volume production due to superelastic recovery and kink resistance, though cobalt chromium platforms gain traction in thoracic applications where radial strength requirements exceed nitinol fatigue limits.
FDA pre-market approval pathways and EMA medical device regulation compliance costs structure competitive barriers, with notified body capacity constraints in Europe extending conformity assessment timelines. Japan's PMDA Shonin approval process demands domestic clinical trials that filter market entry to manufacturers with sustained Japan investment capacity. Stakeholders must monitor evolving EVAR-2 trial long-term durability data and corresponding reimbursement recalibrations that could shift physician preference between endovascular and open surgical protocols.
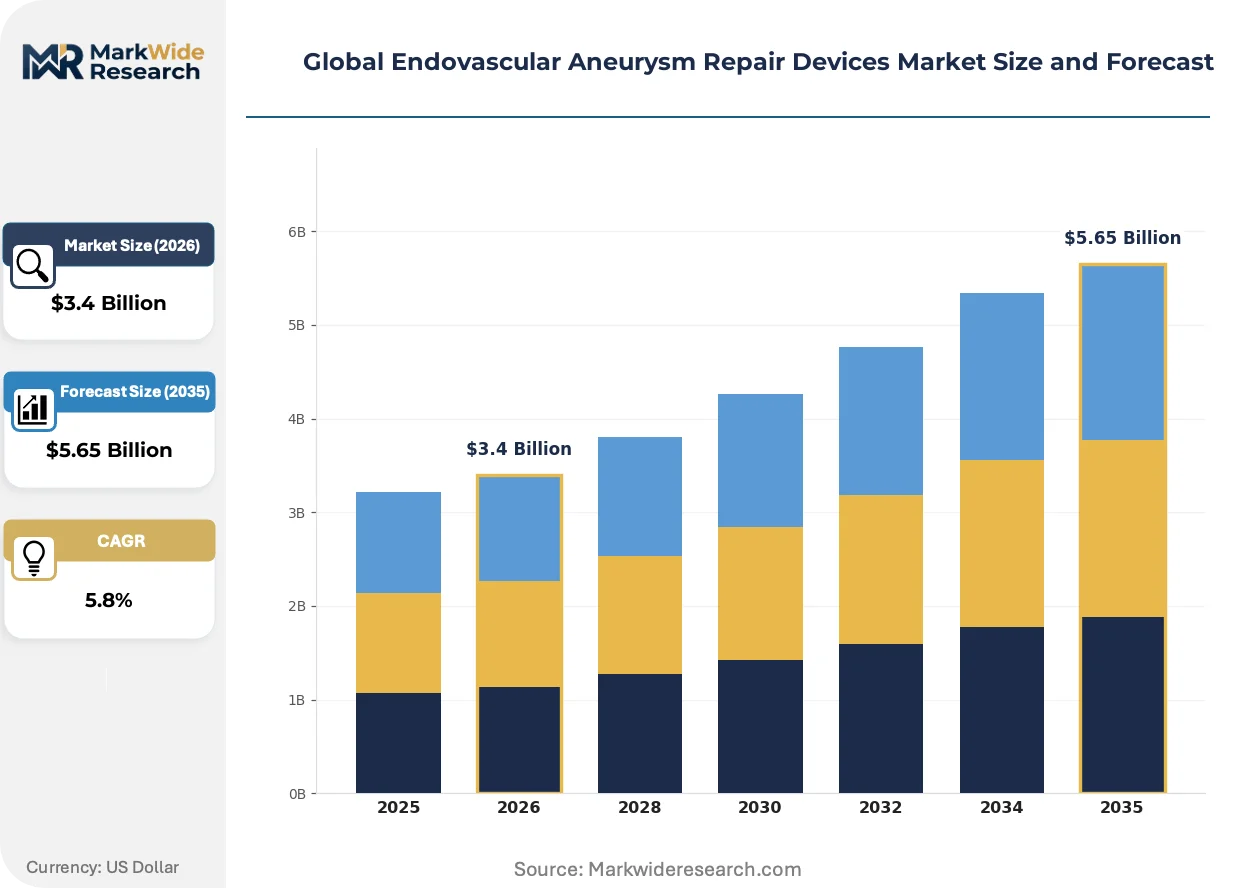
Market Dynamics
Physician training infrastructure and procedural reimbursement frameworks now determine competitive positioning more than device innovation cycles, as vascular surgery suites consolidate purchasing authority around integrated supply contracts.
Growth Catalysts
- Japan PMDA Shonin pathway:Domestic clinical trial requirements filter market entry to manufacturers with sustained investment capacity, creating defensive moats for established players.
- Nitinol superelastic recovery properties:Kink resistance and fatigue performance enable complex aortic anatomies previously requiring open surgical repair.
- Vascular surgery clinic consolidation:Minimally invasive procedure volume concentrates in high-throughput centers with dedicated endovascular suites and specialized nursing staff.
Market Restraints
- European notified body capacity constraints:MDR conformity assessment timelines extend product launch windows by 12-18 months versus historical CE marking cycles.
- Cobalt chromium foundry concentration:Thoracic stent graft radial strength requirements depend on limited North American and European metallurgical suppliers.
- Endoleak revision economics:Type II endoleak management protocols create unpredictable follow-on procedure costs that complicate hospital budgeting.
Strategic Opportunities
- India CDSCO regulatory harmonization:Emerging domestic clinical trial infrastructure enables first-mover positioning in underpenetrated abdominal aortic aneurysm screening populations.
- Fenestrated and branched stent graft convergence:Customized physician-specific designs integrate with 3D-printed modeling workflows for juxtarenal anatomies.
- Hospital-at-home reimbursement pilots:Post-EVAR monitoring protocols shift toward remote patient surveillance, opening ambulatory device service channels.
Industry Challenges
- Interventional radiology-vascular surgery credentialing overlap:Procedural ownership disputes complicate sales force deployment and training resource allocation in hybrid operating rooms.
- Legacy ERP integration with device traceability systems:Unique device identifier mandates require supply chain software upgrades that strain mid-tier manufacturer IT budgets.
- Polymer sheeting sterilization validation:ePTFE lamination process changes trigger extensive biocompatibility re-testing under ISO 10993 protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endovascular Aneurysm Repair Devices Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Grafts, Balloon Catheters, Guidewires, Sheaths, Delivery Systems Application: Abdominal Aortic Aneurysm, Thoracic Aortic Aneurysm, Peripheral Aneurysm, Cerebral Aneurysm End User: Vascular Surgery Clinics, Cardiology Centers, Diagnostic Labs, Specialty Hospitals Technology: Cobalt Chromium, Nitinol, Stainless Steel, Polymer Coating, Bioactive Surface |
| Companies Covered | Medtronic, Cook Medical, W. L. Gore & Associates, Terumo Corporation, Endologix, Boston Scientific, Cardinal Health, Getinge, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endovascular Aneurysm Repair Devices Market Shifts & Advancements
Computational modeling and intraoperative imaging fusion are compressing the gap between preoperative planning and real-time deployment accuracy, reducing reliance on historical sizing algorithms.
Self-expanding nitinol stent platforms with laser-cut fenestration patterns are absorbing procedural complexity previously managed through open surgical branch vessel revascularization. High-volume aortic centers in Germany and the United States adopt these systems for juxtarenal anatomies at accelerating cadence. The technology is absorbing market share from conventional infrarenal grafts by extending endovascular eligibility to sicker patient cohorts previously excluded from EVAR protocols.
EU MDR Article 117 requirements now mandate notified body involvement for all Class III implantable device quality management systems, not just product conformity. This regulatory friction compresses the viable manufacturer base to entities with dedicated European regulatory affairs infrastructure. Thoracic stent graft portfolios face disproportionate impact given higher device classification complexity and clinical evidence demands.
Hospital purchasing committees now consolidate stent graft procurement through multi-year sole-source agreements tied to procedure volume commitments, displacing traditional physician preference item selection. Integrated delivery networks in the United States negotiate these contracts directly with manufacturers, bypassing distributor intermediaries. This channel compression concentrates pricing power among health systems with annual EVAR volumes exceeding 200 procedures.
Global Endovascular Aneurysm Repair Devices Market Segmentation
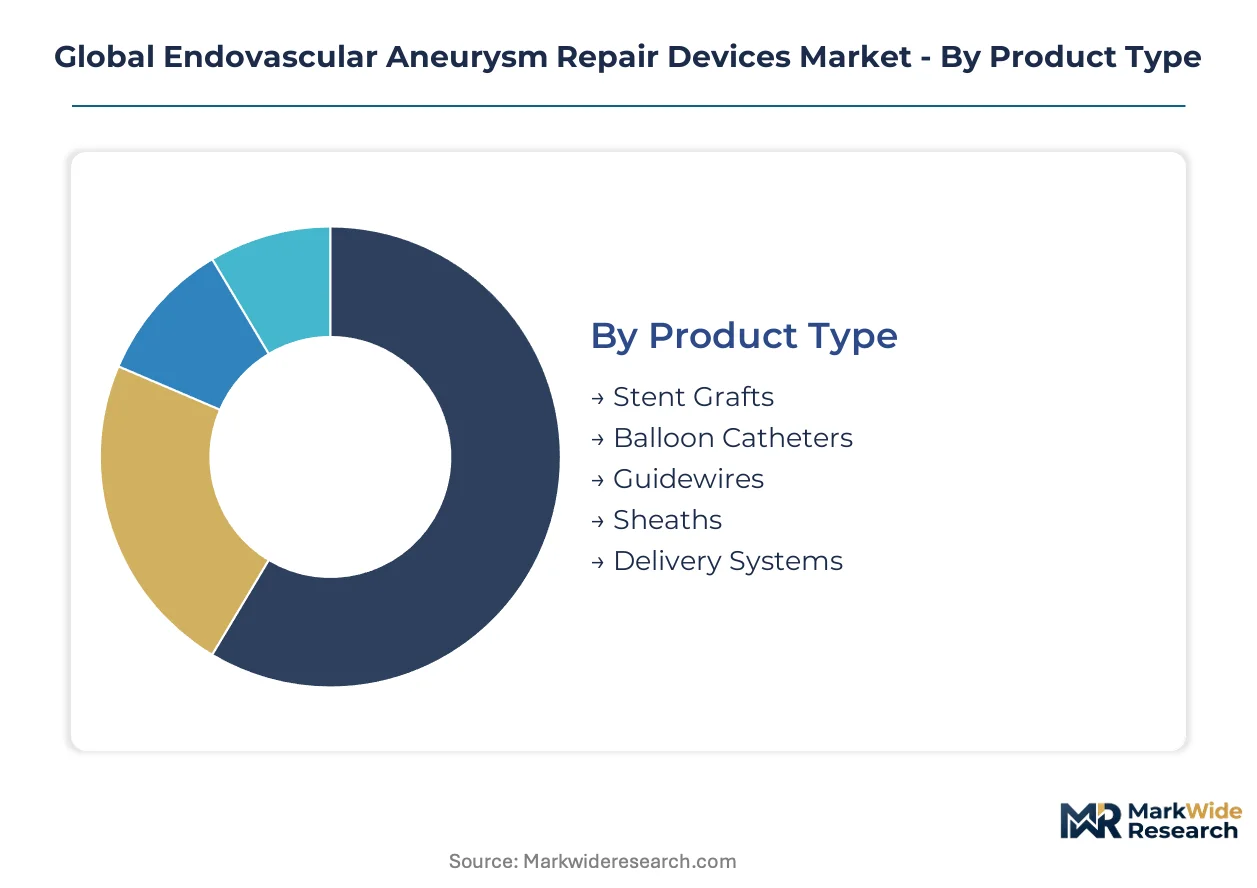
Device segmentation in endovascular aneurysm repair reveals how capital concentrates in implantable systems versus disposable accessories, and how material science investments partition competitive advantage across anatomical applications.
Product Type:
Stent grafts command premium pricing per procedure while balloon catheters scale through volume penetration in seal zone optimization protocols.
- Stent Grafts:Self-expanding or balloon-expandable metal frameworks sheathed in expanded polytetrafluoroethylene or polyester fabric, designed to exclude aneurysmal sacs from arterial pressure. Demand concentrates in Germany and the United States where high-throughput aortic centers perform complex juxtarenal anatomies requiring fenestrated designs. FDA pre-market approval pathways and EMA MDR compliance costs filter viable manufacturers to entities with dedicated regulatory infrastructure.
- Balloon Catheters:High-pressure inflatable systems for intraoperative angioplasty of seal zones and branch vessel origins. Adoption accelerates in vascular surgery clinics across Japan where PMDA Shonin requirements favor established suppliers with sustained domestic clinical trial investment. Operators deploy these adjunctively to optimize proximal fixation and reduce Type Ia endoleak incidence.
- Guidewires:Hydrophilic-coated steerable platforms enabling catheter navigation through tortuous iliac anatomy.
- Sheaths:Large-bore vascular access conduits ranging 14–24 French for stent graft delivery system introduction.
- Delivery Systems:Integrated deployment handles with trigger mechanisms controlling stent graft unsheathing under fluoroscopy.
Today's leader: Stent Grafts. Tomorrow's challenger: Balloon Catheters.
Application:
Anatomical targeting determines reimbursement coding complexity and long-term durability surveillance requirements.
- Abdominal Aortic Aneurysm:Infrarenal and juxtarenal sac exclusion represents the procedural volume foundation across all major markets. Screening programs in the United States and Germany identify expanding eligible populations, while Japan's aging demographics sustain procedure growth despite PMDA regulatory friction.
- Thoracic Aortic Aneurysm:Descending aortic pathology requiring cobalt chromium radial strength exceeding nitinol fatigue limits. European notified body capacity constraints under MDR Article 117 disproportionately delay thoracic portfolio launches given higher device classification and clinical evidence demands.
- Peripheral Aneurysm:Popliteal and visceral artery applications with specialized sizing requirements.
- Cerebral Aneurysm:Intracranial flow diversion and stent-assisted coiling outside traditional EVAR protocols.
Abdominal applications anchor current revenue. Thoracic segments are climbing the fastest as cobalt chromium platforms extend endovascular eligibility.
End User:
Site-of-care consolidation shifts purchasing authority from individual physicians to integrated delivery network procurement committees.
- Vascular Surgery Clinics:Dedicated endovascular suites with specialized nursing staff and hybrid operating room infrastructure. United States-based integrated delivery networks now negotiate sole-source agreements tied to annual procedure volume commitments exceeding 200 EVARs, bypassing distributor intermediaries entirely.
- Cardiology Centers:Interventional cardiology suites expanding into peripheral vascular territory. Credentialing overlap between interventional radiology and vascular surgery complicates sales force deployment and training resource allocation in these hybrid environments.
- Diagnostic Labs:Preoperative imaging and surveillance monitoring sites.
- Specialty Hospitals:High-acuity centers managing complex aortic pathology.
Vascular surgery clinics dominate implantable device procurement. Cardiology centers are gaining share fastest as procedural ownership boundaries blur.
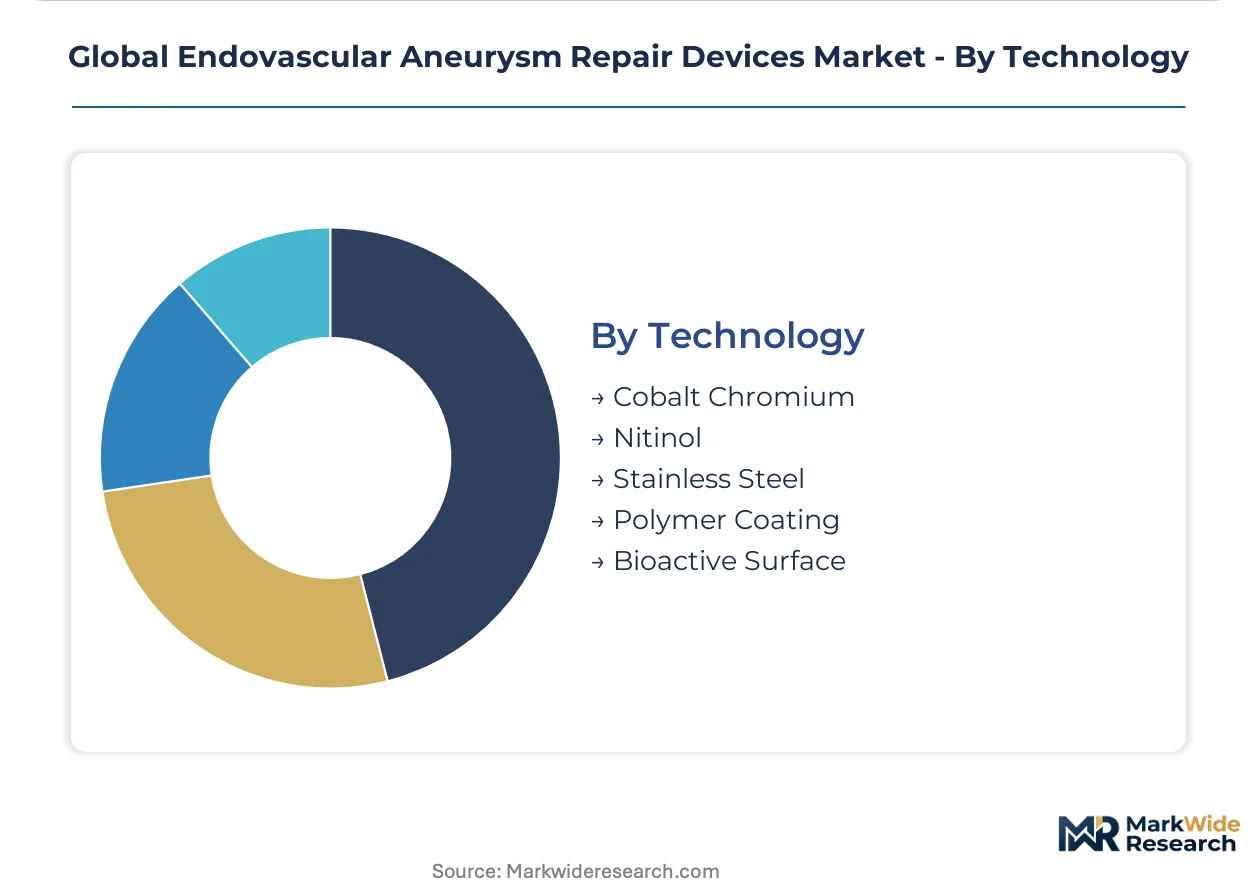
Technology:
Material selection traces directly to anatomical loading requirements and fatigue performance specifications.
- Nitinol:Nickel-titanium alloy delivering superelastic recovery and kink resistance for self-expanding platforms. Nitinol wire drawing capacity in Europe is decoupling from Asian polymer sheeting supply, creating regional sourcing asymmetries for stent graft manufacturers with integrated production.
- Cobalt Chromium:High radial strength alloy for thoracic applications where fatigue limits exceed nitinol capabilities. Foundry concentration in North America and Europe creates supply vulnerability for thoracic stent graft portfolios dependent on these metallurgical suppliers.
- Stainless Steel:Balloon-expandable platforms for precise diameter control.
- Polymer Coating:ePTFE and polyester fabric lamination technologies.
- Bioactive Surface:Endothelialization-promoting modifications under early clinical evaluation.
Nitinol platforms anchor current production. Cobalt chromium systems show the steepest expansion trajectory as thoracic indications absorb procedural complexity from open surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in procedural concentration, with German aortic centers consolidating complex fenestrated repairs while US integrated delivery networks optimize throughput across broader geographic footprints.
United States
Medicare reimbursement frameworks and aging demographics sustain procedure volumes across abdominal and thoracic indications. FDA pre-market approval pathways filter viable manufacturers to entities with dedicated regulatory infrastructure and sustained clinical trial investment. High-throughput aortic centers in Texas and Florida anchor demand for fenestrated stent graft systems.
Germany
Established screening programs and vascular surgery specialization drive per-capita EVAR penetration above European averages. EMA MDR Article 117 compliance costs and notified body capacity constraints extend product launch timelines for thoracic portfolios. Industrial clusters in Baden-Württemberg and Bavaria concentrate nitinol wire drawing and polymer lamination capabilities.
Japan
PMDA Shonin approval requirements mandate domestic clinical trials that limit market entry to manufacturers with sustained Japan investment capacity. Aging demographics and established universal health coverage sustain procedure growth despite regulatory friction. Tokyo and Osaka metropolitan areas concentrate specialized endovascular suites and hybrid operating room infrastructure.
India
Underpenetrated abdominal aortic aneurysm screening populations and expanding private hospital networks create first-mover positioning opportunities. CDSCO regulatory harmonization with international standards accelerates product registration pathways for established manufacturers. Maharashtra and Karnataka host emerging domestic clinical trial infrastructure and vascular surgery training programs.
United Kingdom
NHS procurement frameworks consolidate purchasing authority around multi-year supply agreements tied to volume commitments. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while streamlining conformity assessment for UK-specific labeling. London and the Southeast concentrate high-acuity aortic centers managing complex thoracic pathology.
Global Endovascular Aneurysm Repair Devices Market Competitive Landscape
North American producers anchor the premium-tier stent graft segment; European specialists hold differentiated positions in physician training infrastructure and metallurgical supply chains. Market structure concentrates around integrated manufacturers with captive nitinol foundry capacity and dedicated regulatory affairs divisions. Three archetypes dominate: diversified cardiovascular conglomerates with endovascular franchises, mid-cap specialists focused exclusively on aortic therapies, and component suppliers backward-integrated into finished device assembly. Competitive moves center on multi-year sole-source hospital contracts and geographic expansion through regulatory first-mover positioning in emerging markets.
Among diversified cardiovascular conglomerates, Medtronic and Boston Scientific exemplify scale-driven archetypes with integrated manufacturing footprints spanning cobalt chromium metallurgy and polymer lamination. Cook Medical occupies a specialist position emphasizing physician training infrastructure and vascular surgery suite relationships. These three entities represent distinct competitive vectors: manufacturing scale, clinical education depth, and technology platform breadth.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| W. L. Gore & Associates |
| Terumo Corporation |
| Endologix |
| Boston Scientific |
| Cardinal Health |
| Getinge |
| Abbott |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists anchor the nitinol wire drawing tier, translating captive metallurgical capacity into pricing discipline that resists commoditization pressure from Asian polymer sheeting imports. Their ownership structure insulates procurement decisions from quarterly earnings cycles, enabling long-term supply contracts with German and Japanese stent graft assemblers that stabilize input costs across volatile nickel markets.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for cobalt chromium thoracic platforms as foundry investments ease metallurgical scarcity premiums. Three-tier pricing structure across premium, standard, and economy levels separates fenestrated custom designs from stock infrarenal grafts and entry-level balloon catheters. Cost compression in standard-tier stent grafts is intensifying because hospital-at-home reimbursement pilots demand lower per-procedure device economics. Integrated delivery networks with annual EVAR volumes exceeding 200 procedures exhibit least price sensitivity, while mid-tier community hospitals face acute budget constraints.
Supply Chain Analysis
Nitinol alloy supply rests on European wire drawing specialists in Baden-Württemberg and Bavaria, with cobalt chromium feedstock concentrated in North American and European foundries. Raw material dependencies span nickel-titanium billet, expanded polytetrafluoroethylene resin, and high-purity cobalt chromium rod. Single-source vulnerability in thoracic-grade metallurgy exposes manufacturers to disruption from mining concentration in the Democratic Republic of Congo and Russia. Distribution runs through direct hospital contracts negotiated by high-volume aortic centers, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA MDR Article 117 implementation and FDA pre-market approval pathway extensions continuously elevate compliance costs that filter weaker competitors from viable manufacturer pools.
For Market Incumbents: Cement defensive positioning through captive cobalt chromium foundry investments and dedicated European regulatory affairs infrastructure that accelerates MDR conformity assessment timelines. Threat from fenestrated design convergence demands deepening physician training infrastructure to lock in vascular surgery suite relationships. Capacity addition in German nitinol wire drawing secures margin resilience against Asian polymer sheeting cost pressure. For New Entrants and Emerging Players: Laser-cut fenestration pattern software offers a technology-first wedge into juxtarenal anatomies previously requiring open surgical branch vessel revascularization. White-space targets concentrate in India's underpenetrated abdominal aortic aneurysm screening populations and CDSCO regulatory harmonization pathways. Go-to-market through 3D-printed modeling workflow partnerships with high-volume aortic centers bypasses incumbent sales force density. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking integrated metallurgical supply and facing ERP integration costs for unique device identifier mandates. Long-term viability favors entities with backward integration into nitinol or cobalt chromium production and sustained Japan PMDA investment capacity. Watch EVAR-2 trial durability data recalibrations as the signal for reimbursement shifts between endovascular and open surgical protocols.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Market Approval Pathway | Filters viable manufacturers to entities with dedicated clinical trial infrastructure and sustained regulatory investment capacity. |
| CE Marking Pathway under MDR Article 117 | Extends conformity assessment timelines, compressing manufacturer base to those with European notified body relationships. |
| Hospital System Partnership | Enables multi-year sole-source agreements tied to annual procedure volume commitments exceeding 200 EVARs. |
| Software Companion Development | Integrates computational modeling and intraoperative imaging fusion for real-time deployment accuracy improvements. |
| Reimbursement Strategy | Aligns device portfolio with Medicare frameworks and hospital-at-home pilot protocols shifting toward remote patient surveillance. |
Research Methodology
Multiple input streams — vascular surgeon interviews, hospital purchasing committee discussions, biomedical engineer consultations, and GPO contracts manager surveys — were reconciled against FDA 510(k) and PMA filings, EMA MDR submission databases, CMS Medicare procedure volume data, and hospital procurement contract records. Primary fieldwork with clinicians and procurement officers in Texas, Florida, Baden-Württemberg, and Tokyo informed demand assumptions. Bottom-up stent graft shipment modeling and top-down healthcare expenditure allocation cross-validated market sizing across the analysis window.
Historical procedural volume trajectories were cross-referenced against panel input from regulatory affairs specialists and reimbursement consultants to anchor growth assumptions. Segmentation dimensions spanned product type, anatomical application, end-user site-of-care, and material technology platform. CAGRs were derived from fitted trend lines adjusted for regulatory milestone impacts and demographic projection inputs including aging population indices and screening program penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EVAR-2 trial durability recalibrations, cobalt chromium supply disruptions, and PMDA Shonin pathway modifications. Forecasts reflect documented assumptions on procedure volume concentration, reimbursement stability, and regulatory timeline continuity. A small set of named triggers — thoracic stent graft radial strength failures, EU notified body capacity collapse, and India CDSCO harmonization reversals — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurointerventional Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Hydrocephalus Shunts Market