
 North America Dental Implants and Prosthetics Market | 2026-2036
North America Dental Implants and Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dental Implants and Prosthetics Market Insights
Mexican contract manufacturers is expanding production capacity for titanium implant abutments serving U.S. distributors. Zimmer Biomet leverages vertical integration across implant design and surgical instrumentation to sustain pricing power in premium segments. Institut Straumann anchors its North American position through intensive R&D spending on digital workflow integration. Danaher competes via its dental equipment and consumables platform, while Dentsply Sirona controls distribution reach through direct sales to large dental service organizations.
Dental implants and prosthetics comprise surgically placed fixtures and custom-fabricated restorations that replace missing teeth, with endosteal titanium screws typically measuring 3.0–6.0 mm in diameter and 7.0–16.0 mm in length, osseointegrating over 3–6 months before crown attachment. These devices restore masticatory function and aesthetic appearance for edentulous and partially edentulous patients across clinical and commercial settings. Endosteal implants dominate procedure volumes due to established biomechanical reliability, while zirconia materials gain share among patients seeking metal-free alternatives. Dental clinics represent the largest end-user channel, though prosthodontists capture disproportionate margin pools through complex full-arch reconstructions.
FDA 510(k) clearance requirements govern implant device commercialization, while Health Canada's Medical Devices Bureau enforces parallel standards across Canadian provinces. State dental boards in California, Texas, and New York regulate practitioner scope and continuing education for implant placement. OSHA bloodborne pathogen standards and CDC infection control guidelines shape clinic-level procurement of sterile implant kits and disposable surgical components. Stakeholders must monitor evolving FDA guidance on 3D-printed patient-specific implants and provincial reimbursement shifts affecting Canadian procedure accessibility.
Market Dynamics
Digital surgical planning platforms and chairside CAD/CAM milling are compressing restoration turnaround times from weeks to hours, forcing traditional dental laboratories to defend their position against in-clinic production networks across the United States and Canada.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Accelerated clearance timelines for titanium endosteal systems reduce commercialization barriers for innovative implant geometries. Device developers leverage predicate device databases to fast-track regulatory submissions.
- Prosthodontist-Led Complex Reconstruction Demand:Full-arch rehabilitation procedures generate premium procedure volumes in California, Texas, and Florida metropolitan clusters. These specialists command disproportionate margin pools through immediate-load protocols.
- Zirconia Bioceramics:Metal-free alternatives capture patient preference segments seeking aesthetic superiority and reduced peri-implant inflammation risk. Material science advances in yttria-stabilized tetragonal zirconia polycrystal enhance fracture resistance.
Market Restraints
- Titanium Feedstock Concentration:Sponge and mill product supply concentrates among limited North American and Asian suppliers. Price volatility in aerospace-grade titanium ripples into medical device input costs.
- Osseointegration Timeline Rigidity:Three-to-six-month healing protocols constrain procedure throughput regardless of implant surface modifications. Immediate-loading remains restricted to select bone density categories.
- Private Payer Reimbursement Gaps:Canadian provincial plans and U.S. dental insurance exclude implant procedures from standard coverage. Out-of-pocket payment requirements limit addressable patient populations.
Strategic Opportunities
- Mexican Manufacturing Proximity:Contract manufacturers in Tijuana and Monterrey expand titanium abutment production capacity for U.S. distributor networks. Maquiladora cost structures enable competitive export positioning.
- Guided Surgery Convergence:Integration of cone-beam computed tomography with 3D-printed surgical stents reduces chair time and improves placement accuracy. Prosthodontists adopt these workflows for complex multi-unit cases.
- Same-Day Restoration Protocols:Chairside milling and intraoral scanning enable single-visit crown delivery in select clinical scenarios. This channel innovation targets time-sensitive professional and executive patient segments.
Industry Challenges
- Digital Workflow Integration Complexity:Legacy practice management systems resist seamless data exchange with modern CAD/CAM platforms. IT infrastructure upgrades demand capital deployment and staff retraining.
- Implantologist Certification Variability:State dental boards maintain inconsistent continuing education requirements for surgical placement authority. California, Texas, and New York standards diverge on didactic hour minimums and supervised case volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dental Implants and Prosthetics Market |
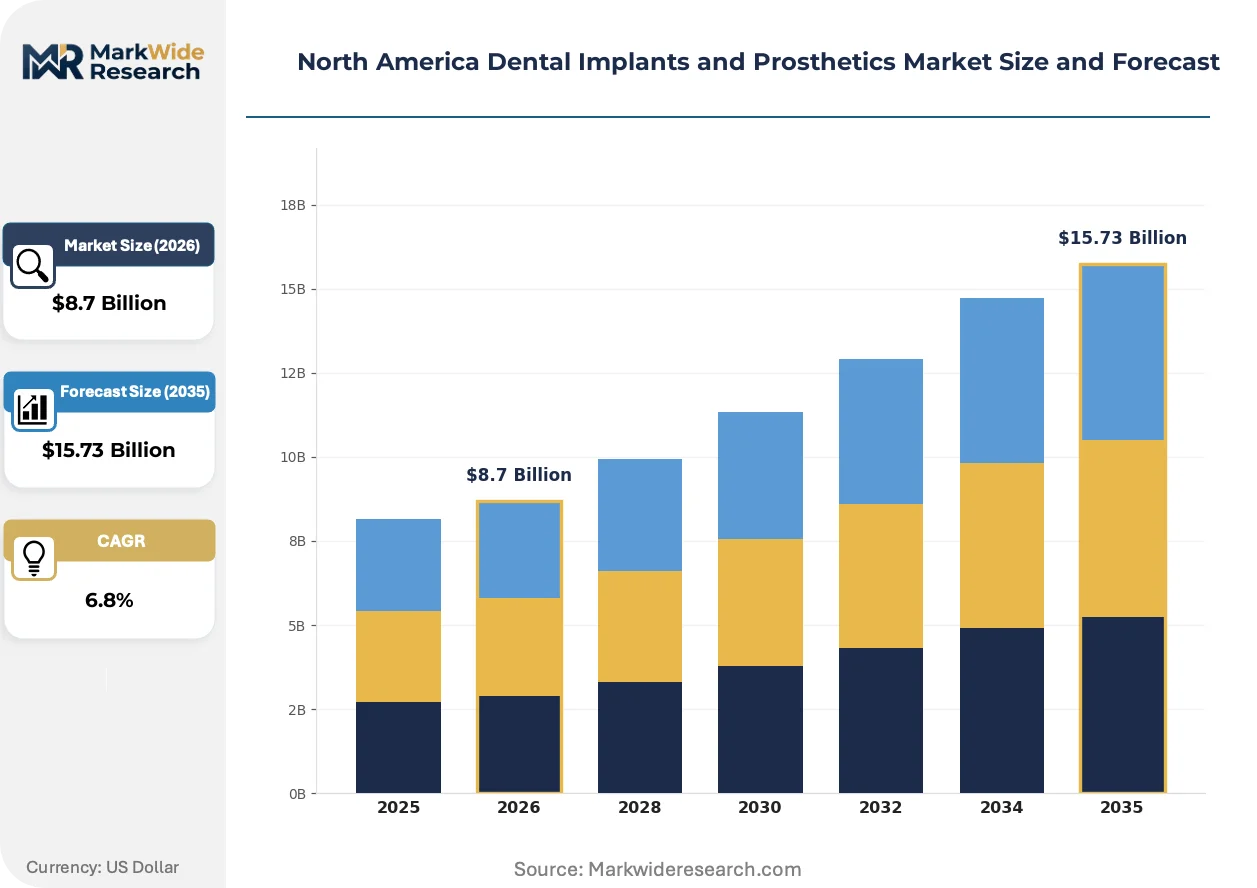
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal Implants, Subperiosteal Implants, Transosteal Implants, Dental Crowns Material: Titanium, Zirconia, Stainless Steel, Polymer End User: Dentists, Oral Surgeons, Prosthodontists, Dental Clinics Distribution Channel: Direct Sales, Online Retail, Distributors, Dental Supply Stores |
| Companies Covered | Henry Schein, Zimmer Biomet, Institut Straumann, BioHorizons, Danaher, Envista Holdings Corporation, ZimVie, Bicon, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dental Implants and Prosthetics Market Trends and Innovations
Computer-guided surgical protocols and patient-specific implant geometries are redrawing competitive boundaries between premium device manufacturers and value-oriented suppliers across North American dental markets.
Intraoral scanning systems are modularizing traditional impression workflows by eliminating elastomeric material steps and enabling direct digital transmission to milling centers or in-office production units. General practitioners and prosthodontists in Ontario and California adopt these platforms at accelerating rates. The technology is modularizing laboratory service relationships and compressing the geographic radius of supplier relevance.
Health Canada's Medical Devices Bureau and the FDA maintain parallel scrutiny of 3D-printed patient-specific implants through evolving guidance documents on additive manufacturing quality systems. Industrial consequence includes heightened documentation burdens for design history files and process validation protocols. Canadian manufacturers targeting U.S. market entry face dual compliance architecture requiring synchronized quality management system investments.
Large dental service organizations consolidate procurement authority across multi-site networks, displacing individual practitioner discretion in implant system selection. DSOs in Texas and Florida negotiate enterprise pricing agreements with preferred manufacturers. This concentration is most visible in Sun Belt metropolitan markets where corporate dentistry penetration exceeds national averages.
North America Dental Implants and Prosthetics Market Segmentation
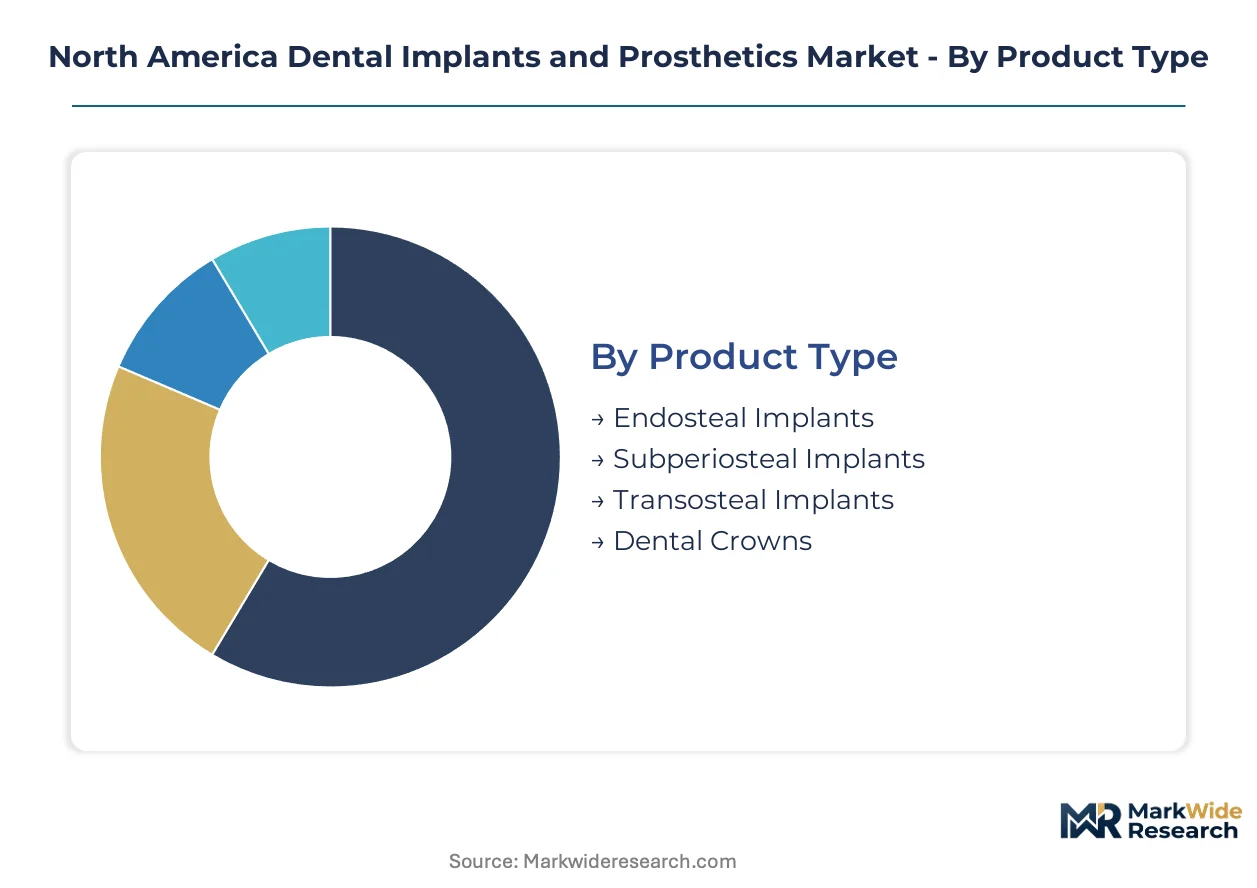
Segmentation in North American dental implants reveals how regulatory pathways, material science trajectories, and channel economics create distinct competitive arenas. Each dimension carries specific FDA 510(k) or Health Canada clearance burdens that shape manufacturer resource allocation and go-to-market timing.
Product Type:
FDA 510(k) clearance requirements vary sharply across implant geometries, with endosteal systems leveraging predicate databases while transosteal designs face novel device scrutiny.
- Endosteal Implants:Titanium screws measuring 3.0–6.0 mm in diameter anchor directly into jawbone, with surface-modified variants commanding premium positioning in California and Texas metropolitan clusters where prosthodontist density drives complex case volumes. FDA predicate pathways accelerate commercialization for threaded cylinder designs.
- Dental Crowns:Custom-fabricated restorations—milled from zirconia blocks or layered porcelain—complete the implant superstructure, with chairside CAD/CAM production compressing turnaround from dental laboratories in Ontario and Florida to same-day delivery protocols. Health Canada's Medical Devices Bureau classifies these as Class II devices with streamlined quality system requirements.
- Subperiosteal Implants:Custom metal frameworks sit atop bone for patients with inadequate vertical bone height, requiring patient-specific casting and extended FDA review timelines.
- Transosteal Implants:Penetrating mandibular designs serve severe atrophy cases through limited U.S. oral surgery centers, with novel device designation triggering PMA pathway requirements.
Endosteal implants sit at the top of the volume ranking, with dental crowns climbing the fastest as digital workflows expand in-clinic production capacity.
Material:
Raw material certification tiers separate aerospace-grade titanium from emerging bioceramics, with supply concentration in sponge production creating cost stratification.
- Titanium:Commercially pure grades and Ti-6Al-4V alloys dominate implant fixtures, with osseointegration performance validated across decades of clinical data. California and New York dental clusters source primarily from North American mill products suppliers.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal offers metal-free alternatives for aesthetic-sensitive patients, with fracture resistance improvements expanding prosthodontist adoption in Florida and Ontario. Health Canada maintains parallel biocompatibility testing standards to FDA.
- Stainless Steel:Surgical-grade alloys serve temporary abutments and provisional restorations through cost-sensitive distributor channels.
- Polymer:PEEK and PMMA materials enable provisional crowns and surgical guides, with 3D-printed patient-specific applications drawing evolving FDA guidance on additive manufacturing quality systems.
Titanium retains dominant volume position, while zirconia gains share fastest among metal-averse patient segments.
End User:
Credentialing requirements diverge across state dental boards, with surgical scope authority creating distinct procurement behaviors.
- Prosthodontists:Three-year accredited residency training qualifies these specialists for complex full-arch reconstructions, commanding premium procedure fees in Texas and California DSO networks. Immediate-load protocols and guided surgery adoption concentrate in this segment.
- Dental Clinics:Multi-practitioner settings aggregate procurement volume, with large DSOs in Florida and Ontario negotiating enterprise pricing agreements that displace individual practitioner discretion.
- Oral Surgeons:Maxillofacial specialists handle bone grafting and complex placement, with hospital-affiliated practices in New York maintaining distinct supply chain relationships.
- Dentists:General practitioners deliver single-unit restorations through distributor-mediated implant systems, with continuing education variability across state boards constraining surgical placement authority.
Dental clinics aggregate the highest procedure volume, with prosthodontists expanding fastest through DSO integration.
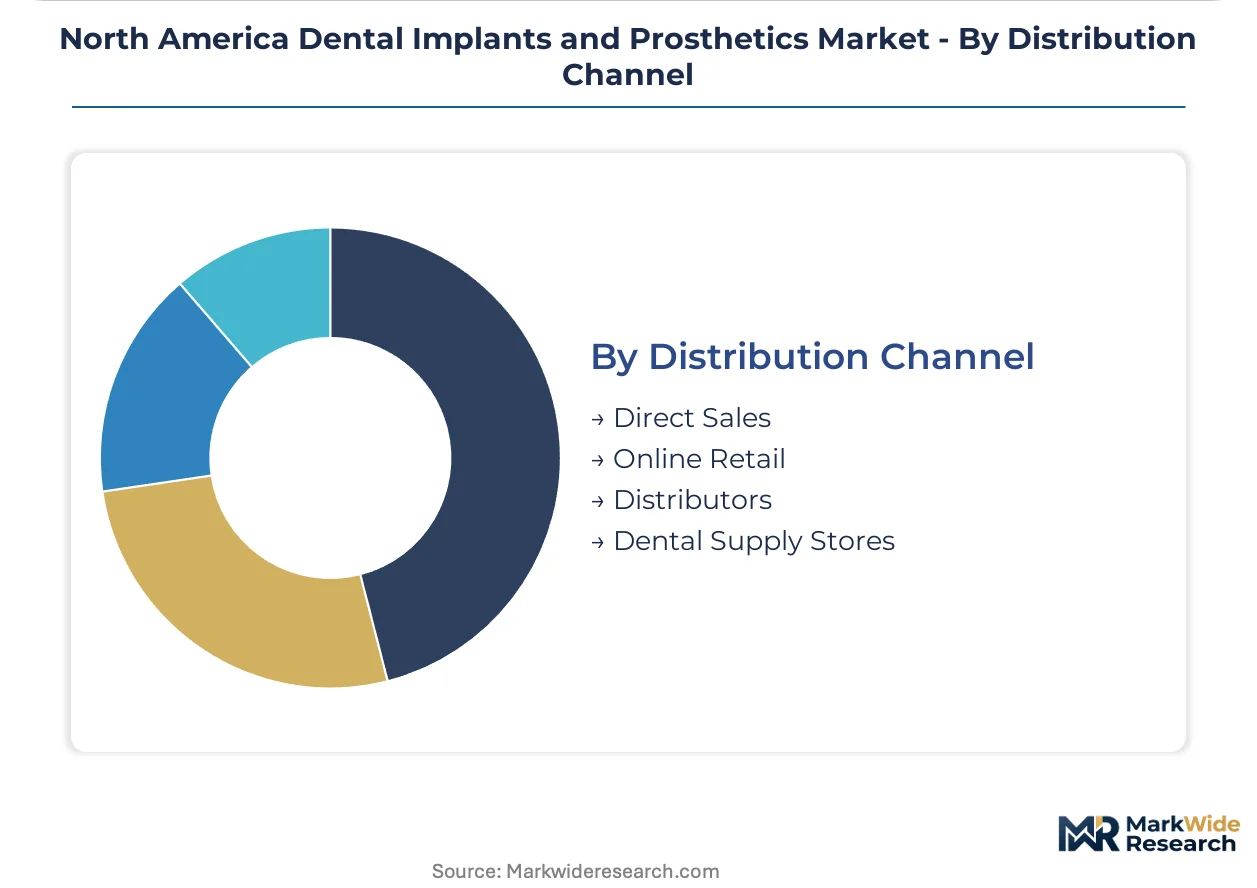
Distribution Channel:
Channel economics reflect inventory carrying costs and technical support requirements, with digital platforms disrupting traditional dental supply relationships.
- Direct Sales:Manufacturers maintain dedicated representatives for high-volume prosthodontist accounts and DSO headquarters in Texas and California, offering surgical instrumentation bundling and digital workflow training.
- Distributors:Henry Schein and Patterson Dental aggregate fragmented general practitioner demand across U.S. states and Canadian provinces, with regional warehouses enabling next-day implant kit delivery.
- Dental Supply Stores:Local counters serve emergency replacement components and consumables, with limited implant fixture inventory due to sterilization and traceability requirements.
- Online Retail:E-commerce platforms capture auxiliary products—healing abutments, impression copings—while implant fixtures remain restricted to professional credential verification.
Distributors handle the greatest transaction volume, with direct sales expanding most quickly through DSO consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger procedure volumes than Canada, though Mexican manufacturing capacity is narrowing the supply chain gap across the continent. Provincial reimbursement limitations in Canada constrain patient accessibility relative to U.S. out-of-pocket markets. Cross-border production networks now link Tijuana assembly to California distribution hubs.
United States
Prosthodontist-led full-arch reconstructions concentrate in California, Texas, and Florida metropolitan clusters where immediate-load protocols generate premium procedure fees. FDA 510(k) clearance pathways for titanium endosteal systems accelerate commercialization timelines for innovative implant geometries. Los Angeles and Houston dental service organizations negotiate enterprise pricing agreements that consolidate procurement authority across multi-site networks.
Canada
Provincial health plans exclude implant procedures from standard coverage, limiting addressable populations to private-pay segments in Ontario and Quebec. Health Canada's Medical Devices Bureau enforces Class II device standards parallel to FDA requirements, creating dual compliance architecture for manufacturers targeting both markets. Toronto prosthodontists adopt digital workflow integration at rates exceeding national averages, driving intraoral scanner penetration.
Mexico
Maquiladora operations in Tijuana and Monterrey expand titanium abutment production capacity for U.S. distributor networks seeking cost-competitive sourcing. Mexican contract manufacturers leverage proximity advantages to California and Texas dental clusters while maintaining ISO quality certifications. Guadalajara technical institutes feed engineering talent into medical device fabrication operations serving North American demand.
North America Dental Implants and Prosthetics Market Competitive Landscape
U.S.-based producers anchor the premium-tier implant segment; Swiss and German specialists hold differentiated positions in digital workflow integration. The vendor base stratifies across three tiers: multinational conglomerates with dental platform breadth, pure-play implant manufacturers with vertical control over surgical instrumentation, and regional distributors aggregating fragmented general practitioner demand. Strategic archetypes include DSO-focused direct sales organizations, R&D-intensive premium device developers, and value-oriented contract manufacturers. Dominant competitive moves encompass backward integration into titanium feedstock sourcing and strategic partnerships with cone-beam computed tomography platform developers.
Within the premium device tier, Zimmer Biomet and Institut Straumann occupy positions emphasizing surgical instrumentation bundling and digital workflow training. Among distributor-anchored players, Henry Schein exemplifies the fragmented general practitioner aggregation model through regional warehouse networks enabling next-day implant kit delivery. Dentsply Sirona represents the dental platform conglomerate archetype with direct sales penetration into large dental service organizations.
| Leading Market Players |
|---|
| Henry Schein |
| Zimmer Biomet |
| Institut Straumann |
| BioHorizons |
| Danaher |
| Envista Holdings Corporation |
| ZimVie |
| Bicon |
| Dentsply Sirona |
| Others |
Pricing and Supply Chain Analysis
Aerospace-grade titanium sponge price indices cascade through North American dental implant supply chains, compressing margins for value-tier distributors while premium manufacturers absorb volatility through captive mill relationships and long-term offtake contracts with Japanese and Russian feedstock suppliers.
Pricing Analysis
Distributor margin layers stratify pricing across Henry Schein and Patterson Dental networks, with 15-25 point markups separating wholesale implant fixture costs from clinic-level procurement. Three-tier pricing structure across premium, standard, and economy levels reflects surface modification technology, FDA predicate pathway vintage, and bundled surgical instrumentation. Cost compression in economy-tier titanium screws is intensifying because Mexican maquiladora abutment production feeds price-competitive distributor channels. General practitioner segments exhibit highest price sensitivity, while prosthodontist-led DSO networks prioritize workflow integration over unit cost.
Supply Chain Analysis
Reverse-logistics flows for surgical guide remanufacturing and implant retrieval components remain underdeveloped, constraining circular economy participation despite FDA guidance on reprocessing validation. Titanium sponge production concentrates in Japan, Russia, and Kazakhstan, with U.S. mill product fabrication anchoring downstream fixture manufacturing. Supply chains draw from yttria-stabilized zirconia feedstock sourced from European ceramic powder specialists and Chinese processed bioceramics. Single-source vulnerability in aerospace-grade titanium sponge creates exposure to export restriction shocks. Distribution runs through regional dental distributor warehouses with next-day delivery commitments to California and Texas metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway streamlining functions as a regulatory compounder, accelerating commercialization timelines for innovative implant geometries and expanding addressable procedure volumes across U.S. metropolitan dental markets.
For Market Incumbents: Deploy backward integration into titanium feedstock sourcing to secure margin insulation against aerospace-grade sponge volatility. Incumbent manufacturers should consolidate distributor relationships through exclusive digital workflow bundling, countering Henry Schein and Patterson Dental price transparency initiatives. Capacity addition in Monterrey maquiladora operations preserves cost competitiveness for U.S. distributor networks facing Mexican contract manufacturer encroachment.
For New Entrants and Emerging Players: Capture chairside CAD/CAM restoration segments where traditional dental laboratory displacement creates white-space opportunity. New entrants should target Ontario and Quebec private-pay markets where Health Canada Class II device pathways offer faster clearance than FDA predicate routes. Digital-native go-to-market positioning through cloud-based surgical planning subscriptions bypasses incumbent direct sales force scale advantages.
For Investors and Strategic Acquirers: Asymmetric upside sits with Mexican contract manufacturers possessing ISO 13485 certifications and California distribution hub proximity. Long-term viability centers on five-to-ten year DSO procurement consolidation trajectories, with enterprise pricing agreement penetration serving as inflection indicator. Acquisition target archetypes include cone-beam computed tomography software developers and patient-specific implant additive manufacturing specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Database Expansion | Accelerated clearance timelines reduce commercialization barriers for threaded cylinder innovations. |
| Digital Workflow Platform Integration | Intraoral scanner and CAD/CAM bundling displaces traditional dental laboratory relationships. |
| Maquiladora Manufacturing Scale-Up | Tijuana and Monterrey capacity expansion enables cost-competitive titanium abutment export positioning. |
| DSO Enterprise Pricing Agreements | Multi-site procurement consolidation in Texas and Florida displaces individual practitioner discretion. |
| Zirconia Bioceramic R&D Investment | Yttria-stabilized tetragonal zirconia polycrystal advances capture metal-averse patient preference segments. |
Research Methodology
Bottom-up prosthodontist procedure volume modeling reconciled against top-down titanium implant fixture production tracking forms the analytical core of this study. Primary interviews with oral surgeons, prosthodontists, dental service organization procurement directors, and Henry Schein regional distribution managers combined with secondary validation from FDA 510(k) clearance databases, Health Canada Medical Devices Bureau registrations, and dental laboratory industry association capacity surveys. Triangulation across implant system unit shipment data and procedure reimbursement code analysis ensures dimensional consistency.
Historical trendline analysis of endosteal implant adoption rates and digital workflow penetration patterns anchored projection frameworks across the analysis window. Segmentation modeling incorporated product type, material grade tier, end-user credentialing level, and distribution channel structure dimensions. CAGRs derived from slope-stability testing of year-over-year procedure volume trajectories, with titanium feedstock price elasticity and provincial reimbursement policy shifts serving as industry-specific forecast sensitivity inputs.
Underlying measurement precision varies by segment; endosteal implant volumes carry tighter precision than transosteal novel device categories due to predicate pathway data availability. Forecasts reflect assumptions regarding FDA guidance evolution on 3D-printed patient-specific implants and DSO market share consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
China Dental Devices Market
Dental Devices
Europe Dental Implants Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Veneers Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Dental Chair Market
Dental Devices
US Orthodontics Market
Dental Devices
Global Dental Burs Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Carpule Market
Dental Devices
North America Dental Lab Market