
 Sweden Neurology Devices Market | 2026-2036
Sweden Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Neurology Devices Market Analytics
Project finance for high-value neuroimaging suites is reconfiguring competitive access across Swedish hospital networks. Stryker Corporation leverages its deep brain stimulation portfolio to anchor premium positioning in Stockholm and Gothenburg. Medtronic PLC sustains R&D intensity across neurostimulation platforms, while Philips Healthcare competes on integrated MRI-neurophysiology workflows.
Neurology devices encompass instruments for diagnosing, monitoring, and treating disorders of the central and peripheral nervous systems, including electroencephalography systems capturing electrical activity at 256+ channels and implantable pulse generators delivering targeted electrical modulation. Deep brain stimulation and neurostimulation segments command concentrated margin pools due to surgical complexity and long-term service contracts. Electroencephalography maintains mature volume throughput across neurology clinics, while wearable devices represent the fastest-expanding technology dimension as remote patient monitoring protocols diffuse through Swedish regional health authorities.
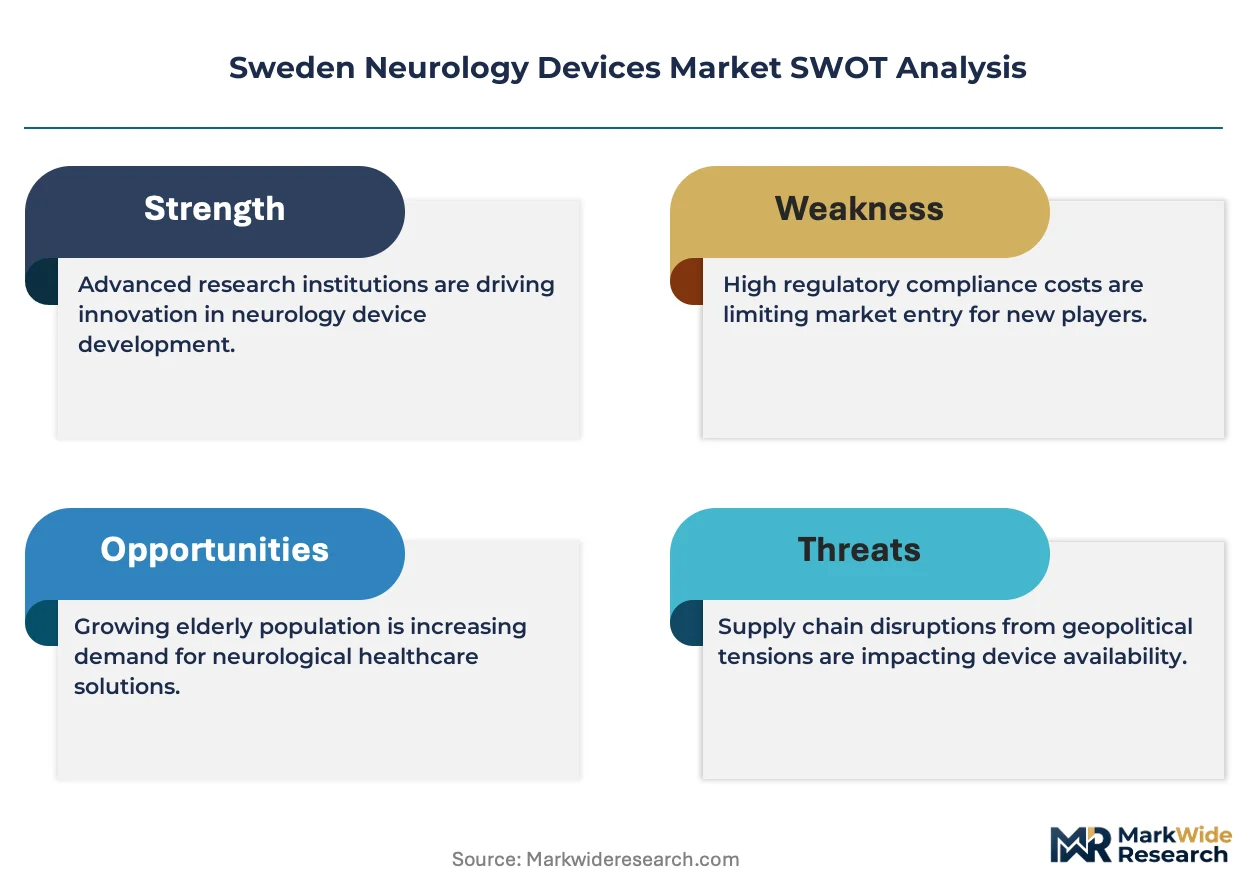
Sweden's Medical Products Agency enforces EU MDR compliance for all implantable neurology devices, while the Swedish Work Environment Authority shapes occupational exposure standards for intraoperative neurophysiology staff. The country's national pharmaceutical regulator maintains vigilance over software-as-medical-device classifications for AI-enabled EEG interpretation tools. Stakeholders must monitor how Sweden's transition to outcome-based healthcare procurement reshapes capital allocation between traditional device categories and connected monitoring platforms.
Market Dynamics
Sweden's transition to outcome-based healthcare procurement is compressing capital cycles for traditional neuroimaging equipment while accelerating subscription models for connected neurology monitoring platforms. Stockholm's university hospital cluster is reconfiguring vendor access through consolidated neurostimulation service contracts.
Growth Catalysts
- EU MDR compliance frameworks:Sweden's Medical Products Agency enforces stringent CE marking requirements for implantable neural devices, creating competitive moats for manufacturers with established regulatory infrastructure.
- Wearable neurology monitoring:Swedish regional health authorities are expanding remote patient monitoring protocols, driving hospital procurement of ambulatory EEG and seizure detection systems.
- Deep brain stimulation therapies:Stockholm and Gothenburg hospital networks are scaling neurosurgical capacity for movement disorder treatments, anchoring demand for implantable pulse generators.
Market Restraints
- Neuroimaging suite capex intensity:MRI-neurophysiology integration requires capital commitments that strain county council budgets outside Sweden's three major urban centers.
- Implantable device supply concentration:Critical components for deep brain stimulation systems depend on specialized European suppliers with limited second-source alternatives.
- AI-enabled EEG software classification:Sweden's national pharmaceutical regulator maintains ambiguous software-as-medical-device pathways, delaying market entry for automated interpretation tools.
Strategic Opportunities
- Västra Götaland and Skåne regional expansion:Secondary hospital networks outside Stockholm remain underpenetrated for advanced neurostimulation therapies, offering volume growth potential.
- Telemedicine integration:Convergence of wearable neurology devices with remote consultation platforms enables new service delivery models across Sweden's dispersed population.
- Swedish Work Environment Authority standards:Occupational exposure mandates for intraoperative neurophysiology staff are creating demand for automated monitoring and staff protection systems.
Industry Challenges
- Neurophysiology technologist scarcity:Specialized training programs for intraoperative monitoring personnel lag hospital expansion plans, constraining surgical throughput.
- Legacy EEG system integration:County council procurement of cloud-connected platforms faces interoperability friction with existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Neurology Devices Market |
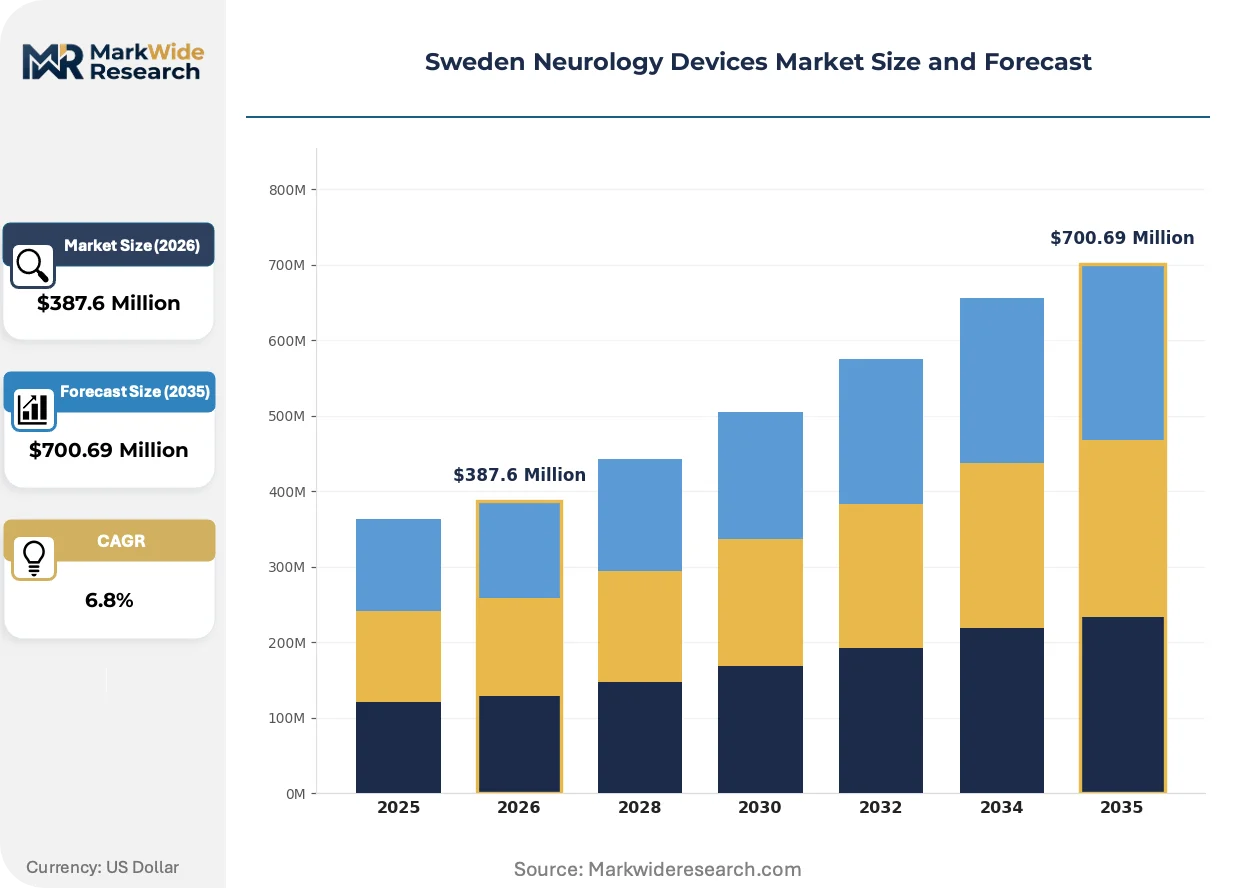
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography, Deep Brain Stimulation, Neurostimulation, MRI Systems End User: Hospitals, Neurology Clinics, Research Institutions, Rehabilitation Centers Technology: Wearable Devices, Traditional Devices, Software Solutions, Imaging Technology Application: Epilepsy Treatment, Pain Management, Stroke Rehabilitation, Cognitive Disorders |
| Companies Covered | Stryker Corporation, Boston Scientific Corporation, Medtronic PLC, Abbott Laboratories, B. Braun SE, Integra LifeSciences Corporation, Nihon Kohden Corporation, Philips Healthcare, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Neurology Devices Market Evolving Landscape
Neurology device architectures are pivoting toward closed-loop stimulation systems and edge-computing diagnostics, compressing the latency between neural signal detection and therapeutic response. Swedish healthcare procurement is rewarding vendors who bundle hardware with predictive analytics subscriptions.
Deep brain stimulation technology is migrating from fixed-parameter implantable pulse generators to adaptive systems that modulate therapy based on real-time biomarker feedback. Stockholm's university hospitals are piloting these devices for epilepsy and Parkinson's disease cohorts. This shift is compressing the service revenue model from hardware replacement cycles toward continuous algorithm optimization contracts.
Sweden's Medical Products Agency is tightening post-market surveillance requirements under EU MDR for implantable neural devices, mandating extended clinical follow-up and periodic safety reporting. Manufacturers must maintain Swedish-specific regulatory infrastructure to sustain market access. Deep brain stimulation and spinal cord stimulation product lines face the steepest compliance cost escalation.
County council purchasing consortia are consolidating neuroimaging and neurology monitoring procurement into multi-year managed service agreements, displacing traditional capital equipment tenders. Regional health authorities in Västra Götaland and Skåne are leading this transition. Vendors now compete on total cost of ownership metrics rather than device specifications alone.
Sweden Neurology Devices Market Segmentation
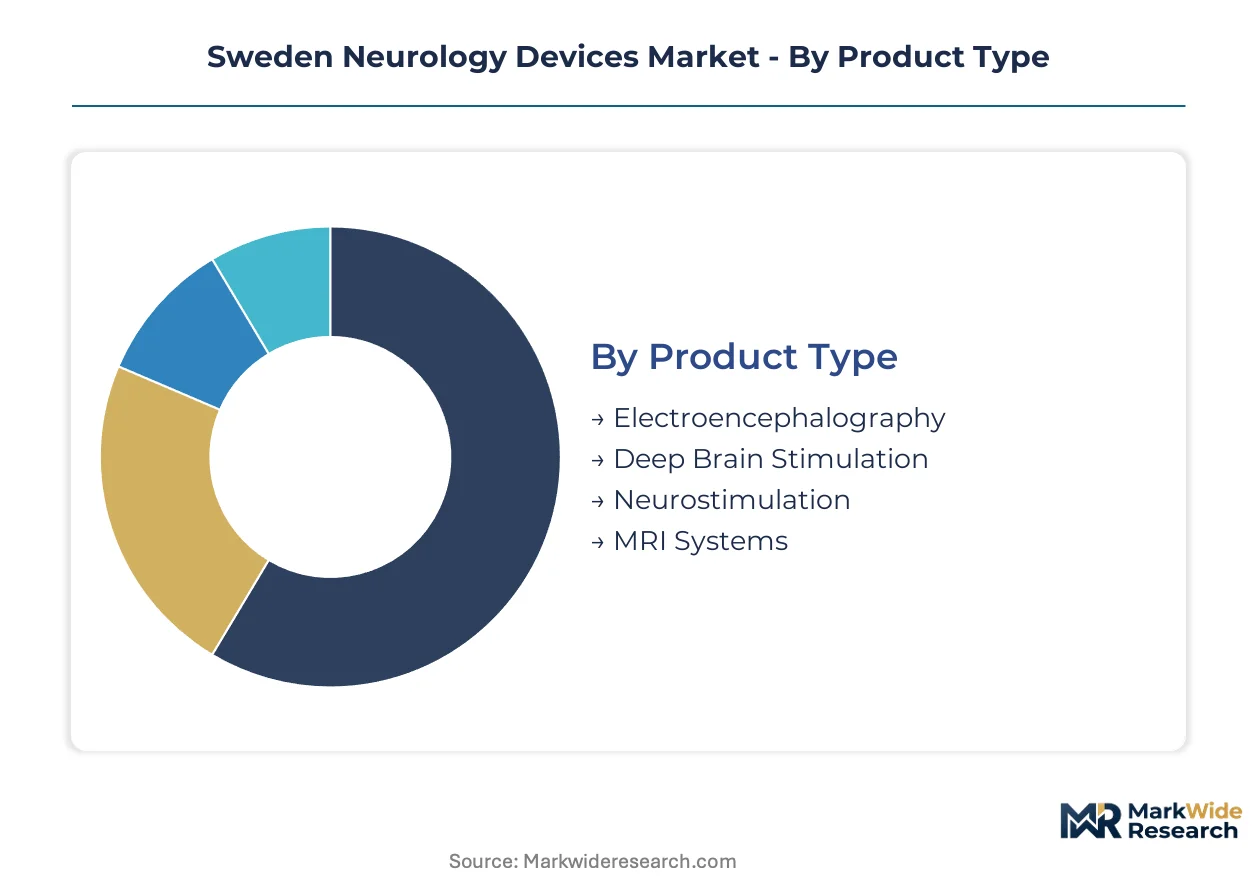
Sweden's neurology devices market fragments across four critical dimensions that determine procurement patterns and vendor access. Product type captures hardware revenue concentration, while end user and application segments reveal where clinical workflows are restructuring around connected monitoring platforms.
Product Type:
Cost tier stratification separates capital-intensive imaging and implantable systems from monitoring devices with lower entry thresholds but recurring service revenue.
- Deep Brain Stimulation:Implantable pulse generators deliver targeted electrical modulation to subcortical structures for movement disorders. Stockholm's university hospital cluster anchors demand as neurosurgical capacity expands for Parkinson's disease cohorts, with long-term service contracts creating sticky revenue streams.
- Electroencephalography:Systems capturing electrical activity at 256+ channels maintain mature volume throughput across Swedish neurology clinics. County councils outside the three major urban centers prioritize 32-64 channel configurations that balance diagnostic capability against capital constraints.
- Neurostimulation:Spinal cord and peripheral nerve stimulation devices address chronic pain refractory to pharmacological intervention. Västra Götaland regional health authority procurement is scaling faster than national averages.
- MRI Systems:Integrated MRI-neurophysiology workflows require substantial capital commitments that strain county council budgets. Philips Healthcare competes on bundled service agreements rather than hardware specifications alone.
Deep brain stimulation holds installed capacity. Wearable-connected EEG configurations are rotating up the share rankings.
End User:
Customer type determines purchasing authority complexity, from centralized hospital procurement to distributed clinic networks with fragmented decision-making.
- Hospitals:Academic medical centers in Stockholm, Gothenburg, and Malmö concentrate neurosurgical volume and advanced neuroimaging investment. Consolidated neurostimulation service contracts are reconfiguring vendor access through multi-year managed service agreements.
- Neurology Clinics:Outpatient facilities handle diagnostic workup and chronic disease monitoring for dispersed populations. Regional health authorities in Skåne are piloting remote patient monitoring protocols that expand ambulatory EEG deployment.
- Research Institutions:Karolinska Institute and Lund University drive early adoption of adaptive deep brain stimulation systems. Investigational device exemptions under Sweden's Medical Products Agency frameworks accelerate clinical validation timelines.
- Rehabilitation Centers:Post-acute facilities integrate neurostimulation and wearable monitoring for stroke recovery protocols. Occupational therapy staffing ratios constrain technology absorption outside metropolitan catchments.
Hospitals dominate capital allocation. Neurology clinics are gaining procurement autonomy as regional monitoring networks decentralize.
Technology:
Maturity gradients separate established hardware categories from software-enabled platforms where regulatory classification remains unsettled.
- Wearable Devices:Ambulatory EEG and seizure detection systems enable remote patient monitoring across Sweden's dispersed geography. Swedish regional health authorities are expanding procurement as telemedicine integration matures.
- Traditional Devices:Fixed-installation neurophysiology equipment maintains volume throughput in established clinical workflows. Legacy system integration friction slows cloud-connected platform adoption.
- Software Solutions:AI-enabled EEG interpretation tools face ambiguous software-as-medical-device pathways under Sweden's national pharmaceutical regulator. Automated diagnostic algorithms promise labor cost reduction but delayed market entry.
- Imaging Technology:MRI-neurophysiology integration requires specialized coil configurations and real-time processing architectures. County council purchasing consortia are consolidating procurement into outcome-based contracts.
Traditional devices hold installed capacity. Wearable platforms are climbing the fastest as remote monitoring protocols diffuse through county council networks.
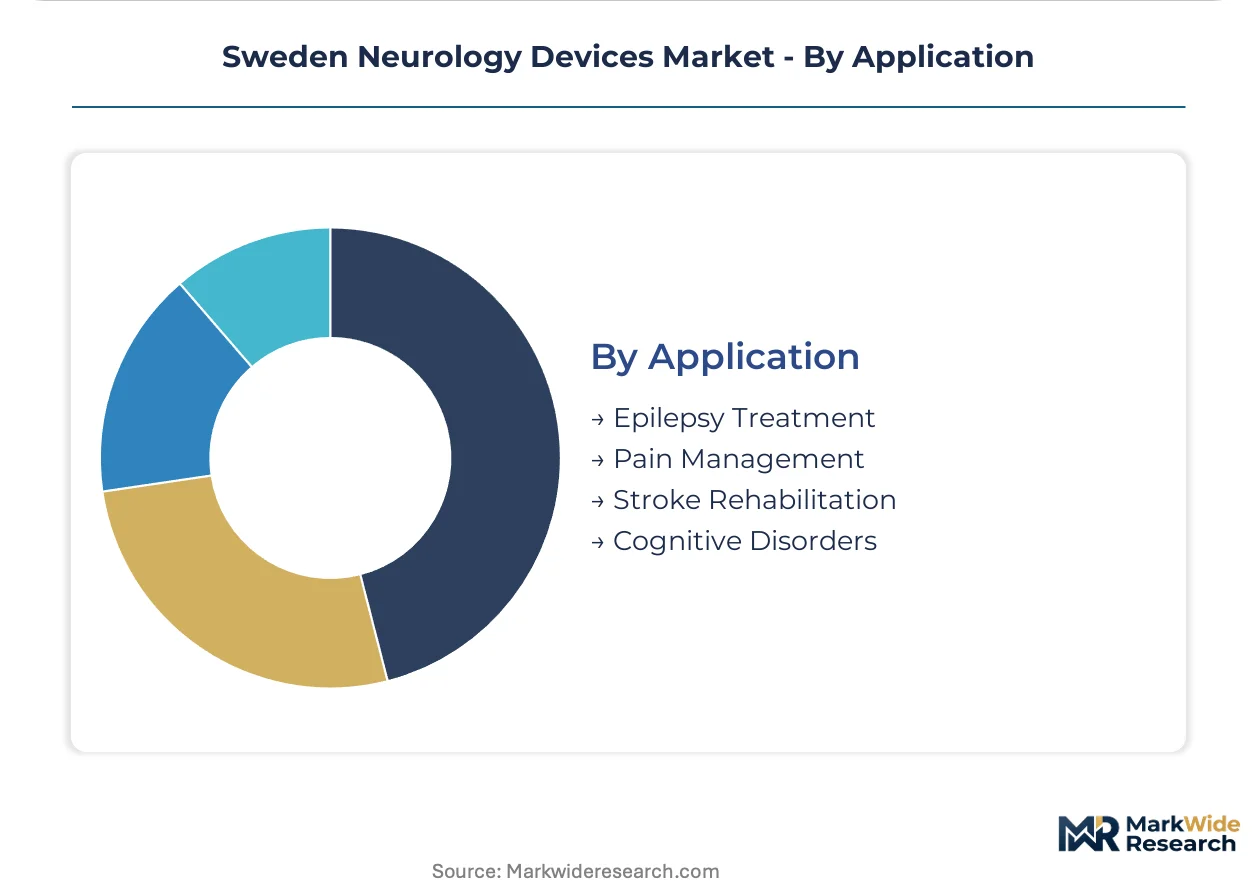
Application:
Clinical indication determines reimbursement pathway complexity and the relative priority of diagnostic versus therapeutic device categories.
- Epilepsy Treatment:Closed-loop stimulation systems and chronic ambulatory monitoring dominate device expenditure. Stockholm's university hospitals are piloting adaptive neurostimulation that modulates therapy based on real-time biomarker feedback.
- Pain Management:Spinal cord stimulation and peripheral neuromodulation address refractory chronic pain populations. Neurostimulation service contracts bundle hardware with algorithm optimization subscriptions.
- Stroke Rehabilitation:Functional electrical stimulation and wearable monitoring support motor recovery protocols. Rehabilitation center staffing constraints limit technology penetration outside metropolitan regions.
- Cognitive Disorders:EEG biomarker research and non-invasive neuromodulation target dementia and mild cognitive impairment. Research institutions anchor demand as clinical validation pathways mature.
Epilepsy treatment holds installed capacity. Pain management applications are rotating up the share rankings as outcome-based contracts expand neurostimulation access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's national healthcare reform agenda prioritizes decentralized neurology care delivery, with county councils allocating capital toward remote monitoring infrastructure across dispersed population centers. The Medical Products Agency's EU MDR enforcement creates regulatory harmonization with neighboring Nordic markets, while Stockholm's university hospital cluster anchors advanced neurosurgical capacity that radiates specialist expertise outward.
Stockholm County
Karolinska University Hospital and Danderyd Hospital concentrate Sweden's deep brain stimulation surgical volume and adaptive neurostimulation pilot programs. The county council's consolidated neurostimulation service contracts bundle hardware procurement with long-term algorithm optimization subscriptions. Södersjukhuset and St. Göran's Hospital are expanding ambulatory EEG capacity to reduce specialist consultation backlogs.
Västra Götaland Region
Sahlgrenska University Hospital in Gothenburg anchors neurosurgical services for western Sweden, with regional health authority procurement scaling spinal cord stimulation faster than national averages. The county council's purchasing consortium is consolidating neuroimaging procurement into multi-year managed service agreements. Borås and Skövde hospitals are piloting wearable seizure detection systems for dispersed rural populations.
Skåne Region
Skåne University Hospital in Lund and Malmö drives epilepsy treatment device adoption, with closed-loop stimulation systems deployed across movement disorder and epilepsy cohorts. The regional health authority is piloting remote patient monitoring protocols that expand ambulatory EEG deployment to municipal clinics. Lund University's research collaboration accelerates investigational device validation timelines.
Uppsala County
Uppsala University Hospital maintains specialized neurophysiology capacity for central Sweden, with intraoperative monitoring services supporting surgical throughput across adjacent counties. The county council prioritizes 32-64 channel EEG configurations that balance diagnostic capability against capital constraints. Akademiska Sjukhuset is integrating cloud-connected platforms with existing hospital information systems.
Sweden Neurology Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Sweden's neurology devices market, with consolidated purchasing consortia in major county councils favoring vendors offering bundled service agreements. The vendor base separates into three strategic archetypes: diversified medtech conglomerates with full neurostimulation portfolios, imaging specialists competing on integrated MRI-neurophysiology workflows, and emerging wearable monitoring platforms. M&A activity concentrates on algorithm capabilities for adaptive stimulation systems, while strategic partnerships between hardware manufacturers and cloud analytics providers reshape procurement evaluation criteria.
Among diversified medtech conglomerates, Stryker Corporation and Medtronic PLC exemplify the full-portfolio archetype, with Stryker leveraging its deep brain stimulation assets and Medtronic sustaining R&D intensity across neurostimulation platforms. Philips Healthcare occupies a distinct position competing on integrated imaging workflows rather than implantable devices. These three anchors represent divergent competitive vectors: hardware-service bundling, continuous algorithm development, and diagnostic system integration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| B. Braun SE |
| Integra LifeSciences Corporation |
| Nihon Kohden Corporation |
| Philips Healthcare |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Swiss precision component suppliers for deep brain stimulation implantable pulse generators compresses margin buffers across Swedish procurement tiers while simultaneously forcing vendors toward algorithm-subscription revenue models. This chokepoint simultaneously widens pricing spreads between CE-MDR certified premium systems and standard diagnostic configurations while reshaping inventory strategies toward consignment stocking at Stockholm's university hospital cluster.
Pricing Analysis
Certification level under EU MDR creates the primary spread between premium implantable neural devices and standard monitoring equipment. Three-tier pricing structure across premium adaptive neurostimulation, standard fixed-parameter systems, and economy diagnostic configurations dominates procurement evaluation. Cost compression in mid-tier EEG systems intensifies because county council purchasing consortia prioritize total cost of ownership metrics over hardware specifications. Neurology clinics in secondary Swedish regions exhibit highest price sensitivity, while Stockholm's academic medical centers prioritize algorithm optimization subscriptions over upfront capital expenditure.
Supply Chain Analysis
Tariff exposure between Germany and Switzerland for precision microelectronic components dominates supply chain risk assessment for Swedish neurology device vendors. Manufacturing concentrates in Germany, Switzerland, and the United States for implantable pulse generators, while sensor arrays and wearable monitoring substrates source from Taiwan and South Korea. Critical dependencies include platinum-iridium electrode alloys, biocompatible titanium housings, and application-specific integrated circuits for neural signal processing. Single-source vulnerability for EU MDR notified body certifications creates regulatory chokepoints. Distribution runs through regional health authority purchasing consortia with consolidated tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's neurology devices market rewards vendors who attach predictive analytics subscriptions to hardware procurement, with algorithm optimization contracts expanding faster than implantable pulse generator replacement cycles. Remote patient monitoring service layers now capture recurring revenue streams that exceed traditional device margin profiles.
For Market Incumbents: Pre-empt algorithm commoditization by securing exclusive data-sharing agreements with Karolinska Institute and Lund University research cohorts. Consolidate neurostimulation service contracts across Västra Götaland and Skåne regional health authorities before emerging wearable platforms achieve scale. Vertical integration into cloud analytics development protects margin structures against software-as-medical-device entrants. For New Entrants and Emerging Players: Secondary hospital networks in Uppsala County and dispersed municipal clinics in northern Sweden represent the most penetrable entry points for ambulatory EEG and seizure detection systems. White-space concentration in rehabilitation center stroke recovery protocols offers volume growth potential with lower competitive intensity than Stockholm's saturated academic market. Telemedicine integration partnerships with regional health authorities provide the fastest path to procurement qualification. For Investors and Strategic Acquirers: Adaptive stimulation algorithm developers with validated clinical datasets in movement disorder cohorts offer the strongest acquisition target profile for long-term viability across the 5-10 year horizon. Software-enabled closed-loop systems command premium valuation multiples compared to hardware-centric vendors. The signal to watch is EU MDR post-market surveillance compliance cost escalation forcing consolidation among sub-scale implantable device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance under Sweden's Medical Products Agency secures Nordic market access against regulatory fragmentation. |
| Hospital System Partnership | Consolidated neurostimulation service contracts with Stockholm County Council lock out competing vendors through multi-year agreements. |
| Software Companion Development | Predictive analytics subscriptions for adaptive deep brain stimulation shift revenue from hardware replacement to continuous optimization. |
| Reimbursement Strategy | Outcome-based procurement alignment with Swedish regional health authorities accelerates capital allocation toward connected monitoring platforms. |
| Regulatory Approval Pathway | Investigational device exemptions through Lund University research collaborations compress clinical validation timelines for novel neurostimulation architectures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU MDR regulatory filings, Swedish county council procurement databases, and hospital capital expenditure records. Interviews with neurosurgeons at Karolinska University Hospital, biomedical engineers at Sahlgrenska University Hospital, regional health authority procurement directors, and GPO contracts managers informed demand-side validation. Secondary sources include Medical Products Agency device registrations, Swedish Work Environment Authority occupational exposure standards, and EU clinical trial registries. Bottom-up installation base modeling triangulates against top-down healthcare expenditure flows.
Forecast inputs span product type segmentation across deep brain stimulation, electroencephalography, neurostimulation, and MRI systems; end user categories from academic medical centers to rehabilitation facilities; and technology tiers separating wearable platforms from traditional fixed-installation equipment. CAGRs derive from regression analysis against historical procurement patterns and projected regional health authority budget allocations. Industry-specific inputs include neurosurgical capacity expansion timelines at Stockholm's university hospital cluster and EU MDR transition cost burdens on manufacturer pricing power.
Macroeconomic conditions sit as an overlay; deviation in Swedish krona exchange rates against euro-denominated component sourcing or shifts in county council healthcare budget prioritization would shift the trajectory. Forecasts reflect assumptions around EU MDR enforcement continuity and telemedicine reimbursement policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Acute Repetitive Seizures Market
Neurology
Chile Neurology Devices Market
Neurology
Optic Neuropathy Management Market
Neurology
Canada Neurology Devices Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Mild Cognitive Impairment Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Hepatic Encephalopathy Market
Neurology
Global Vertigo Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Australia Neurology Devices Market
Neurology
Pediatric Neurology Device Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Neurology Software Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Ulnar Nerve Treatment Market