
 Biologic Injectors Market | 2026-2036
Biologic Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Biologic Injectors Market Analytics
North American manufacturing expansion is reshaping supply availability for advanced biologic injectors. Becton, Dickinson and Company leverages its vertically controlled supply chain to dominate disposable pen injector production. SHL Medical anchors large-format autoinjector assembly through Swiss-engineered precision manufacturing. Ypsomed specializes in connected device platforms that compete on data integration rather than unit cost alone.
Biologic injectors are drug delivery devices engineered to administer large-molecule therapies—monoclonal antibodies, fusion proteins, and peptide hormones—through subcutaneous or intramuscular routes at controlled volumes, viscosities, and injection depths. These devices incorporate spring-driven or electromechanical mechanisms to ensure reproducible dosing outside clinical settings. Wearable injectors capture expanding margin pools as biologics shift toward higher-volume, less frequent administration regimens. Electronic injectors lead technology adoption where dose tracking and compliance monitoring command premium positioning. Homecare end users represent the fastest-growing demand channel as payer structures redirect chronic disease management from hospitals to patient-controlled environments.
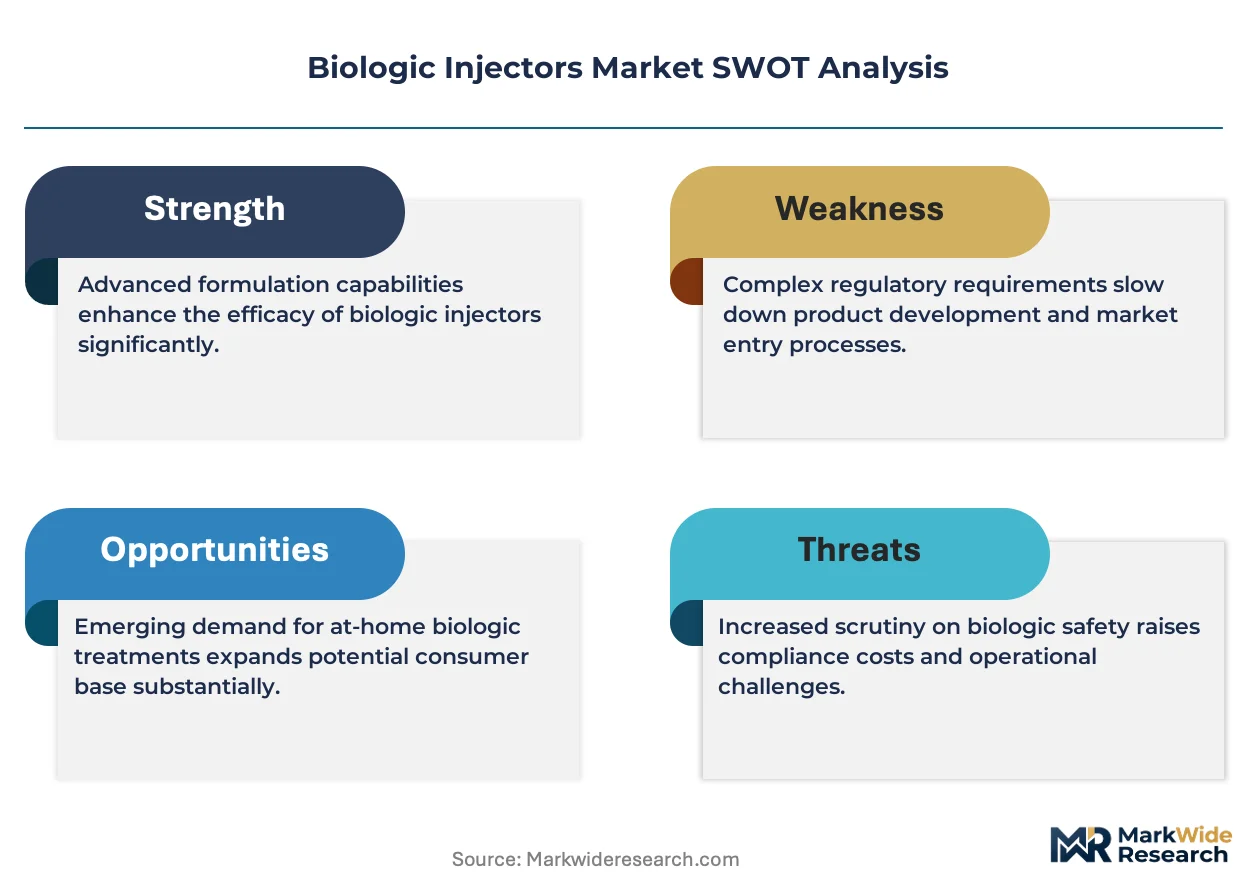
FDA combination product regulations and EMA MDR requirements enforce stringent device-drug compatibility testing that elevates barriers to market entry. ISO 11608 standards for needle-based injection systems govern dimensional tolerances, dose accuracy, and sterility assurance across manufacturing batches. Stakeholders must monitor evolving reimbursement codes for smart injector data services as payers weigh clinical outcomes against hardware subsidies.
Market Dynamics
Biologic injectors face intensifying pressure from FDA combination product regulations that mandate device-drug compatibility testing before market authorization, compressing development timelines while elevating capital requirements for manufacturers seeking to serve chronic disease patients outside clinical settings.
Growth Catalysts
- Homecare Migration:Payer structures in the United States, Germany, and Japan redirect reimbursement toward patient-controlled administration environments, expanding addressable volume for self-injection platforms.
- Wearable Form Factor Expansion:Higher-volume biologic therapies requiring less frequent dosing drive demand for large-format wearable injectors that automate extended subcutaneous delivery.
- ISO 11608 Harmonization:Standardized dimensional tolerances and sterility protocols reduce regulatory friction across manufacturing batches, accelerating multi-market product launches.
Market Restraints
- Spring Steel and Medical-Grade Polymer Volatility:Input cost fluctuations for precision-machined components compress margins on disposable pen injector production.
- Swiss-German Supply Concentration:Precision assembly capabilities cluster in Alpine manufacturing corridors, creating single-source vulnerability for autoinjector mechanical subsystems.
- Viscosity Ceiling:Current spring-driven mechanisms face hard limits at 50+ centipoise formulations, excluding next-generation high-concentration monoclonal antibodies from existing device platforms.
Strategic Opportunities
- Connected Device Data Monetization:Bluetooth-enabled adherence tracking creates recurring revenue streams through payer-subsidized compliance monitoring services.
- Japanese Elderly Care Integration:METI incentives for aging-in-place technologies position electronic injectors with caregiver alert systems for rapid penetration.
- EMA MDR Quality Benchmark Elevation:Stricter device-drug integration standards disadvantage non-compliant competitors, opening share capture for certified manufacturers.
Industry Challenges
- Combination Product Regulatory Skill Scarcity:FDA 21 CFR Part 4 compliance expertise concentrates at a handful of specialized consultancies, inflating submission preparation costs.
- Electromechanical Firmware Validation Burden:IEC 62304 medical device software lifecycle documentation extends development timelines for electronic injector platforms.
- Legacy Hospital Contract Integration:Established purchasing agreements with infusion center networks resist disintermediation by direct-to-patient delivery models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologic Injectors Market |
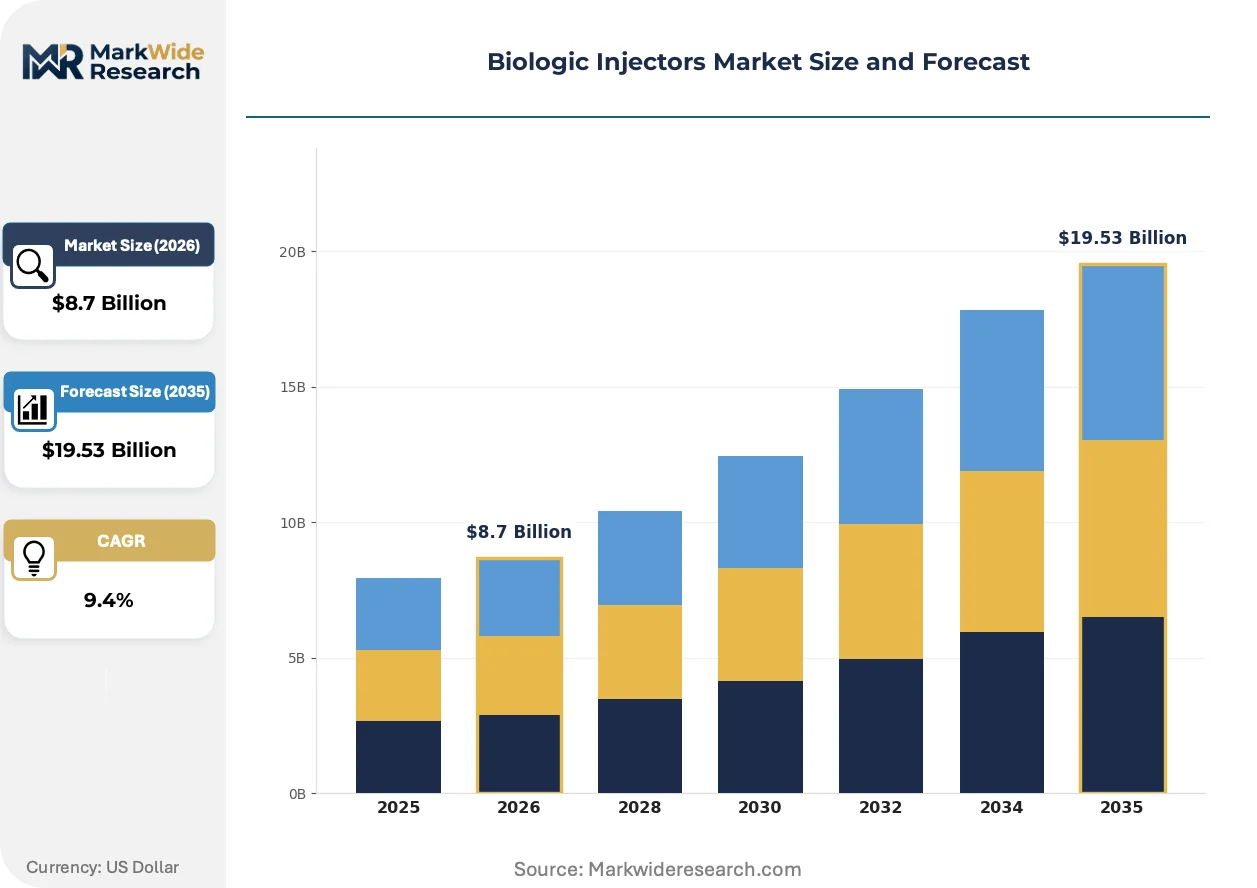
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pen Injectors, Syringe Injectors, Wearable Injectors, Implantable Injectors End User: Hospitals, Clinics, Homecare, Research Laboratories Application: Oncology, Rheumatoid Arthritis, Diabetes, Multiple Sclerosis Technology: Autoinjectors, Electronic Injectors, Smart Injectors, Manual Injectors |
| Companies Covered | Becton, Dickinson and Company, SHL Medical, Ypsomed, AbbVie, Novo Nordisk, Eli Lilly and Company, Amgen, Roche Holding, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologic Injectors Market Evolving Landscape
Device architectures are fragmenting along functional lines as manufacturers bet on divergent technology stacks—spring simplicity versus electronic intelligence—while regulatory bodies on both sides of the Atlantic tighten integration standards.
Electromechanical injection systems is hybridizing with capacitive touch interfaces and real-time dose verification sensors. Rheumatology and endocrinology practices in the United States are piloting these platforms for patient cohorts requiring complex titration regimens. The convergence is compressing differentiation timelines for purely mechanical competitors while opening premium positioning for data-integrated offerings.
EMA Medical Device Regulation enforcement is intensifying post-market surveillance obligations for combination products, mandating annual safety update reports and expanded clinical follow-up. Swiss and German notified bodies are extending review cycles by four to six months for devices incorporating novel materials. Manufacturers are responding by front-loading biocompatibility testing and locking supply agreements with ISO 13485-certified component vendors.
Hospital procurement departments are unbundling device selection from pharmaceutical contracting, creating direct purchasing relationships with injector specialists. This separation is most advanced in German statutory health insurance networks and select United States integrated delivery networks. The shift exposes incumbent device divisions of pharmaceutical conglomerates to competitive displacement by independent platform developers.
Biologic Injectors Market Segmentation
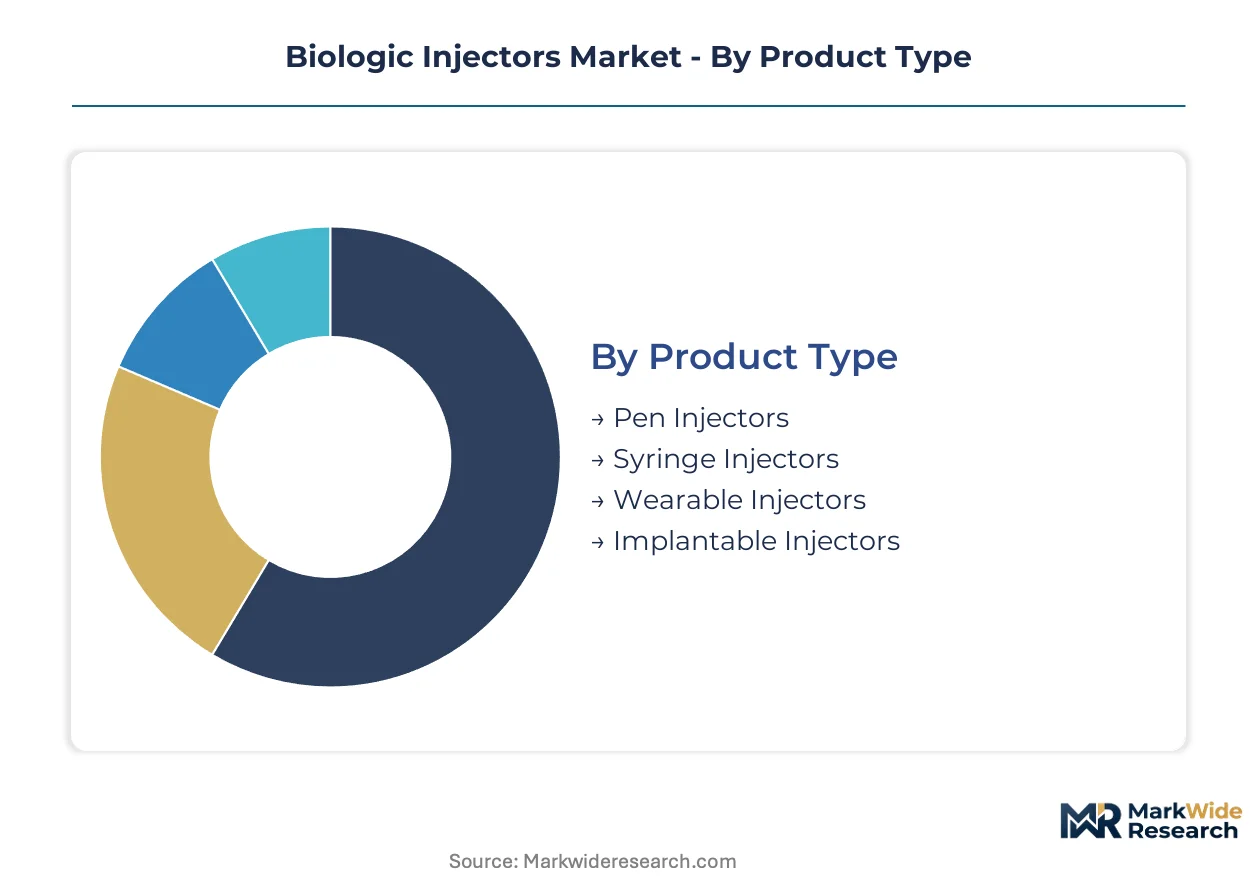
Device architecture and administration setting determine reimbursement pathways, regulatory classification, and manufacturing scale for biologic injectors. Each segmentation dimension reveals distinct margin structures, technology requirements, and competitive dynamics that shape platform development priorities.
Product Type:
Form factor selection hinges on dose volume, viscosity tolerance, and patient dexterity requirements across therapeutic categories.
- Pen Injectors:Spring-driven disposable platforms dominate insulin and growth hormone delivery with standardized 3mL cartridge compatibility. United States homecare demand concentrates here as payer formularies favor unit-dose simplicity over reusable complexity.
- Wearable Injectors:Electromechanical large-volume devices automate extended subcutaneous infusion for monoclonal antibody regimens exceeding 10mL. Rheumatology practices in Germany and Japan pilot these for patient cohorts requiring less frequent clinic visits.
- Syringe Injectors:Conventional glass-barrel systems persist in hospital settings where healthcare professionals manage dose preparation.
- Implantable Injectors:Subdermal reservoir systems serve long-acting peptide therapies requiring month-scale release kinetics.
Established volume favors pen injectors; emerging adoption favors wearable injectors.
End User:
Site of administration dictates device sophistication, training burden, and connectivity requirements.
- Homecare:Patient-controlled environments demand intuitive interfaces, error-proofing mechanisms, and Bluetooth adherence tracking. Japanese METI aging-in-place incentives accelerate electronic injector deployment with caregiver alert integration.
- Hospitals:Acute care settings prioritize rapid volume delivery and multi-dose flexibility for oncology infusion protocols.
- Clinics:Outpatient rheumatology and endocrinology practices balance patient throughput against reimbursement for self-injection training.
- Research Laboratories:Preclinical and Phase I studies require dose precision and data capture for regulatory submission packages.
Reimbursement gravity centers on homecare; clinical trial complexity sustains research laboratory demand.
Application:
Therapeutic area determines viscosity range, injection frequency, and competitive generic pressure on device economics.
- Diabetes:High-volume insulin analog delivery drives pen injector commoditization while continuous glucose monitor integration creates premium tier differentiation.
- Oncology:Cytotoxic biologics require protective needle shields and precise dosing for weight-based regimens in hospital settings.
- Rheumatoid Arthritis:Anti-TNF and IL-6 inhibitor self-administration concentrates demand in United States and German homecare channels.
- Multiple Sclerosis:Interferon and monoclonal antibody platforms favor autoinjector simplicity for patient populations with dexterity impairment.
Diabetes commands unit scale; oncology sustains price premiums through safety engineering requirements.
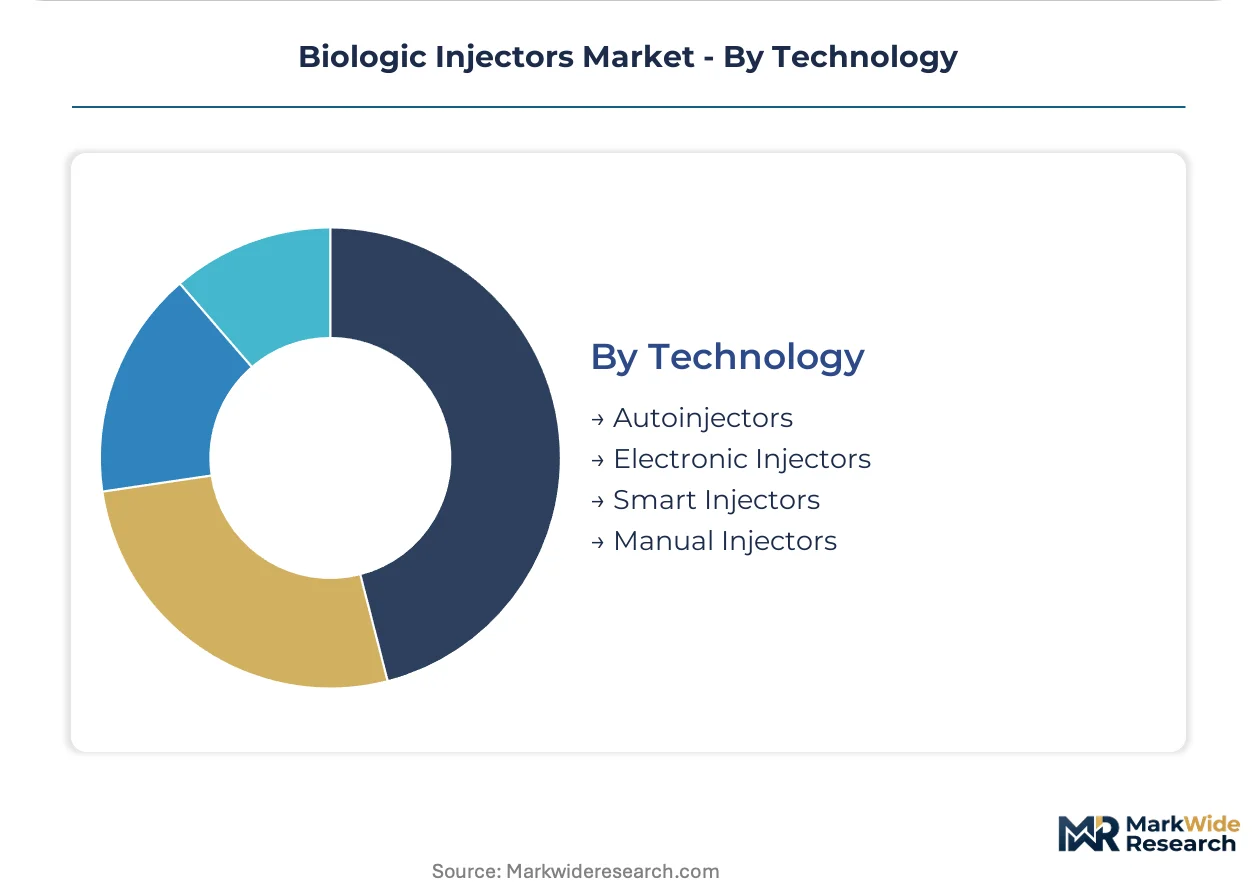
Technology:
Mechanism selection divides manufacturers between spring simplicity and electronic intelligence with divergent R&D investment profiles.
- Autoinjectors:Spring-driven platforms with automatic needle insertion and fixed dosing dominate disposable pen economics. ISO 11608 dimensional standardization enables multi-source component procurement.
- Smart Injectors:Bluetooth-enabled adherence tracking and cloud-connected dose verification attract payer subsidies for compliance-critical therapies. FDA 21 CFR Part 4 combination product scrutiny elevates firmware validation costs.
- Electronic Injectors:Motor-driven precision dosing serves complex titration regimens in rheumatology and endocrinology practices.
- Manual Injectors:Conventional syringe-and-needle systems persist where cost minimization overrides convenience features.
Autoinjectors anchor current volume; smart injectors capture expanding margin pools through data monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States patients favor disposable pen simplicity for home self-administration. German and Japanese markets prioritize electromechanical precision with integrated adherence monitoring.
United States
Medicare reimbursement codes for self-injection training accelerate homecare migration away from infusion centers. FDA 21 CFR Part 4 combination product scrutiny elevates compliance costs for new market entrants. Massachusetts and California clusters concentrate contract manufacturing for biologic-device integration.
Germany
Statutory health insurance unbundling of device procurement from pharmaceutical contracting creates direct purchasing channels. EMA MDR post-market surveillance obligations extend review cycles for novel materials. Baden-Württemberg precision engineering corridors anchor autoinjector mechanical subsystem production.
Japan
METI aging-in-place incentives subsidize electronic injectors with caregiver alert integration for elderly patient cohorts. PMDA quality benchmarks for combination products align with EMA standards. Kanto region medical device manufacturing concentrates connected platform assembly.
Switzerland
Swissmedic oversight of high-risk combination products maintains stringent device-drug compatibility protocols. ISO 13485-certified component vendor networks reduce supply friction for precision assembly. Zurich and Basel corridors specialize in large-format wearable injector engineering.
United Kingdom
NHS England reimbursement shifts favor patient-controlled administration for chronic disease management. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards. Southeast England medical technology clusters develop smart injector firmware platforms.
Biologic Injectors Market Competitive Landscape
Capability concentration sits with precision manufacturing specialists; scale advantage sits with vertically integrated healthcare conglomerates. The vendor base separates into three tiers: pharmaceutical-owned device divisions, independent platform developers, and contract manufacturing specialists. Dominant competitive moves include backward integration into component supply and strategic partnerships for connected device data services.
Among independent platform developers, Ypsomed and SHL Medical occupy distinct positioning archetypes. Ypsomed exemplifies the connected-device tier where data integration commands premium positioning beyond unit economics. SHL Medical anchors large-format precision manufacturing through Swiss-engineered assembly capabilities. Becton, Dickinson and Company represents the scale-driven conglomerate tier with vertically controlled supply chain dominance in disposable pen production.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| SHL Medical |
| Ypsomed |
| AbbVie |
| Novo Nordisk |
| Eli Lilly and Company |
| Amgen |
| Roche Holding |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg precision engineering corridors concentrate autoinjector mechanical subsystem production, translating Swiss-German manufacturing scarcity into premium pricing power for ISO 13485-certified platforms serving FDA and EMA combination product pathways.
Pricing Analysis
Long-term offtake contracts dominate procurement between pharmaceutical conglomerates and tier-one device manufacturers, while spot purchasing persists for clinical trial supply. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled adherence platforms from spring-driven disposables and manual syringe systems. Cost compression in disposable pen injectors is intensifying because spring steel and medical-grade polymer volatility compresses margins. Hospital procurement departments exhibit highest price sensitivity; homecare payers in Germany and Japan demonstrate lowest sensitivity where reimbursement frameworks favor data-integrated platforms.
Supply Chain Analysis
Swiss contract manufacturers including SHL Medical and Ypsomed anchor large-format wearable injector assembly, while Becton, Dickinson and Company controls North American disposable pen production. Component sourcing draws from Switzerland, Germany, and the United States for precision-machined spring mechanisms and ISO 11608-compliant polymer housings. Single-source vulnerability concentrates in Alpine manufacturing corridors for autoinjector mechanical subsystems. Distribution runs through pharmaceutical-owned device divisions and direct hospital procurement channels unbundled from drug contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral biologic formulations and infusion center networks present substitution threats that incumbent device manufacturers must navigate through platform stickiness and data integration lock-in.
For Market Incumbents: Pre-empt disintermediation by infusion center networks through backward integration into connected device data services that capture payer subsidies for adherence monitoring. Lock supply agreements with ISO 13485-certified polymer and spring steel vendors to defend against input cost volatility. Prioritize firmware validation investments that accelerate FDA 21 CFR Part 4 submissions ahead of EMA MDR enforcement tightening.
For New Entrants and Emerging Players: Japanese elderly care integration represents underpenetrated white space where METI aging-in-place incentives subsidize electronic injectors with caregiver alert functionality. Target United States integrated delivery networks that have unbundled device procurement from pharmaceutical contracting. Enter through software companion development partnerships that bypass capital-intensive precision manufacturing barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected device platforms with Bluetooth-enabled adherence tracking and cloud-connected dose verification. Viability over the projection horizon favors manufacturers with locked pharmaceutical partnerships and ISO 11608 certification breadth. Monitor FDA combination product approval velocity as inflection indicator for platform adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected Device Data Monetization | Bluetooth adherence tracking creates payer-subsidized recurring revenue streams for compliance-critical therapies. |
| EMA MDR Certification Investment | Swissmedic and German notified body alignment accelerates multi-market launches through harmonized quality benchmarks. |
| Hospital Procurement Unbundling | German statutory health insurance separation of device and drug contracting exposes incumbent divisions to competitive displacement. |
| Japanese Elderly Care Integration | METI incentives for aging-in-place technologies position electronic injectors with caregiver alerts for rapid penetration. |
| Spring-Driven Mechanism R&D | Viscosity ceiling extension beyond 50 centipoise unlocks next-generation high-concentration monoclonal antibody compatibility. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads, hospital procurement managers, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, EMA combination product submissions, ISO 11608 documentation, and CMS Medicare reimbursement code databases anchors the qualitative findings. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Calibration against historical approval timelines and commercial launch trajectories informs the projection framework across device architecture, end-user setting, therapeutic application, and mechanism technology dimensions. CAGRs derive from segment-level growth rate synthesis weighted by reimbursement pathway maturity. Forecast inputs incorporate FDA 21 CFR Part 4 submission velocity and EMA MDR notified body review cycle extensions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oral biologic formulation developers or infusion center network consolidators would shift outcomes. Quarterly review of FDA combination product approval backlogs and German statutory health insurance procurement unbundling progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Glass Syringe Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Ventilation Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Anti-Snore Device Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Pectus Bar Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
US Contact Lenses Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
UHD Surgical Display Market