
 Arterial Cannula Market | 2026-2036
Arterial Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Arterial Cannula Market Intelligence
A shift from single-source polymer supply toward multi-source resin qualification is pivoting procurement strategy across arterial cannula manufacturing. Getinge AB leverages backward integration into silicone compounding to secure batch consistency for perfusion-grade tubing. Terumo Corporation anchors its position through captive extrusion facilities in Japan that sustain JIS-compliant cleanroom output. Edwards Lifesciences differentiates via polymer science investments targeting thromboresistant surface chemistries.
An arterial cannula is a sterile, biocompatible tube inserted into an artery to establish vascular access for cardiopulmonary bypass, blood sampling, or hemodynamic monitoring, typically manufactured from medical-grade silicone or polyurethane via precision extrusion and tip-forming processes. Single lumen configurations dominate procedural volume in routine coronary artery bypass grafting, while double lumen designs capture expanding share in complex ECMO circuits where simultaneous infusion and pressure monitoring streamline catheter management. Pediatric arterial cannulas represent a concentrated margin pool due to dimensional tolerance requirements and limited supplier bases capable of sub-6 French fabrication.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments govern market access, with both agencies intensifying scrutiny of particulate release and endotoxin thresholds in blood-contacting devices. ISO 10993 biocompatibility testing and REACH-compliant plasticizer documentation now function as baseline qualifiers for hospital procurement committees evaluating vendor qualification. Stakeholders must monitor evolving EPA and ECHA restrictions on phthalate-based PVC additives, as material substitution timelines will reshape cost structures and supplier competitiveness across the arterial cannula value chain.
Market Dynamics
Multi-source resin qualification is restructuring procurement economics across arterial cannula manufacturing as single-source polymer dependencies expose supply vulnerabilities. Manufacturers now face simultaneous pressure from EMA MDR conformity assessments and EPA phthalate restrictions, forcing material substitution timelines that compress margin structures.
Growth Catalysts
- ECMO Circuit Expansion:Extracorporeal membrane oxygenation programs in cardiac centers are pulling double lumen configurations into standard protocols for simultaneous infusion and pressure monitoring.
- FDA 510(k) Pathway Clarity:Streamlined blood-contacting device clearances are accelerating time-to-market for thromboresistant surface chemistries.
- Pediatric Subspecialization:Concentrated demand from neonatal intensive care units for sub-6 French fabrication is creating premium positioning opportunities for qualified suppliers.
Market Restraints
- Silicone Feedstock Concentration:Medical-grade silicone compounding capacity clusters in East Asian suppliers, exposing batch consistency risks during geopolitical friction.
- REACH Phthalate Restrictions:ECHA documentation requirements for plasticizer alternatives are extending qualification timelines and raising formulation costs.
- Cleanroom Capital Intensity:JIS-compliant extrusion facilities require sustained capex commitments that deter mid-tier entrants from scaling perfusion-grade output.
Strategic Opportunities
- India Cardiac Center Buildout:CDSCO regulatory harmonization with ISO 10993 standards is opening procurement pathways for international suppliers in underpenetrated tertiary care networks.
- Surface Chemistry Convergence:Integration of heparin-bonded coatings with nanostructured topography is creating next-generation thromboresistance without systemic anticoagulant burden.
- Direct Hospital Contracting:Bypassing distributor markups through GPO-negotiated direct agreements is capturing share in United States integrated delivery networks.
Industry Challenges
- Polymer Science Talent Scarcity:Blood-contacting material specialists command premium compensation, constraining R&D velocity at emerging manufacturers.
- ISO 10993 Timeline Compression:Biocompatibility testing bottlenecks at certified laboratories are delaying product launches amid intensifying FDA scrutiny of endotoxin thresholds.
- Legacy Equipment Integration:New cannula designs must maintain compatibility with established cardiopulmonary bypass consoles, limiting geometric innovation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arterial Cannula Market |
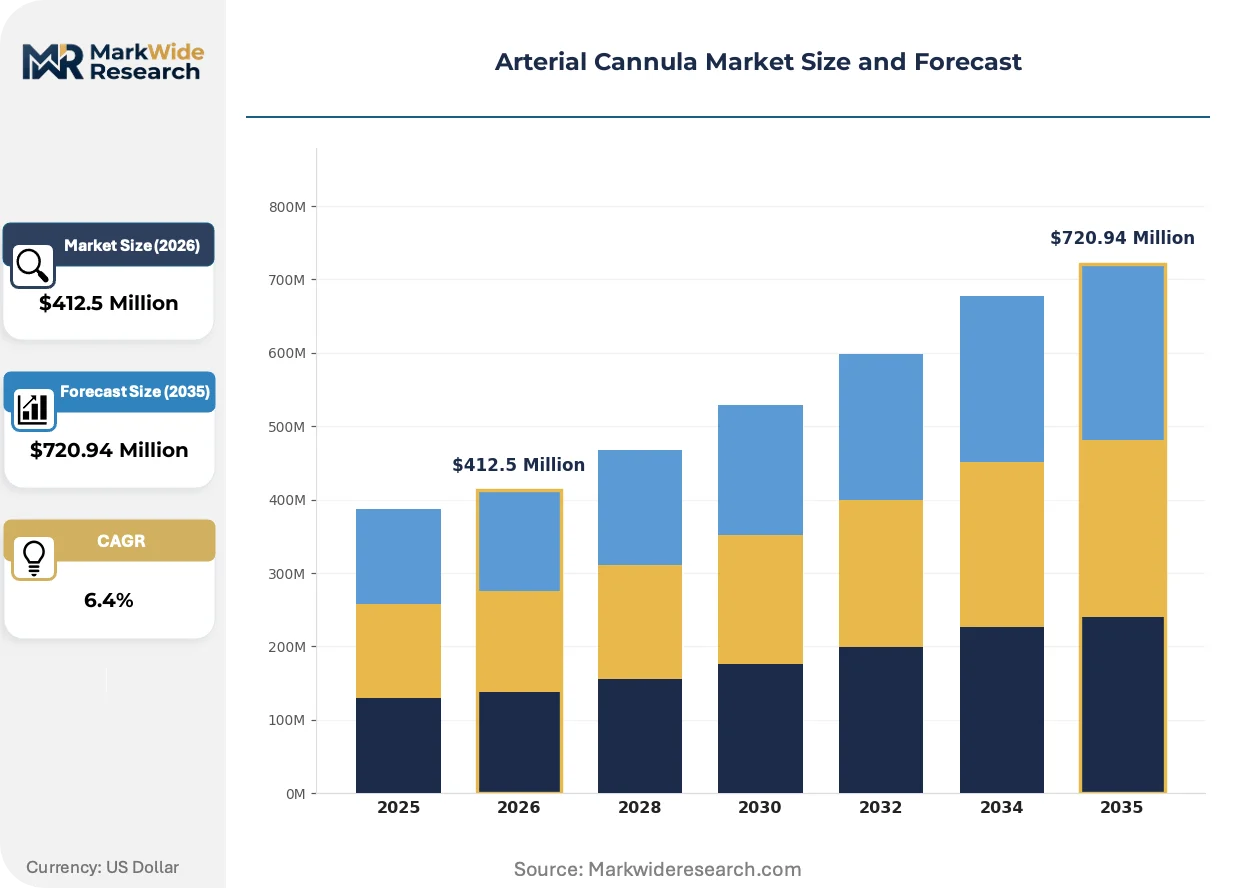
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lumen, Double Lumen, Pediatric, Specialty Application: Cardiovascular Surgery, Blood Sampling, Hemodynamic Monitoring, Extracorporeal Membrane Oxygenation End User: Hospitals, Surgical Centers, Academic Research Institutions, Home Healthcare Material: Silicone, Polyurethane, PVC, Others |
| Companies Covered | Getinge AB, Terumo Corporation, Medtronic, Fresenius Medical Care, Nipro Corp., Edwards Lifesciences, BD, Andocor, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arterial Cannula Market Strategic Shifts & Innovations
Material science advances and procurement model evolution are converging to redefine competitive positioning in arterial cannula supply. Three developments are compressing traditional differentiation mechanisms while opening new value capture vectors.
Antithrombogenic surface coatings derived from zwitterionic polymer brushes are electrifying clinical preference formation in high-risk coagulopathy patients. Academic medical centers in Germany and Japan are prioritizing these chemistries in ECMO protocols despite unit cost premiums. The technology is electrifying procurement committee criteria, forcing commodity suppliers toward accelerated R&D partnerships or margin erosion.
EMA Medical Device Regulation (MDR) post-market surveillance requirements are mandating systematic particulate release tracking across sterilization cycles. Manufacturers must now maintain validated aseptic production documentation spanning batch genealogy to point-of-use. Pediatric arterial cannula suppliers face disproportionate compliance burdens due to dimensional tolerance sensitivity and limited production run sizes.
Consolidated procurement through integrated delivery networks is compressing vendor rosters to three qualified suppliers per product category. United States hospital systems are unbundling after-sales service from device pricing, creating transparent cost benchmarking. This behavioral shift is most visible in cardiovascular surgery programs where GPO-negotiated contracts now specify minimum service response thresholds independent of hardware margins.
Arterial Cannula Market Segmentation
Arterial cannula procurement committees evaluate segments through divergent lenses—clinical efficacy for surgeons, total cost of ownership for supply chain managers, and biocompatibility documentation for regulatory affairs. Understanding how these decision criteria fragment across product, application, and material dimensions illuminates where margin concentrates and where commodification threatens.
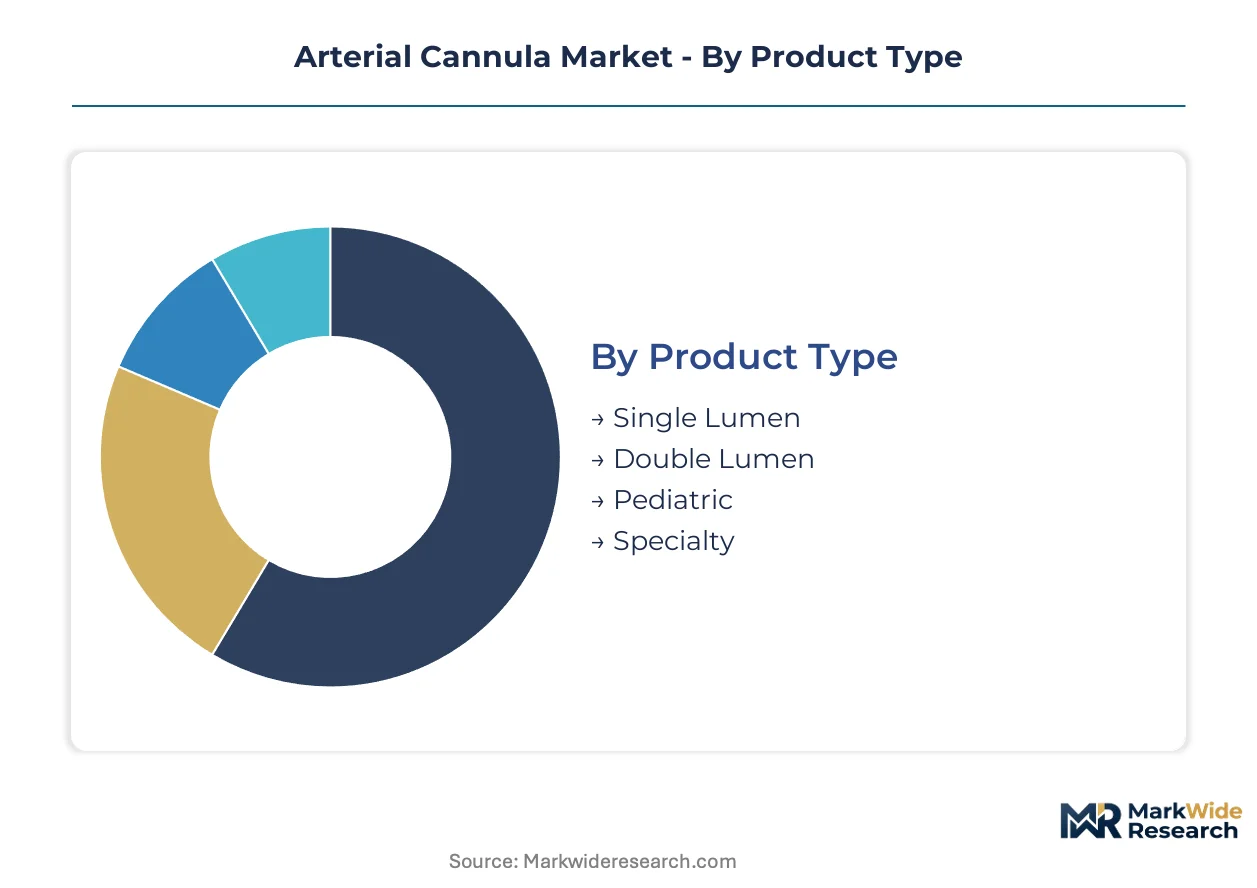
Product Type:
Surgeons select lumen configuration based on procedural complexity and vascular access site characteristics, with dimensional tolerance requirements escalating sharply for neonatal populations.
- Single Lumen:Manufactured via precision extrusion of medical-grade silicone or polyurethane, these devices dominate routine coronary artery bypass grafting volumes. United States hospital systems standardize on single lumen formats for cost efficiency in high-throughput cardiac centers.
- Double Lumen:Simultaneous infusion and pressure monitoring capabilities position these configurations as essential for ECMO circuit standardization. German academic medical centers are pulling double lumen designs into protocol-driven procurement specifications despite unit cost premiums.
- Pediatric:Sub-6 French fabrication demands specialized cleanroom infrastructure and limited supplier bases.
- Specialty:Custom geometries for minimally invasive access routes serve niche thoracic surgery applications.
Single lumen leads on scale; double lumen leads on momentum.
Application:
Procedure reimbursement codes and clinical outcome metrics determine which applications absorb premium-priced surface-modified devices versus commodity alternatives.
- Cardiovascular Surgery:Cardiopulmonary bypass procedures consume the highest cannula volumes per case. Japan's dense cardiac center network sustains procedural density that amortizes specialized inventory investments.
- Extracorporeal Membrane Oxygenation:ECMO program expansion in tertiary care networks is accelerating demand for thromboresistant surface chemistries. United States integrated delivery networks specify heparin-bonded coatings in high-risk coagulopathy protocols.
- Blood Sampling:Arterial line maintenance for intermittent monitoring serves intensive care unit populations.
- Hemodynamic Monitoring:Continuous pressure transduction requirements shape catheter stiffness and tip geometry specifications.
Cardiovascular surgery anchors volume concentration; ECMO commands the steepest expansion trajectory.
End User:
Capital equipment integration requirements and sterilization workflow compatibility segment purchasing authority across institutional types.
- Hospitals:Full-service cardiac centers with perfusion departments maintain captive inventory of multiple lumen configurations. FDA 510(k) clearance documentation and ISO 10993 biocompatibility certificates function as baseline procurement qualifiers.
- Surgical Centers:Ambulatory settings concentrate on single lumen formats for diagnostic catheterization procedures.
- Academic Research Institutions:Protocol-driven purchasing for clinical trials demands batch traceability and particulate release documentation.
- Home Healthcare:Emerging ECMO discharge programs in Germany and Japan are testing remote monitoring compatibility.
Hospitals dominate absolute consumption; home healthcare exhibits the most rapid emergence from negligible base.
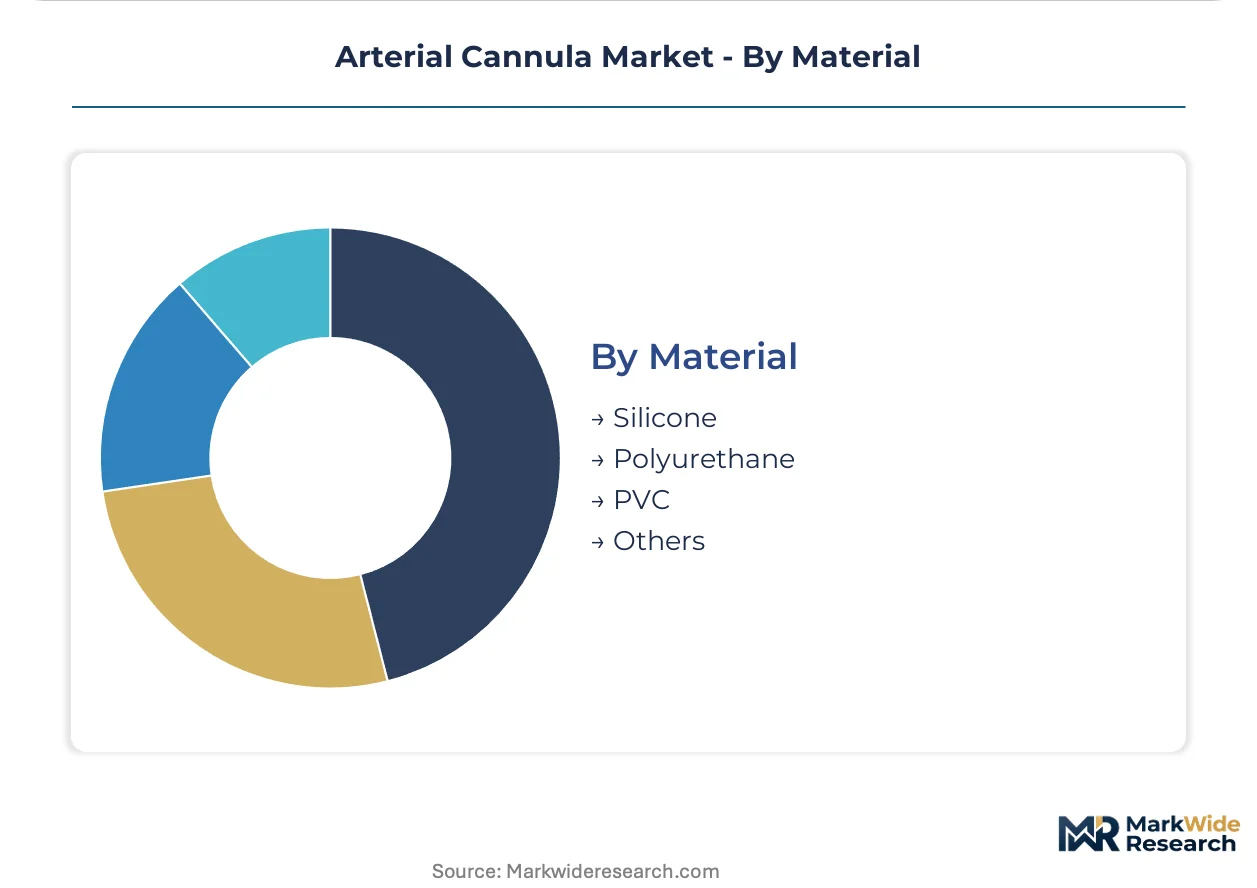
Material:
Polymer selection balances thrombogenicity profiles against extrusion processability and regulatory documentation burdens.
- Silicone:Perfusion-grade silicone compounding delivers superior elasticity and biocompatibility for extended dwell times. East Asian supplier concentration exposes batch consistency risks that Getinge AB addresses through backward integration.
- Polyurethane:Higher tensile strength enables thinner wall construction and improved flow dynamics. Terumo Corporation's captive extrusion facilities in Japan sustain JIS-compliant cleanroom output for polyurethane-intensive product lines.
- PVC:REACH phthalate restrictions are forcing formulation substitutions that compress margin structures.
- Others:Experimental polymer blends and surface-modified substrates serve research applications.
Silicone maintains volume leadership; polyurethane gains share fastest in high-performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting arterial cannula manufacturing investment toward jurisdictions with streamlined blood-contacting device pathways. Cost-of-compliance gaps between FDA 510(k) and EMA MDR frameworks are accelerating facility qualification decisions in Asia-Pacific manufacturing clusters.
United States
Integrated delivery networks in Texas and Florida are consolidating perfusion supply contracts through GPO-negotiated direct agreements. FDA 510(k) clearance timelines for thromboresistant surface chemistries are compressing time-to-market for qualified submitters. The Cleveland Clinic and Mayo Clinic cardiac centers in Ohio and Minnesota are driving protocol standardization that ripples through regional hospital procurement committees.
Germany
Academic medical centers in Berlin and Munich are mandating heparin-bonded coatings in ECMO protocols despite unit cost premiums. EMA MDR post-market surveillance requirements are forcing systematic particulate release documentation across sterilization cycles. The Baden-Württemberg medical technology corridor around Stuttgart hosts concentrated cleanroom extrusion capacity serving perfusion-grade tubing demand.
Japan
Tokyo and Osaka cardiac center density sustains procedural volume that amortizes specialized arterial cannula inventory investments. PMDA harmonization with ISO 10993 biocompatibility standards is streamlining market access for domestic and international suppliers. Terumo Corporation's captive extrusion facilities in the Kanto region maintain JIS-compliant cleanroom output for polyurethane-intensive product lines.
India
CDSCO regulatory harmonization with ISO standards is opening procurement pathways for international suppliers in underpenetrated tertiary care networks. Maharashtra and Karnataka are witnessing cardiac center buildout in Mumbai and Bangalore that expands addressable demand for single lumen configurations. Domestic manufacturers are qualifying multi-source resin supply chains to reduce import dependency for medical-grade silicone.
China
NMPA medical device registration reforms are accelerating review timelines for blood-contacting devices with established biocompatibility dossiers. The Yangtze River Delta manufacturing cluster around Shanghai is attracting backward integration investments from multinational perfusion equipment suppliers. Local producers are scaling sub-6 French fabrication capacity to capture pediatric arterial cannula demand from Southeast Asian export markets.
Arterial Cannula Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue thromboresistant surface chemistry specialization. The market exhibits tiered consolidation with three to five qualified suppliers capturing integrated delivery network contracts while mid-tier fabricators serve regional hospital systems. Strategic archetypes include backward-integrated polymer compounders, captive extrusion specialists, and surface chemistry licensors. Dominant competitive moves encompass direct hospital contracting bypassing distributor markups and multi-source resin qualification to secure batch consistency.
Among Nordic and Japanese fabricators, Getinge AB and Terumo Corporation exemplify backward-integrated archetypes with in-house polymer compounding capabilities. Edwards Lifesciences occupies a position within the surface chemistry tier, representing investment-intensive differentiation through thromboresistant material science. These three anchors demonstrate how geographic concentration of cleanroom infrastructure and regulatory expertise creates defendable positioning in blood-contacting device supply.
| Leading Market Players |
|---|
| Getinge AB |
| Terumo Corporation |
| Medtronic |
| Fresenius Medical Care |
| Nipro Corp. |
| Edwards Lifesciences |
| BD |
| Andocor |
| LivaNova |
| Others |
Cost & Logistics Intelligence
REACH phthalate restrictions and EPA silicone feedstock scrutiny gate qualified supply and premium-tier pricing access in arterial cannula manufacturing. ECHA documentation requirements for plasticizer alternatives extend qualification timelines, compressing margin structures for commodity-tier producers while reinforcing pricing power for validated aseptic production lines.
Pricing Analysis
Input-cost pass-through from medical-grade silicone compounding and JIS-compliant cleanroom operations shapes arterial cannula pricing structures. Three-tier pricing stratifies across heparin-bonded premium configurations, standard perfusion-grade tubing, and economy PVC alternatives. Certification tier—FDA 510(k) clearance versus pending dossiers—drives price differentiation alongside volume scale commitments from integrated delivery networks. Pricing pressure stems from REACH-compliant plasticizer substitution costs. Academic medical centers exhibit lowest price sensitivity for thromboresistant surface chemistries, while surgical centers prioritize economy single lumen formats.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, while distributor networks serve regional cardiac centers and ambulatory surgical settings. Geographic supply concentration clusters in Japan, Germany, and the United States for JIS-compliant extrusion and EMA-validated aseptic production. Raw material dependencies center on perfusion-grade silicone resin, polyurethane elastomers, and REACH-compliant plasticizer alternatives. Single-source vulnerability in East Asian silicone compounding exposes batch consistency risks during geopolitical friction. Distribution runs through GPO-negotiated contracts, perfusion equipment OEM bundling, and specialty distributor networks serving tertiary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arterial cannula market functions as a regulatory compounder where EMA MDR post-market surveillance mandates and FDA endotoxin threshold intensification continuously elevate compliance-driven replacement demand.
For Market Incumbents: To counter emerging entrants with zwitterionic polymer brush surface chemistries, anchor positioning through backward integration into silicone compounding and captive JIS-compliant extrusion capacity. Deepen hospital system partnerships through GPO-negotiated direct agreements that unbundle after-sales service from device pricing. Prioritize ISO 10993 biocompatibility certification maintenance as procurement committees elevate documentation requirements. For New Entrants and Emerging Players: Capture white-space opportunity in India's underpenetrated tertiary cardiac center buildout where CDSCO harmonization with ISO standards opens procurement pathways. Target pediatric sub-6 French fabrication segments where dimensional tolerance requirements and limited qualified supplier bases sustain premium positioning. Pursue surface chemistry licensing partnerships with academic medical centers in Germany and Japan to accelerate clinical protocol adoption. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier cleanroom extrusion specialists because EMA MDR compliance burdens and ISO 10993 testing bottlenecks create acquisition targets with stranded value awaiting capital injection for regulatory remediation. Platform viability extends across the mid-term projection horizon for operators with validated aseptic production documentation spanning batch genealogy. Monitor EPA phthalate restriction enforcement intensity as inflection indicator for material substitution timeline compression and margin structure reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Getinge AB secures batch consistency for perfusion-grade tubing amid East Asian supplier concentration risks. |
| EMA MDR Post-Market Surveillance Compliance | Systematic particulate release documentation mandates reshape competitive moats for pediatric arterial cannula suppliers. |
| Hospital System Direct Contracting | GPO-negotiated agreements in United States integrated delivery networks compress distributor markups and vendor rosters. |
| Surface Chemistry R&D Partnerships | Heparin-bonded coating integration with nanostructured topography creates next-generation thromboresistance without systemic anticoagulant burden. |
| India Cardiac Center Supply Qualification | CDSCO regulatory harmonization opens procurement pathways for international suppliers in Maharashtra and Karnataka buildouts. |
Research Approach
Bottom-up cardiovascular surgery and ECMO procedure modeling reconciled against top-down perfusion equipment installation tracking forms the analytical core of this study. Primary interviews with perfusionists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers were cross-validated against FDA 510(k) clearance databases, EMA MDR conformity assessment registries, hospital procurement contract disclosures, and ISO 10993 biocompatibility testing laboratory records. Top-down trade data and import-export flows for medical-grade silicone and polyurethane resin provided supply-side boundary conditions.
The input-output matrix framing connects procedure volume forecasts to cannula consumption intensity by lumen configuration, application setting, and material specification across the projection horizon. Segmentation dimensions modeled include product type, procedural application, end-user institution category, and polymer composition. CAGRs were derived from regression analysis of historical procedural growth rates against cardiac center density projections and reimbursement pathway stability indices. Forecast inputs incorporated ECMO program expansion trajectories and pediatric subspecialization demand curves.
Regulatory timeline delays, silicone feedstock supply disruptions, and REACH phthalate restriction enforcement intensity are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding EMA MDR implementation pacing and ISO 10993 testing laboratory capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Global Intravascular Catheters Market