
 Cardiovascular Surgical Devices Market | 2026-2036
Cardiovascular Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
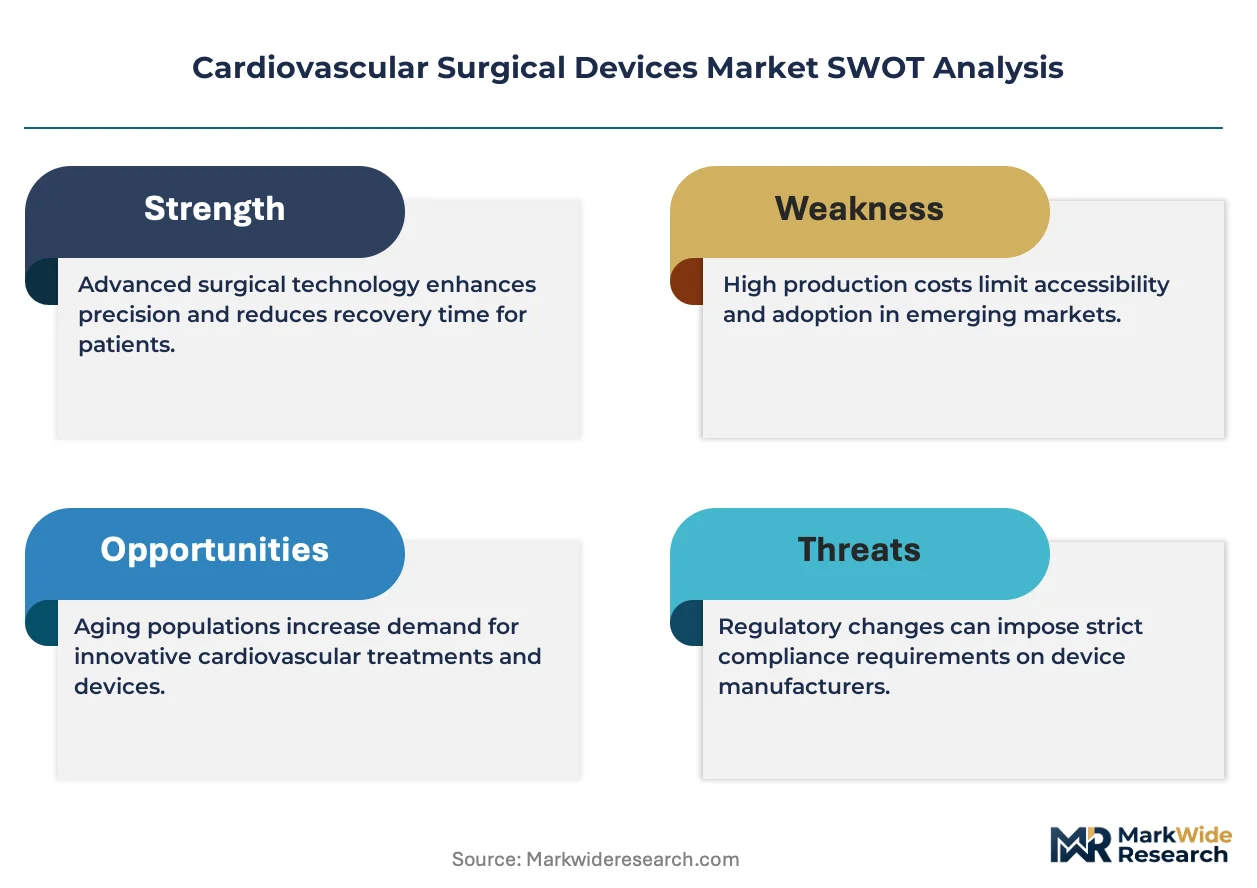
Cardiovascular Surgical Devices Market Analysis
German precision manufacturers is shifting toward robotic-assisted production lines for cardiovascular surgical devices. Medtronic leverages its integrated supply chain to dominate mechanical heart valve production. Edwards Lifesciences anchors its position through sustained R&D intensity in transcatheter valve platforms. Abbott Laboratories differentiates via geographic diversification across cardiac rhythm and vascular graft portfolios.
Cardiovascular surgical devices encompass implantable and instrument-based systems engineered from biocompatible alloys, biological tissues, and polymer matrices to restore cardiac and vascular function during open or minimally invasive procedures. Coronary stents and cardiac valves represent the largest product segments, with bioengineered tissue valves capturing expanding margin pools as durability improves. Minimally invasive and robotic-assisted technologies are displacing conventional surgery in elective coronary bypass and valve repair applications, while vascular graft demand tracks aneurysm repair volumes in aging patient cohorts.
FDA premarket approval requirements and EU MDR conformity assessments shape product development timelines and market access barriers for cardiovascular device manufacturers. ISO 13485 quality management standards and Japan's PMDA pharmaceutical and medical device agency further govern manufacturing compliance across major commercial jurisdictions. Stakeholders must monitor reimbursement policy shifts for robotic-assisted cardiac procedures as these technologies command premium pricing and influence hospital capital allocation decisions.
Market Dynamics
Robotic-assisted cardiac surgery platforms are compressing traditional open-procedure volumes while forcing hospital capital committees to reallocate budgets toward integrated surgical ecosystems.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated review pathway for novel transcatheter valve repair systems compresses commercialization timelines from 36 months to 18 months for qualifying innovations.
- Germany's Aortic Valve Replacement Volumes:Hospital systems in Bavaria and Baden-Württemberg are expanding hybrid operating suites to capture rising elective structural heart procedure demand among patients over 75.
- Nitinol Alloy Processing Advances:Superelastic stent architectures now enable thinner strut profiles without sacrificing radial strength, expanding treatable lesion complexity in coronary interventions.
Market Restraints
- Platinum-Iridium Cathode Cost Volatility:Electrophysiology catheter manufacturers face margin pressure from precious metal price swings tied to South African mining output fluctuations.
- EU MDR Technical Documentation Burden:The expanded clinical evidence requirements for Class III implantable devices have extended conformity assessment timelines by 14-22 months for legacy product renewals.
- Sutureless Valve Durability Limitations:Rapid deployment aortic valves demonstrate elevated paravalvular leak rates at 5-year follow-up compared to conventional sewn prostheses, constraining adoption in younger surgical candidates.
Strategic Opportunities
- Japan's Underserved Peripheral Vascular Segment:Endovascular aneurysm repair penetration in rural prefectures remains 40% below Tokyo-Osaka corridor levels, creating whitespace for mobile angiography deployment.
- AI-Enabled Intraoperative Imaging Fusion:Real-time echocardiography-CT overlay systems are reducing fluoroscopy exposure during structural heart procedures while improving device positioning accuracy.
- India's PLI Scheme for Medical Devices:The production-linked incentive framework offers 5-10% cashback on incremental sales for domestic manufacturing of cardiac stents and catheters.
Industry Challenges
- Robotic Surgery Credentialing Bottlenecks:Hospital systems lack standardized proctoring frameworks for transcatheter mitral valve repair, extending surgeon learning curves and limiting program expansion.
- ISO 13485 Audit Backlog:Notified body capacity constraints have created 8-12 month queues for quality management system recertification, freezing new product introductions for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Surgical Devices Market |
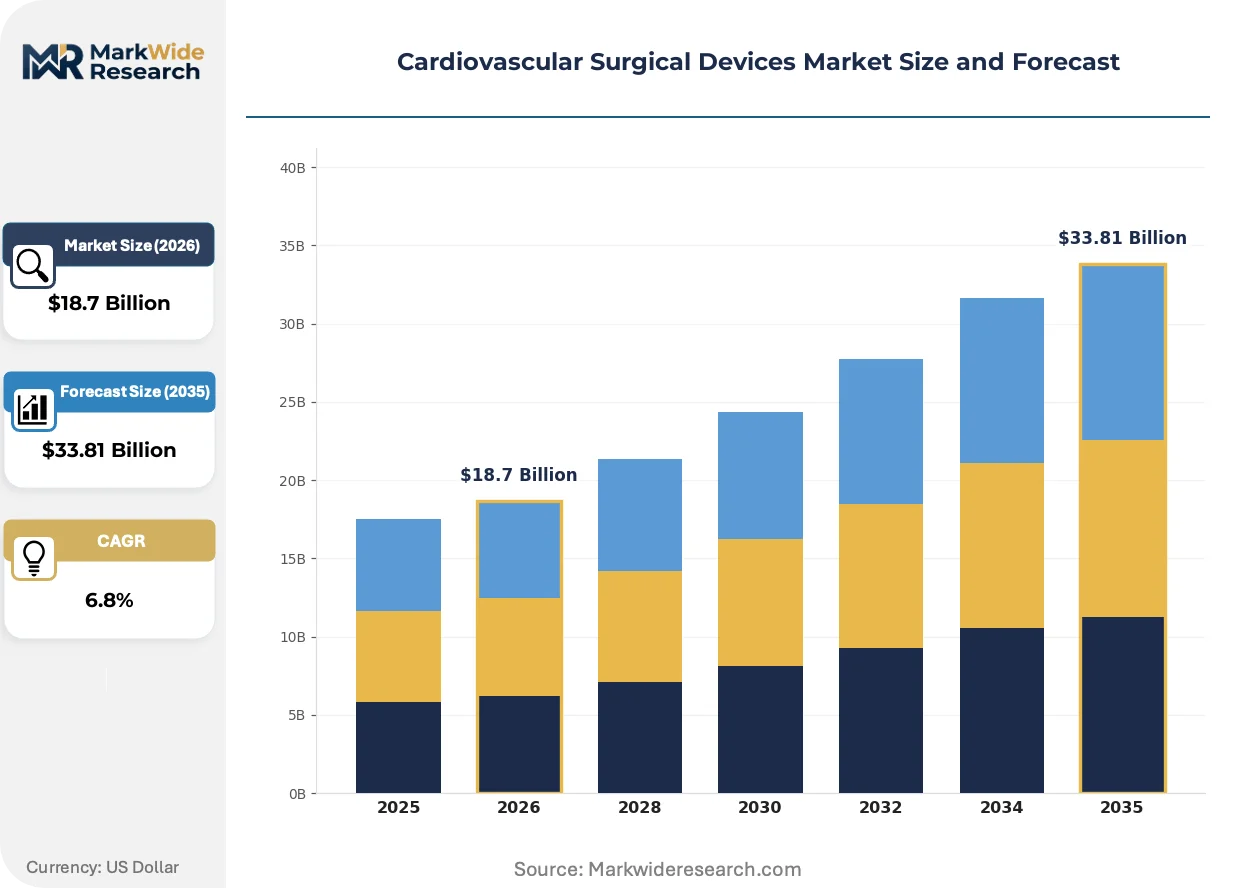
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Valves, Coronary Stents, Vascular Grafts, Aneurysm Clips End User: Hospitals, Clinics, Surgical Centers, Research Facilities Application: Coronary Bypass Surgery, Valve Repair, Aneurysm Repair, Vascular Surgery Technology: Minimally Invasive, Robotic-Assisted, Bioengineered, Conventional Surgery |
| Companies Covered | Medtronic, Edwards Lifesciences, Abbott Laboratories, Boston Scientific Corporation, Terumo Corporation, LivaNova PLC, Cardinal Health, GE Healthcare, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Surgical Devices Market Emerging Trajectories
Digital twin modeling of patient-specific cardiac anatomy is reshaping preoperative planning workflows while compressing the boundary between simulation and intervention.
Transcatheter edge-to-edge repair systems is electrifying structural heart programs by enabling mitral valve intervention without cardiopulmonary bypass. German heart centers are adopting these platforms at twice the rate of conventional surgical referrals, collapsing the historical volume split between interventional cardiologists and cardiac surgeons. The technology is compressing average length of stay from 6 days to 48 hours while expanding treatable patient cohorts to high-surgical-risk populations previously managed medically.
EU MDR Article 120 transition deadlines are forcing cardiovascular device manufacturers to retire legacy product lines rather than absorb clinical evaluation report costs. The regulation's enhanced post-market surveillance requirements are diverting R&D budgets toward regulatory affairs functions. Class III active implantable devices face the steepest compliance burden, with notified bodies in Germany and the Netherlands prioritizing audits for cardiac rhythm management systems.
Hospital procurement committees are consolidating vendor relationships around full-procedure bundles rather than discrete device purchasing. Cardiac surgery departments in the United States are negotiating multi-year supply agreements that wrap stents, delivery systems, and disposable instrumentation into per-procedure pricing. This concentration is most visible in integrated delivery networks across Texas and Florida, where purchasing power has compressed supplier margins by 12-18% over three contracting cycles.
Cardiovascular Surgical Devices Market Segmentation
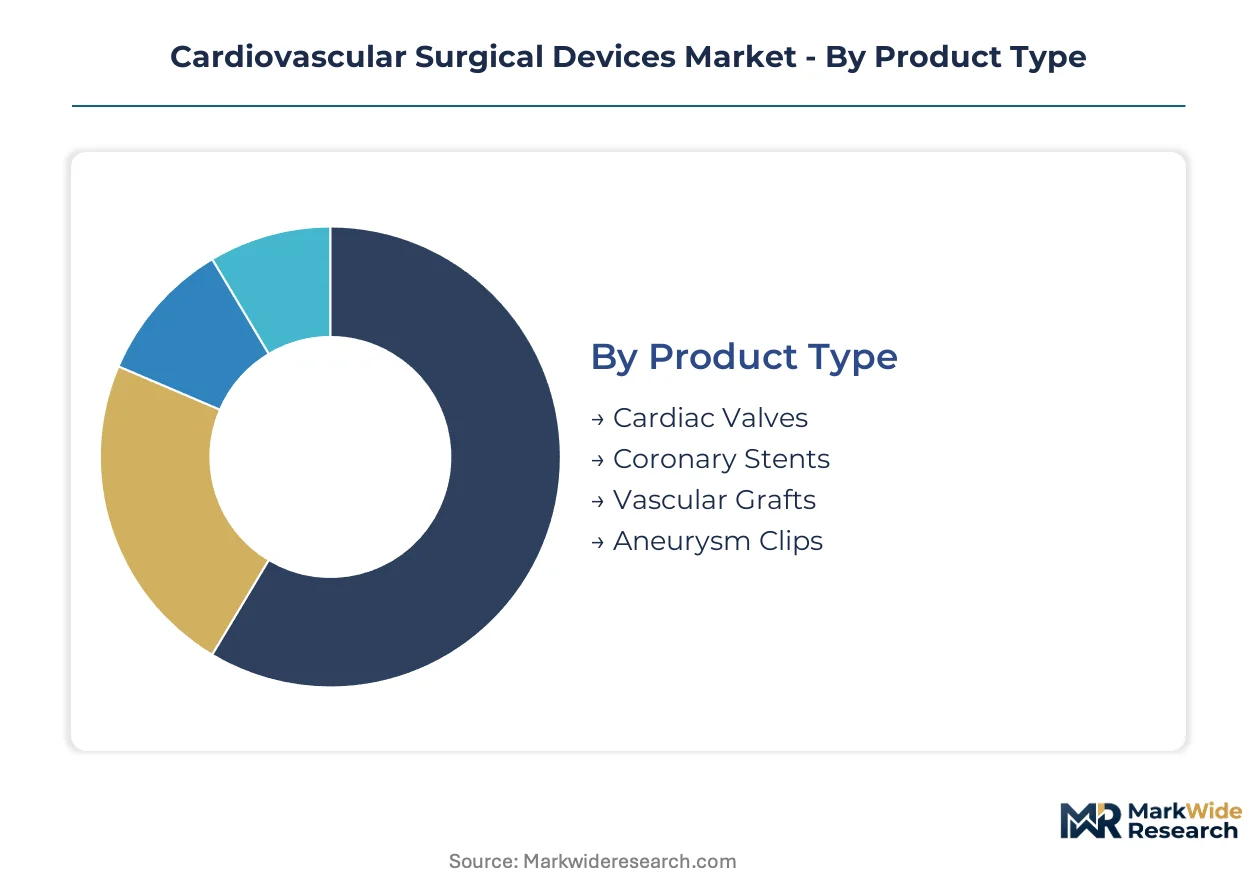
Cardiovascular surgical devices fragment across four distinct taxonomies that reshape competitive positioning. Product type determines margin structure and regulatory pathway intensity. Technology tier governs capital deployment requirements and hospital credentialing complexity.
Product Type:
Standalone implantable devices demand discrete regulatory submissions and specialized manufacturing infrastructure, while integrated delivery systems bundle hardware with consumables under unified quality systems.
- Cardiac Valves:Biological tissue valves incorporate bovine pericardium or porcine aortic leaflets mounted on polymer or metallic frames. Demand concentrates in German heart centers and Japanese university hospitals where transcatheter delivery platforms now capture elective aortic stenosis cases previously routed to surgical valve replacement.
- Coronary Stents:Drug-eluting platforms deploy limus-class compounds from cobalt-chromium or platinum-chromium alloy scaffolds. US interventional cardiology programs in Texas and Florida drive volume concentration as integrated delivery networks negotiate bundled per-procedure pricing.
- Vascular Grafts:Polyester woven tubes and expanded polytetrafluoroethylene conduits address aortic aneurysm and peripheral bypass indications.
- Aneurysm Clips:Cobalt-based alloys and titanium configurations secure intracranial aneurysm necks during open neurovascular procedures.
Coronary stents lead volumes today; cardiac valves are gaining share fastest.
End User:
Facility scale determines procurement sophistication and capital equipment access, with tier-one academic medical centers operating on multi-year technology partnership models distinct from independent surgical centers.
- Hospitals:Tertiary cardiac surgery programs in the United States, Germany, and Japan maintain hybrid operating suites combining surgical sterility with catheterization laboratory imaging. These institutions anchor demand for robotic-assisted platforms and transcatheter delivery systems.
- Clinics:Ambulatory settings in rural Japan and suburban Germany handle diagnostic workup and postoperative surveillance rather than implant procedures.
- Surgical Centers:Independent facilities in Florida and Texas focus on elective vascular access and pacemaker generator changes.
- Research Facilities:Academic medical centers in Bavaria and North Rhine-Westphalia conduct preclinical validation of novel valve repair mechanisms.
Hospitals dominate absolute procedure counts; surgical centers are expanding their addressable case mix most aggressively.
Application:
Clinical indication shapes reimbursement intensity and device selection criteria, with structural heart interventions commanding distinct coding and coverage determinations from coronary revascularization.
- Coronary Bypass Surgery:Saphenous vein and internal mammary artery grafting procedures deploy anastomotic assist devices and stabilization platforms. German cardiac surgery volumes in Baden-Württemberg and Bavaria sustain demand for conventional bypass instrumentation alongside hybrid revascularization approaches.
- Valve Repair:Annuloplasty rings and chordal replacement systems address degenerative mitral regurgitation. Japanese cardiac surgeons in Tokyo and Osaka academic centers increasingly adopt repair-first strategies over replacement.
- Aneurysm Repair:Endovascular stent grafts and open surgical grafts target abdominal and thoracic aortic pathology.
- Vascular Surgery:Peripheral arterial and venous procedures encompass carotid endarterectomy and dialysis access creation.
Coronary bypass surgery maintains the largest installed procedure base; valve repair applications are climbing the fastest.
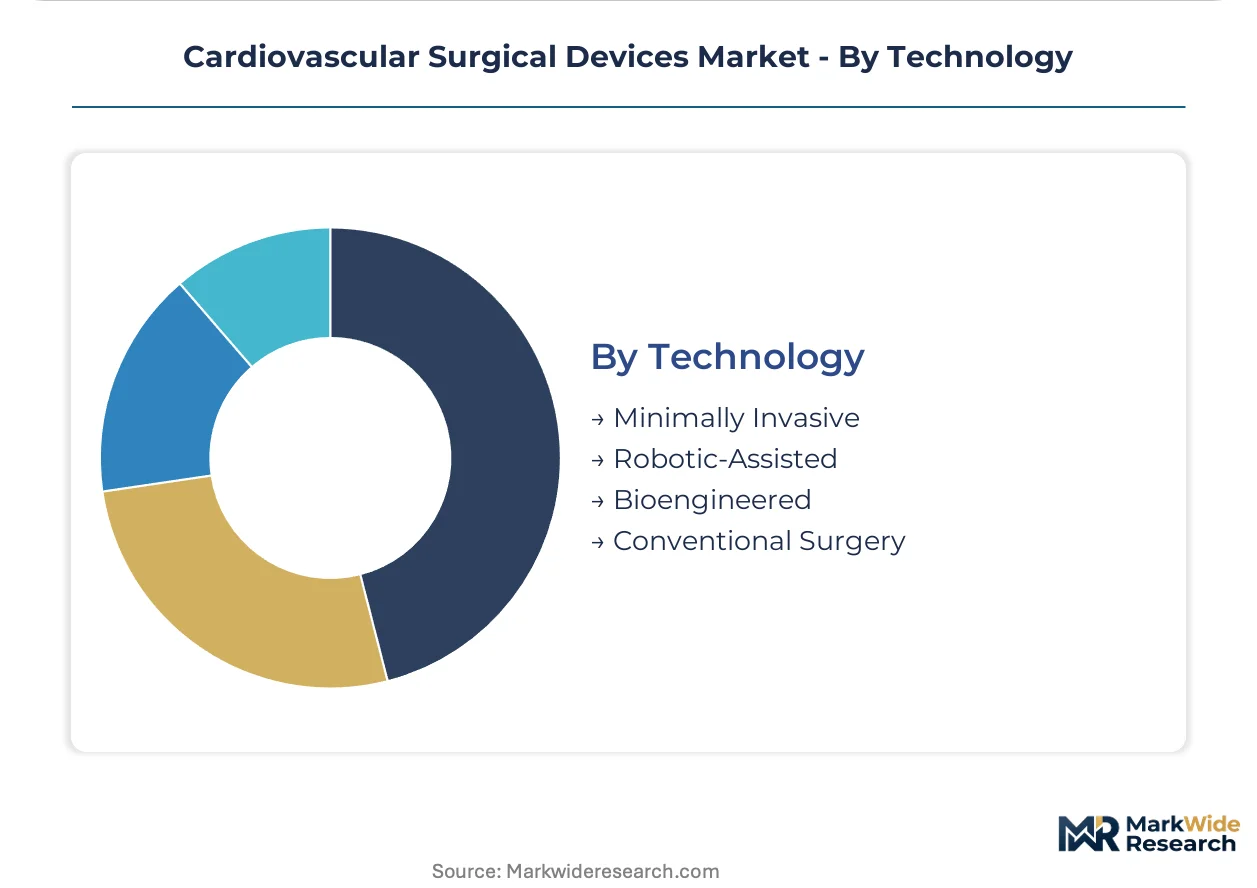
Technology:
Platform maturity stratifies capital intensity and training burden, with established conventional techniques coexisting alongside emerging robotic and bioengineered modalities.
- Minimally Invasive:Port-access and thoracoscopic approaches reduce sternal trauma in isolated valve and coronary procedures. German heart centers in Leipzig and Hamburg have standardized mini-sternotomy and right thoracotomy corridors for aortic valve replacement.
- Robotic-Assisted:Telemanipulation platforms enable endoscopic internal mammary artery harvest and mitral valve repair through 8-millimeter port sites. US hospital systems in California and New York face proctoring bottlenecks that constrain program expansion.
- Bioengineered:Tissue-engineered vascular grafts and decellularized matrices remain in clinical investigation.
- Conventional Surgery:Median sternotomy and standard cardiopulmonary bypass persist for complex reoperations and multivessel disease.
Conventional surgery retains dominant volume share; robotic-assisted platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as cardiovascular device producers migrate production to jurisdictions with streamlined quality system certifications and favorable reimbursement pathways. Cost-of-compliance gaps between mature and emerging regulatory environments are accelerating facility relocation decisions.
United States
FDA breakthrough device designations for transcatheter valve platforms are compressing commercialization timelines for Boston Scientific and Edwards Lifesciences. The agency's premarket approval pathway maintains stringent clinical evidence requirements that favor well-capitalized incumbents. Texas and Florida integrated delivery networks are consolidating procurement around multi-year supply agreements, compressing supplier margins through bundled per-procedure pricing.
Germany
Bavarian and Baden-Württemberg heart centers are expanding hybrid operating suites to capture rising elective structural heart volumes among patients over 75. EU MDR conformity assessments from German notified bodies are prioritizing cardiac rhythm management systems, creating audit queues that freeze mid-tier manufacturer product introductions. Leipzig and Hamburg surgical clusters have standardized mini-sternotomy corridors for aortic valve replacement, anchoring demand for minimally invasive instrumentation.
Japan
Tokyo and Osaka academic centers are adopting mitral valve repair-first strategies at twice the rate of conventional surgical referrals. PMDA pharmaceutical and medical device agency oversight governs manufacturing compliance, with METI industrial policy supporting domestic production of cardiac stents. Rural prefecture endovascular aneurysm repair penetration remains 40% below metropolitan corridor levels, creating whitespace for mobile angiography deployment.
India
Domestic manufacturing of cardiac stents and catheters is accelerating under CDSCO oversight and the PLI scheme's 5-10% cashback on incremental sales. Karnataka and Maharashtra medical device clusters are attracting contract manufacturers seeking cost advantages in nitinol alloy processing. Price controls on coronary stents have forced multinational suppliers to reconfigure distribution models toward premium catheter and structural heart platforms.
China
NMPA national medical products administration is harmonizing clinical trial requirements with international standards, accelerating local approval timelines for transcatheter valve systems. Yangtze River Delta and Pearl River Delta manufacturing hubs are capturing contract production for Western cardiovascular device brands seeking tariff mitigation. Domestic champions are securing market share in drug-eluting stents through hospital procurement consortiums that favor local suppliers.
Cardiovascular Surgical Devices Market Vendor Landscape
United States producers anchor the premium tier through integrated supply chains and sustained R&D intensity; German precision manufacturers hold the mid-market through robotic-assisted production capabilities. The vendor base stratifies across three archetypes: diversified conglomerates with cardiac surgery portfolios, specialized structural heart pure-plays, and contract manufacturers supplying alloy scaffolds and biological tissues. Dominant competitive moves include backward integration into nitinol processing and strategic partnerships around AI-enabled intraoperative imaging.
Among diversified medical technology conglomerates, Medtronic, Edwards Lifesciences, and Abbott Laboratories exemplify distinct strategic postures. Medtronic occupies a position anchored in mechanical heart valve production and integrated supply chain control. Edwards Lifesciences sits within the transcatheter platform specialization tier, with its archetype defined by sustained investment intensity in structural heart repair systems. Abbott Laboratories represents geographic diversification strategy, spanning cardiac rhythm management and vascular graft portfolios across multiple continental markets.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Terumo Corporation |
| LivaNova PLC |
| Cardinal Health |
| GE Healthcare |
| Getinge AB |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in Texas and Florida anchor pricing power through multi-year bundled contracts that compress supplier margins while consolidating vendor relationships around per-procedure economics. This buyer concentration forces cardiovascular device manufacturers to absorb cost volatility in precious metal inputs rather than pass through price adjustments.
Pricing Analysis
Distributor margins on coronary stents and cardiac valves absorb 12-18% compression as hospital procurement committees consolidate around full-procedure bundles. Pricing stratifies across premium transcatheter platforms, standard surgical valves, and economy mechanical prostheses based on clinical evidence tier and FDA approval pathway. Cost compression in the standard tier intensifies because EU MDR conformity assessments extend timelines and divert R&D budgets toward regulatory affairs. Academic medical centers demonstrate lowest price sensitivity due to reimbursement stability for robotic-assisted procedures, while independent surgical centers in Florida and Texas drive hardest bargain negotiations.
Supply Chain Analysis
Workforce availability in nitinol alloy processing constrains capacity expansion across German precision manufacturers and Yangtze River Delta contract producers. Supply concentrates in Germany, Japan, and China for superelastic stent architectures, with biological tissue sourcing anchored in bovine pericardium suppliers in Australia and New Zealand. Raw material dependencies on platinum-iridium cathodes, cobalt-chromium alloys, and decellularized matrices expose electrophysiology catheter manufacturers to South African mining output fluctuations. Distribution runs through specialized cardiovascular device distributors with GPO contracts in the United States, direct hospital relationships in Germany, and regional medical device traders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiovascular surgical devices function as a stable compounder anchored by irreversible demographic shifts toward aging patient cohorts requiring structural heart intervention. Procedure volume growth in coronary and valve applications sustains predictable revenue streams across economic cycles.
For Market Incumbents: Acquire robotic-assisted surgery platforms to counter transcatheter displacement of conventional open procedures. Consolidate backward integration into nitinol processing capabilities to defend margin position against precious metal cost volatility. Expand hybrid operating suite partnerships with Bavarian and Baden-Württemberg heart centers to capture rising elective structural heart volumes among patients over 75.
For New Entrants and Emerging Players: Begin with Japan's rural prefecture peripheral vascular segment where endovascular aneurysm repair penetration remains 40% below Tokyo-Osaka corridor levels. Target mobile angiography deployment models that bypass fixed catheterization laboratory infrastructure requirements. Pursue CDSCO registration and PLI scheme qualification for domestic cardiac stent manufacturing in Karnataka and Maharashtra clusters.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with cardiac surgery portfolios are the most active acquirer in this space, seeking transcatheter platform capabilities and geographic expansion assets. Five-to-ten year viability hinges on reimbursement stability for robotic-assisted procedures and FDA breakthrough pathway access for novel valve repair mechanisms. Monitor EU MDR Article 120 transition deadlines for forced legacy product retirements that create acquisition opportunities among mid-tier manufacturers facing audit backlogs.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses commercialization timelines for novel transcatheter valve repair systems. |
| Hospital System Partnership | Multi-year supply agreements with Texas and Florida integrated delivery networks lock in volume commitments. |
| Backward Integration into Nitinol Processing | In-house superelastic alloy capacity insulates margin from South African platinum group metal volatility. |
| Software Companion Development | AI-enabled intraoperative imaging fusion reduces fluoroscopy exposure and improves device positioning accuracy. |
| Reimbursement Strategy | Coding and coverage determinations for robotic-assisted cardiac procedures influence hospital capital allocation. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market's stakeholder ecosystem. The analysis combines structured interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA premarket approval databases, EU MDR notified body registries, PMDA submission records, and CMS Medicare procedure volume data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchor market size estimation.
Granularity extends to product type, end user facility tier, clinical application, and technology platform maturity across the projection horizon. Segmentation dimensions encompass standalone implantable devices versus integrated delivery systems, tertiary hospitals versus ambulatory surgical centers, coronary bypass versus valve repair indications, and conventional versus robotic-assisted versus bioengineered modalities. CAGRs derive from weighted average procedure growth trajectories and per-procedure device pricing trends, with inputs from aging demographic projections and regulatory approval pipeline assessments.
Several conditions sit outside the modeled scope, including sudden reimbursement policy reversals for robotic-assisted procedures and catastrophic supply disruptions in South African platinum mining. Forecasts reflect assumptions about EU MDR audit queue resolution and FDA staffing capacity for breakthrough device reviews. Practitioners should monitor CMS coding determinations and Japanese METI industrial policy shifts for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market