
 Global Angio Suites Market | 2026-2036
Global Angio Suites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Angio Suites Market Foresight
Software-defined imaging subscription tiers is decoupling capital equipment from recurring revenue models across angio suite deployments. Siemens Healthcare GmbH leverages its service infrastructure to lock in multi-year maintenance contracts. Canon Medical Systems Corporation anchors its competitive stance through R&D intensity in flat-panel detector architectures. Koninklijke Philips N.V. dominates the hybrid angio suite segment through integrated surgical workflow design.
Angio suites are integrated X-ray imaging systems built around C-arm gantries with flat-panel detectors capable of sub-millimeter spatial resolution, designed to enable real-time fluoroscopic guidance during minimally invasive vascular and interventional procedures. Digital subtraction angiography remains the foundational technology, though 3D imaging capabilities are displacing conventional two-dimensional workflows in complex neurovascular interventions. Hybrid angio suites command the deepest margin pools by combining surgical and imaging functions in a single sterile field. Interventional cardiology sustains the largest installed base, while neurovascular procedures represent the fastest-growing application as stroke intervention protocols expand.
The FDA governs device clearance through 510(k) and PMA pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class III imaging systems. Japan's PMDA maintains distinct pharmaceutical and medical device agency review timelines that shape product launch sequencing. Stakeholders must monitor regulatory divergence between FDA breakthrough device designations and EUDAMED database compliance obligations as they allocate R&D budgets across geographies.
Market Dynamics
Hybrid angio suite configurations are compressing capital procurement cycles as metropolitan hospital clusters consolidate interventional cardiology and surgical workflows into single sterile fields, forcing vendors to restructure service revenue models around software-defined imaging subscriptions.
Growth Catalysts
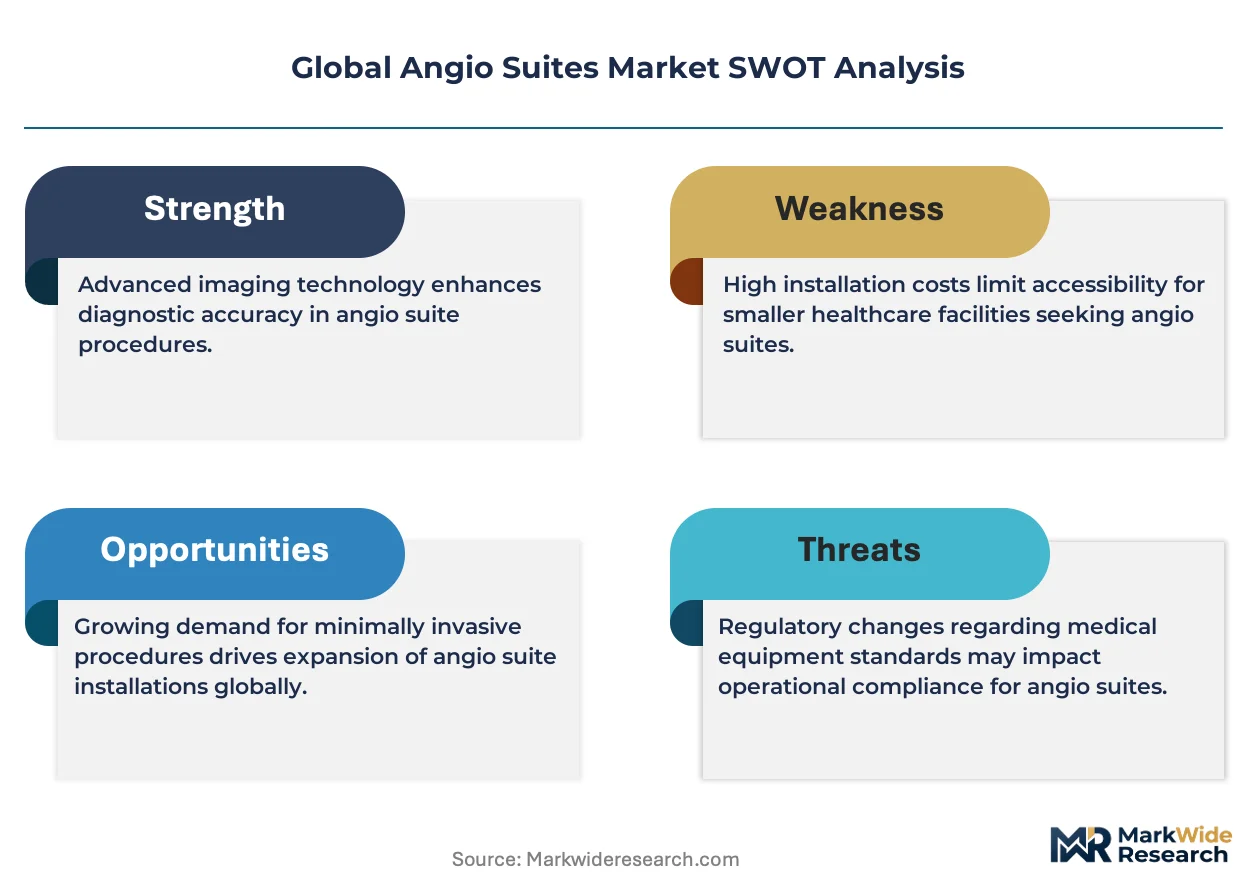
- EU Medical Device Regulation:Stricter clinical evidence requirements for Class III imaging systems are accelerating hospital replacement of legacy C-arm gantries with compliant flat-panel detector architectures.
- Stroke intervention protocols:Expanded neurovascular procedure volumes in Japan, Germany, and the United States are pulling demand for 3D rotational angiography capabilities.
- Metropolitan hospital clusters:Capital budget concentration in Tokyo, Munich, and Chicago is sustaining procurement of integrated surgical-imaging infrastructure despite macroeconomic headwinds.
Market Restraints
- Flat-panel detector supply concentration:Manufacturing of high-resolution amorphous silicon arrays concentrates among a limited supplier base in East Asia, creating input vulnerability.
- FDA 510(k) pathway friction:Tightening imaging dose documentation requirements are extending clearance timelines for iterative hardware modifications.
- Fixed-room installation economics:Structural ceiling reinforcement and radiation shielding requirements limit retrofit opportunities in aging hospital infrastructure.
Strategic Opportunities
- India's tertiary hospital expansion:Government-backed medical city developments in Hyderabad and Chennai are creating greenfield demand for hybrid configurations.
- Artificial intelligence-fluoroscopy convergence:Real-time image enhancement algorithms are opening premium pricing tiers for software-layer differentiation.
- Japan's PMDA breakthrough pathway:Accelerated review timelines for innovative imaging modalities are enabling earlier product launch sequencing versus EU markets.
Industry Challenges
- Interventional radiologist training pipelines:Procedural complexity in neurovascular applications is outpacing fellowship program output in the United States and Germany.
- Legacy DICOM integration:Hospital information system connectivity requirements are extending deployment timelines and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Angio Suites Market |
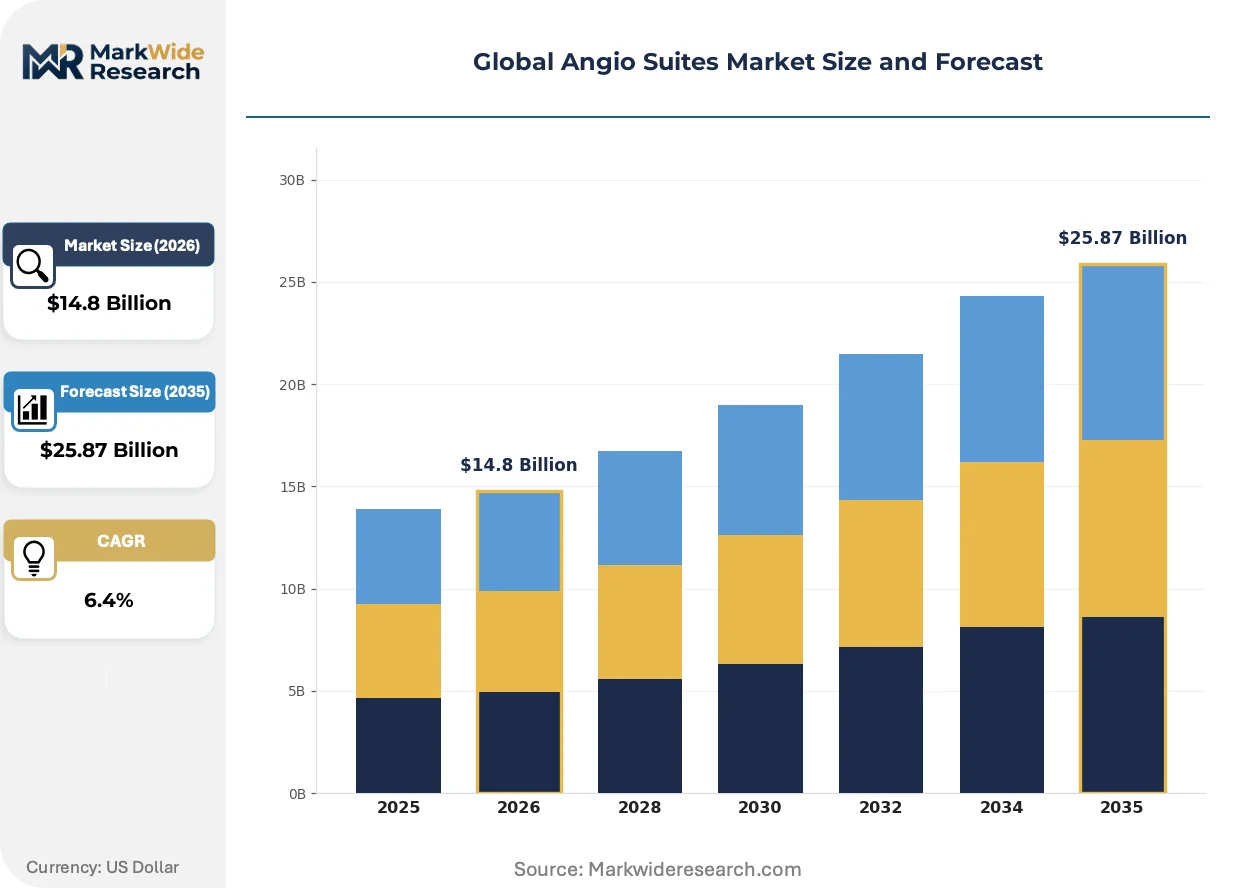
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Angio Suites, Mobile Angio Suites, Hybrid Angio Suites, Portable Angio Suites, Customized Angio Suites Application: Interventional Cardiology, Neurovascular Procedures, Peripheral Vascular, Electrophysiology, Oncology Interventions End User: Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutes, Imaging Centers Technology: Flat Panel Detector, C-arm, Bi-plane Imaging, Digital Subtraction Angiography, 3D Imaging |
| Companies Covered | Siemens Healthcare GmbH, Canon Medical Systems Corporation, GE Healthcare, Koninklijke Philips N.V., Carestream Health, Shimadzu Corporation, Hitachi, Ltd., ZEISS International, FUJIFILM Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Angio Suites Market Shifts & Advancements
Digital subtraction angiography is yielding procedural share to volumetric imaging modalities as stroke intervention protocols demand real-time three-dimensional roadmap guidance during complex neurovascular navigation.
Photon-counting detector technology is absorbing research investment from major imaging OEMs seeking to displace conventional energy-integrating flat-panel architectures. Academic medical centers in the United States and Germany are piloting first-generation systems for quantitative perfusion imaging. This transition is absorbing service revenue from legacy hardware maintenance contracts as hospitals defer replacement decisions awaiting clinical validation data.
The EU Medical Device Regulation's Class III imaging system requirements are forcing manufacturers to maintain parallel technical documentation for EUDAMED database compliance versus FDA 510(k) submissions. European notified bodies are extending review timelines for software-as-a-medical-device components embedded in angio suite control systems. Manufacturers are responding by sequencing product launches in Japan's PMDA pathway to generate clinical evidence prior to EU submission.
Subscription-based software tiers are unbundling capital equipment ownership from imaging capability access in metropolitan hospital clusters. Interventional cardiology departments in Chicago and Tokyo are piloting usage-based licensing for advanced 3D reconstruction modules. This model is compressing traditional five-year replacement cycles while shifting vendor revenue recognition toward recurring service streams.
Global Angio Suites Market Segmentation
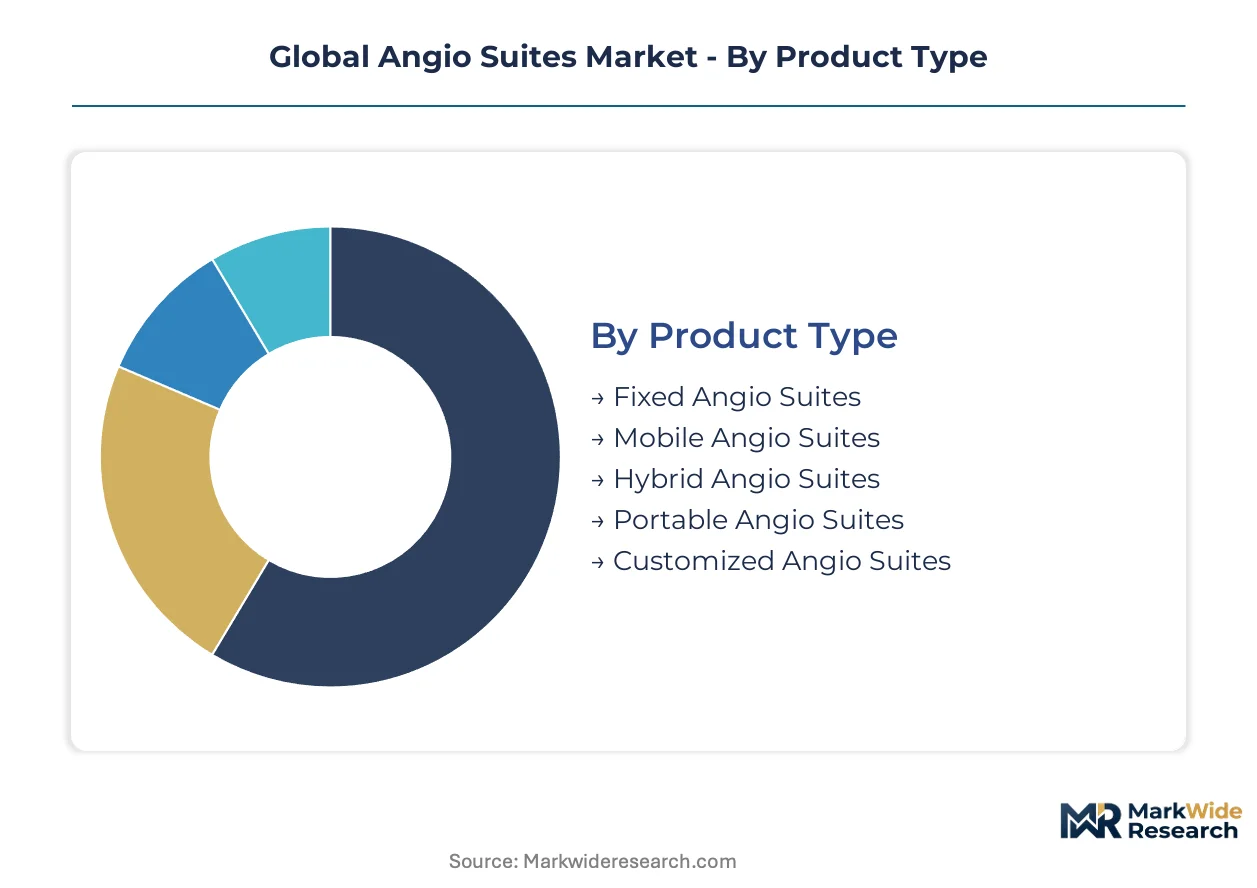
Angio suite procurement patterns diverge sharply across hospital infrastructure maturity, procedural complexity requirements, and capital deployment timelines. Understanding these fault lines reveals where vendors can extract premium pricing versus where hardware commoditization pressures dominate.
Product Type:
Supply concentration in gantry manufacturing and detector fabrication determines margin capture across fixed versus mobile configurations.
- Fixed Angio Suites:Permanent installations with reinforced ceiling mounts and integrated radiation shielding anchor interventional cardiology departments in metropolitan hospital clusters. Procurement concentrates in Tokyo, Munich, and Chicago where capital budgets for single-sterile-field infrastructure remain intact despite macroeconomic headwinds.
- Hybrid Angio Suites:Surgical table integration with C-arm mobility enables combined open and minimally invasive procedures in a single sterile field. Demand clusters in academic medical centers across the United States and Germany where neurovascular and structural heart programs require immediate surgical backup capability.
- Mobile Angio Suites:Wheeled C-arm configurations serve emergency departments and hybrid operating rooms requiring flexible positioning.
- Portable Angio Suites:Compact battery-powered systems address field deployment and temporary facility expansion scenarios.
- Customized Angio Suites:Bespoke configurations for specialized research protocols or unique architectural constraints.
Today's leader: Hybrid Angio Suites. Tomorrow's challenger: Mobile Angio Suites.
Application:
Procedural reimbursement rates and fellowship training pipeline output shape demand concentration across clinical specialties.
- Interventional Cardiology:Percutaneous coronary intervention and structural heart procedures sustain the largest installed base of angio suites worldwide. Volume concentrates in United States hospital systems where Medicare reimbursement for transcatheter aortic valve replacement procedures supports capital recovery timelines.
- Neurovascular Procedures:Mechanical thrombectomy for acute ischemic stroke and endovascular aneurysm repair demand sub-millimeter spatial resolution and 3D rotational roadmap capabilities. Procedure volumes are climbing the fastest in Japan and Germany as population aging expands eligible patient pools.
- Peripheral Vascular:Lower extremity revascularization and dialysis access maintenance drive utilization in community hospital settings.
- Electrophysiology:Atrial fibrillation ablation requires specialized mapping integration with fluoroscopic guidance.
- Oncology Interventions:Transarterial chemoembolization and tumor ablation procedures in liver and kidney malignancies.
Interventional Cardiology commands current revenue share. Neurovascular Procedures are gaining share fastest.
End User:
Capital access and procedure reimbursement differentiation fragment purchasing authority across delivery settings.
- Specialty Clinics:Cardiovascular and neurovascular focused outpatient facilities concentrate high-volume elective procedures away from general hospitals. Procurement in the United States favors mobile and portable configurations to minimize facility modification costs.
- Diagnostic Laboratories:Standalone imaging centers performing peripheral angiography and venography access tiered pricing through equipment leasing structures.
- Ambulatory Surgical Centers:Medicare-certified ASCs in the United States are expanding endovascular service lines under site-of-care payment differentials.
- Research Institutes:Academic medical centers pilot photon-counting detector technology and AI-fluoroscopy convergence.
- Imaging Centers:Multi-modality diagnostic chains seek cross-platform software compatibility for workflow integration.
Specialty Clinics dominate near-term procurement. Ambulatory Surgical Centers present the steepest expansion trajectory.
Technology:
Detector architecture transitions and software layer unbundling are restructuring competitive differentiation.
- Flat Panel Detector:Amorphous silicon and cesium iodide scintillator arrays remain the dominant image capture technology. Manufacturing concentrates among East Asian component suppliers, creating input vulnerability for OEMs assembling systems in Germany and the United States.
- 3D Imaging:Cone-beam CT reconstruction and rotational angiography enable real-time three-dimensional roadmap guidance during complex neurovascular navigation. Academic medical centers in Germany and Japan are piloting next-generation photon-counting implementations.
- C-arm:Gantry mobility and isocenter stability determine procedural workflow efficiency.
- Bi-plane Imaging:Dual orthogonal detector configurations reduce contrast injection volumes in neurointervention.
- Digital Subtraction Angiography:Conventional two-dimensional fluoroscopy with motion correction algorithms.
Flat Panel Detector anchors current installed base. 3D Imaging is reshaping premium tier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's metropolitan hospital clusters outpace Germany's academic medical centers in hybrid angio suite procurement velocity, while the United States sustains the deepest installed base across interventional cardiology networks.
United States
Medicare reimbursement for transcatheter aortic valve replacement procedures sustains capital recovery timelines for fixed-room installations. The FDA's 510(k) pathway governs device clearance with tightening imaging dose documentation requirements. Chicago anchors procurement concentration where hospital systems consolidate interventional cardiology and surgical workflows into single sterile fields.
Germany
Academic medical centers in Munich and Heidelberg pilot photon-counting detector implementations for quantitative perfusion imaging. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class III imaging systems through EUDAMED database compliance. Bavaria's hospital clusters drive replacement of legacy C-arm gantries with compliant flat-panel detector architectures.
Japan
Population aging expands eligible patient pools for mechanical thrombectomy procedures, accelerating neurovascular application growth. The PMDA maintains distinct review timelines that shape product launch sequencing ahead of EU markets. Tokyo's metropolitan hospital clusters concentrate capital budgets for integrated surgical-imaging infrastructure despite macroeconomic headwinds.
India
Government-backed medical city developments in Hyderabad and Chennai create greenfield demand for hybrid configurations. The CDSCO regulates medical device imports and domestic manufacturing under evolving classification frameworks. Tertiary hospital expansion in Telangana and Tamil Nadu pulls procurement toward mobile and portable configurations to minimize facility modification costs.
United Kingdom
NHS capital allocation pressures compress procurement cycles toward equipment leasing structures for diagnostic laboratories. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for imaging system vendors. London's hospital trusts concentrate demand for 3D rotational angiography capabilities in neurovascular intervention centers.
Global Angio Suites Market Competitive Landscape
Top-tier vendors anchor premium hybrid configurations, while mid-tier specialists compete on mobile and portable system accessibility. The vendor base stratifies across three tiers: diversified imaging OEMs with full modality portfolios, regional specialists with concentrated detector fabrication expertise, and emerging entrants targeting price-sensitive tertiary hospital expansions. Strategic archetypes include service-integrated incumbents leveraging multi-year maintenance contracts, R&D-intensive flat-panel detector architects, and workflow-optimized hybrid suite designers. Competitive moves center on software-defined imaging subscription unbundling and artificial intelligence-fluoroscopy convergence for premium pricing tiers.
Among diversified imaging OEMs, Siemens Healthcare GmbH and Koninklijke Philips N.V. exemplify service-integrated incumbents with established maintenance infrastructure, while Canon Medical Systems Corporation occupies a position within the R&D-intensive archetype focused on detector architecture advancement. These three anchors represent distinct competitive vectors: workflow-optimized hybrid design, recurring revenue model lock-in, and hardware-layer differentiation through detector technology investment.
| Leading Market Players |
|---|
| Siemens Healthcare GmbH |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Carestream Health |
| Shimadzu Corporation |
| Hitachi, Ltd. |
| ZEISS International |
| FUJIFILM Holdings Corporation |
| Others |
Supply & Pricing Matrix
Detector engineering talent concentration in Japan and Germany widens pricing-tier spreads as labor-cost differentials between these precision-manufacturing hubs and assembly operations in Southeast Asia feed into three-tier equipment positioning. OEMs leverage this geographic skill gradient to separate premium photon-counting configurations from standard flat-panel offerings.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for amorphous silicon detector substrates, compressing margins on mid-tier fixed angio suites. Three-tier pricing structure across premium, standard, and economy levels separates hybrid configurations with surgical integration from mobile units with basic fluoroscopy. Pricing pressure stems from hospital procurement committees extending replacement cycles amid capital budget constraints. Community hospitals in India exhibit highest price sensitivity, while academic medical centers in Germany and Japan absorb premiums for 3D rotational capabilities.
Supply Chain Analysis
Ocean freight cost volatility from East Asian component ports to European assembly facilities is elevating landed cost uncertainty for gantry manufacturers. Manufacturing of high-resolution flat-panel detectors concentrates in Japan, South Korea, and Taiwan, with amorphous silicon wafer processing and cesium iodide scintillator deposition as critical inputs. Single-source vulnerability in photon-counting detector crystal growth creates supply chain risk as academic medical centers await clinical validation. Distribution runs through direct OEM-hospital relationships for fixed installations and regional distributors for mobile configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in angio suites rests on software-defined imaging subscriptions decoupling recurring revenue from capital equipment cycles, with AI-fluoroscopy modules enabling premium-tier pricing independent of hardware replacement timelines.
For Market Incumbents: Anticipate photon-counting detector commoditization by locking hospital systems into multi-year software maintenance contracts before clinical validation data democratizes access. Deepen backward integration into flat-panel detector fabrication to defend against East Asian component supply disruptions. Prioritize workflow-optimized hybrid suite design in Tokyo and Munich metropolitan clusters where capital budgets concentrate. For New Entrants and Emerging Players: Begin with mobile and portable configurations in India's tertiary hospital expansion, where government-backed medical cities in Hyderabad and Chennai favor equipment minimizing facility modification costs. Target diagnostic laboratories and ambulatory surgical centers in the United States seeking usage-based licensing for 3D reconstruction modules. Pursue channel partnerships with established service infrastructure rather than direct hospital sales. For Investors and Strategic Acquirers: Diversified imaging OEMs with full modality portfolios are the most active acquirer in this space, seeking detector fabrication specialists to secure input supply. Long-term viability hinges on software-layer differentiation as hardware margins compress across the projection horizon. Monitor FDA breakthrough device designations versus EUDAMED database compliance obligations as inflection indicators for R&D budget allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | AI-fluoroscopy convergence enables subscription revenue unbundling from capital equipment ownership. |
| Hospital System Partnership | Metropolitan clusters in Chicago and Tokyo consolidate procurement authority through integrated surgical-imaging workflows. |
| Reimbursement Strategy | Medicare coverage for transcatheter aortic valve replacement sustains capital recovery timelines for fixed-room installations. |
| CE Marking Pathway | EUDAMED database compliance for Class III imaging systems extends review timelines versus Japan's PMDA accelerated pathway. |
| Backward Integration into Detectors | Captive supply of amorphous silicon arrays mitigates East Asian component concentration vulnerability. |
Research Methodology
Direct dialogue with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative insights in procurement decision dynamics. Secondary validation drew from FDA 510(k) clearance databases, PMDA approval records, EUDAMED device registrations, and hospital capital expenditure disclosures. Bottom-up installed base estimates triangulated against top-down equipment spending flows across metropolitan hospital clusters.
Segment-level outputs across the analysis window reflect modeled projections for product type, application, end user, and technology dimensions including detector architecture transitions and software unbundling patterns. CAGRs derived from equipment replacement cycle analysis, procedure volume elasticity to imaging capability access, and capital budget allocation trends in named geographies. Forecast inputs incorporated stroke intervention protocol expansion rates and photon-counting detector clinical validation timelines.
Several conditions sit outside the modeled scope, including sudden regulatory divergence between FDA breakthrough pathways and EU MDR requirements, acute supply disruptions in flat-panel detector substrate manufacturing, and unanticipated reimbursement cuts for transcatheter procedures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Global Coil Wound Devices Market