
 Fibromuscular Dysplasia Treatment Market | 2026-2036
Fibromuscular Dysplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Fibromuscular Dysplasia Treatment Market Intelligence
Multi-source procurement of stent platforms and catheter systems is shifting toward captive supply arrangements among top-tier device manufacturers. Abbott Laboratories leverages its endovascular portfolio to sustain leadership in renal artery interventions. Medtronic anchors its position through integrated imaging-guided catheter platforms. Boston Scientific Corporation differentiates via specialized balloon technologies for fibromuscular stenosis.
Fibromuscular dysplasia treatment encompasses percutaneous transluminal angioplasty, pharmacologic blood pressure management, and emerging neuromodulation approaches targeting aberrant renal sympathetic signaling in non-atherosclerotic vascular disease. Antihypertensive drugs occupy the largest revenue pool given chronic maintenance requirements across the 46 to 60 patient age group, while renal denervation represents the fastest-expanding treatment type as catheter-based sympathetic ablation gains procedural traction. Application area demand concentrates in renal artery interventions, though carotid artery cases command premium reimbursement due to stroke prevention urgency.
The FDA's orphan drug designations and breakthrough device pathways shape development economics for FMD-specific therapies, while HIPAA governs real-world evidence collection from specialized registries. EMA's MDR requirements for Class III implantable devices extend compliance burdens for European market access. Stakeholders must monitor evolving CMS coverage determinations for renal denervation and position clinical evidence generation to match payer evidentiary thresholds.
Market Dynamics
The renal denervation catheter segment is consolidating procurement around integrated imaging platforms, as tertiary hospitals demand single-vendor solutions for complex fibromuscular stenosis cases. This supply-side concentration is compressing margins for standalone balloon manufacturers while elevating platform economics.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for catheter-based sympathetic ablation systems accelerate commercialization of renal denervation platforms targeting resistant hypertension in FMD patients.
- Tertiary Hospital Expansion:Academic medical centers in the United States are establishing dedicated fibrovascular centers of excellence, creating concentrated demand pools for interventional cardiology procedures.
- Sympathetic Nerve Mapping:Advanced electrophysiological localization techniques are improving procedural precision for renal artery interventions, expanding addressable patient populations beyond pharmaceutical management.
Market Restraints
- Platinum-Iridium Alloy Costs:Electrode material price volatility constrains margin flexibility for catheter manufacturers dependent on precious metal electrodes for radiofrequency ablation systems.
- EMA MDR Compliance Burden:European Class III implantable device requirements extend certification timelines and clinical evidence thresholds, delaying market access for novel stent platforms.
- Pharmacologic Substitution:Fixed-dose combination antihypertensive therapies retain strong payer preference for first-line FMD management, limiting procedural intervention rates in cost-sensitive health systems.
Strategic Opportunities
- Carotid Artery Intervention Premium:Stroke prevention urgency commands superior reimbursement rates compared to renal procedures, creating margin expansion potential for specialized catheter platforms.
- Real-World Evidence Registries:HIPAA-compliant longitudinal outcome databases enable post-market surveillance that satisfies CMS evidentiary requirements for renal denervation coverage determinations.
- Neuromodulation Convergence:Integration of renal sympathetic ablation with baroreflex activation therapy creates dual-mechanism platforms for resistant vascular hypertension management.
Industry Challenges
- Interventional Cardiology Fellowship Pipeline:Specialized training programs for complex FMD cases remain concentrated at select academic institutions, creating procedural capacity constraints.
- Orphan Indication Trial Design:Small patient populations complicate randomized controlled study enrollment, forcing reliance on adaptive trial frameworks that extend regulatory negotiation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibromuscular Dysplasia Treatment Market |
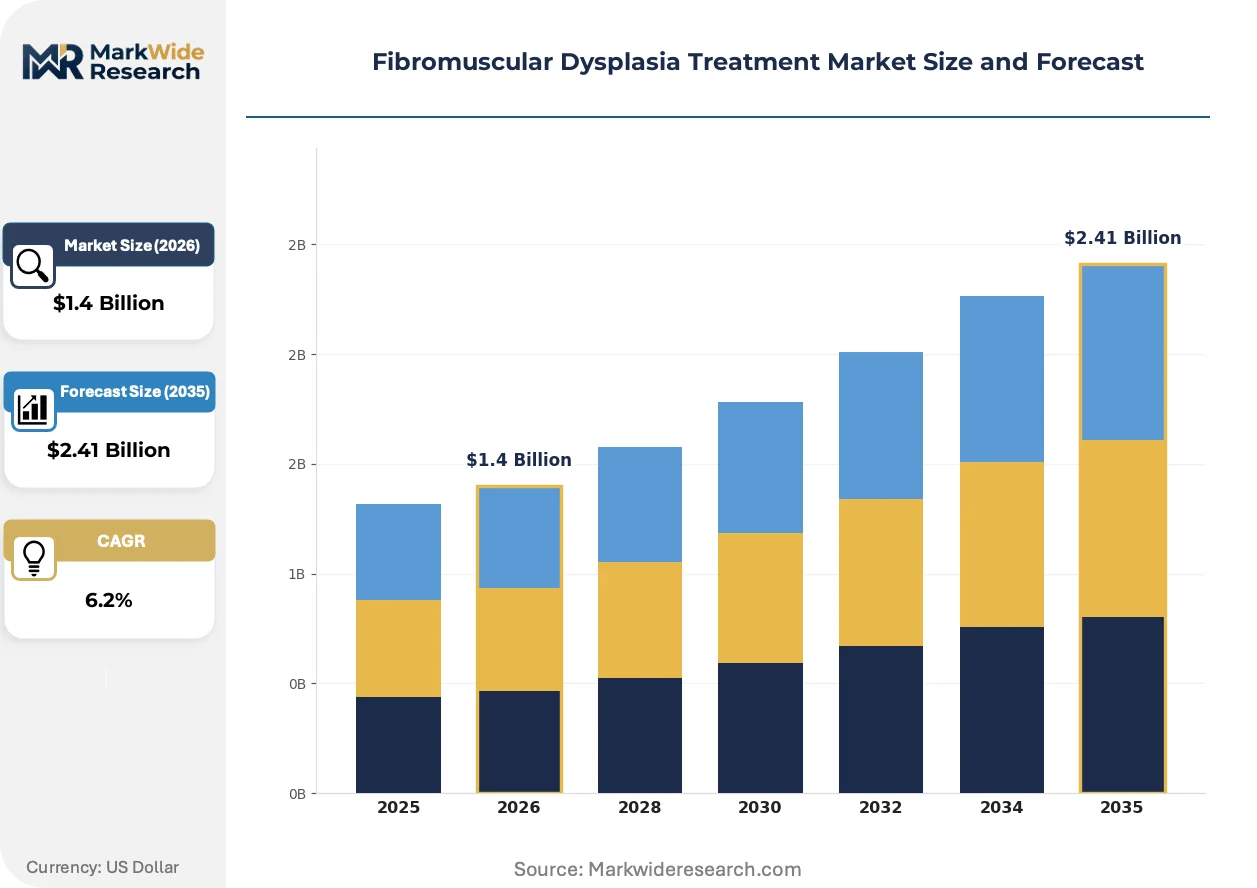
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Angioplasty, Antihypertensive Drugs, Beta Blockers, Renal Denervation Application Area: Renal Artery, Carotid Artery, Vertebral Artery, Mesenteric Artery Patient Age Group: Under 30, 31 to 45, 46 to 60, Above 60 Healthcare Provider Type: Specialty Clinics, Diagnostic Centers, Tertiary Hospitals, Rehabilitation Centers |
| Companies Covered | Abbott Laboratories, Bayer, Pfizer, Bristol-Myers Squibb, Novartis, Medtronic, Sanofi, AstraZeneca, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibromuscular Dysplasia Treatment Market Strategic Shifts & Innovations
Catheter-based renal denervation is displacing chronic pharmaceutical management as the preferred intervention for resistant FMD-associated hypertension. Platform integration and procedural automation are compressing the competitive set around imaging-guided systems.
Radiofrequency balloon catheter systems are automating electrode positioning and temperature modulation during renal artery interventions. Tertiary hospitals with high FMD case volumes are adopting these platforms to reduce operator-dependent variability. The technology is automating procedural standardization while compressing training curves for interventional cardiologists entering the fibrovascular specialty.
EMA's Medical Device Regulation is extending clinical evidence requirements for Class III implantable stents and catheters. European manufacturers face extended notified body review timelines and enhanced post-market surveillance obligations. Renal denervation device developers are responding with parallel FDA-EMA submission strategies that prioritize breakthrough designation pathways.
Hospital procurement departments are consolidating vendor relationships around full-platform contracts for interventional suites. Standalone balloon suppliers face exclusion from preferred vendor lists as integrated imaging-catheter platforms capture procurement decisions. This concentration is most visible in United States academic medical centers establishing fibrovascular centers of excellence.
Fibromuscular Dysplasia Treatment Market Segmentation
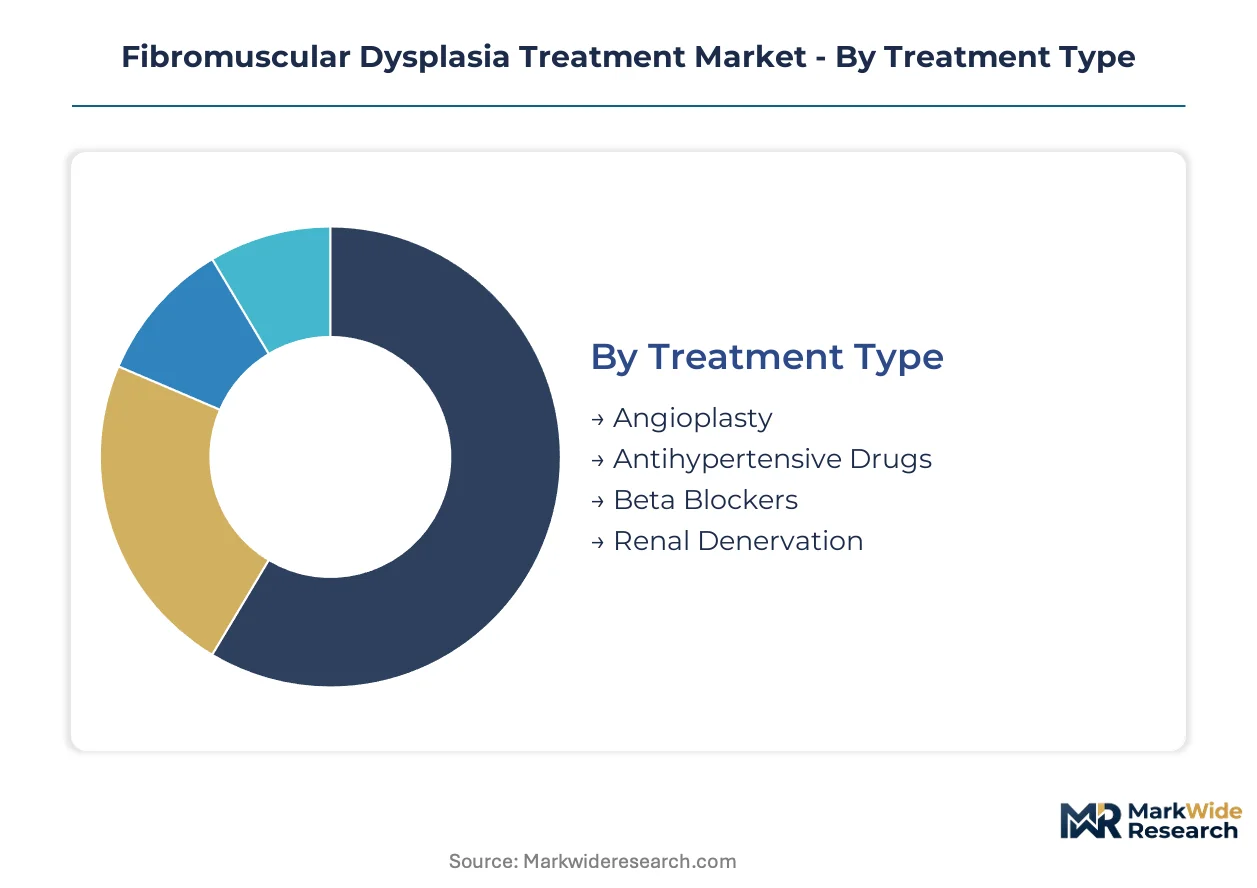
Segmentation in the Fibromuscular Dysplasia Treatment Market reveals distinct procurement patterns across intervention modalities and care settings. Treatment type selection hinges on hypertension severity and anatomic lesion characteristics, while provider type concentration shapes device purchasing power and platform standardization decisions.
Treatment Type:
Reimbursement tier and procedural complexity determine how hospitals allocate capital budgets across therapeutic categories.
- Antihypertensive Drugs:Chronic pharmaceutical regimens combining ACE inhibitors, calcium channel blockers, and diuretics constitute the foundational management approach for hemodynamically stable FMD patients. United States payers maintain strong preference for fixed-dose combination therapies as first-line intervention, constraining procedural escalation rates in cost-sensitive health systems.
- Renal Denervation:Catheter-based radiofrequency and ultrasound ablation platforms target aberrant renal sympathetic signaling in resistant hypertension cases. Tertiary hospitals with dedicated fibrovascular centers are consolidating procurement around integrated imaging-guided systems, accelerating adoption beyond pharmaceutical failure thresholds.
- Angioplasty:Percutaneous transluminal balloon dilation restores luminal patency in fibromuscular stenosis without permanent implantation.
- Beta Blockers:Sympatholytic agents manage adrenergic-mediated hypertension in patients with bilateral renal artery involvement.
Antihypertensive drugs lead on scale; renal denervation leads on momentum.
Application Area:
Anatomic site dictates reimbursement intensity and procedural urgency, with cerebrovascular applications commanding premium rates.
- Renal Artery:The predominant intervention site accounts for the majority of FMD-related procedures, presenting with hypertension, renal dysfunction, or flank pain. United States academic medical centers are concentrating fellowship-trained interventionalists at dedicated fibrovascular centers of excellence, creating referral density for complex bilateral cases.
- Carotid Artery:Cervicocranial fibromuscular dysplasia carries elevated stroke risk, mandating urgent intervention timelines. Stroke prevention urgency secures superior reimbursement rates from CMS and commercial payers compared to renal procedures, attracting specialized catheter platform development.
- Vertebral Artery:Posterior circulation involvement presents with dizziness, vertigo, or posterior circulation ischemia requiring neurovascular expertise.
- Mesenteric Artery:Visceral artery FMD manifests as intestinal angina or mesenteric ischemia in rare presentations.
Renal artery interventions anchor procedure volume; carotid applications capture margin expansion.
Patient Age Group:
Demographic distribution aligns with FMD's peak incidence in middle-aged women, shaping clinical trial enrollment and device sizing specifications.
- 46 to 60:The core epidemiological cohort for fibromuscular dysplasia, predominantly perimenopausal women presenting with resistant hypertension or incidental imaging findings. United States specialty clinics report concentrated case volumes in this demographic, driving demand for catheter platforms sized to smaller renal artery diameters.
- 31 to 45:Early-onset presentations require differential diagnosis from vasculitis and connective tissue disorders, extending diagnostic workup timelines.
- Under 30:Pediatric and young adult FMD often associates with genetic syndromes or multifocal disease patterns.
- Above 60:Late diagnoses compete with atherosclerotic renovascular disease for etiologic attribution.
The 46 to 60 cohort dominates absolute patient flow; the 31 to 45 segment shows the steepest expansion trajectory as imaging sensitivity improves.
Healthcare Provider Type:
Capital intensity and case complexity stratify purchasing authority across the care continuum.
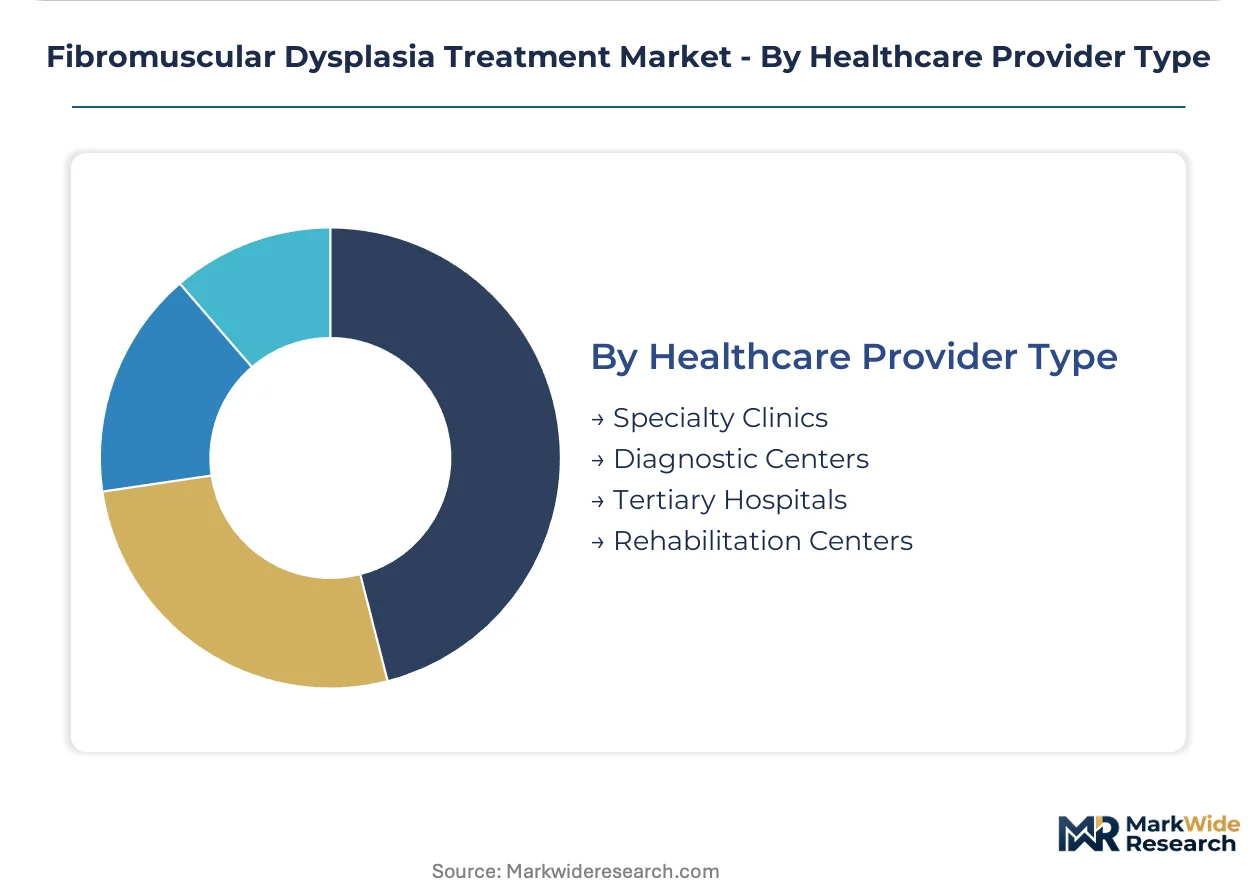
- Tertiary Hospitals:Academic medical centers with interventional cardiology and vascular surgery programs aggregate complex FMD referrals requiring multimodality intervention. These institutions are driving consolidation toward single-vendor platform contracts for integrated imaging-catheter systems, marginalizing standalone device suppliers.
- Specialty Clinics:Dedicated hypertension and vascular medicine practices manage stable patients and coordinate procedural referrals.
- Diagnostic Centers:Imaging facilities with CT angiography and MR angiography capabilities provide initial detection and surveillance.
- Rehabilitation Centers:Post-interventional recovery and blood pressure optimization programs support functional outcomes.
Tertiary hospitals concentrate purchasing power; specialty clinics expand access reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturers exploit regulatory-arbitrage opportunities as EMA MDR compliance costs in Europe diverge from FDA breakthrough pathways in the United States. Production and clinical trial investments migrate toward jurisdictions offering faster market access for orphan vascular indications.
United States
Academic medical centers in Cleveland, Rochester, and Boston anchor specialized fibrovascular centers of excellence that concentrate complex referral volumes. FDA breakthrough device designations for renal denervation catheters accelerate commercialization timelines compared to standard PMA pathways. Tertiary hospitals in these clusters are consolidating procurement around single-vendor imaging-catheter platforms, marginalizing standalone balloon suppliers from preferred vendor lists.
Germany
EMA MDR requirements for Class III implantable devices extend notified body review timelines and amplify post-market surveillance obligations for stent manufacturers. Heidelberg and Munich host Europe's densest concentrations of interventional cardiology fellowship programs trained in complex FMD cases. German hospitals face compressed margins as precious metal electrode costs for radiofrequency ablation systems fluctuate on commodity markets.
Japan
PMDA's sakigake designation system offers expedited review for innovative catheter platforms addressing resistant hypertension in non-atherosclerotic vascular disease. Tokyo and Osaka medical centers report concentrated case volumes in perimenopausal women aged 46 to 60, driving demand for renal artery platforms sized to smaller diameters. Domestic manufacturers face pricing pressure as integrated imaging-catheter systems from US and European suppliers capture procurement decisions.
United Kingdom
NICE technology appraisals for renal denervation create coverage determination uncertainty that delays procedural adoption in NHS trusts. London teaching hospitals maintain referral density for carotid artery interventions where stroke prevention urgency secures premium reimbursement rates. Post-Brexit regulatory divergence from EMA MDR is forcing parallel submission strategies for device developers seeking both UKCA and CE marking.
Australia
TGA's priority review pathway for orphan devices offers faster market access than standard registration routes for fibrovascular intervention platforms. Melbourne and Sydney academic centers are establishing dedicated hypertension clinics that coordinate with interventional cardiology for resistant cases. Real-world evidence collection from specialized registries satisfies payer evidentiary requirements for procedural coverage determinations in the private health system.
Fibromuscular Dysplasia Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue neuromodulation convergence and real-world evidence generation as differentiation vectors. The vendor base stratifies across three archetypes: diversified cardiovascular conglomerates with full-platform portfolios, specialized catheter manufacturers focused on balloon technologies, and pharmaceutical incumbents with chronic antihypertensive franchises. Dominant competitive moves include backward integration into electrode material supply chains and strategic partnerships with academic medical centers for registry-based evidence generation.
Within the diversified cardiovascular tier, Abbott Laboratories, Medtronic, and Boston Scientific Corporation exemplify platform-centric strategies. Abbott leverages its endovascular portfolio breadth to sustain leadership in renal artery interventions. Medtronic anchors its competitive position through integrated imaging-guided catheter systems that tertiary hospitals favor for complex fibromuscular stenosis cases. Boston Scientific occupies a specialized position via balloon technologies differentiated for fibrovascular applications rather than atherosclerotic disease. These three conglomerates represent the consolidation pressure forcing standalone device suppliers toward acquisition or niche specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bayer |
| Pfizer |
| Bristol-Myers Squibb |
| Novartis |
| Medtronic |
| Sanofi |
| AstraZeneca |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Consolidated procurement at United States tertiary hospitals toward single-vendor imaging-catheter platforms is compressing margins for standalone balloon manufacturers and forcing supply-side restructuring around integrated system economics.
Pricing Analysis
Platinum-iridium electrode cost pass-through volatility constrains margin flexibility for radiofrequency ablation catheter manufacturers. Three-tier pricing structure across premium integrated platforms, standard imaging-guided systems, and economy balloon-only devices reflects certification level and after-sales service bundling. Cost compression in the economy tier is intensifying because hospital procurement departments exclude standalone suppliers from preferred vendor lists. Academic medical centers show least price sensitivity due to bundled platform contracts; cost-sensitive health systems in secondary markets exhibit highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Rotterdam, and Singapore anchor hub-and-spoke patterns for catheter platform delivery to tertiary hospitals. Manufacturing concentrates in the United States, Ireland, and Costa Rica for FDA-registered device production. Supply chains draw from South African platinum mines, German precision electronics, and Japanese catheter tubing. Single-source vulnerability in precious metal electrode supply creates procurement risk. Distribution runs through GPO-contracted channels and direct hospital agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device pathways offer faster commercialization timelines than EMA MDR compliance, creating geographic-arbitrage opportunities for catheter manufacturers prioritizing United States market entry over European access.
For Market Incumbents: To counter procurement consolidation toward single-vendor platforms, Abbott Laboratories and Medtronic should deepen backward integration into electrode material supply chains and establish captive real-world evidence registries at Cleveland Clinic and Mayo Clinic to secure preferred vendor status. For New Entrants and Emerging Players: Enter via carotid artery intervention platforms where stroke prevention urgency commands premium reimbursement and incumbent presence remains thinner than renal denervation. Target Australian and Japanese markets through TGA priority review and PMDA sakigake pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized neuromodulation convergence platforms combining renal sympathetic ablation with baroreflex activation therapy. Long-term viability hinges on CMS coverage determination outcomes for renal denervation. Watch for FDA advisory committee meetings as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Device Pathway Submission | FDA expedited review accelerates commercialization timelines for renal denervation catheters beyond standard PMA routes. |
| Academic Medical Center Partnership | Cleveland Clinic and Mayo Clinic registry collaborations generate CMS-compliant real-world evidence for coverage determinations. |
| Backward Integration into Electrode Supply | In-house platinum-iridium sourcing mitigates commodity price volatility for radiofrequency ablation systems. |
| Neuromodulation Platform Convergence | Dual-mechanism systems combining renal denervation with baroreflex activation target resistant hypertension segments. |
| Parallel FDA-EMA Submission Strategy | Coordinated regulatory filings navigate divergent timelines between breakthrough pathways and MDR compliance. |
Research Approach
Multiple input streams — primary interviews with interventional cardiologists and hospital purchasing committees, secondary validation through FDA filings and CMS coverage databases, and procedural volume triangulation — were reconciled to construct market estimates. Stakeholder roles included catheter platform engineers, GPO contracts managers, biomedical engineers at tertiary hospitals, and regulatory affairs leads at device manufacturers. Secondary sources encompassed hospital procurement databases, ClinicalTrials.gov entries for renal denervation studies, and Medicare claims data. Bottom-up procedure counts and top-down device revenue estimates were cross-referenced.
Historical procedural growth patterns were cross-referenced against expert panel inputs from interventional cardiology fellowship directors. Segmentation dimensions modeled include treatment modality, anatomic application site, patient age cohort, and healthcare provider type. CAGRs were derived from weighted procedure volume projections and device pricing trajectories. Forecast inputs incorporated FDA approval timelines, EMA MDR transition schedules, and tertiary hospital expansion plans.
Inputs from CMS coverage determinations and European notified body review timelines were available through the study window; gaps in real-world renal denervation outcome data introduce uncertainty bands around procedural adoption curves. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and hospital procurement consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market