
 Global Transcranial Doppler Ultrasound Market | 2026-2036
Global Transcranial Doppler Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcranial Doppler Ultrasound Market Foresight
Clinical performance is decoupling from basic hardware specifications as portable and handheld systems achieve diagnostic parity with stationary consoles. Viasonix leverages proprietary digital signal processing to sustain premium positioning in cerebrovascular monitoring. DWL Elektronische Systeme anchors its European installed base through specialized vasospasm detection protocols. NovaSignal competes by integrating artificial intelligence into automated emboli detection, differentiating its workflow from conventional manual interpretation.
Transcranial Doppler ultrasound measures blood flow velocity in cerebral arteries using pulsed-wave or continuous-wave ultrasound at 2 MHz frequency, enabling non-invasive assessment of cerebrovascular hemodynamics for stroke risk stratification and brain death confirmation. Portable systems are capturing the fastest growth trajectory as emergency care units and neurology clinics prioritize bedside deployment over capital-intensive console installations. Duplex Doppler technology commands the deepest margin pools by combining anatomical B-mode imaging with spectral flow analysis, whereas basic continuous-wave devices face commoditization in screening applications.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and software documentation burdens for manufacturers seeking market access. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility testing constrain design choices for portable devices intended for uncontrolled clinical environments. Stakeholders must monitor evolving reimbursement codes for remote neurovascular monitoring as payers reassess coverage for outpatient TCD services.
Market Dynamics
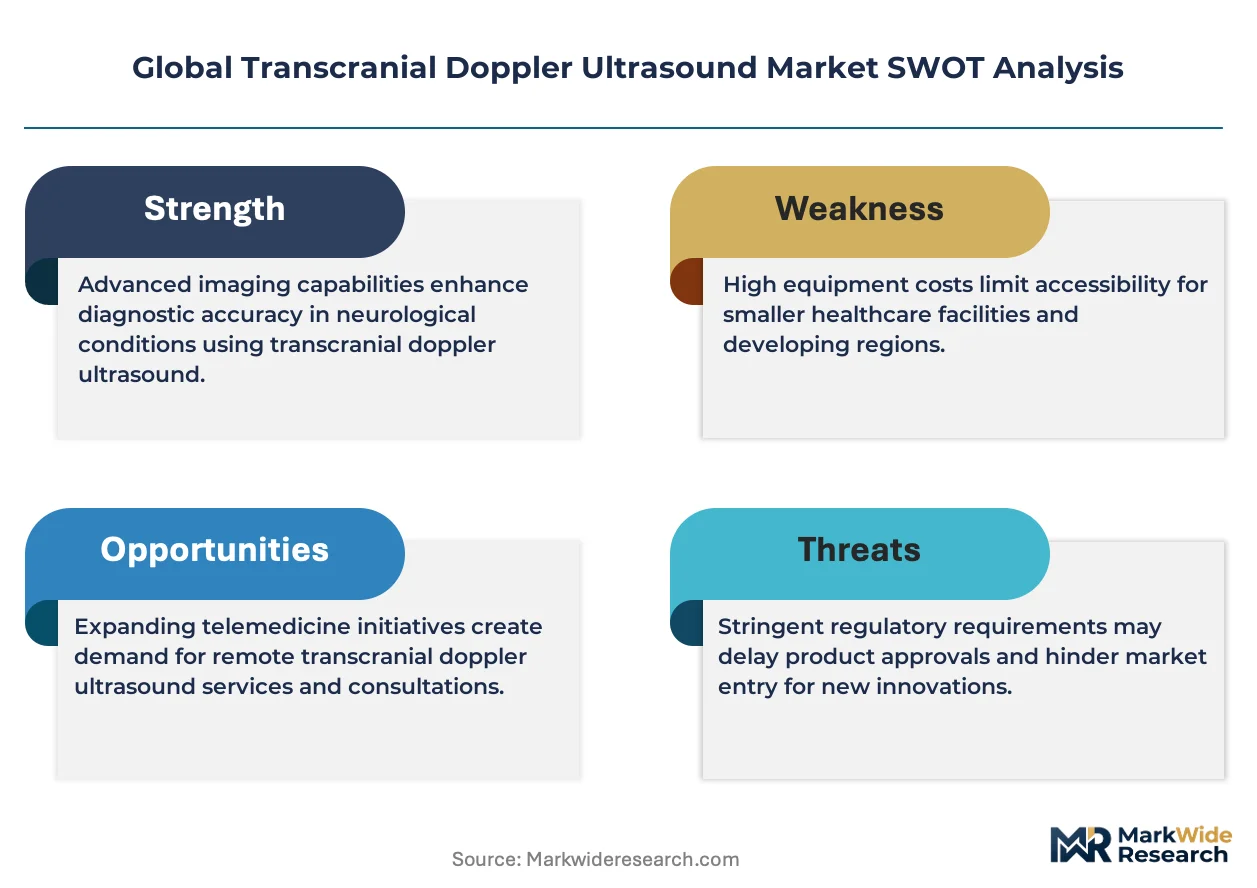
Portable TCD systems are compressing capital deployment cycles as neurology clinics bypass stationary console procurement in favor of bedside-deployable hardware with equivalent diagnostic fidelity.
Growth Catalysts
- EU MDR software validation mandates:Stricter documentation requirements for Class II medical devices are accelerating replacement of legacy systems with compliant next-generation platforms across German and French hospital networks.
- Japan's aging cerebrovascular patient pool:METI-supported diagnostic infrastructure investments in Tokyo and Osaka prefectures are expanding installed base for emboli detection systems in stroke centers.
- 2 MHz pulsed-wave signal processing:Advances in digital beamforming are enabling portable devices to match stationary console sensitivity for middle cerebral artery flow velocity measurement.
Market Restraints
- Piezoelectric transducer supply concentration:Single-source dependency on Japanese and German ceramic manufacturers creates input volatility for 2 MHz probe production.
- FDA 510(k) pathway friction:Extended software documentation requirements for AI-integrated Doppler interpretation are lengthening time-to-market for algorithm-enhanced systems.
- CT angiography substitution threat:Widespread availability of non-contrast CT perfusion in US emergency departments siphons triage volume from TCD-based stroke protocols.
Strategic Opportunities
- Remote neurovascular monitoring reimbursement:Evolving CPT code coverage for outpatient TCD services in the United States creates service revenue potential beyond hardware sales.
- AI-Doppler convergence:Integration of machine learning classification with spectral waveform analysis enables automated emboli counting without specialist interpretation.
- India's underpenetrated stroke infrastructure:CDSCO regulatory harmonization with ISO 13485 standards reduces entry barriers for portable systems in tier-2 city hospitals.
Industry Challenges
- Neurosonographer training scarcity:Specialized certification requirements for transcranial window acquisition and spectral interpretation constrain deployment velocity in community hospital settings.
- Legacy EMR integration complexity:DICOM compliance gaps between proprietary TCD software and hospital information systems demand costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcranial Doppler Ultrasound Market |
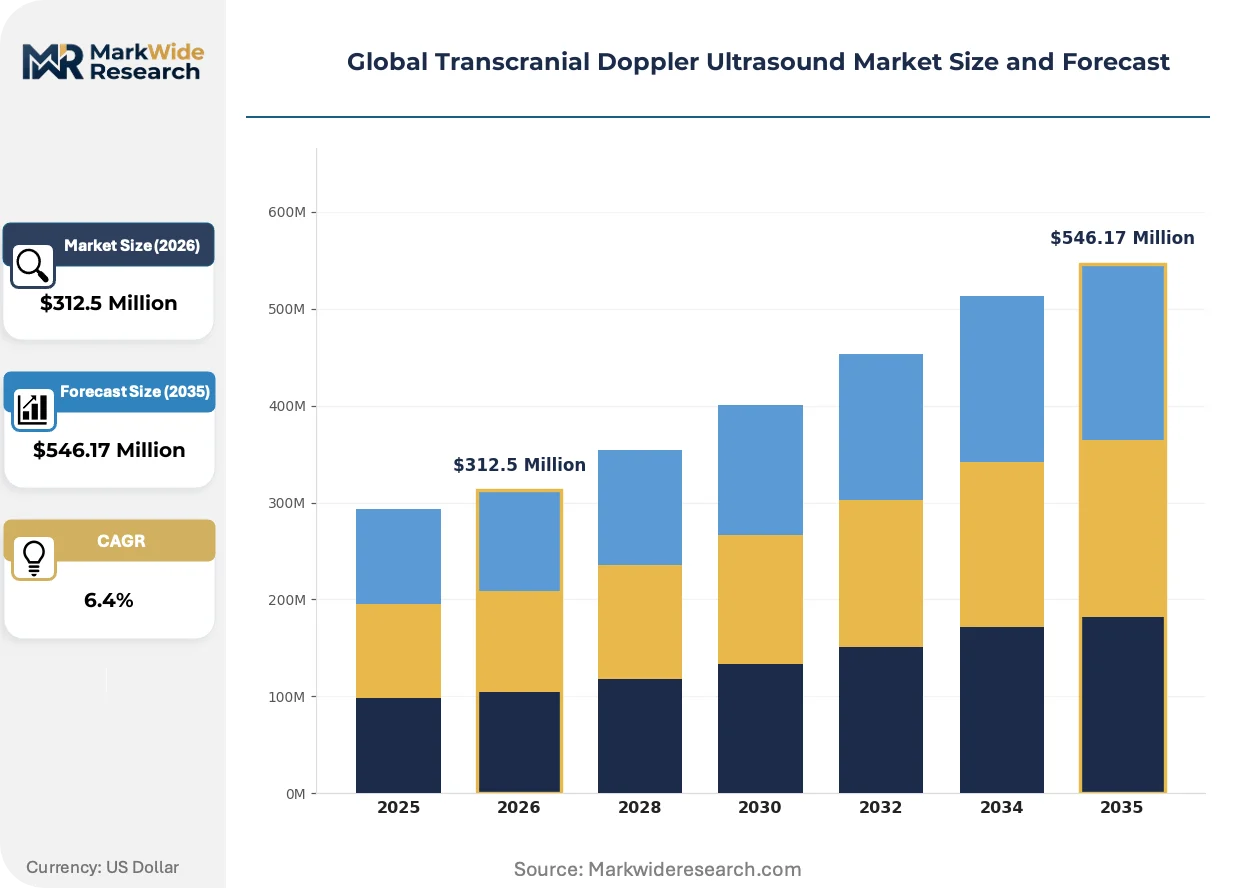
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
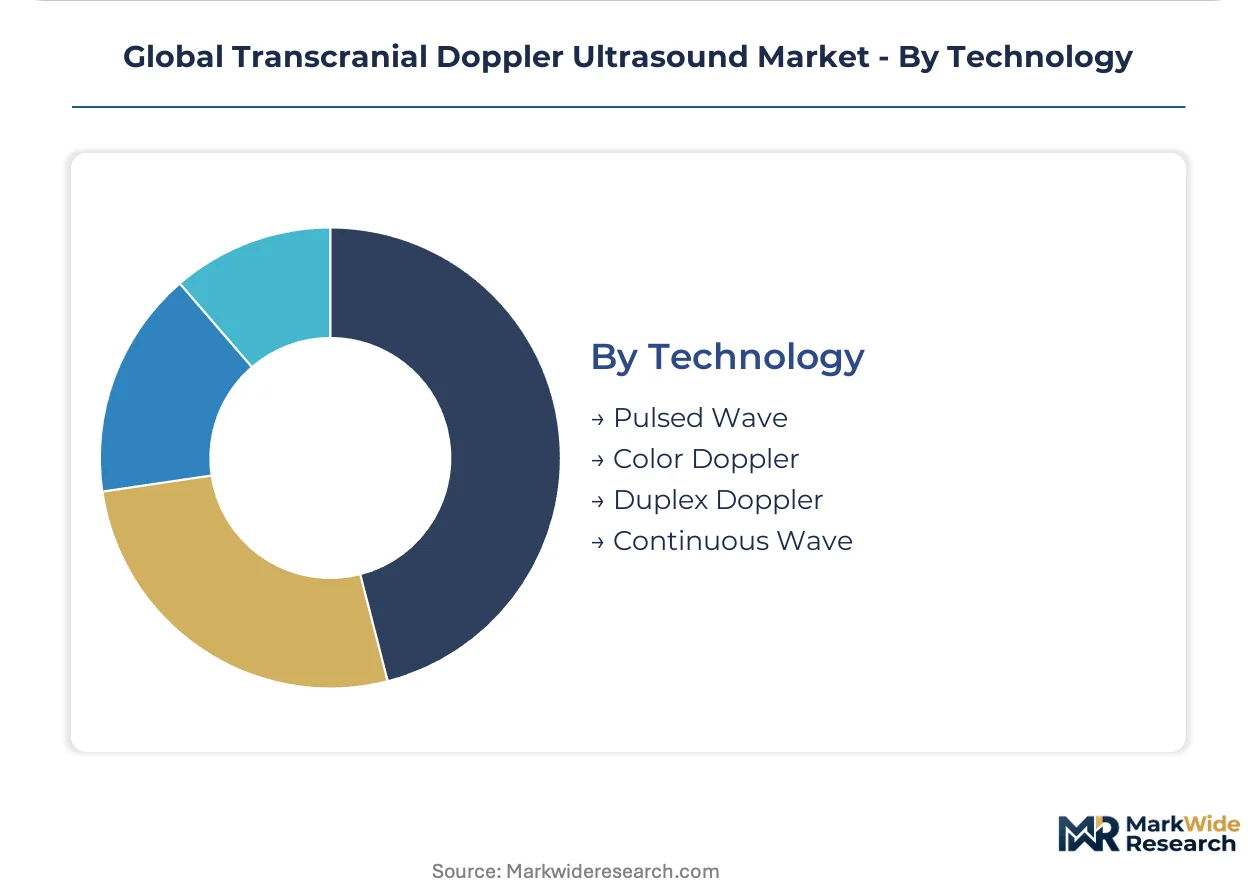
| Segmentation | Product Type: Portable, Stationary, Handheld, Console Application: Cerebral Blood Flow Monitoring, Stroke Diagnosis, Vasospasm Detection, Brain Death Assessment, Sickle Cell Disease Screening End User: Neurology Clinics, Diagnostic Centers, Research Institutes, Specialized Laboratories, Emergency Care Units Technology: Pulsed Wave, Color Doppler, Duplex Doppler, Continuous Wave |
| Companies Covered | Compumedics, Atys Medical, Viasonix, B. Braun, NovaSignal, Rimed, DWL Elektronische Systeme, Konica Minolta, Natus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcranial Doppler Ultrasound Market Shifts & Advancements
Signal processing automation and regulatory documentation digitization are compressing the gap between hardware acquisition and clinical deployment, while procurement patterns favor operational expenditure models over capital commitment.
Machine learning algorithms trained on spectral waveform libraries are automating emboli detection and microembolic signal classification. Academic stroke centers in the United States and Germany are piloting these systems to reduce dependency on fellowship-trained neurosonographers. The technology is automating routine screening workflows and enabling task-shifting to bedside nursing staff.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence documentation for software-as-medical-device components. Manufacturers serving European markets must maintain post-market surveillance systems with periodic safety update reports. CE-marked devices with integrated AI modules face heightened scrutiny of algorithm validation datasets.
Hospital procurement departments are unbundling service contracts from hardware acquisition, negotiating separate agreements for probe replacement and software maintenance. US health system buying consortia are driving this shift, using scale to compress multi-year service pricing. The pattern is most visible in integrated delivery networks consolidating stroke care across multiple sites.
Global Transcranial Doppler Ultrasound Market Segmentation
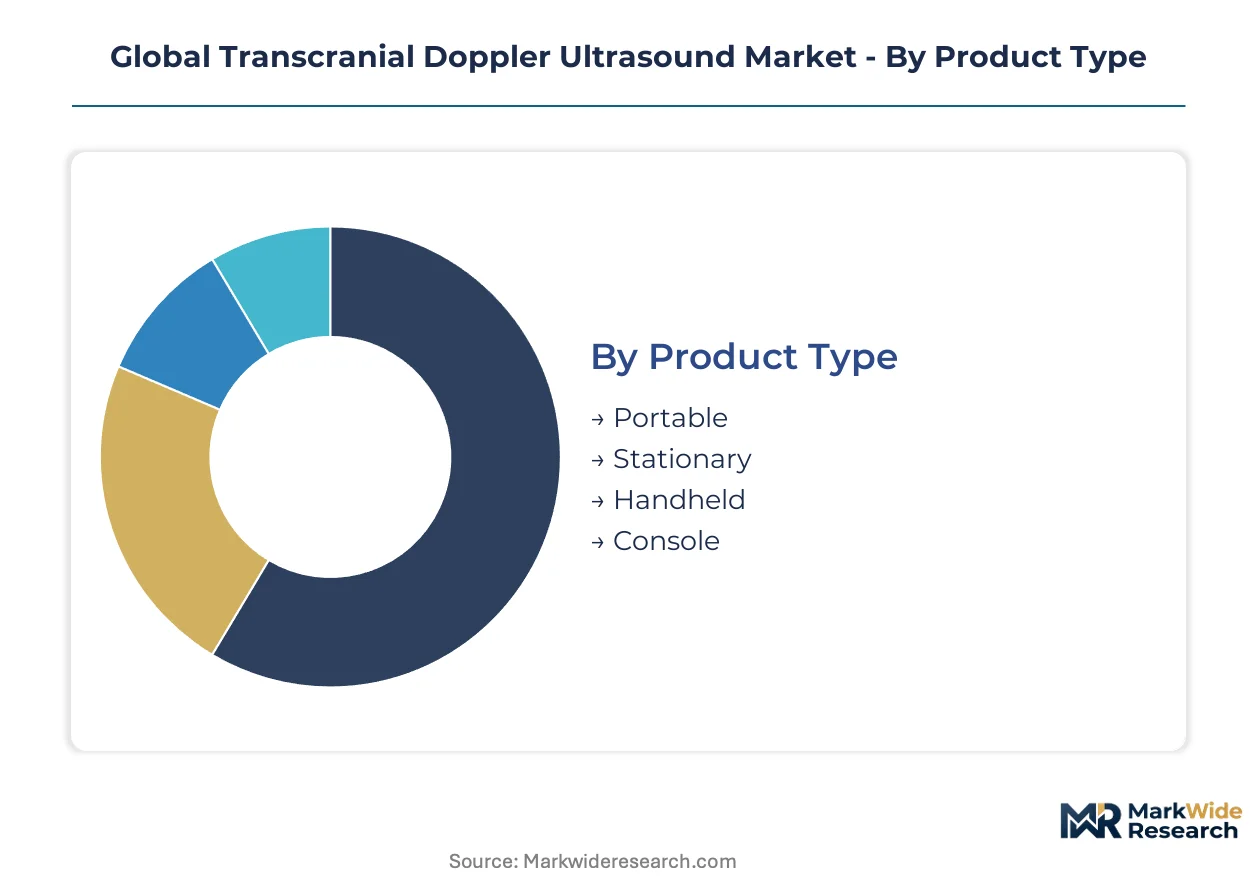
Transcranial Doppler ultrasound segments diverge sharply by deployment context: bedside units demand ruggedized portability and rapid boot sequences, while laboratory installations prioritize signal fidelity and multi-channel acquisition. Understanding these integration patterns clarifies why hardware specifications alone no longer determine competitive position.
Product Type:
Standalone units dominate acute care triage where immediate deployment outweighs integration complexity, whereas console-embedded systems anchor comprehensive cerebrovascular laboratories with centralized data management.
- Portable:Battery-powered units with 2 MHz pulsed-wave transducers enable point-of-care deployment in emergency departments and neurology wards. Demand concentrates in United States hospital networks where bedside stroke triage protocols bypass radiology department queues. These systems compress capital cycles and reduce per-procedure overhead.
- Stationary:Fixed-installation consoles with multi-depth sampling and automated M-mode display serve high-volume stroke centers in Germany and Japan. Clinical uptake depends on dedicated neurosonographer staffing and established reimbursement pathways for inpatient monitoring.
- Handheld:Smartphone-connected probes with simplified spectral display target resource-limited settings and community hospital screening programs.
- Console:Integrated workstation platforms with EMR connectivity and archival database management anchor academic medical center installations.
Stationary consoles lead volumes today; portable systems are gaining share fastest.
Application:
Diagnostic applications command premium hardware specifications and specialist interpretation, while screening workflows prioritize throughput and operator independence.
- Cerebral Blood Flow Monitoring:Continuous or intermittent measurement of middle cerebral artery velocity supports perioperative neuroprotection and traumatic brain injury management. Intensive care units in Japanese stroke centers drive demand for automated trend analysis and alarm integration.
- Stroke Diagnosis:Acute occlusion detection and collateral flow assessment guide thrombolysis decisions in emergency departments. United States hospitals with comprehensive stroke center certification represent the primary demand concentration.
- Vasospasm Detection:Daily velocity surveillance following subarachnoid hemorrhage requires consistent window acquisition and serial comparison protocols.
- Brain Death Assessment:Confirmatory flow pattern documentation for cerebral circulatory arrest follows strict institutional protocols in specialized neurocritical care units.
- Sickle Cell Disease Screening:Annual transcranial Doppler velocity measurement in pediatric populations identifies stroke risk in comprehensive sickle cell programs.
Stroke diagnosis anchors revenue today; cerebral blood flow monitoring shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement access separate institutional buyers, with hospital-integrated departments commanding volume discounts and standalone facilities facing capital constraints.
- Neurology Clinics:Outpatient cerebrovascular assessment programs require portable systems with rapid patient turnover and simplified billing integration. German ambulatory care networks expand adoption of handheld devices for carotid stenosis follow-up.
- Diagnostic Centers:High-throughput imaging facilities bundle TCD with carotid ultrasound and echocardiography for comprehensive stroke risk stratification. United States independent diagnostic testing facilities negotiate bundled reimbursement with regional payers.
- Research Institutes:Academic neuroscience programs demand research-grade signal export and customizable acquisition protocols for cerebral autoregulation studies.
- Specialized Laboratories:Dedicated neurovascular testing units in academic medical centers maintain legacy console installations for training and protocol standardization.
- Emergency Care Units:Pre-hospital and emergency department deployment prioritizes immediate usability and durability in uncontrolled environments.
Diagnostic centers lead volumes today; neurology clinics are climbing the fastest.
Technology:
Signal processing architecture determines whether systems operate as standalone diagnostic tools or require complementary imaging for anatomical correlation.
- Pulsed Wave:Range-gated sampling at selectable depths enables targeted insonation of specific cerebral arteries with spectral waveform display. Portable device manufacturers in Japan and Germany compete on digital beamforming algorithms that match console sensitivity.
- Color Doppler:Velocity-encoded overlay on B-mode anatomical images assists vessel identification in technically difficult windows. Academic stroke centers in the United States pilot these systems for neurosonographer training and quality assurance.
- Duplex Doppler:Combined grayscale imaging and spectral analysis commands premium positioning in comprehensive cerebrovascular laboratories with established reimbursement for combined diagnostic procedures.
- Continuous Wave:Unrange-gated velocity detection without anatomical localization serves screening applications and brain death confirmation where depth specificity is unnecessary.
Duplex Doppler leads volumes today; pulsed wave portable implementations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurosonographer training programs in the United States anchor the largest concentration of clinical expertise for transcranial Doppler interpretation. German engineering clusters sustain precision transducer manufacturing. Japanese metropolitan stroke centers drive protocol standardization for acute cerebrovascular assessment.
United States
Comprehensive stroke center certification requirements drive demand for duplex Doppler systems in emergency departments. FDA 510(k) clearance pathways shape software validation timelines for AI-integrated devices. The Texas Medical Center in Houston anchors one of the highest-volume neurovascular monitoring installations nationwide.
Germany
Established reimbursement for inpatient cerebrovascular monitoring sustains stationary console procurement across university hospital networks. EU MDR conformity requirements accelerate replacement of legacy systems with compliant platforms. The Munich-Stuttgart corridor concentrates specialized vasospasm detection protocol development.
Japan
METI-supported diagnostic infrastructure investments expand emboli detection system deployment in Tokyo and Osaka prefecture stroke centers. PMDA regulatory harmonization with ISO 13485 standards streamlines market access for portable device manufacturers. The Kansai region anchors high-volume cerebral blood flow monitoring for perioperative neuroprotection.
India
CDSCO regulatory alignment with international quality management standards reduces entry barriers for portable systems in tier-2 city hospitals. National stroke program expansion creates demand for handheld devices in resource-limited settings. Maharashtra and Karnataka state medical colleges pilot task-shifted TCD screening for pediatric sickle cell populations.
United Kingdom
NHS England specialized commissioning frameworks concentrate neurovascular diagnostic capacity in designated stroke centers. MHRA post-market surveillance requirements influence software documentation practices for CE-marked devices. The Oxford-Cambridge-London research triangle anchors academic validation studies for automated spectral interpretation algorithms.
Global Transcranial Doppler Ultrasound Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the transcranial Doppler ultrasound landscape. The vendor base separates between integrated medical technology conglomerates and specialized cerebrovascular equipment developers. Three archetypes dominate: diversified diagnostic imaging platforms, focused neurovascular monitoring specialists, and emerging AI-native workflow disruptors. Consolidation pressure favors portfolio diversification through technology licensing and strategic distribution partnerships over direct manufacturing expansion.
Within the neurovascular specialist tier, Viasonix and DWL Elektronische Systeme exemplify sustained European engineering positioning, while NovaSignal occupies a position at the AI-Doppler convergence frontier. Konica Minolta represents diversified imaging platform leverage into cerebrovascular applications. These three anchors illustrate how competitive differentiation increasingly depends on signal processing automation rather than transducer hardware specifications alone.
| Leading Market Players |
|---|
| Compumedics |
| Atys Medical |
| Viasonix |
| B. Braun |
| NovaSignal |
| Rimed |
| DWL Elektronische Systeme |
| Konica Minolta |
| Natus Medical |
| Others |
Supply & Pricing Matrix
Digital beamforming migration in portable 2 MHz systems is compressing manufacturing economies while concentrating probe assembly expertise in Japanese and German ceramic facilities. This technological shift simultaneously elevates software value-capture in final system pricing and deepens dependency on single-source piezoelectric suppliers.
Pricing Analysis
The bundled-vs-unbundled service split now defines transaction structures across hospital procurement. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated consoles from basic portable units and handheld screening probes. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification depth. Cost compression in economy handhelds is intensifying because CDSCO harmonization invites Indian manufacturing entrants. Community hospitals in tier-2 Indian cities exhibit highest price sensitivity; academic stroke centers in Germany and Japan show lowest.
Supply Chain Analysis
Reverse logistics flows for probe refurbishment and transducer remanufacturing are expanding as US health system consortia negotiate extended service lifecycles. Manufacturing concentrates in Japan, Germany, and the United States for piezoelectric ceramics, signal processing chipsets, and precision acoustic housings. Component sourcing draws from specialized 2 MHz crystal growers, medical-grade FPGA suppliers, and electromagnetic shielding fabricators. Single-source vulnerability in Japanese ceramic substrates poses structural risk. Distribution runs through regional medical device distributors with GPO contracts in US hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by demand migration toward AI-validated spectral interpretation and automated emboli detection workflows.
For Market Incumbents: Hedge against CT angiography substitution by embedding Doppler systems into comprehensive stroke center certification bundles. Deepen backward integration into probe manufacturing to offset Japanese ceramic supply volatility. Prioritize EU MDR software documentation investment to accelerate legacy system replacement cycles in German hospital networks. For New Entrants and Emerging Players: Launch via smartphone-connected handheld distribution targeting India's tier-2 stroke infrastructure expansion. White-space concentrates in pediatric sickle cell screening programs and task-shifted community hospital deployment. Penetrate through CDSCO-fast-tracked portable systems with simplified spectral displays for nursing staff operation. For Investors and Strategic Acquirers: Valuations sit cheapest among AI-native workflow disruptors with FDA 510(k) submissions pending but no installed base. Long-term viability centers on software-as-medical-device revenue durability beyond hardware replacement cycles. Target acquisition profile: neurovascular specialists with proprietary digital signal processing libraries. Monitor PMDA regulatory harmonization progress as inflection indicator for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Software Development | Automated emboli detection reduces neurosonographer dependency in US stroke centers. |
| EU MDR Compliance Pathway | CE marking with Annex I clinical evidence documentation unlocks German hospital replacement demand. |
| Portable System Distribution Partnership | Bedside deployment contracts with Indian state medical colleges bypass capital procurement cycles. |
| Probe Manufacturing Scale-Up | In-house 2 MHz transducer production insulates against Japanese ceramic supply concentration. |
| Remote Monitoring Reimbursement Strategy | CPT code coverage expansion for outpatient TCD services creates US service revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged stroke neurologists, hospital biomedical engineers, GPO contracts managers, and neurosonography training program directors. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and Japanese METI diagnostic infrastructure investment disclosures. Bottom-up installed base estimates triangulated against top-down cerebrovascular procedure volume projections.
Segment-weighting distributed value across portable, stationary, handheld, and console product architectures. Application-level modeling incorporated cerebral blood flow monitoring, stroke diagnosis, vasospasm detection, brain death assessment, and sickle cell screening protocols. Technology tiers separated pulsed-wave, color Doppler, duplex Doppler, and continuous-wave implementations. CAGR derivation anchored in procedure volume elasticity to stroke center certification expansion and aging demographic penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software validation timeline extensions or EU MDR notified body capacity constraints. Forecasts reflect assumptions regarding reimbursement code stability and ceramic supply continuity. Practitioners should monitor PMDA regulatory harmonization announcements and US comprehensive stroke center certification velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Spain Cardiovascular Devices Market