
 Organ Function Assays Market | 2026-2036
Organ Function Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Function Assays Market Analytics
Hospital procurement of organ function assays is collapsing as diagnostic laboratories capture greater volume share through centralized testing networks. Roche Diagnostics leverages its installed base of immunoassay analyzers to sustain recurring revenue streams across major health systems. Abbott Laboratories anchors its position through point-of-care cardiac marker platforms that bypass traditional lab workflows. Siemens Healthineers competes on integrated liver and kidney panels delivered through automated laboratory lines.
Organ function assays comprise quantitative biochemical, immunoassay, and molecular diagnostic methods that measure biomarkers indicating physiological performance of the liver, kidney, heart, and lungs, typically requiring serum or plasma samples analyzed through spectrophotometric, electrochemical, or fluorescence-based detection systems with turnaround times ranging from minutes to hours depending on platform complexity. Their primary purpose is to enable clinicians to detect organ injury, monitor chronic disease progression, and guide therapeutic interventions before irreversible damage occurs. Liver function tests dominate current revenue given the prevalence of metabolic and viral etiologies requiring routine monitoring, while molecular diagnostics represents the fastest-expanding technology segment as nucleic acid amplification methods penetrate transplant rejection surveillance and pharmacogenomic applications. Point-of-care testing commands premium pricing in emergency and perioperative settings where rapid clinical decision-making outweighs laboratory economies of scale.
The FDA governs assay analytical validity and clinical performance claims through its in vitro diagnostic framework, while the Clinical Laboratory Improvement Amendments set proficiency standards that shape product design for decentralized use. The European Medicines Agency and In Vitro Diagnostic Regulation impose post-market surveillance obligations that extend compliance costs for multi-market suppliers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as home-based assay adoption accelerates outside traditional clinical settings.
Market Dynamics
Centralized laboratory networks are consolidating testing volumes away from hospital-based labs, forcing assay manufacturers to reconfigure distribution and service models around high-throughput automated platforms rather than fragmented point-of-care deployments.
Growth Catalysts
- Chronic Disease Surveillance Intensification:Health systems in the United States are expanding liver and kidney panel testing protocols for diabetes and metabolic syndrome populations, driving recurring reagent consumption through installed chemistry analyzers.
- IVDR Compliance Deadlines:The European Union's In Vitro Diagnostic Regulation mandates enhanced clinical evidence for Class C and D devices, accelerating replacement cycles for legacy assays with validated next-generation platforms.
- Transplant Pharmacogenomics:Molecular HLA typing and drug metabolism genotyping are penetrating post-transplant monitoring protocols, opening specialized assay segments with premium pricing power.
Market Restraints
- Reagent Supply Concentration:Critical enzyme and antibody inputs for liver enzyme assays depend on concentrated biologics manufacturing in Germany and Switzerland, exposing the supply chain to single-source vulnerabilities.
- Capital Intensity of Automation:Laboratory information system integration and track-based sample handling require seven-figure infrastructure commitments that freeze mid-tier hospital labs out of competitive bidding.
- Reimbursement Compression:CMS clinical laboratory fee schedule reductions in the United States are squeezing margins on routine chemistry panels, forcing volume concessions or test menu rationalization.
Strategic Opportunities
- Home-Based Renal Monitoring:Remote patient monitoring codes in the United States are enabling capitated kidney care models to deploy patient-operated creatinine and eGFR testing outside traditional lab settings.
- AI-Assisted Interpretation:Machine learning algorithms trained on multi-biomarker patterns are converging with cloud-connected analyzers to differentiate acute from chronic organ injury with reduced specialist oversight.
- Point-of-Care Cardiac Expansion:Emergency departments in India are adopting handheld natriuretic peptide assays to bypass centralized lab turnaround constraints in acute heart failure triage.
Industry Challenges
- LIS Integration Complexity:Middleware compatibility with legacy laboratory information systems from multiple vendors consumes 12-18 month implementation timelines, delaying platform conversions.
- Specialized Field Service Scarcity:Electromechanical troubleshooting for integrated chemistry-immunoassay lines requires hybrid skill sets combining biochemistry and robotics expertise that training pipelines have not scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Function Assays Market |
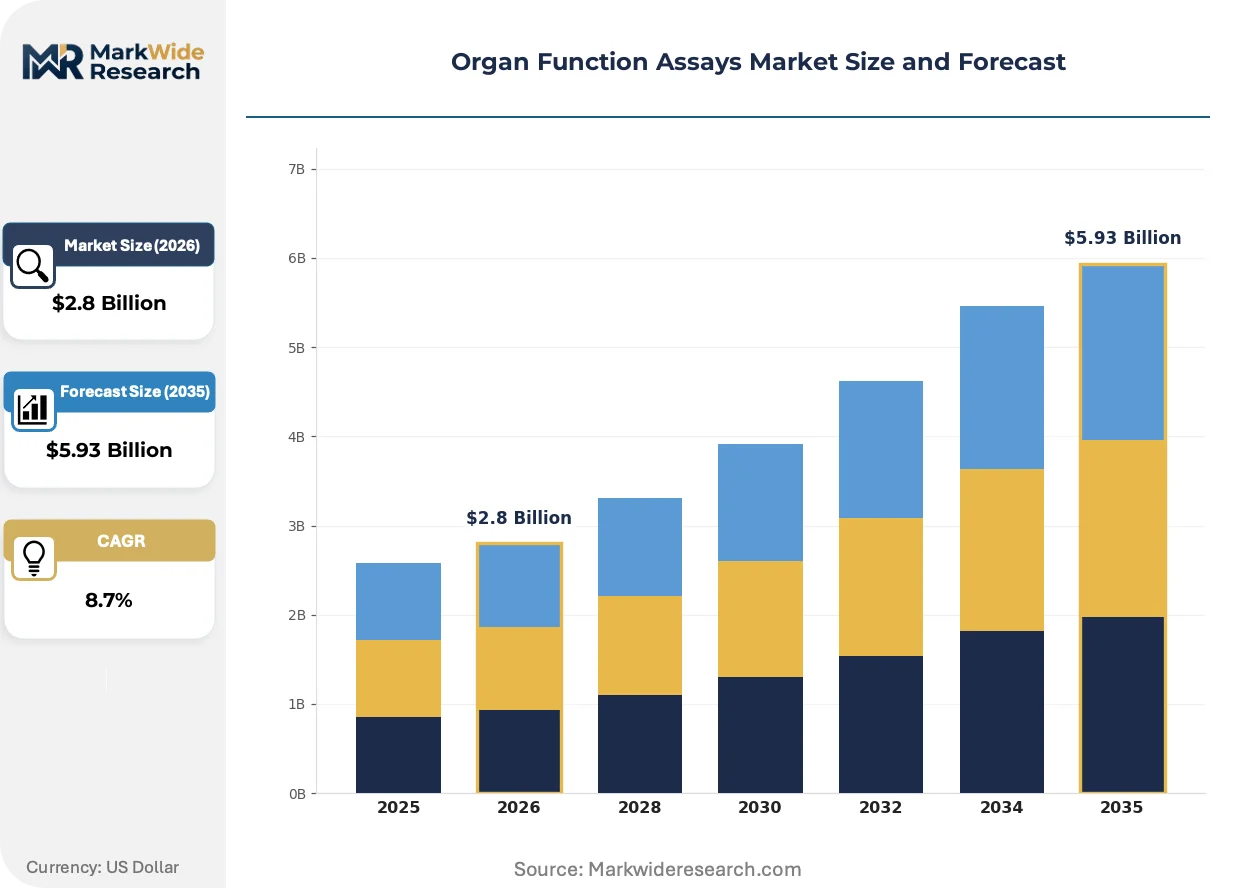
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liver Function Tests, Kidney Function Tests, Heart Function Tests, Lung Function Tests Technology: Biochemical Assays, Immunoassays, Molecular Diagnostics, Flow Cytometry End User: Hospitals, Diagnostic Laboratories, Research Institutions, Homecare Delivery Mode: Point-of-Care Testing, Laboratory Testing, Remote Monitoring, Traditional Testing |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Danaher, Thermo Fisher Scientific, Nova Biomedical, Horiba Medical, Randox Laboratories, Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Function Assays Market Evolving Landscape
Assay platforms are fragmenting into two distinct performance tiers—high-throughput laboratory automation versus distributed rapid testing—each demanding incompatible engineering and commercial architectures from suppliers.
Multiplexed molecular panels combining donor-derived cell-free DNA with traditional protein biomarkers are bifurcating transplant rejection surveillance into centralized reference laboratory workflows versus hospital-based stat testing, with academic medical centers in the United States and Germany adopting the former while community hospitals favor the latter for cost containment.
Japan's Pharmaceuticals and Medical Devices Agency has tightened analytical performance requirements for troponin assays used in acute coronary syndrome diagnosis, compelling manufacturers to demonstrate 99th percentile precision at the lower detection limit and driving consolidation toward platforms with documented six-sigma quality control.
Integrated health networks in the United States are unbundling equipment procurement from reagent supply agreements, forcing manufacturers to compete on per-test economics through competitive bidding rather than capital placement strategies that previously locked in long-term volume commitments.
Organ Function Assays Market Segmentation
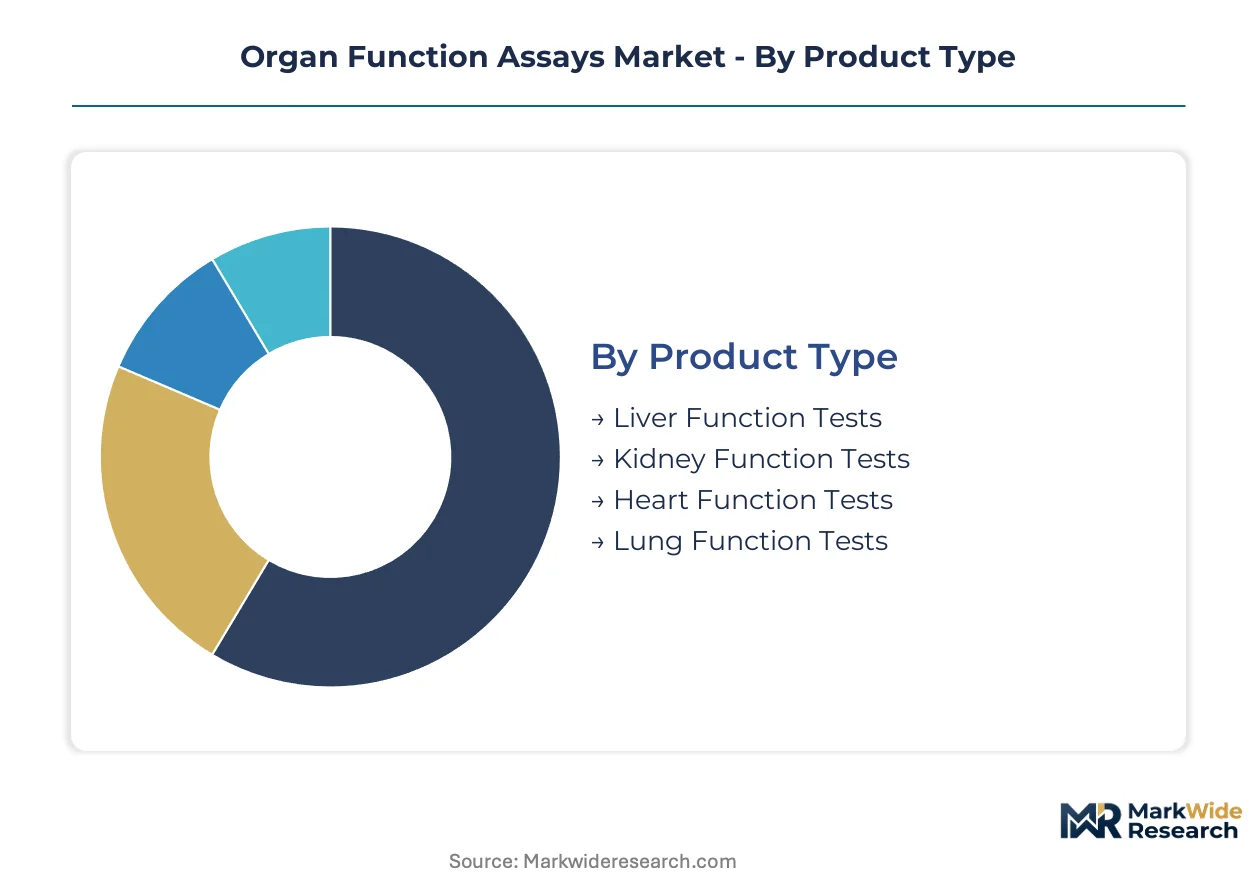
Segmentation in the Organ Function Assays Market reveals how regulatory pathways, clinical workflows, and reimbursement structures shape procurement decisions across distinct product and technology categories. Understanding these divisions enables manufacturers to align platform development with specific validation requirements and end-use economics.
Product Type:
FDA and EMA validation pathways diverge sharply across organ-specific panels, with liver and kidney assays facing lower evidentiary bars than cardiac biomarkers used in acute coronary syndrome diagnosis.
- Liver Function Tests:These panels measure serum enzymes including ALT, AST, alkaline phosphatase, and bilirubin through spectrophotometric methods. Demand concentrates in United States integrated health networks expanding metabolic syndrome monitoring protocols, though reagent supply concentration in German and Swiss biologics manufacturing creates vulnerability.
- Kidney Function Tests:Creatinine, BUN, and eGFR calculations dominate routine chemistry analyzer menus. Homecare adoption is accelerating fastest in United States capitated kidney care models leveraging remote patient monitoring reimbursement codes.
- Heart Function Tests:Troponin and natriuretic peptide assays command premium pricing in emergency settings. Japan's PMDA has tightened analytical performance requirements for high-sensitivity troponin platforms.
- Lung Function Tests:Pulmonary biomarker panels remain less standardized than other organ categories, with diffusion capacity and arterial blood gas measurements requiring specialized equipment.
Established volume favors Liver Function Tests; emerging adoption favors Kidney Function Tests.
Technology:
Capital intensity and regulatory classification separate mature biochemical methods from emerging molecular platforms requiring specialized infrastructure and expertise.
- Biochemical Assays:Spectrophotometric and electrochemical detection systems anchor installed chemistry analyzer bases. United States hospital consolidation is driving replacement toward integrated platforms with track-based sample handling.
- Immunoassays:Sandwich and competitive binding formats on automated analyzers generate recurring reagent revenue. EMA's IVDR compliance deadlines are accelerating replacement cycles for legacy platforms.
- Molecular Diagnostics:Nucleic acid amplification methods for HLA typing and pharmacogenomic applications are gaining share fastest in transplant rejection surveillance. United States academic medical centers and German reference laboratories lead centralized adoption.
- Flow Cytometry:Cell-based functional assays serve specialized transplant monitoring and immunology applications requiring dedicated operator training.
Biochemical Assays capture current test volume; Molecular Diagnostics commands steepest expansion trajectory.
End User:
Procurement authority is shifting from hospital-based laboratories toward centralized networks and emerging home-based models.
- Diagnostic Laboratories:High-throughput automated platforms with seven-figure infrastructure commitments dominate volume consolidation. United States health system centralization is freezing mid-tier hospital labs from competitive bidding.
- Hospitals:Point-of-care deployments in emergency and perioperative settings prioritize rapid turnaround over per-test economics. India's emergency departments are adopting handheld cardiac marker assays to bypass centralized lab constraints.
- Research Institutions:Multiplexed molecular panels and specialized pharmacogenomic applications drive demand in academic medical centers.
- Homecare:Patient-operated renal monitoring devices are penetrating United States capitated care models under remote patient monitoring reimbursement frameworks.
Diagnostic Laboratories consolidate procurement authority; Homecare represents the fastest-climbing adoption curve.
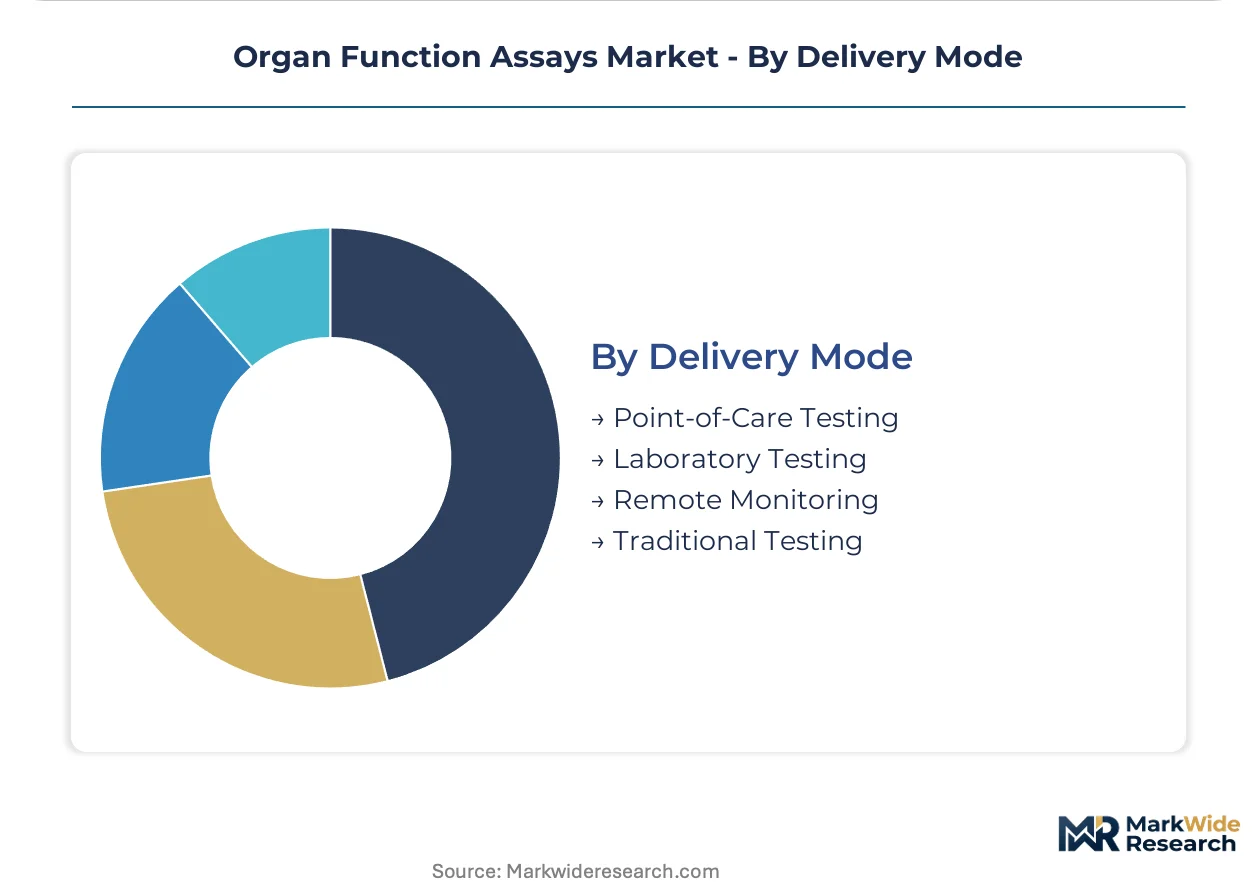
Delivery Mode:
Turnaround requirements and reimbursement structures create incompatible economic models across centralized and distributed testing architectures.
- Laboratory Testing:Automated chemistry-immunoassay lines with integrated track handling deliver economies of scale for routine panels. Middleware compatibility with legacy laboratory information systems consumes 12-18 month implementation timelines.
- Point-of-Care Testing:Handheld and cartridge-based platforms command premium pricing where clinical decision speed outweighs laboratory efficiency. Emergency departments and perioperative settings drive demand concentration.
- Remote Monitoring:Cloud-connected home-based devices with AI-assisted interpretation are emerging in United States renal care models. Reimbursement code evolution shapes commercial viability.
- Traditional Testing:Manual bench methods persist in resource-constrained settings lacking capital for automation infrastructure.
Laboratory Testing retains volume dominance; Remote Monitoring is gaining share fastest outside traditional clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain logistics infrastructure underwrites European distribution of temperature-sensitive reagents, while the United States leverages its integrated health network density to concentrate procurement authority.
United States
Integrated health networks in Texas and Florida are consolidating liver and kidney panel testing through centralized laboratory networks. CMS clinical laboratory fee schedule revisions are compressing margins on routine chemistry assays. The Research Triangle Park cluster in North Carolina anchors molecular diagnostics development for transplant pharmacogenomics applications.
Germany
Bavarian biologics manufacturers supply critical enzyme inputs for liver enzyme assays across European markets. EMA's IVDR compliance deadlines are accelerating replacement cycles for legacy immunoassay platforms. The Munich-Stuttgart corridor hosts automated chemistry analyzer production facilities serving diagnostic laboratory networks.
Japan
Acute coronary syndrome diagnosis protocols drive demand for high-sensitivity troponin platforms in Tokyo and Osaka medical centers. PMDA has tightened analytical performance requirements for cardiac biomarker assays at the 99th percentile detection limit. The Kobe biomedical cluster specializes in fluorescence-based detection system manufacturing.
India
Emergency departments in Mumbai and Delhi are adopting handheld natriuretic peptide assays to bypass centralized laboratory turnaround constraints. CDSCO diagnostic device registration pathways are streamlining point-of-care platform approvals. The Hyderabad pharmaceutical corridor is incubating local assay reagent manufacturing capabilities.
Switzerland
Swissmedic oversight of in vitro diagnostic quality standards shapes product validation for multi-market suppliers. Basel and Zurich host concentrated antibody production facilities serving global immunoassay manufacturers. The country's precision manufacturing base supports electrochemical detection component supply chains.
Organ Function Assays Market Competitive Landscape
Listed leaders compete with private specialists across reagent supply and platform automation dimensions, producing a tiered structure where scale-driven conglomerates anchor high-throughput laboratory segments while mid-cap specialists occupy point-of-care niches. Three archetypes dominate: diversified diagnostics conglomerates with installed analyzer bases, biologics-focused reagent suppliers with concentrated manufacturing assets, and point-of-care platform specialists with handheld cartridge expertise. Competitive moves center on unbundling equipment procurement from reagent supply agreements and backward integration into critical antibody manufacturing.
Among diversified diagnostics conglomerates, Abbott Laboratories exemplifies the point-of-care cardiac marker platform archetype, while Roche Diagnostics occupies a position representing installed-base immunoassay analyzer leverage. Siemens Healthineers anchors the integrated liver and kidney panel automation tier, with its German corporate structure reflecting the European manufacturing concentration visible across the competitive set.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Danaher |
| Thermo Fisher Scientific |
| Nova Biomedical |
| Horiba Medical |
| Randox Laboratories |
| Laboratory Corporation of America Holdings |
| Others |
Value Network & Pricing Analysis
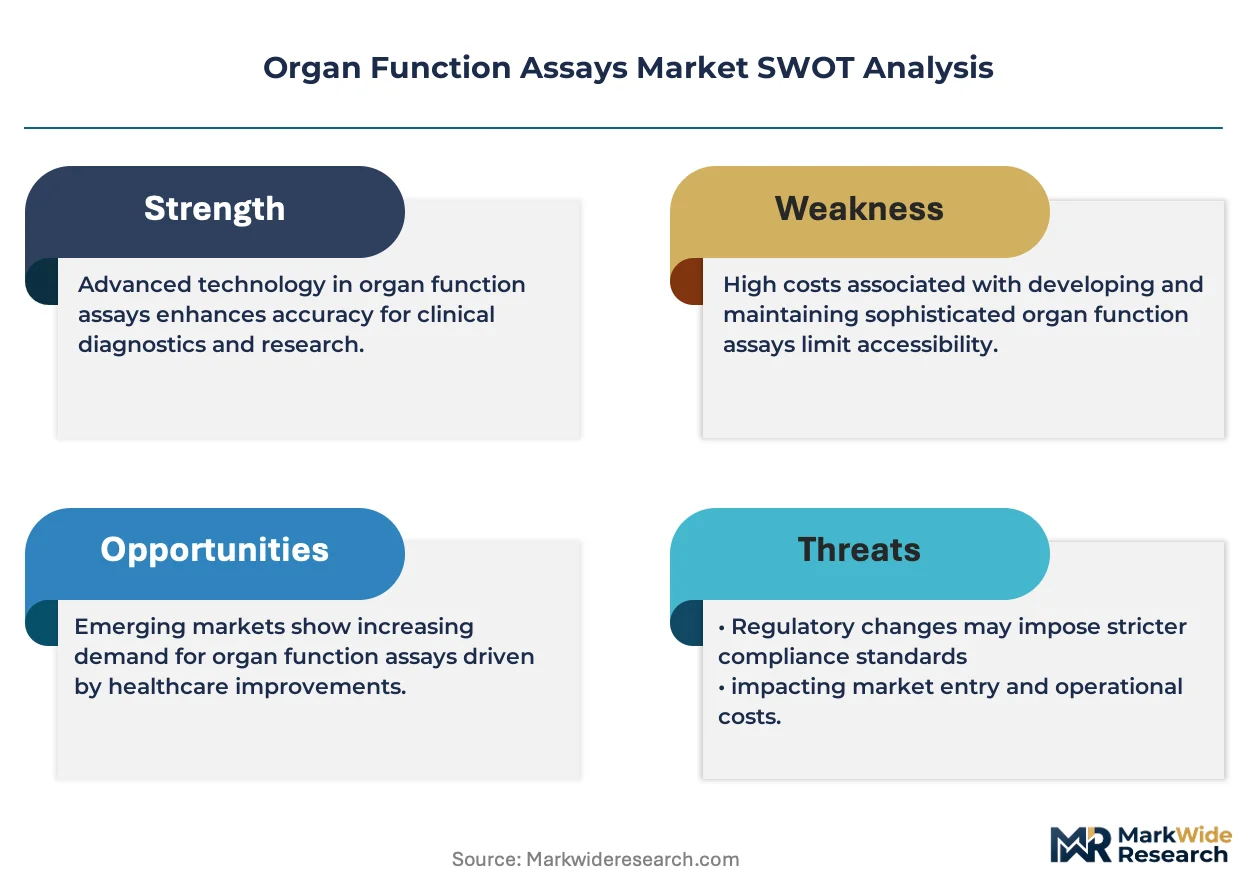
FDA's in vitro diagnostic framework gates both supply qualification and price differentiation simultaneously, as Class C and D device classifications impose clinical evidence requirements that stratify manufacturers into premium-validated tiers versus economy-positioned alternatives. The resulting market structure rewards platforms with documented analytical validity while compressing margins for undifferentiated biochemical assays.
Pricing Analysis
Volume-discount tiering structures dominate procurement between integrated health networks and assay manufacturers, with three-tier pricing separating high-sensitivity cardiac platforms from standard chemistry panels and economy-positioned reagent bundles. Price differentiation rests on FDA validation tier and installed-base lock-in, with premium tiers capturing emergency department point-of-care deployments. Cost compression in routine liver and kidney panels is intensifying because CMS fee schedule reductions squeeze per-test economics. Mid-tier hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize analytical performance over per-unit cost.
Supply Chain Analysis
Inventory lead times for critical enzyme inputs extend 12-16 weeks due to concentrated biologics manufacturing in Germany and Switzerland. Geographic supply concentration centers on Bavarian fermentation facilities for ALT/AST reagents, Swiss antibody production for immunoassay components, and Japanese fluorescence detection module assembly. Raw material dependencies include recombinant enzymes, monoclonal antibodies, and electrochemical sensor substrates. Single-source vulnerability in German enzyme manufacturing exposes the supply chain to regulatory inspection disruptions. Distribution runs through cold-chain logistics networks anchored at Rotterdam for European markets and Memphis for North American fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as IVDR compliance deadlines in Europe force replacement cycles for legacy immunoassay platforms, generating sustained reagent demand through validated next-generation systems.
For Market Incumbents: Fortify installed-base positions through backward integration into critical antibody manufacturing, reducing exposure to Swiss supply concentration. Deepen field service capabilities in hybrid biochemistry-robotics expertise to defend against mid-tier automation competitors. Prioritize LIS middleware certification investments that compress 12-18 month implementation timelines and accelerate platform conversions. For New Entrants and Emerging Players: Anchor in India's point-of-care cardiac segment, where CDSCO streamlines handheld natriuretic peptide approvals and emergency departments bypass centralized lab constraints. Target United States home-based renal monitoring white space enabled by remote patient monitoring reimbursement codes. Pursue capitated kidney care model partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: EMA's IVDR implementation reshapes the acquisition landscape toward platforms with validated clinical evidence packages. Long-term viability favors molecular diagnostics specialists with transplant pharmacogenomics capabilities over commodity biochemical assay manufacturers. Monitor FDA guidance evolution on AI-assisted biomarker interpretation as the critical inflection signal for platform differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Acceleration | EMA deadlines force replacement of legacy immunoassay platforms with validated next-generation systems. |
| Home-Based Renal Monitoring Deployment | United States capitated care models leverage remote patient monitoring codes for patient-operated creatinine testing. |
| AI-Assisted Interpretation Integration | Machine learning algorithms differentiate acute from chronic organ injury through cloud-connected analyzer platforms. |
| Point-of-Care Cardiac Expansion | Indian emergency departments adopt handheld natriuretic peptide assays to bypass centralized laboratory turnaround. |
| Antibody Manufacturing Backward Integration | Swiss and German biologics concentration drives captive production strategies for critical immunoassay inputs. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, hospital procurement committees, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, CMS clinical laboratory fee schedules, and hospital procurement databases. Bottom-up test volume modeling triangulated against top-down market sizing across instrument placements and reagent consumption curves.
Sensitivity analysis framed the quantitative approach across the projection horizon, with segmentation dimensions spanning organ panel type, technology platform, delivery mode, and end-user setting. CAGRs derived from installed-base expansion rates, replacement cycle timing, and reimbursement trajectory assumptions. Forecast inputs incorporated IVDR compliance deadline phasing, remote patient monitoring code evolution, and transplant pharmacogenomics penetration curves.
Decision-makers should treat outputs as directional under sustained chronic disease surveillance intensification and centralized laboratory network consolidation; material deviation in reimbursement policy or regulatory timeline would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Lab Mailers Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market