
 Asia Pacific Interventional Cardiology Market | 2026-2036
Asia Pacific Interventional Cardiology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Interventional Cardiology Market Analysis
Buyer concentration among hospital procurement consortia is realigning vendor relationships across the Asia Pacific interventional cardiology landscape. Abbott Laboratories leverages its structural heart portfolio to anchor premium catheter positions in Australian tertiary centers. Medtronic plc competes through geographic dominance in Japan's reimbursed stent segment, where PMDA-approved drug-eluting platforms sustain recurring revenue. Terumo Corporation differentiates via guidewire specialization and manufacturing scale across Southeast Asian distribution channels.
Interventional cardiology encompasses minimally invasive catheter-based procedures to diagnose and treat coronary, peripheral, and structural heart conditions, utilizing balloon-expandable devices typically constructed from cobalt-chromium or platinum-iridium alloys and drug-polymer matrices eluting antiproliferative agents. Balloon catheters and drug-eluting stents command the largest installed base, while bioresorbable stent technology represents the fastest-advancing segment despite limited reimbursement in emerging Asian markets. Optical coherence tomography guidance systems concentrate margin pools in Japan and South Korea, where hospital capital budgets prioritize intravascular imaging integration.
Japan's PMDA, Australia's TGA, and China's NMPA enforce divergent clinical evidence requirements that fragment product registration timelines and shape regional launch sequencing for device manufacturers. India's CDSCO accelerates coronary stent approvals through abbreviated pathways, though price controls compress margins for multinational suppliers relative to domestic competitors like Lepu Medical Technology and MicroPort Scientific Corporation. Stakeholders must monitor reimbursement harmonization efforts across ASEAN markets, where divergent public health financing models determine adoption velocity for next-generation interventional platforms.
Market Dynamics
Hospital procurement consortia across Asia Pacific are consolidating vendor relationships, forcing device manufacturers to restructure pricing and service architectures around multi-year supply agreements rather than transactional sales.
Growth Catalysts
- CDSCO abbreviated pathways:India's streamlined coronary stent approvals compress registration timelines for drug-eluting platforms, accelerating market entry relative to full clinical trial requirements.
- Tier-one city cath lab expansion:Public hospital procurement volumes in Shanghai, Beijing, and Guangzhou anchor regional demand for balloon-expandable devices and intravascular imaging systems.
- PMDA drug-eluting preference:Japan's reimbursement framework systematically favors antiproliferative agent matrices over bare-metal alternatives, sustaining recurring platform upgrades.
Market Restraints
- Cobalt-chromium alloy supply concentration:Specialty metallurgy for stent platforms depends on limited Japanese and German precision forging capacity, exposing manufacturers to input bottlenecks.
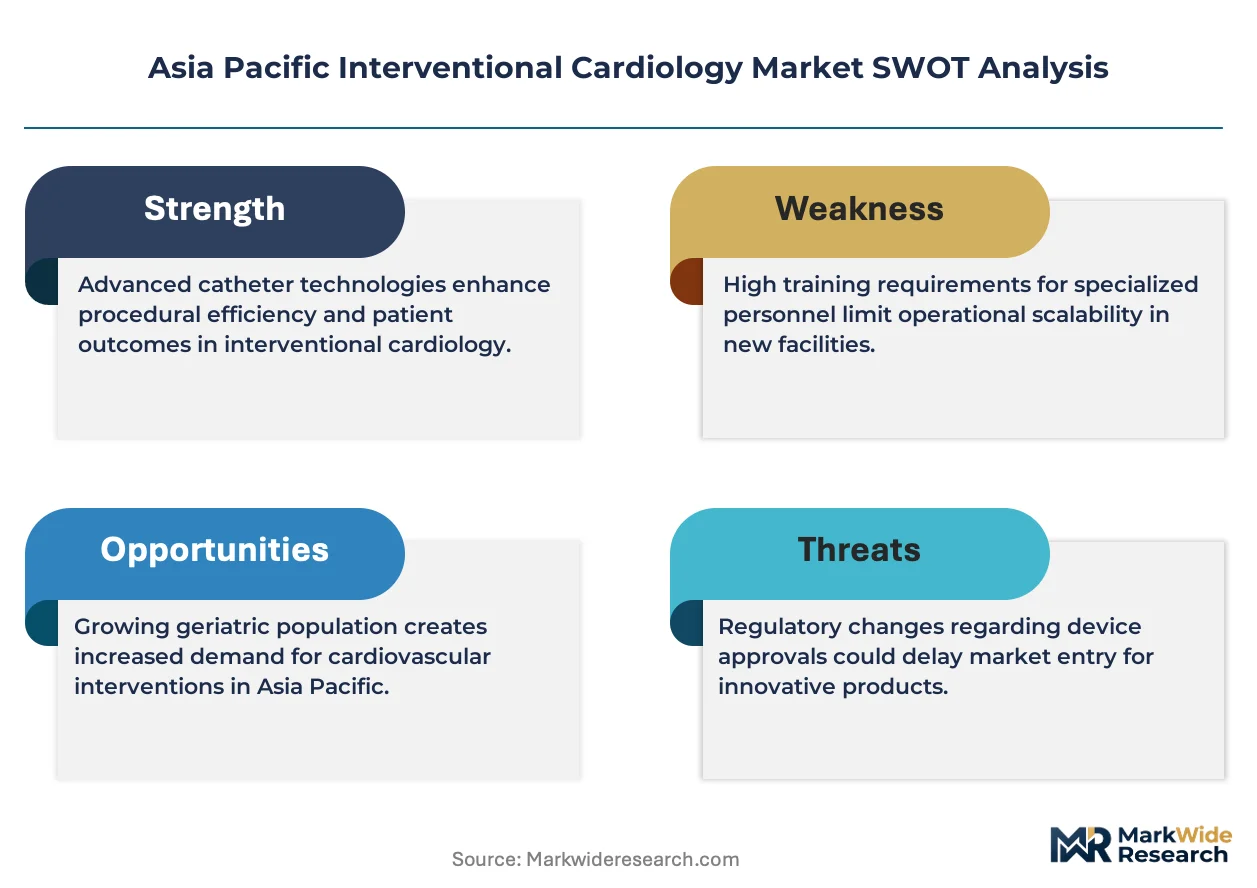
- Bioresorbable stent reimbursement gaps:China's NMPA has not established distinct procedural codes for absorbable scaffolds, forcing providers to absorb premium device costs within standard stent reimbursement bands.
- Domestic price compression in India:CDSCO price controls on coronary stents compress margins for multinational suppliers relative to Lepu Medical Technology and MicroPort Scientific Corporation.
Strategic Opportunities
- ASEAN reimbursement harmonization:Divergent public health financing models across Southeast Asia are converging toward centralized procurement frameworks, creating first-mover advantages for integrated platform suppliers.
- Optical coherence tomography integration:Hospital capital budgets in South Korea and Japan prioritize intravascular imaging guidance, expanding margin pools for catheter systems with embedded OCT compatibility.
- Peripheral vascular extension:Drug-coated balloon applications in renal and femoropopliteal segments remain underpenetrated across Australian regional hospitals.
Industry Challenges
- Interventional cardiologist training pipelines:Complex structural heart procedures require extended proctoring periods, constraining cath lab throughput expansion in Vietnam and Indonesia.
- PMDA-TGA-NMPA evidence divergence:Fragmented clinical trial requirements force manufacturers to maintain parallel regulatory dossiers, extending product launch sequencing by 18-24 months across the region.
- Legacy bare-metal stent inventory:Hospital procurement consortia face write-down pressure on depreciated stent stockpiles as drug-eluting platforms capture procedural preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Interventional Cardiology Market |
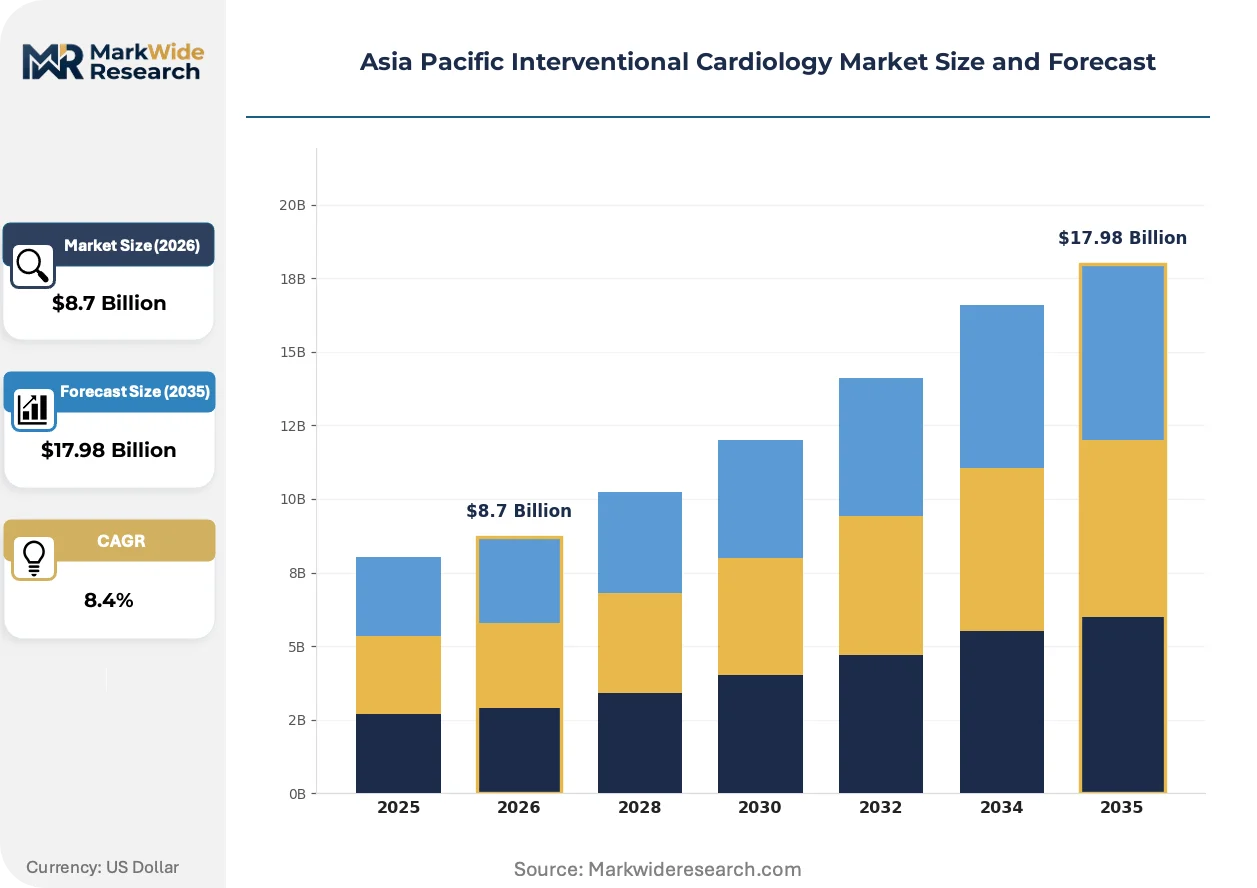
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stents, Guidewires, Access Devices End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Application: Coronary Diseases, Peripheral Vascular Diseases, Structural Heart Diseases, Valvular Diseases Technology: Balloon Angioplasty, Drug-eluting Stents, Bioresorbable Stents, Optical Coherence Tomography |
| Companies Covered | Abbott Laboratories, BIOTRONIK SE & Co. KG, Medtronic plc, Lepu Medical Technology, MicroPort Scientific Corporation, Terumo Corporation, B. Braun Melsungen AG, Biosensors International Group, Boston Scientific Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Interventional Cardiology Market Emerging Trajectories
Device miniaturization and bioresorbable materials are compressing the functional lifecycle of implanted platforms, while imaging integration and AI-guided procedural planning reshape capital equipment purchasing criteria across Asia Pacific cath labs.
Bioresorbable vascular scaffolds constructed from poly-L-lactide matrices provide temporary luminal support before complete metabolic absorption, eliminating permanent metallic foreign bodies. Japanese academic medical centers are piloting these platforms in complex bifurcation lesions despite limited NMPA reimbursement in China. This absorption capability is rewriting long-term antiplatelet therapy protocols and reducing late stent thrombosis surveillance requirements.
PMDA's 2022 guidance on real-world evidence integration for stent approvals now permits registry data supplementation alongside randomized trial endpoints. Device manufacturers are restructuring post-market surveillance architectures to capture Japanese clinical outcomes for label expansion. Drug-eluting platforms with extended follow-up datasets command preferential reimbursement positioning against newer market entrants.
Public hospital procurement committees in China's tier-one cities are consolidating vendor relationships around single-source platform agreements spanning stents, balloons, and guidewires. Distributors with fragmented product portfolios face displacement by integrated supply partners offering cath lab capital equipment bundling. This consolidation pattern is most visible in Shanghai's municipal hospital network, where three-year framework agreements now cover 70 percent of interventional device spending.
Asia Pacific Interventional Cardiology Market Segmentation
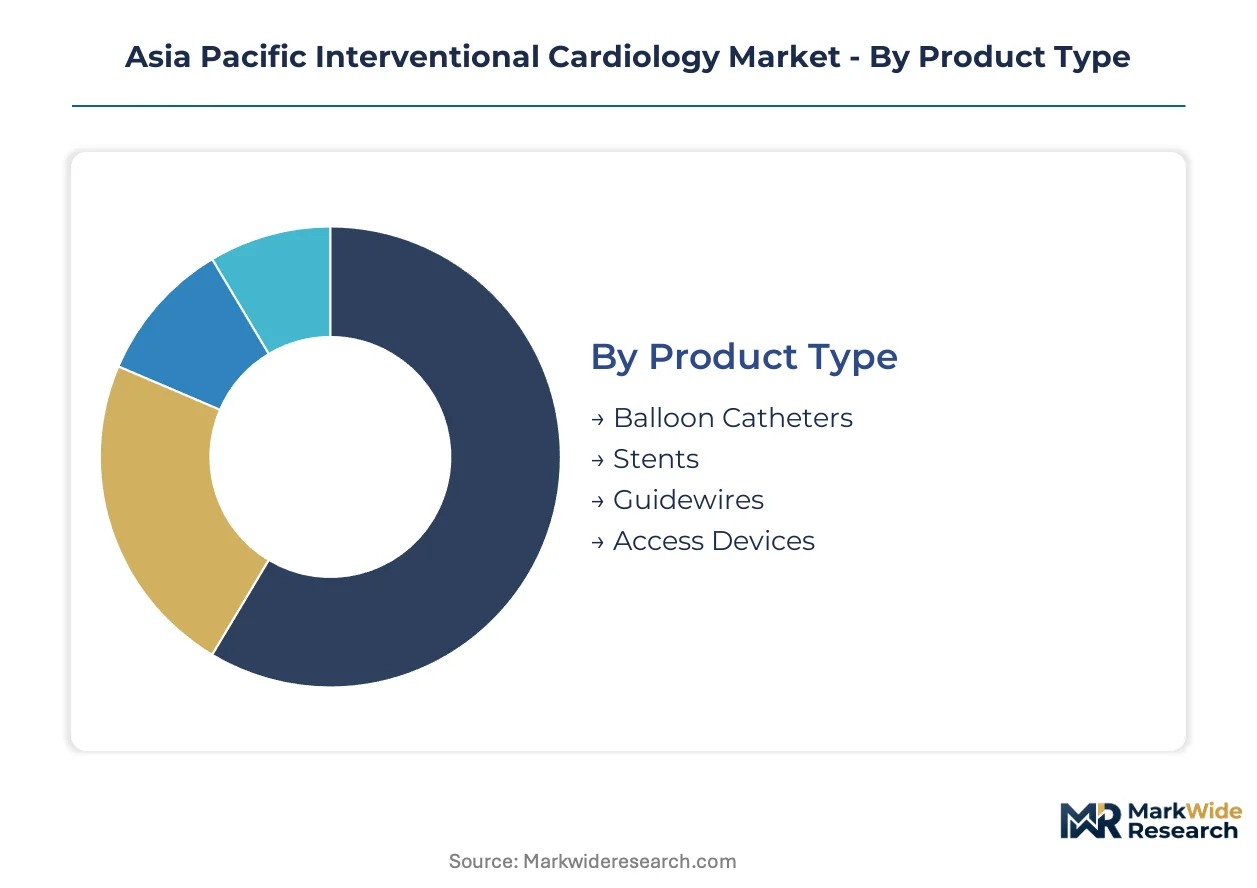
Interventional cardiology markets fragment across four critical dimensions that determine procurement patterns and margin architecture. Product type and technology segments command capital-intensive manufacturing footprints, while end-user and application dimensions shape geographic demand concentration across Asia Pacific healthcare systems.
Product Type:
Capital deployment requirements vary sharply across product categories, with stent manufacturing demanding precision metallurgy investments that dwarf catheter assembly costs.
- Stents:Cobalt-chromium and platinum-iridium alloy platforms require Japanese and German precision forging partnerships for raw material supply. Drug-eluting matrices with antiproliferative agents dominate procurement volumes in Japan's reimbursed segment, while bare-metal alternatives face inventory write-down pressure across Indian hospital networks.
- Balloon Catheters:Polymer extrusion and balloon molding operations concentrate manufacturing scale advantages. Demand clusters in China's tier-one cities where Shanghai and Beijing municipal hospital networks anchor regional volume through consolidated vendor agreements.
- Guidewires:Nitinol core wire and hydrophilic coating technologies define performance differentiation.
- Access Devices:Sheath and introducer systems complete procedural toolkits with lower regulatory burden.
Most installed capacity flows through Stents. Expansion is steepest in Balloon Catheters.
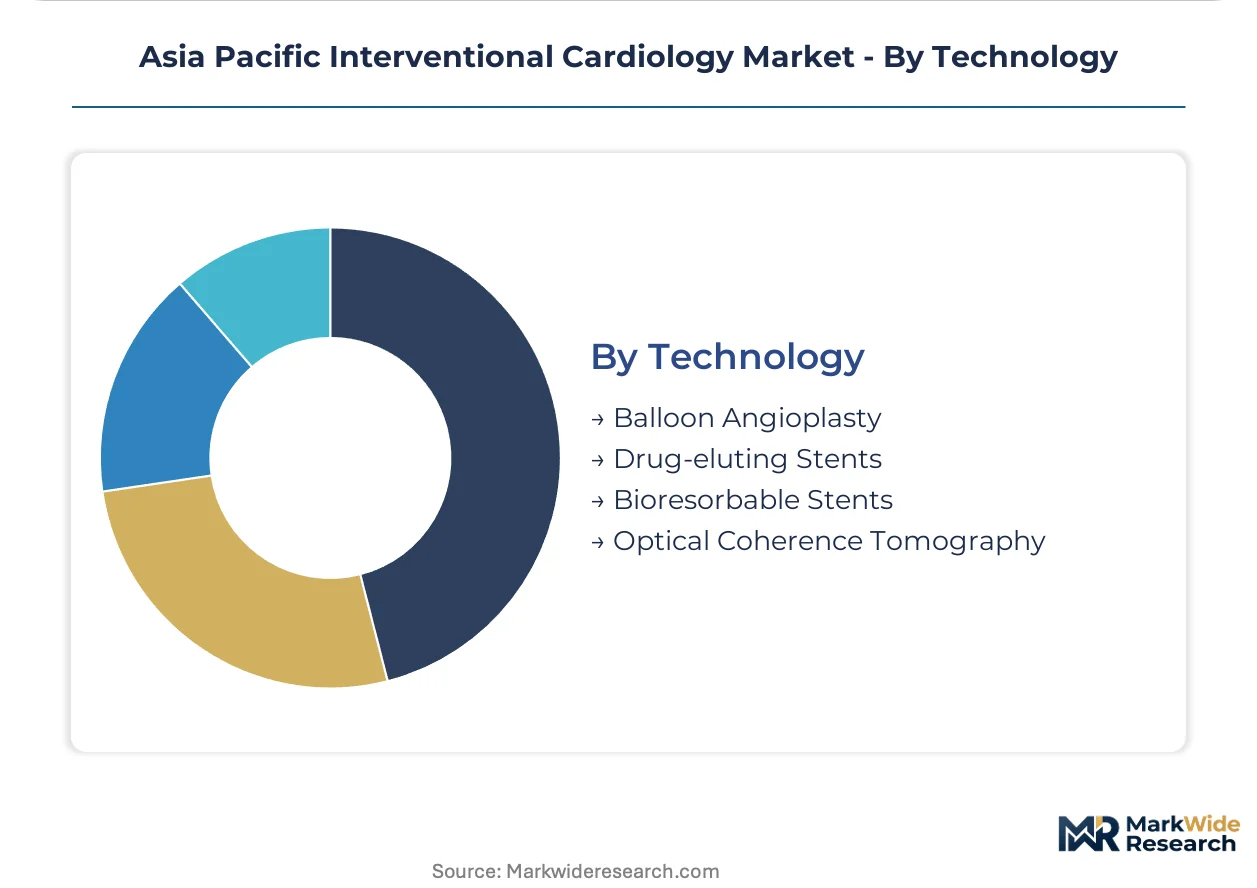
Technology:
Reimbursement eligibility and clinical evidence requirements create tiered adoption velocities that separate premium platforms from commoditized alternatives.
- Drug-eluting Stents:Polymer matrices eluting sirolimus or paclitaxel analogs sustain recurring platform upgrades. Japan's PMDA maintains stringent approval pathways that favor these platforms over bare-metal alternatives, locking in manufacturer revenue predictability.
- Bioresorbable Stents:Poly-L-lactide scaffolds provide temporary luminal support before metabolic absorption. Chinese adoption faces NMPA reimbursement gaps that force providers to absorb premium device costs within standard stent bands.
- Balloon Angioplasty:Plain balloon platforms retain utility in cost-constrained Indian procedures.
- Optical Coherence Tomography:Intravascular imaging systems command capital equipment budgets in South Korea and Japan.
Drug-eluting Stents capture the dominant revenue share. Bioresorbable platforms are climbing the fastest despite reimbursement headwinds.
End User:
Procurement authority concentration determines vendor relationship structures and pricing negotiation leverage across the region.
- Hospitals:Public and private acute care facilities control procedural volume and capital equipment purchasing. Tier-one city networks in China consolidate vendor relationships around multi-year framework agreements covering stents, balloons, and guidewires.
- Cardiology Clinics:Specialized outpatient facilities drive diagnostic catheter demand with lower capital intensity.
- Ambulatory Surgical Centers:Same-day discharge protocols expand peripheral intervention capacity.
- Rehabilitation Centers:Post-procedural care settings influence long-term antiplatelet therapy adherence.
Hospital procurement committees command the largest volume flows. Ambulatory Surgical Centers are gaining share fastest in Australian regional markets.
Application:
Disease burden distribution and procedural complexity shape technology requirements and specialist training investments.
- Coronary Diseases:Atherosclerotic lesion intervention consumes the majority of catheterization laboratory capacity. India's CDSCO accelerates stent approvals through abbreviated pathways, though price controls compress margins for multinational suppliers.
- Structural Heart Diseases:Transcatheter valve repair and replacement procedures demand extended proctoring periods. Complex structural interventions constrain cath lab throughput expansion in Vietnam and Indonesia.
- Peripheral Vascular Diseases:Renal and femoropopliteal segments remain underpenetrated across Australian regional hospitals.
- Valvular Diseases:Aortic and mitral valve pathologies drive specialized device development.
Coronary procedures anchor the installed base. Structural heart applications show the steepest expansion trajectory in Japanese academic medical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's municipal hospital networks command procurement volumes that dwarf Australia's tertiary center demand, yet Japan's PMDA approval pathways sustain premium pricing power that eludes both markets. Divergent regulatory frameworks across these three economies fragment vendor strategies and shape distinct competitive outcomes.
China
Shanghai, Beijing, and Guangzhou anchor balloon catheter and stent demand through consolidated three-year framework agreements covering seventy percent of municipal hospital spending. NMPA maintains distinct reimbursement bands that exclude bioresorbable scaffolds from premium procedural codes. Yangtze River Delta manufacturing clusters supply cobalt-chromium alloy platforms to domestic champions like Lepu Medical Technology and MicroPort Scientific Corporation.
Japan
PMDA's stringent drug-eluting stent approval pathways lock in recurring platform upgrades at academic medical centers in Tokyo and Osaka. METI coordinates post-market surveillance architectures that permit real-world evidence supplementation for label expansion. Kanto region cath labs prioritize optical coherence tomography capital equipment integration, expanding margin pools for imaging-compatible catheter systems.
India
CDSCO abbreviated approval pathways compress registration timelines for multinational drug-eluting platforms entering Mumbai and Delhi hospital networks. Central government price controls on coronary stents compress margins for foreign suppliers relative to domestic competitors. Maharashtra and Gujarat state procurement consortia are consolidating vendor relationships around multi-year supply agreements.
Australia
TGA maintains stringent stent approval pathways that favor drug-eluting platforms over bare-metal alternatives in Sydney and Melbourne tertiary centers. Public hospital procurement committees face write-down pressure on depreciated legacy stent stockpiles. Regional hospital networks exhibit underpenetrated demand for peripheral vascular drug-coated balloon applications in renal and femoropopliteal segments.
South Korea
MFDS reimbursement frameworks sustain premium positioning for intravascular imaging systems across Seoul Capital Area cath labs. Hospital capital budgets prioritize optical coherence tomography guidance integration alongside balloon-expandable device procurement. Busan-Ulsan manufacturing corridors supply nitinol core wire and hydrophilic coating technologies for guidewire specialization.
Asia Pacific Interventional Cardiology Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia Pacific interventional cardiology procurement channels. Hospital networks in China and Japan favor integrated platform suppliers offering bundled stent, balloon, and guidewire portfolios under multi-year framework agreements. Three archetypes dominate: multinational device conglomerates with structural heart diversification, regional manufacturing specialists with nitinol and polymer extrusion scale, and domestic champions leveraging abbreviated regulatory pathways and price control exemptions. Competitive moves concentrate on geographic expansion through distributor acquisition and backward integration into cobalt-chromium alloy forging capacity.
Among diversified multinational suppliers, Abbott Laboratories and Medtronic plc occupy positions anchoring premium catheter placements in Australian tertiary centers and Japan's reimbursed stent segment respectively. Terumo Corporation exemplifies the regional manufacturing specialist archetype through guidewire specialization and Southeast Asian distribution channel scale. These three names represent the competitive tension between global platform breadth and focused manufacturing excellence that defines vendor selection criteria across Asia Pacific hospital procurement consortia.
| Leading Market Players |
|---|
| Abbott Laboratories |
| BIOTRONIK SE & Co. KG |
| Medtronic plc |
| Lepu Medical Technology |
| MicroPort Scientific Corporation |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Biosensors International Group |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Cobalt-chromium alloy spot prices on the London Metal Exchange cascade through Japanese precision forging partnerships into three distinct pricing tiers for Asia Pacific catheterization laboratories, compressing margins for manufacturers without captive metallurgy supply.
Pricing Analysis
Capacity additions in Chinese Yangtze River Delta manufacturing clusters are reshaping price floors for balloon catheter platforms, forcing Japanese and German suppliers to defend premium positioning through PMDA-approved drug-eluting certifications. Three-tier pricing structure across premium, standard, and economy levels separates OCT-integrated catheter systems from plain balloon alternatives. Cost compression in India's CDSCO-controlled stent segment is intensifying because central government price controls force multinational suppliers to absorb margin erosion against Lepu Medical and MicroPort. Public hospital procurement committees in China's tier-one cities exhibit lowest price sensitivity, while Indian state-level consortia demonstrate acute cost responsiveness.
Supply Chain Analysis
Single-source vulnerability sits with Japanese precision forging capacity for cobalt-chromium and platinum-iridium alloy platforms, tethering stent manufacturers to Kobe and Osaka metallurgy partnerships. Raw material flows draw from German specialty steel producers, Chinese rare earth processors for nitinol guidewire cores, and South Korean polymer extrusion houses for balloon molding. Tariff exposure on precision alloy imports threatens margin stability for Australian and Southeast Asian distributors. Distribution runs through hospital procurement consortia consolidating vendor relationships around multi-year framework agreements rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific interventional cardiology market functions as a stable compounder anchored by irreversible cath lab capacity expansion across hospital networks responding to rising coronary disease burdens.
For Market Incumbents: Deepen backward integration into cobalt-chromium alloy forging capacity to escape Japanese supply bottlenecks and defend margin architecture against domestic Chinese champions. Lock in multi-year framework agreements with Shanghai and Beijing municipal hospital networks before procurement consolidation completes. Prioritize OCT compatibility investments to capture South Korean and Japanese capital equipment budgets.
For New Entrants and Emerging Players: Begin with peripheral vascular drug-coated balloon applications across Australian regional hospitals, where underpenetrated renal and femoropopliteal segments offer white-space expansion without incumbent entrenched relationships. Target ASEAN reimbursement harmonization windows through centralized procurement framework pre-qualification. Lead with integrated platform bundling spanning stents, balloons, and guidewires to match hospital consortium vendor consolidation preferences.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional manufacturing specialists possessing nitinol core wire and hydrophilic coating scale across Southeast Asian distribution channels. Long-term viability over a 5-10 year horizon rests on regulatory dossier breadth spanning PMDA, TGA, NMPA, and CDSCO pathways rather than single-market dependence. Monitor NMPA reimbursement code establishment for bioresorbable scaffolds as the critical inflection signal for premium platform adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Real-World Evidence Integration | Registry data supplementation accelerates Japanese label expansion for drug-eluting stent manufacturers. |
| CDSCO Abbreviated Pathway Utilization | Streamlined coronary stent approvals compress multinational market entry timelines against domestic competitors. |
| Hospital System Partnership Consolidation | Three-year framework agreements with Shanghai municipal networks lock in seventy percent of device spending. |
| OCT Capital Equipment Bundling | Imaging-compatible catheter systems capture premium margin pools in Seoul and Tokyo cath labs. |
| ASEAN Centralized Procurement Pre-Qualification | First-mover positioning ahead of reimbursement harmonization across Southeast Asian public health systems. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down stent and balloon manufacturing tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combined with secondary validation against PMDA approval databases, CDSCO registration filings, NMPA reimbursement codes, and hospital procurement expenditure records. Triangulation between procedural volume estimates and device shipment data ensures consistency across market sizing outputs.
Input-output matrices map catheterization laboratory capacity expansion, coronary disease prevalence trajectories, and regulatory approval timelines into segmented demand projections across the analysis window. Segmentation dimensions encompass product type, technology tier, end-user procurement authority, and application complexity. CAGRs derive from fitted growth curves anchored to historical procedural volumes and policy-driven reimbursement adjustments. Forecast inputs include PMDA real-world evidence integration velocity and CDSCO price control amendment schedules.
Caveats apply where NMPA reimbursement code revisions for bioresorbable scaffolds or ASEAN harmonization delays could materially shift the outlook for premium platform adoption. Forecasts reflect documented assumptions regarding cath lab buildout rates and regulatory pathway stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Global Intracranial Stents Market