
 South America Endotoxin and Pyrogen Testing Market | 2026-2036
South America Endotoxin and Pyrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
South America Endotoxin and Pyrogen Testing Market Analytics
Recombinant Factor C reagents is rebalancing cost structures for endotoxin detection workflows across South American quality control facilities. Lonza Group leverages its rFC portfolio to capture premium positioning in Brazilian pharmaceutical manufacturing. Charles River Laboratories anchors regional service capabilities through its contract testing footprint. Merck KGaA competes on chromogenic assay standardization for high-throughput laboratories.
Endotoxin and pyrogen testing encompasses analytical methods that detect lipopolysaccharide contaminants from Gram-negative bacterial cell walls, with Limulus Amebocyte Lysate assays detecting thresholds down to 0.03 EU/mL and recombinant Factor C tests offering animal-origin-free alternatives for parenteral drug release decisions. The LAL test category retains dominant share due to established pharmacopeial acceptance, while rFC tests represent the fastest-growing segment as manufacturers seek compliance with European pharmacopeia revisions and sustainability mandates. Kits and reagents command the largest product type revenue pool, though services margins expand as outsourced validation work rises.
ANVISA enforces sterility testing protocols aligned with Brazilian pharmacopeia standards, while ISO 10993-11 guides pyrogenicity evaluation for medical device registrants across Mercosur markets. Brazil's national health surveillance agency shapes market access through mandatory lot-release testing requirements for imported parenterals. Stakeholders must monitor pharmacopeial harmonization between ANVISA and European directives to anticipate rFC substitution timelines and reagent registration burdens.
Market Dynamics
Recombinant Factor C assays are compressing testing timelines for Brazilian parenteral manufacturers while ANVISA's sterile product guidelines force quality control budget reallocations across São Paulo biopharma clusters.
Growth Catalysts
- ANVISA sterility mandates:Brazil's national health surveillance agency tightened lot-release testing requirements for imported injectables, compelling pharmaceutical manufacturers to expand endotoxin screening capacity.
- Biopharma cluster concentration:São Paulo and Rio de Janeiro host expanding contract manufacturing organizations driving demand for high-throughput pyrogen detection workflows.
- rFC pharmacopeial alignment:European Pharmacopoeia Chapter 2.6.32 acceptance of recombinant Factor C methods accelerates adoption among exporters targeting EU markets.
Market Restraints
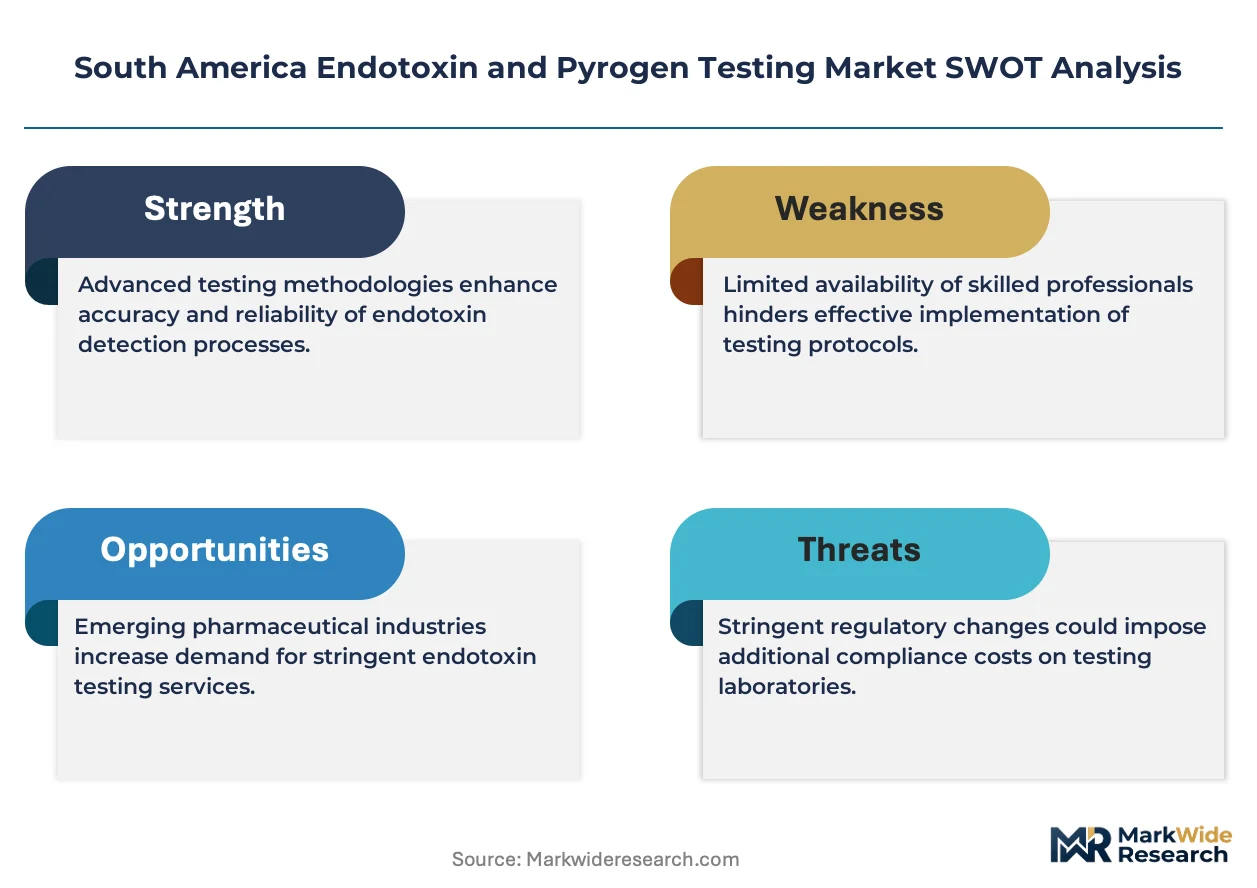
- Import dependency for reagents:Regional laboratories rely on North American and European suppliers for LAL and rFC kits, exposing operations to currency volatility and customs delays.
- Validation cost burden:Method transfer from LAL to rFC requires extensive comparability studies under ISO 10993-11, straining mid-sized quality control budgets.
- Technical workforce scarcity:Specialized expertise in endotoxin detection assay development concentrates in Brazilian metropolitan centers, limiting regional laboratory expansion.
Strategic Opportunities
- Argentine biopharma emergence:Buenos Aires pharmaceutical manufacturing is expanding quality control infrastructure, creating first-mover advantages for rFC assay providers establishing local distribution.
- Cell and gene therapy testing:Advanced therapy medicinal products require specialized pyrogen evaluation beyond standard LAL sensitivity ranges, opening premium service niches.
- Mercosur harmonization:Alignment of medical device regulations across member states enables standardized pyrogen testing protocols for multi-country registrants.
Industry Challenges
- Assay standardization complexity:Inter-laboratory variability in LAL test execution complicates multi-site pharmaceutical manufacturing quality assurance.
- Legacy equipment integration:Chromogenic and turbidimetric detection systems require software updates to accommodate rFC reagent workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Endotoxin and Pyrogen Testing Market |
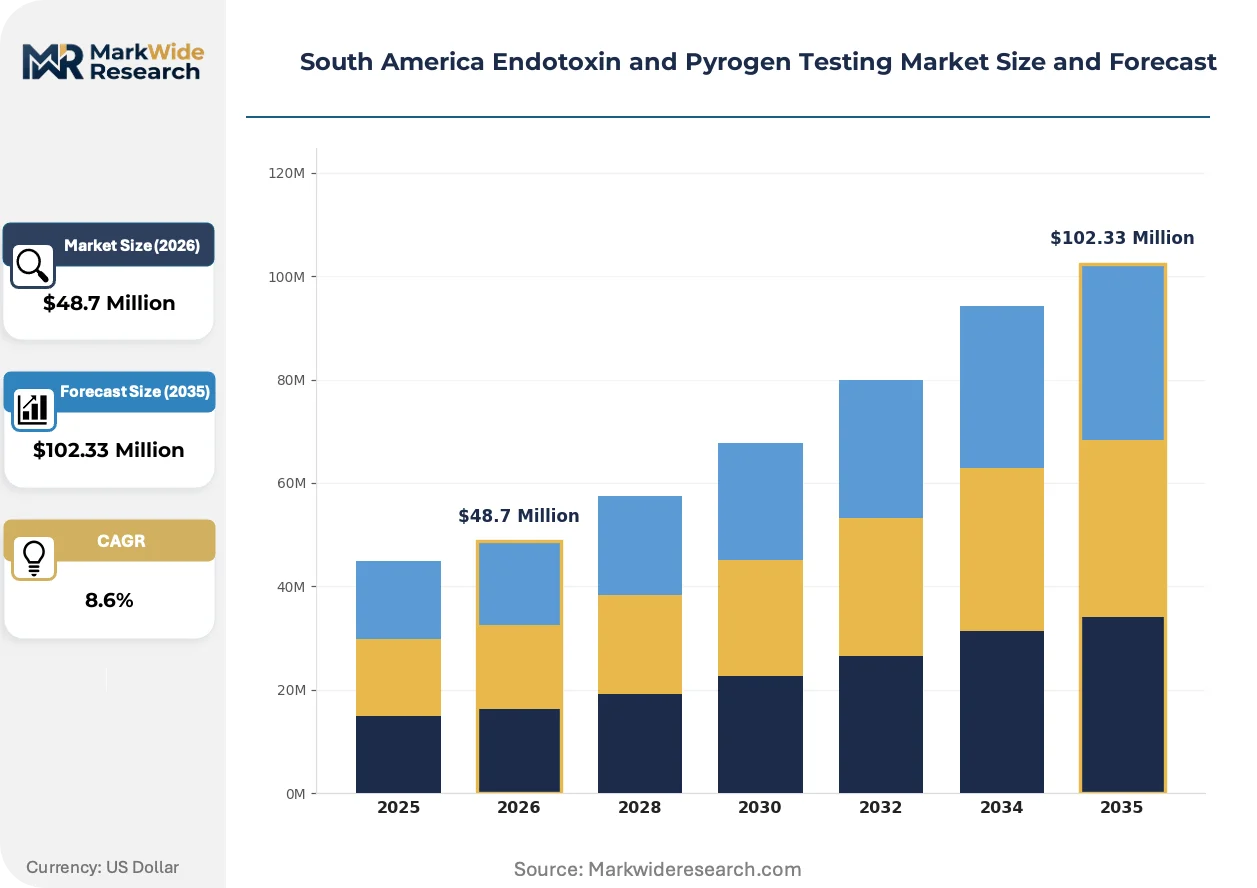
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $102.33 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: LAL Test, rFC Test, Rabbit Test, Chromogenic Test Product Type: Kits, Reagents, Instruments, Services Industry Vertical: Pharmaceutical, Biotechnology, Medical Devices, Research Laboratories End User: Hospitals, Clinics, Contract Laboratories, Manufacturers |
| Companies Covered | Merck KGaA, Charles River Laboratories, Lonza Group, Associates of Cape Cod, Thermo Fisher Scientific, bioMérieux SA, Ellab A/S, GenScript Biotech, Eurofins Biolab Srl, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Endotoxin and Pyrogen Testing Market Evolving Landscape
Endotoxin detection workflows across South American quality control facilities are fragmenting as traditional centralized laboratory models confront point-of-need testing alternatives and automated platform integration.
Recombinant Factor C technology is decentralizing endotoxin testing authority from dedicated microbiology laboratories toward production floor quality control stations. Brazilian biopharma manufacturers in São Paulo industrial parks are deploying portable rFC readers for at-line batch release decisions. This shift is compressing testing turnaround from days to hours while reducing sample transport contamination risks.
ANVISA's alignment with International Council for Harmonisation Q5A guidelines is mandating viral safety documentation that includes endotoxin burden assessments for cell culture media. Contract testing organizations must now maintain dual capability in traditional LAL and molecular pyrogen methods. Argentine and Chilean medical device registrants face expanded biocompatibility dossier requirements under this harmonization.
Quality control procurement in Brazilian pharmaceutical manufacturing is consolidating through preferred supplier agreements with regional contract testing networks. Small and mid-sized manufacturers are outsourcing validation work rather than maintaining in-house endotoxin detection infrastructure. This pattern concentrates most visible in Rio de Janeiro's expanding biopharma corridor, where third-party testing services capture expanding share of release decisions.
South America Endotoxin and Pyrogen Testing Market Segmentation
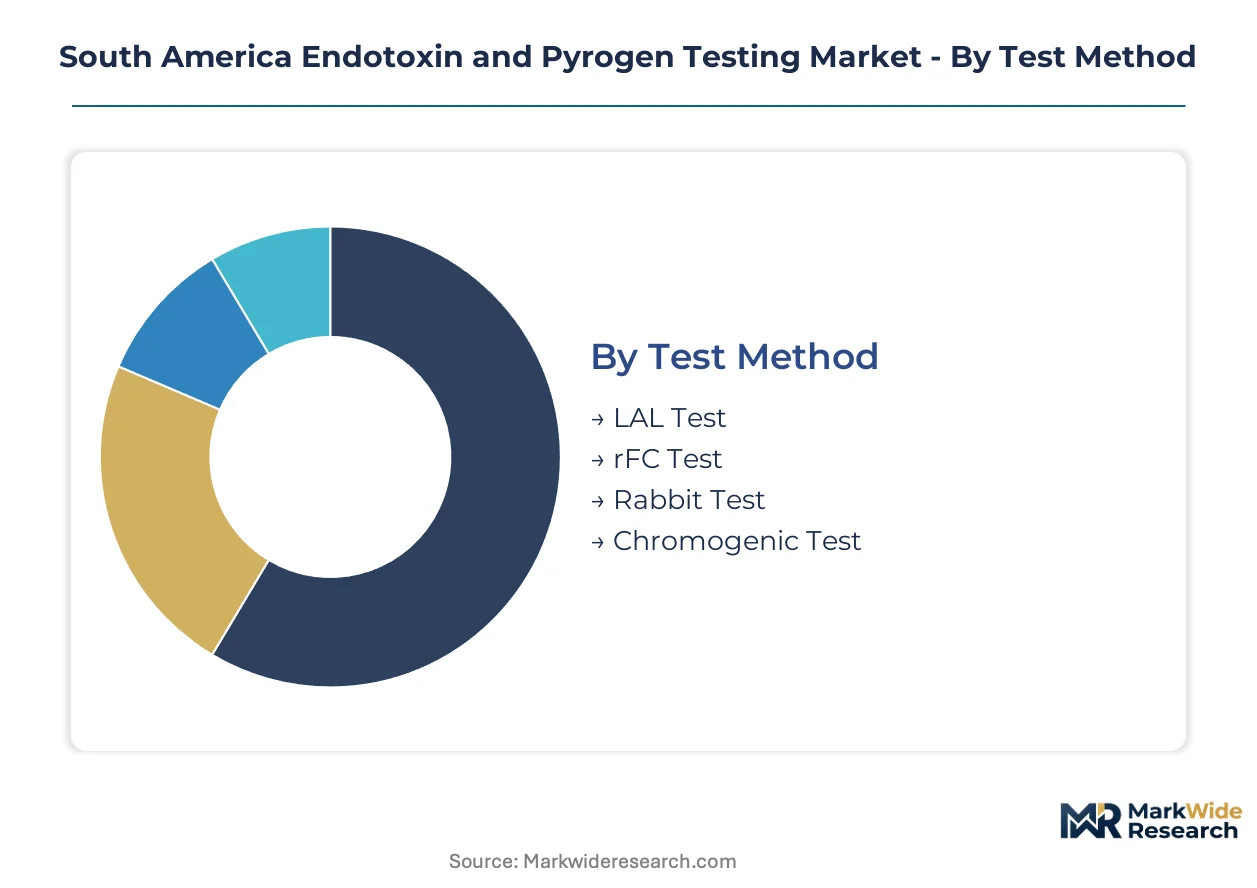
Endotoxin and pyrogen testing configurations across South America fragment sharply by technical sophistication and regulatory exposure. Brazilian pharmaceutical manufacturers prioritize method flexibility to satisfy ANVISA lot-release mandates while managing currency-driven import costs.
Test Method:
LAL and rFC methods split the market between established pharmacopeial acceptance and emerging animal-origin-free alternatives, with volume concentration in high-throughput Brazilian contract laboratories.
- LAL Test:Limulus Amebocyte Lysate assays detect lipopolysaccharide thresholds down to 0.03 EU/mL using horseshoe crab hemolymph derivatives. São Paulo biopharma clusters deploy these for routine parenteral batch release under established Brazilian pharmacopeia protocols.
- rFC Test:Recombinant Factor C assays eliminate animal sourcing while accelerating detection timelines. Rio de Janeiro manufacturers expanding EU export capacity adopt these to align with European Pharmacopoeia Chapter 2.6.32 revisions.
- Rabbit Test:In vivo pyrogenicity evaluation retains niche application for complex biologics where LAL interference persists.
- Chromogenic Test:Colorimetric endpoint detection supports high-volume screening in Argentine and Chilean medical device registration workflows.
Mature deployment sits with LAL Test. Newer deployment is concentrated in rFC Test.
Product Type:
Reagent procurement patterns track import dependency exposure, with Brazilian manufacturers balancing inventory carrying costs against customs clearance uncertainties.
- Kits:Pre-configured assay systems bundle lysate, standards, and controls for standardized endotoxin quantification. Contract laboratories across Mercosur markets favor kit formats to reduce method development overhead and accelerate validation timelines.
- Reagents:Bulk lysate and chromogenic substrates support high-volume manufacturing quality control operations. São Paulo pharmaceutical plants consume substantial reagent volumes for continuous parenteral production monitoring.
- Instruments:Turbidimetric and chromogenic detection platforms automate endpoint reading for high-throughput facilities.
- Services:Outsourced validation and method transfer work expands as mid-sized Brazilian manufacturers abandon in-house microbiology infrastructure.
Volume concentration favors Reagents. Margin expansion is strongest in Services.
Industry Vertical:
Regulatory stringency varies dramatically across verticals, with sterile injectable mandates driving premium testing expenditure compared to device surface evaluation requirements.
- Pharmaceutical:Parenteral drug manufacturers face mandatory endotoxin screening under ANVISA sterile product guidelines. Brazilian facilities producing intravenous solutions and vaccines maintain the most intensive testing frequencies in the regional market.
- Biotechnology:Cell culture media and therapeutic protein production require specialized pyrogen evaluation beyond standard LAL sensitivity ranges. Buenos Aires biotech startups are building quality control capabilities to support monoclonal antibody development pipelines.
- Medical Devices:Implantable and blood-contacting devices require ISO 10993-11 biocompatibility documentation including pyrogenicity assessment.
- Research Laboratories:Academic and government facilities support method development and regulatory science activities with variable throughput demands.
Compliance burden concentrates in Pharmaceutical. Capability building is accelerating fastest in Biotechnology.
End User:
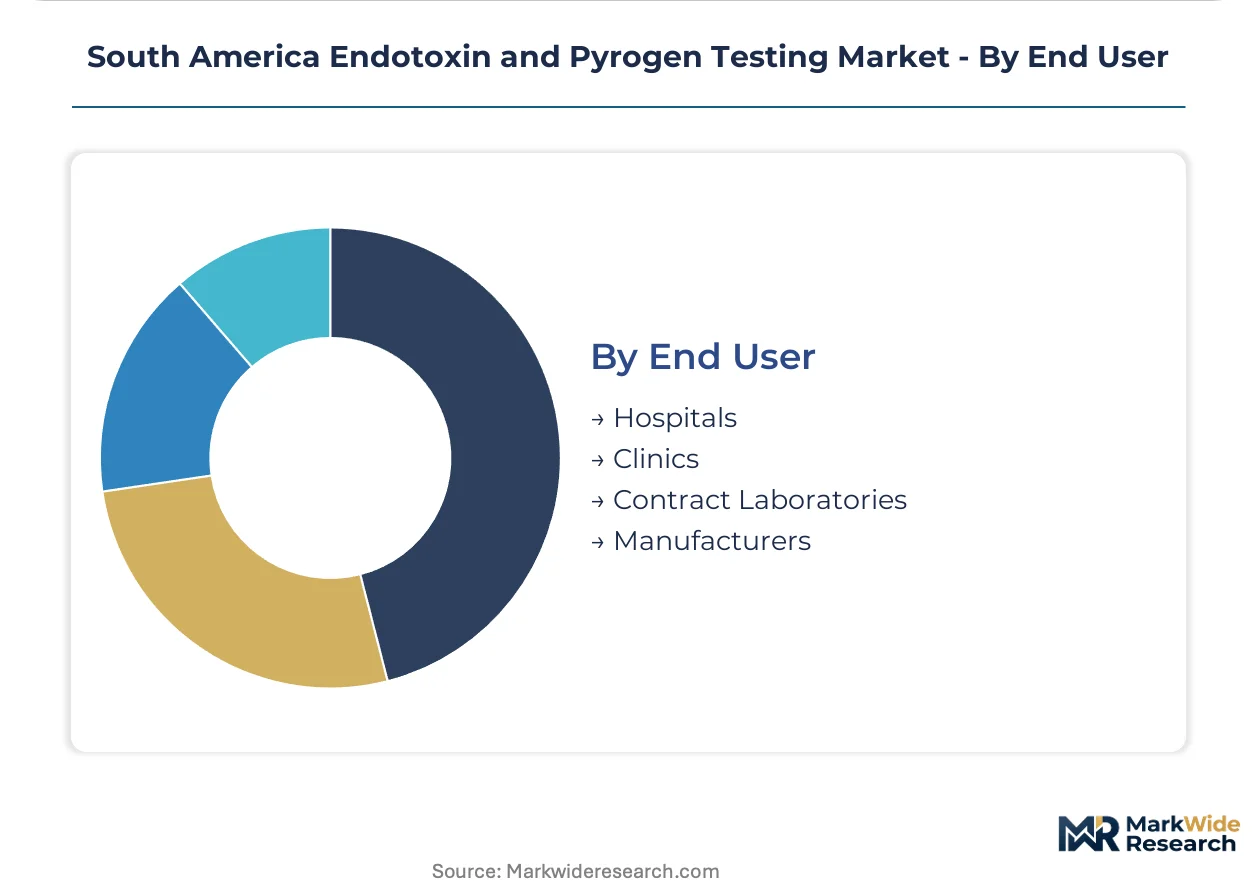
Testing authority distribution reflects outsourcing economics, with manufacturing scale determining in-house versus third-party assay deployment.
- Contract Laboratories:Regional testing networks capture expanding share of release decisions as Brazilian manufacturers consolidate preferred supplier relationships. Rio de Janeiro's biopharma corridor hosts specialized facilities offering dual LAL and rFC capability under single quality agreements.
- Manufacturers:Large pharmaceutical and medical device producers maintain captive testing infrastructure for batch release autonomy. São Paulo industrial parks house the most sophisticated in-house endotoxin detection operations in South America.
- Hospitals:Compounding pharmacies and sterile preparation units conduct point-of-use testing for patient-specific formulations.
- Clinics:Limited testing volume restricts assay deployment to basic screening applications in outpatient settings.
Testing volume concentrates with Manufacturers. Outsourcing momentum is strongest in Contract Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endotoxin and pyrogen testing concentrates in Brazilian biopharma clusters, with São Paulo and Rio de Janeiro absorbing the majority of regional quality control expenditure as ANVISA tightens sterile product oversight.
Brazil
ANVISA mandates lot-release testing for imported parenterals, compelling pharmaceutical manufacturers to expand endotoxin screening capacity. São Paulo's industrial parks host the most sophisticated in-house detection operations, while Rio de Janeiro's biopharma corridor drives outsourcing momentum through specialized contract laboratories offering dual LAL and rFC capability.
Argentina
Buenos Aires pharmaceutical manufacturing is expanding quality control infrastructure to support monoclonal antibody development pipelines. The national pharmaceutical regulator enforces biocompatibility documentation aligned with Mercosur medical device standards, creating first-mover opportunities for rFC assay providers establishing local distribution networks.
Chile
Santiago-based medical device registrants face expanded ISO 10993-11 pyrogenicity requirements under harmonized Mercosur regulations. Chromogenic endpoint detection supports high-volume screening workflows, with import-dependent laboratories managing currency exposure through preferred supplier agreements with regional testing networks.
Colombia
Bogotá pharmaceutical manufacturing is building captive testing infrastructure for batch release autonomy. The national health surveillance agency shapes market access through sterility protocols for injectable products, concentrating specialized expertise in metropolitan quality control facilities.
Peru
Lima's emerging pharmaceutical sector relies on outsourced validation work rather than maintaining in-house endotoxin detection infrastructure. Import dependency for LAL and rFC reagents exposes operations to customs delays, driving consolidation through regional contract testing preferred supplier relationships.
South America Endotoxin and Pyrogen Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with kit and reagent suppliers commanding premium positioning while service providers capture margin expansion through outsourced validation work. The market structure concentrates around three strategic archetypes: multinational life science conglomerates with diversified diagnostics portfolios, specialized endotoxin testing pure-plays with deep pharmacopeial expertise, and regional contract research organizations building dual-method capability. Competitive intensity manifests through strategic partnerships for rFC reagent distribution and capacity expansion in Brazilian biopharma corridors.
Within the multinational tier, Merck KGaA, Lonza Group, and Charles River Laboratories exemplify contrasting positioning strategies. Merck KGaA anchors chromogenic assay standardization for high-throughput laboratories. Lonza Group leverages its rFC portfolio to capture premium positioning in Brazilian pharmaceutical manufacturing. Charles River Laboratories occupies a position as the regional service capability anchor through its contract testing footprint.
| Leading Market Players |
|---|
| Merck KGaA |
| Charles River Laboratories |
| Lonza Group |
| Associates of Cape Cod |
| Thermo Fisher Scientific |
| bioMérieux SA |
| Ellab A/S |
| GenScript Biotech |
| Eurofins Biolab Srl |
| Others |
Value Network & Pricing Analysis
Import parity pricing for LAL lysate and rFC reagent kits cascades through Brazilian pharmaceutical procurement, compressing margins for mid-sized quality control facilities while concentrating purchasing power among São Paulo biopharma clusters with preferred supplier agreements.
Pricing Analysis
Volume concentration in bulk reagent procurement splits from margin capture in outsourced validation services. Three-tier pricing structure across premium, standard, and economy levels differentiates by pharmacopeial certification grade and ANVISA registration status. Pricing pressure stems from currency volatility exposing import-dependent laboratories to customs clearance delays. Mid-sized manufacturers exhibit highest price sensitivity, while large São Paulo parenteral producers prioritize batch release autonomy over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired reagent kits and recalibrated detection instruments remain underdeveloped across South American quality control networks. Supply concentrates in the United States, Switzerland, and Germany for recombinant Factor C reagents and chromogenic substrates. Raw material dependencies include horseshoe crab hemolymph derivatives, synthetic endotoxin standards, and automated reader components. Single-source vulnerability for rFC reagents exposes Brazilian contract laboratories to supplier concentration risk. Distribution runs through regional contract testing networks consolidating preferred supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over rFC reagent manufacturing determines margin sustainability as ANVISA tightens sterile product guidelines.
For Market Incumbents: Hedge against rFC substitution timelines by maintaining dual LAL and recombinant Factor C capability while securing long-term lysate supply agreements. Invest in ANVISA-registered quality agreements with Rio de Janeiro contract laboratories to defend service revenue pools. Backward integration into reagent distribution buffers currency exposure for Brazilian manufacturing clients. For New Entrants and Emerging Players: The premium-economy price gap in Argentine biopharma quality control infrastructure offers first-mover positioning for rFC assay providers establishing Buenos Aires distribution. Target monoclonal antibody development pipelines with specialized pyrogen evaluation beyond standard LAL sensitivity ranges. Pursue Mercosur harmonization pathways to enable standardized multi-country registrant protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract testing specialists with ANVISA-registered dual-method capability in Brazilian metropolitan corridors. Long-term viability hinges on consolidation of outsourced validation work as mid-sized manufacturers abandon captive microbiology infrastructure. Monitor European Pharmacopoeia Chapter 2.6.32 adoption rates among Brazilian exporters as inflection indicator for rFC penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| rFC Reagent Localization | Reduces import dependency exposure for Brazilian quality control facilities facing currency volatility. |
| Dual-Method Laboratory Certification | Enables ANVISA-registered contract testing networks to capture outsourced validation work from mid-sized manufacturers. |
| Preferred Supplier Consolidation | Concentrates purchasing power among São Paulo biopharma clusters negotiating volume-based reagent pricing. |
| Point-of-Need Testing Deployment | Compresses batch release timelines from days to hours for Rio de Janeiro parenteral manufacturers. |
| Mercosur Regulatory Harmonization | Standardizes pyrogen testing protocols across Argentina, Chile, and Brazil for multi-country device registrants. |
Research Methodology
Multi-period observation of ANVISA registration filings, reagent import volumes, and contract testing capacity expansion anchored the trend analysis, supplemented by interviews with quality control directors at Brazilian pharmaceutical manufacturers, regulatory affairs specialists, laboratory procurement managers, and contract research organization executives. Secondary validation drew from ANVISA sterile product guidelines, Brazilian pharmacopeia standards, ISO 10993-11 documentation, and Mercosur medical device harmonization protocols. Bottom-up laboratory capacity estimates triangulated against top-down pharmaceutical manufacturing expenditure data.
Segment-weighting approaches applied differential growth assumptions across test method, product type, and end user dimensions. Modeled variables included LAL-to-rFC substitution velocity, outsourcing penetration rates among mid-sized manufacturers, and biopharma cluster concentration in São Paulo and Rio de Janeiro. CAGRs were derived from regression analysis of historical quality control budget allocations and projected ANVISA enforcement intensity across the analysis window.
Inputs from ANVISA regulatory databases and Brazilian pharmaceutical industry associations were available through the study window; gaps in real-time contract testing pricing data introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding pharmacopeial harmonization timelines and rFC adoption curves. Practitioners should monitor European Pharmacopoeia revision schedules and Brazilian real exchange rate volatility for early signals of pricing pressure and substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US C-Reactive Protein Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Blood Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Autoimmune Disease Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Blood Borne Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Fungal Testing Kits Market