
 Heart Valves Market | 2026-2036
Heart Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Valves Market Analysis
Aftermarket valve-in-valve procedure revenue is fragmenting across independent cardiac centers and integrated hospital networks. Edwards Lifesciences Corporation anchors transcatheter aortic replacement through specialized physician training ecosystems. Medtronic plc competes across surgical and percutaneous platforms with broad tissue and mechanical portfolios. Abbott differentiates in mitral repair through differentiated clip-based systems that bypass replacement entirely.
Heart valves are implantable devices constructed from pyrolytic carbon, bovine pericardium, or porcine leaflets, engineered to regulate unidirectional blood flow across cardiac chambers with durability targets exceeding one billion cycles. Transcatheter valves capture expanding margin pools as cath-lab infrastructure proliferates, while mechanical valves sustain share in younger patients prioritizing longevity over anticoagulation burden. Bioprosthetic tissue segments face accelerated valve-in-valve degradation, creating recurring intervention demand that reshapes lifetime patient value calculations.
FDA breakthrough device designation and EMA conditional approval pathways compress development timelines for novel valve platforms, while ISO 5840 standards govern fatigue resistance and hydrodynamic performance benchmarks. Reimbursement coding by CMS and parallel German G-DRG structures determine site-of-service economics, favoring outpatient transcatheter procedures over surgical admissions. Stakeholders must monitor whether real-world evidence mandates from regulators shift post-market surveillance obligations onto manufacturers.
Market Dynamics
Transcatheter delivery systems are collapsing the traditional surgical episode into outpatient cath-lab workflows, redistributing value capture from hospital cardiac surgery departments to interventional cardiology units and specialized valve centers.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed trial timelines accelerate novel valve platform commercialization, reducing time-to-market for transcatheter mitral and tricuspid systems.
- Valve-in-Valve Degradation Cycles:Bioprosthetic tissue failure creates recurring intervention demand, expanding lifetime patient value pools beyond index procedures.
- Germany's G-DRG Reimbursement Realignment:Outpatient transcatheter procedure coding favors site-of-service economics over surgical admissions, accelerating cath-lab infrastructure investment.
Market Restraints
- Bovine Pericardium Supply Concentration:Tissue sourcing dependence on controlled herds creates input cost volatility and biosecurity exposure.
- Anticoagulation Burden Trade-offs:Mechanical valve longevity in younger patients conflicts with lifelong warfarin therapy compliance and bleeding risk management.
- EMA Conditional Approval Stringency:Post-market surveillance obligations impose ongoing clinical data collection costs that compress margins for mid-tier manufacturers.
Strategic Opportunities
- Japan's Aging Demographics:Underpenetrated transcatheter penetration rates in elderly populations create expansion headroom for mitral repair platforms.
- Artificial Intelligence-Enabled Imaging:Convergence of computed tomography planning software with robotic navigation systems enables precision deployment in complex anatomies.
- Direct-to-Hospital Contracting:Bypassing traditional distributor networks captures margin pools previously allocated to intermediaries in integrated delivery networks.
Industry Challenges
- Structural Heart Fellowship Pipeline:Interventional cardiologist training capacity constraints limit procedure volume scaling at high-throughput centers.
- ISO 5840 Fatigue Certification Timelines:Accelerated life-cycle testing requirements extend regulatory submission preparation without guaranteeing approval.
- Pyrolytic Carbon Machining Capacity:Specialized manufacturing equipment lead times create capex bottlenecks for mechanical valve production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Valves Market |
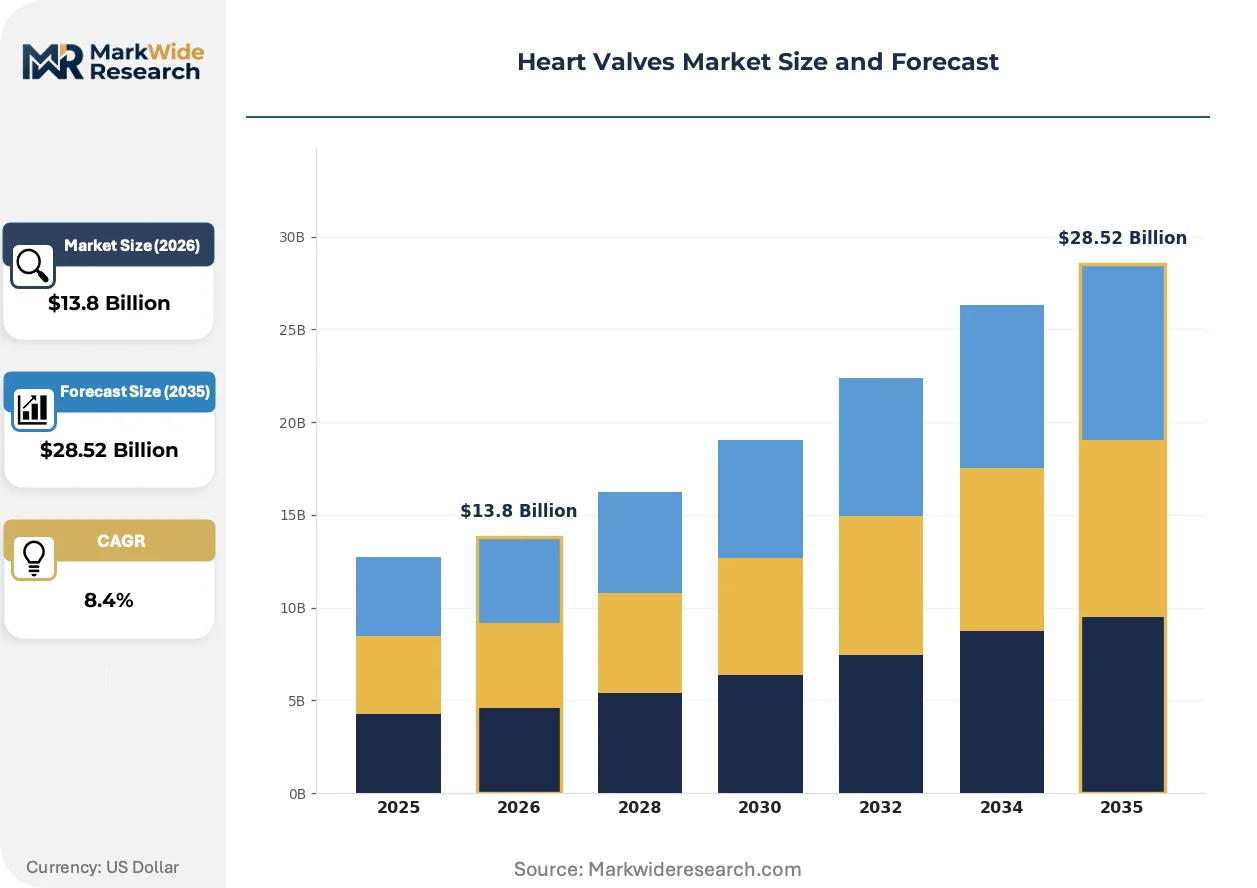
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Tissue Valves, Transcatheter Valves, Bioprosthetic Valves End User: Hospitals, Cardiac Clinics, Research Institutions, Rehabilitation Centers Delivery Mode: Surgical Implantation, Percutaneous Approach, Minimally Invasive Techniques, Open-Heart Surgery Application: Valvular Heart Disease, Aortic Stenosis, Mitral Regurgitation, Heart Valve Replacement |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott, Boston Scientific Corporation, LivaNova, JenaValve Technology, Artivion, Corcym, Foldax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Valves Market Emerging Trajectories
Computational modeling and digital twin technologies are compressing valve design iteration cycles while regulatory science evolves to validate simulated performance against physical bench testing.
Polymeric valve leaflets engineered from advanced thermoplastic polyurethanes are virtualizing the bioprosthetic tissue supply chain, eliminating xenograft sourcing constraints. Cath-lab operators in Germany and the United States are piloting these synthetic systems for transcatheter delivery. The technology is virtualizing traditional procurement relationships between device manufacturers and tissue processors.
EU Medical Device Regulation (MDR) Article 117 requirements for notified body involvement in combination product reviews are extending time-to-certification for drug-device valve systems. Manufacturers with legacy CE certificates under the Medical Device Directive face mandatory technical documentation upgrades. Transcatheter platforms with integrated antithrombotic coatings encounter the most significant compliance friction.
Hospital procurement committees are consolidating vendor contracts around full-procedure bundles that include imaging, access equipment, and valve systems under single-source agreements. Independent cardiac centers are losing negotiating leverage to integrated delivery networks with centralized supply chain authority. This concentration is most visible in the United States, where health system mergers have reduced the number of independent valve purchasers by half over the past decade.
Heart Valves Market Segmentation
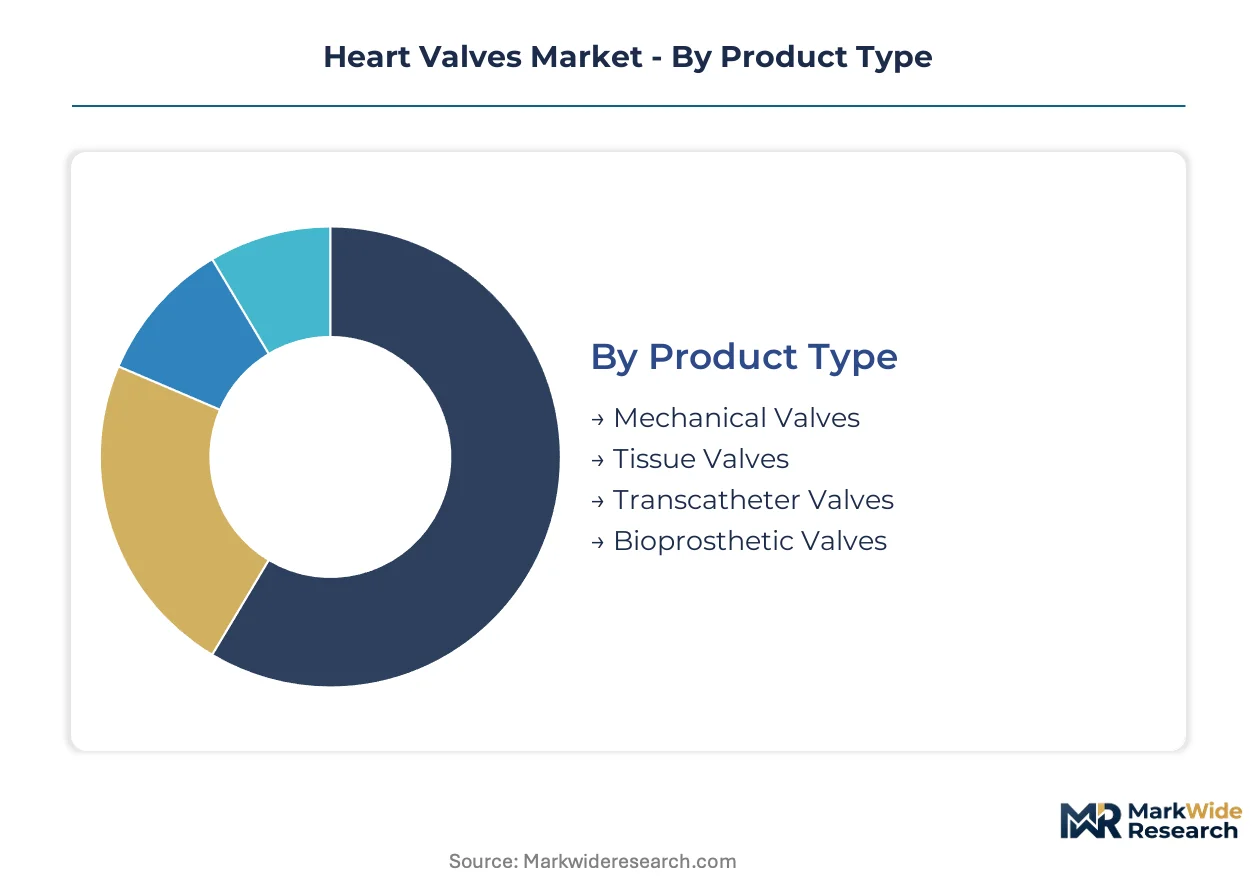
Heart valve segmentation reveals divergent margin profiles across implant technologies and care settings. Product type stratification separates durable mechanical platforms from recurring-revenue bioprosthetic systems, while delivery mode distinctions reshape site-of-service economics.
Product Type:
After-sales service intensity varies sharply across valve categories, with transcatheter systems requiring specialized technical support and physician training ecosystems that mechanical valve manufacturers rarely provide.
- Mechanical Valves:Pyrolytic carbon leaflets and titanium housings deliver durability exceeding 25 years in hemodynamically active patients. Demand concentrates in Germany and Japan where younger surgical candidates prioritize longevity over anticoagulation management, though warfarin monitoring burdens limit expansion in outpatient-focused US systems.
- Tissue Valves:Bovine pericardium and porcine xenograft constructions eliminate lifelong anticoagulation but degrade within 10-15 years. Cardiac surgery departments in the United States favor these for elderly patients where valve-in-valve procedures extend lifetime value, creating recurring intervention demand that reshapes manufacturer-purchaser relationships.
- Transcatheter Valves:Nitinol frames with pericardial leaflets deploy via femoral access without sternotomy. Cath-lab infrastructure investments in Germany and the United States accelerate adoption.
- Bioprosthetic Valves:Tissue-engineered constructs combine biological leaflets with synthetic stents. Research institutions pilot next-generation durability enhancements.
By volume, tissue valves lead. By growth pace, transcatheter valves are climbing the fastest.
End User:
Customer concentration patterns split between high-volume integrated networks and specialized independent centers, with procurement authority increasingly centralizing at health system headquarters.
- Hospitals:Integrated delivery networks in the United States consolidate valve purchasing under centralized supply chain committees, extracting volume discounts from manufacturers. German hospital systems similarly aggregate procurement across regional clusters.
- Cardiac Clinics:Independent interventional cardiology centers in Japan and Germany perform outpatient transcatheter procedures outside hospital admissions, capturing margin pools from abbreviated episode payments.
- Research Institutions:Academic medical centers conduct IDE trials and first-in-human studies for breakthrough device designation pathways. FDA and PMDA submissions originate from these sites.
- Rehabilitation Centers:Post-acute facilities manage anticoagulation therapy and cardiac recovery protocols. These sites generate follow-up data for real-world evidence mandates.
Hospital systems dominate current procurement volume. Cardiac clinics are gaining share fastest as site-of-service shifts accelerate.
Delivery Mode:
Technical complexity and capital equipment requirements stratify delivery approaches, with percutaneous methods demanding entirely different supply chain configurations than surgical platforms.
- Surgical Implantation:Sternotomy-based procedures require cardiopulmonary bypass circuits and dedicated operating suites. German cardiac surgery departments maintain these capabilities for complex redo operations.
- Percutaneous Approach:Femoral access with catheter-based deployment eliminates thoracotomy. Cath-lab operators in the United States and Japan favor this for high-risk surgical candidates.
- Minimally Invasive Techniques:Port-access and robotic-assisted methods reduce recovery times. Specialized valve centers in Germany pioneer these hybrid approaches.
- Open-Heart Surgery:Conventional procedures persist for concomitant coronary bypass or complex congenital repairs. Volume concentrates in academic medical centers.
Percutaneous approaches command premium pricing. Minimally invasive techniques show steepest expansion trajectory among surgical alternatives.
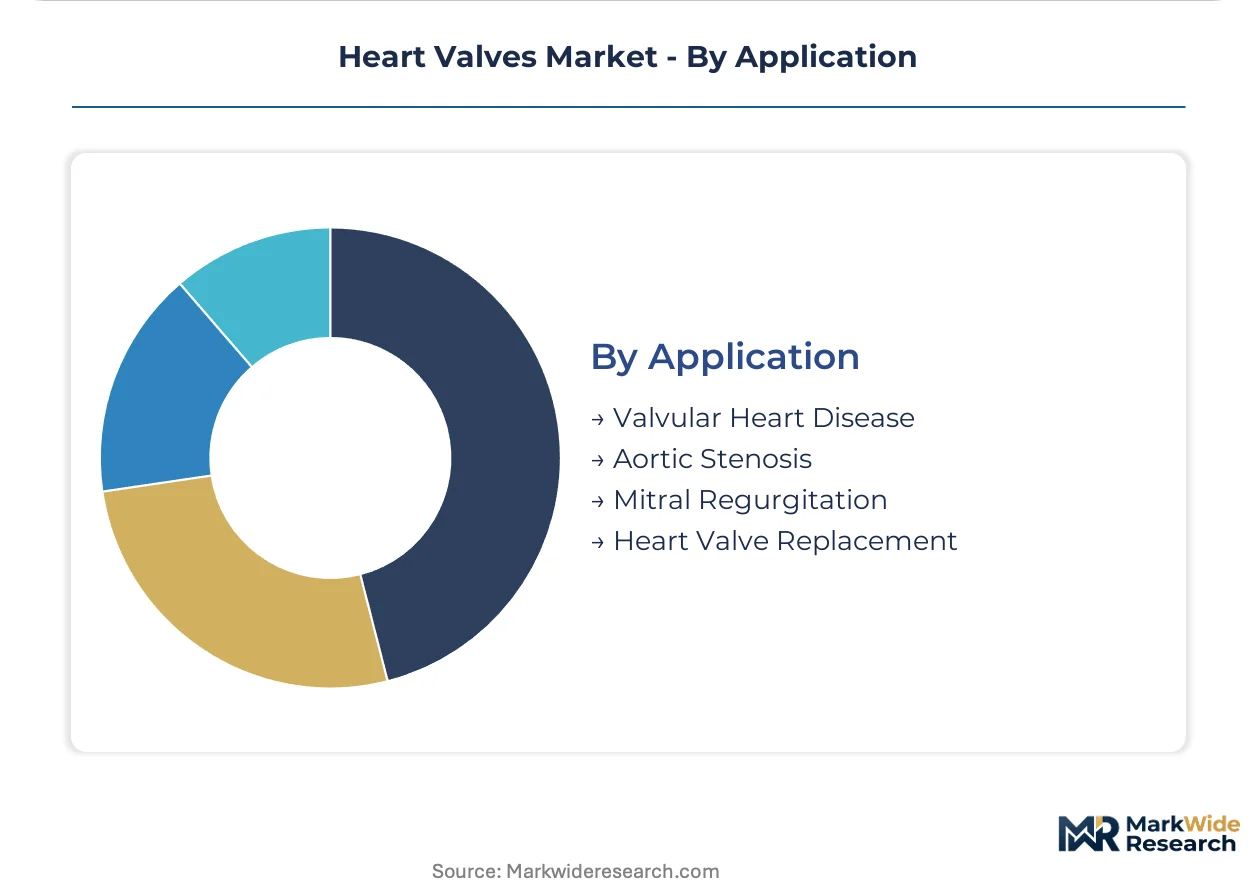
Application:
Clinical indication severity and patient comorbidity profiles determine reimbursement coding and site-of-service eligibility, with aortic pathologies currently dominating addressable procedure volume.
- Valvular Heart Disease:Encompasses stenotic and regurgitant lesions across all four cardiac valves. Aging demographics in Japan and the United States expand the treatable population.
- Aortic Stenosis:Calcific degeneration of the aortic valve represents the largest transcatheter addressable market. FDA-approved indications now extend to low-risk surgical candidates.
- Mitral Regurgitation:Functional and degenerative etiologies drive clip-based repair adoption. German centers lead European volume for transcatheter mitral edge-to-edge repair.
- Heart Valve Replacement:Index procedures and valve-in-valve interventions create recurring revenue streams. Bioprosthetic degradation cycles ensure sustained manufacturer engagement.
Aortic stenosis procedures generate highest current volume. Mitral regurgitation applications are expanding most quickly as repair platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transcatheter valve deployment patterns diverge sharply by geography: German cath-labs favor same-day discharge protocols, while Japanese reimbursement structures still incentivize extended observation. These consumption-mix differentials reshape manufacturer go-to-market investments across the three largest valve markets.
United States
Integrated delivery networks in Texas and the Midwest concentrate transcatheter aortic replacement volume under centralized procurement committees. FDA breakthrough device designations for mitral platforms accelerate site-of-service expansion into outpatient settings. Cleveland Clinic and Mayo Clinic anchor physician training ecosystems that diffuse technique adoption regionally.
Germany
G-DRG reimbursement realignment favors abbreviated cath-lab episodes over surgical admissions in Bavaria and North Rhine-Westphalia. EMA conditional approval pathways compress time-to-market for novel valve platforms relative to US timelines. Heidelberg and Leipzig university hospitals pioneer valve-in-valve degradation monitoring protocols that inform EU post-market surveillance.
Japan
Aging demographics in Kanto and Kansai regions create underpenetrated demand for transcatheter mitral repair among elderly surgical-risk patients. PMDA's streamlined review for breakthrough devices accelerates commercialization lag versus historical five-year gaps. Tokyo and Osaka academic centers conduct first-in-human studies that anchor Asia-Pacific clinical evidence generation.
Heart Valves Market Vendor Landscape
Capability concentration sits with specialized transcatheter developers; scale advantage sits with diversified cardiovascular conglomerates. The market structures around three tiers: integrated multinationals with surgical and percutaneous portfolios, pure-play transcatheter specialists with physician training ecosystems, and emerging synthetic leaflet developers. Dominant competitive moves include cath-lab infrastructure partnerships and direct-to-hospital contracting that bypasses distributor intermediaries.
Among integrated multinationals, Edwards Lifesciences Corporation and Medtronic plc exemplify divergent scale-coverage strategies, while Abbott occupies a distinct position in repair-focused platforms. These three entities anchor the competitive perimeter through specialized training networks and site-of-service economics capture.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott |
| Boston Scientific Corporation |
| LivaNova |
| JenaValve Technology |
| Artivion |
| Corcym |
| Foldax Inc. |
| Others |
Supply Flow & Price Mechanics
Transpacific air freight corridors from Frankfurt and Memphis to Osaka and Singapore carry pyrolytic carbon blanks and bovine pericardium tissue under temperature-controlled conditions, with freight cost volatility compressing margins for mechanical valve manufacturers while enabling premium pricing for rapid-turnaround tissue valve orders from German cath-labs.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated delivery networks and valve manufacturers, locking in volume commitments that insulate against bovine tissue spot price swings. Premium-mid-economy pricing differentiation separates transcatheter systems with FDA breakthrough designation from standard surgical platforms and commodity mechanical valves. Cost compression in the tissue valve tier is intensifying because cardiac surgery departments face bundled payment pressure from CMS reimbursement realignment. Independent cardiac clinics exhibit highest price sensitivity due to capital constraints, while academic medical centers with research funding tolerate premium positioning.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements between nitinol frame manufacturers in Ireland and Germany and their downstream valve assembly partners in California and Minnesota. Pyrolytic carbon machining capacity concentrates in the United States, Germany, and Japan, while bovine pericardium sourcing draws from controlled herds in Australia and New Zealand. Single-source vulnerability in specialized polymer leaflet production from emerging synthetic suppliers creates supply chain risk. Distribution runs through GPO contracts and direct-to-hospital agreements that bypass traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designation for transcatheter mitral platforms is compressing commercialization timelines from years to months, creating a high-growth disruption window where first-movers capture cath-lab infrastructure partnerships before competitors complete regulatory submissions.
For Market Incumbents: Pre-empt synthetic leaflet displacement by securing exclusive supply agreements with thermoplastic polyurethane developers before polymeric valves achieve ISO 5840 fatigue certification. Anchor backward integration into bovine tissue processing to defend against biosecurity disruptions and input cost volatility from concentrated Australian herd sources. For New Entrants and Emerging Players: Build out physician training ecosystems in Japan's Kanto and Kansai regions where transcatheter mitral penetration remains underdeveloped relative to aortic replacement saturation. Target independent cardiac centers in Germany seeking to bypass integrated hospital network procurement committees through direct contracting relationships. For Investors and Strategic Acquirers: Specialized transcatheter training platform developers with established Heidelberg or Leipzig academic center relationships represent priority acquisition targets. Long-term viability hinges on capturing recurring valve-in-valve procedure revenue streams rather than index implant market share alone. Watch for EMA conditional approval pathway utilization rates as inflection signal for European commercialization speed.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures GPO contract access and locks in multi-year valve procurement commitments from integrated delivery networks. |
| CE Marking Pathway | Accelerates EU market entry under MDR Article 117 for drug-device combination valve systems. |
| Software Companion Development | Integrates AI-enabled CT planning tools with robotic navigation for precision deployment in complex anatomies. |
| Reimbursement Strategy | Aligns CMS outpatient procedure coding with G-DRG structures to capture site-of-service economics. |
| FDA Submission | Pursues breakthrough device designation for transcatheter tricuspid platforms to compress trial timelines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, cardiac surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, EMA conditional approval records, CMS reimbursement coding databases, and ISO 5840 certification registries. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue allocations.
Forecast inputs across the projection horizon incorporated product type segmentation by mechanical, tissue, transcatheter, and bioprosthetic platforms; delivery mode stratification across surgical, percutaneous, and minimally invasive approaches; and end-user concentration patterns between integrated delivery networks and independent cardiac centers. CAGRs were derived from elasticity modeling against aging demographic projections and cath-lab infrastructure investment cycles, with transcatheter adoption curves weighted by PMDA and FDA approval pathway velocity.
Stress conditions across bovine tissue supply disruption, EMA post-market surveillance stringency escalation, and anticoagulation therapy compliance rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement alignment and regulatory pathway efficiency. Macroeconomic contraction, biosecurity events affecting controlled herds, or synthetic leaflet durability breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Drainage Sets Market