
 Global Extracorporeal Membrane Oxygenation Machine Market | 2026-2036
Global Extracorporeal Membrane Oxygenation Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extracorporeal Membrane Oxygenation Machine Market Foresight
Market Context
A shortage of certified ECMO specialists and perfusionists is reorganizing how hospitals scale extracorporeal programs, forcing device manufacturers to simplify console interfaces and automate anticoagulation monitoring. Getinge AB leverages its integrated life-support portfolio to dominate European cardiothoracic installations. Medtronic anchors North American hospital networks through long-term service contracts and training academies. Fresenius Medical Care differentiates via dialysis-ECMO hybrid platforms that occupy the bridge-to-transplant segment.
Technical Definition and Segment Structure
Extracorporeal Membrane Oxygenation Machines are external life-support systems that oxygenate blood and remove carbon dioxide through a membrane oxygenator when native lung or heart function fails, typically operating at blood flow rates of 2–7 liters per minute depending on patient size and cannulation configuration. Veno-venous ECMO leads volume for respiratory failure in intensive care units, while portable ECMO configurations represent the fastest-growing sub-category as emergency medical services seek field-deployable options. Centrifugal pump systems command the technology segment due to lower hemolysis rates and quieter operation, though microprocessor-controlled systems are capturing margin pools through integrated safety algorithms.
Regulatory Frame and Outlook
The FDA enforces 510(k) clearance and quality system regulation for ECMO devices in the United States, while the EMA's Medical Device Regulation mandates clinical evidence and post-market surveillance across Europe, with Japan's PMDA requiring local clinical trials for novel oxygenator materials. These frameworks elevate barriers for new entrants but protect incumbent positions for firms with established regulatory dossiers. Stakeholders must monitor how FDA breakthrough device designations and EU AI Act risk classifications reshape competitive access for algorithm-driven perfusion management tools.
Market Dynamics
The ECMO market faces acute pressure from a worldwide deficit of certified perfusionists and ECMO specialists, compelling device manufacturers to automate anticoagulation monitoring and simplify console interfaces for non-specialist operators.
Growth Catalysts
- ICU Infrastructure Expansion:Hospital systems in Germany, Japan, and the United States are establishing ECMO center accreditation programs that mandate minimum case volumes and equipment standards.
- 510(k) Pathway Maturation:The FDA's streamlined premarket notification process for oxygenator biocompatibility testing accelerates device iterations while maintaining safety benchmarks.
- Bridge-to-Transplant Protocols:Cardiothoracic surgery departments are integrating ECMO as standard temporizing therapy for patients awaiting heart or lung transplantation.
Market Restraints
- Silicone Membrane Supply Concentration:Three specialty polymer suppliers in Germany and Japan control downstream access to high-purity silicone sheeting for hollow-fiber oxygenators.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates costly post-market surveillance studies that extend recertification timelines for legacy oxygenator platforms.
- CRRT Substitution Threat:Continuous renal replacement therapy systems with integrated CO2 removal modules are capturing select respiratory failure cases in cost-sensitive hospital systems.
Strategic Opportunities
- Emergency Medical Services Deployment:Portable ECMO configurations are penetrating ambulance and helicopter emergency response networks in Australia and South Korea.
- AI-Act Compliance Advantage:The EU's risk classification framework for algorithm-driven perfusion management creates first-mover benefits for firms with validated safety algorithms.
- Hybrid Dialysis-ECMO Platforms:Convergence of renal replacement and extracorporeal oxygenation technologies opens the bridge-to-recovery segment for multi-organ failure patients.
Industry Challenges
- Perfusionist Training Bottleneck:Accredited ECMO specialist programs produce fewer than four hundred certified practitioners annually across the United States, constraining program expansion.
- Oxygenator Shelf-Life Management:Disposable circuit components require temperature-controlled logistics with strict expiration tracking, complicating inventory positioning for rural hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extracorporeal Membrane Oxygenation Machine Market |
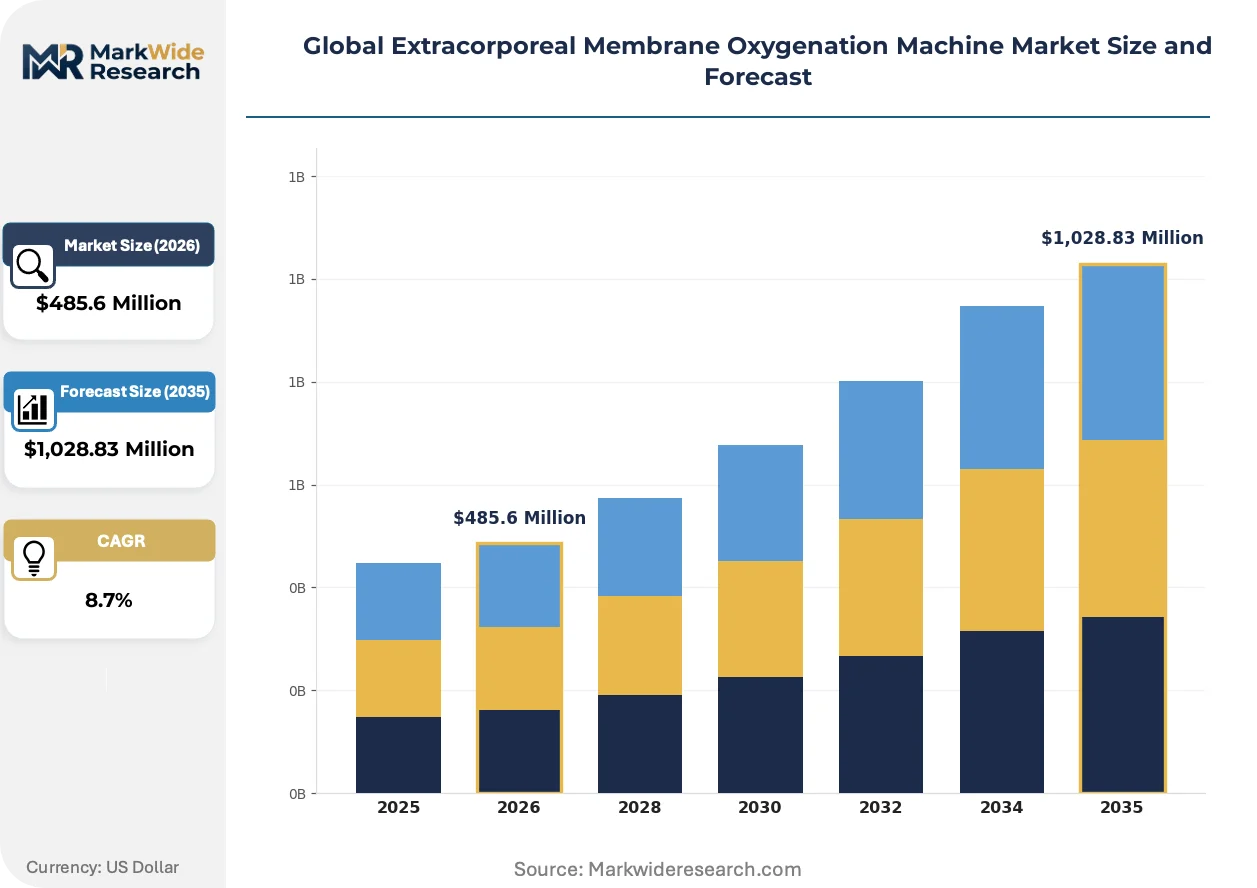
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,028.83 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veno-Venous ECMO, Veno-Arterial ECMO, Portable ECMO, Standalone ECMO Technology: Rotary Pump Systems, Centrifugal Pump Systems, Roller Pump Systems, Microprocessor-Controlled Systems Application: Respiratory Failure, Cardiogenic Shock, Cardiac Arrest, Bridge to Transplant End User: Cardiothoracic Surgery Units, Intensive Care Units, Neonatal Care Units, Emergency Care Facilities |
| Companies Covered | Getinge AB, Medtronic, LivaNova PLC, Terumo Corporation, Fresenius Medical Care, Nipro Corporation, Eurosets, ABIOMED, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extracorporeal Membrane Oxygenation Machine Market Shifts & Advancements
Algorithmic control systems and miniaturized pump architectures are redefining competitive differentiation in extracorporeal life support, shifting value capture from hardware durability toward real-time clinical decision support.
Magnetic levitation centrifugal pump technology is fragmenting the traditional roller pump installed base by eliminating mechanical bearing contact and reducing hemolysis rates below three grams per liter. Pediatric cardiac centers in the United States and tertiary hospitals in Japan are adopting these systems for prolonged respiratory support exceeding fourteen days. The technology is fragmenting procurement patterns as buyers prioritize disposable cartridge compatibility over console longevity.
The EU AI Act's risk-based classification framework is compelling manufacturers to document algorithmic transparency for microprocessor-controlled perfusion systems. This regulatory pressure is elevating development costs for safety interlock software while creating compliance moats around established regulatory dossiers. Class III high-risk device designations are concentrating investment in European notified body relationships among incumbent firms.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, forcing manufacturers to compete on discrete training, maintenance, and consumable pricing. This behavioral shift is most pronounced in German university hospital networks and Japanese prefectural medical centers with centralized supply chain governance. Vendors are responding with modular service tiers and outcome-guarantee pilot programs.
Global Extracorporeal Membrane Oxygenation Machine Market Segmentation
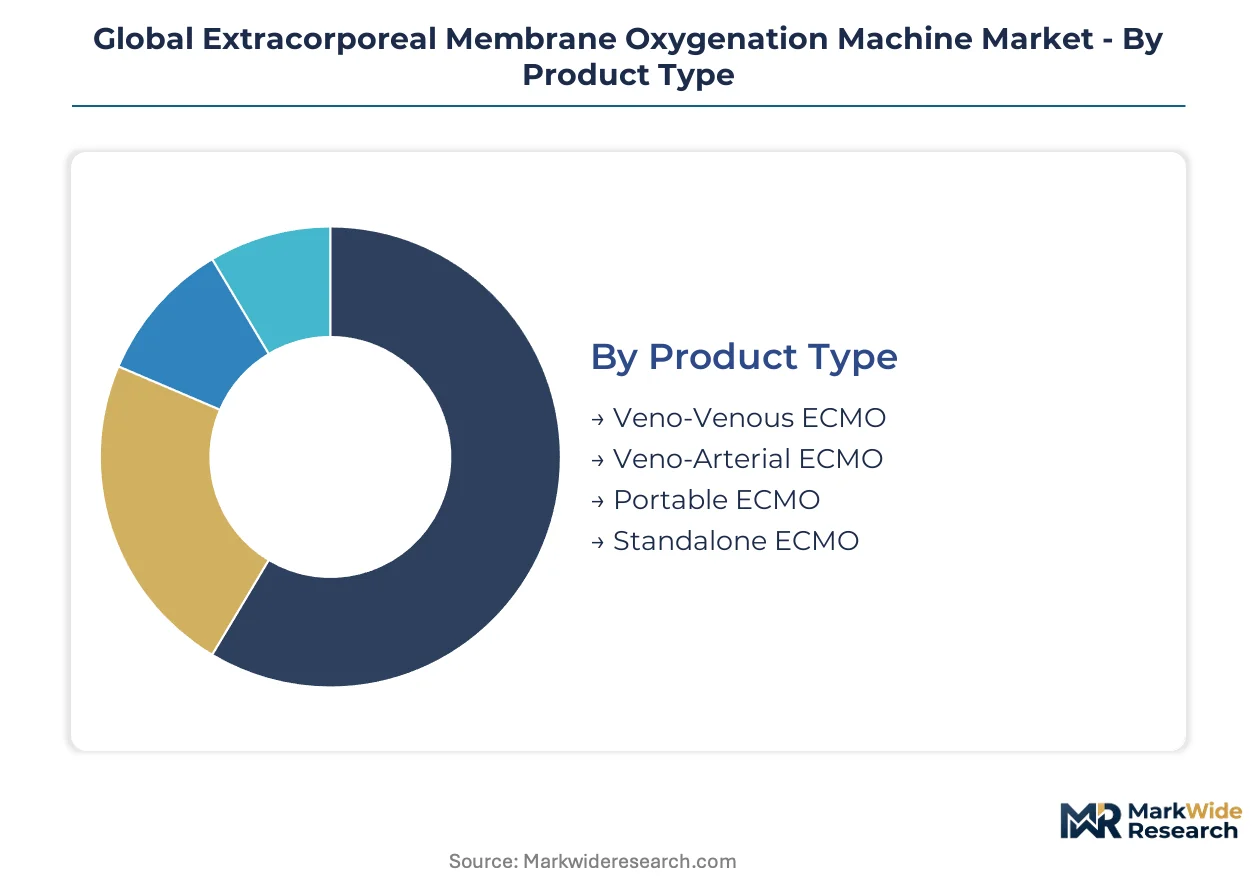
Segmentation in the ECMO market reveals how clinical specialization and regulatory pathways fragment procurement decisions across hospital departments. Product configurations and technology choices diverge sharply between established transplant centers and expanding emergency response networks.
Product Type:
Veno-venous configurations dominate domestic hospital installations in the United States and Germany, while portable systems drive export-led demand from Australian and South Korean emergency medical services.
- Veno-Venous ECMO:Dual-lumen cannulation routes deoxygenated blood from the venous system through the oxygenator and returns it to the right atrium, bypassing the pulmonary circuit entirely. Demand concentrates in German university hospitals managing acute respiratory distress syndrome, constrained by the EU MDR's extended recertification timelines for legacy oxygenator platforms.
- Portable ECMO:Miniaturized pump-oxygenator units with battery backup and compact consoles enable pre-hospital deployment in ambulances and helicopter fleets. Australian and South Korean emergency response networks are expanding field-deployable programs fastest, though perfusionist training bottlenecks limit scaling.
- Veno-Arterial ECMO:Supports both cardiac and pulmonary function through femoral venous drainage and arterial return, standard in cardiogenic shock protocols.
- Standalone ECMO:Fixed-installation consoles with integrated monitoring, preferred by Japanese tertiary centers for prolonged support exceeding fourteen days.
Veno-venous ECMO commands the established base. The steepest expansion runs through portable configurations.
Technology:
Cost tier differentiation separates premium magnetic levitation systems from standard mechanical bearing pumps, with microprocessor-controlled platforms capturing margin pools through integrated safety algorithms.
- Centrifugal Pump Systems:Impeller-driven blood flow eliminates roller compression, reducing hemolysis below three grams per liter during prolonged support. Pediatric cardiac centers in the United States and tertiary hospitals in Japan prioritize these systems for cases exceeding fourteen days, with procurement patterns shifting toward disposable cartridge compatibility.
- Microprocessor-Controlled Systems:Algorithmic perfusion management integrates real-time flow monitoring, bubble detection, and pressure-limiting interlocks through embedded software. The EU AI Act's Class III risk designation elevates development costs while creating compliance moats around established regulatory dossiers.
- Rotary Pump Systems:Compact rotary mechanisms enable miniaturization for portable configurations, common in Australian emergency medical deployments.
- Roller Pump Systems:Peristaltic compression technology retains installed base in cost-sensitive hospital systems, though hemolysis rates limit prolonged use.
Centrifugal pump systems anchor current revenue. Microprocessor-controlled platforms are climbing the fastest as algorithmic safety features become procurement requirements.
Application:
Volume concentration in respiratory failure reflects ICU infrastructure expansion, while bridge-to-transplant protocols concentrate in specialized cardiothoracic centers with established organ procurement relationships.
- Respiratory Failure:Veno-venous cannulation for acute hypoxic respiratory failure constitutes the dominant application, with German hospital networks establishing ECMO center accreditation programs that mandate minimum case volumes and equipment standards.
- Bridge to Transplant:Temporizing support for patients awaiting heart or lung transplantation requires integrated multidisciplinary teams. United States transplant centers with long-term service contracts from incumbent manufacturers dominate this segment.
- Cardiogenic Shock:Veno-arterial support for pump failure following myocardial infarction, standard in Japanese emergency cardiac care protocols.
- Cardiac Arrest:Extracorporeal cardiopulmonary resuscitation (ECPR) deployment in refractory cases, expanding fastest in South Korean metropolitan hospital networks.
Respiratory failure captures the largest patient volume. Bridge-to-transplant applications are gaining share fastest as organ waitlists lengthen.
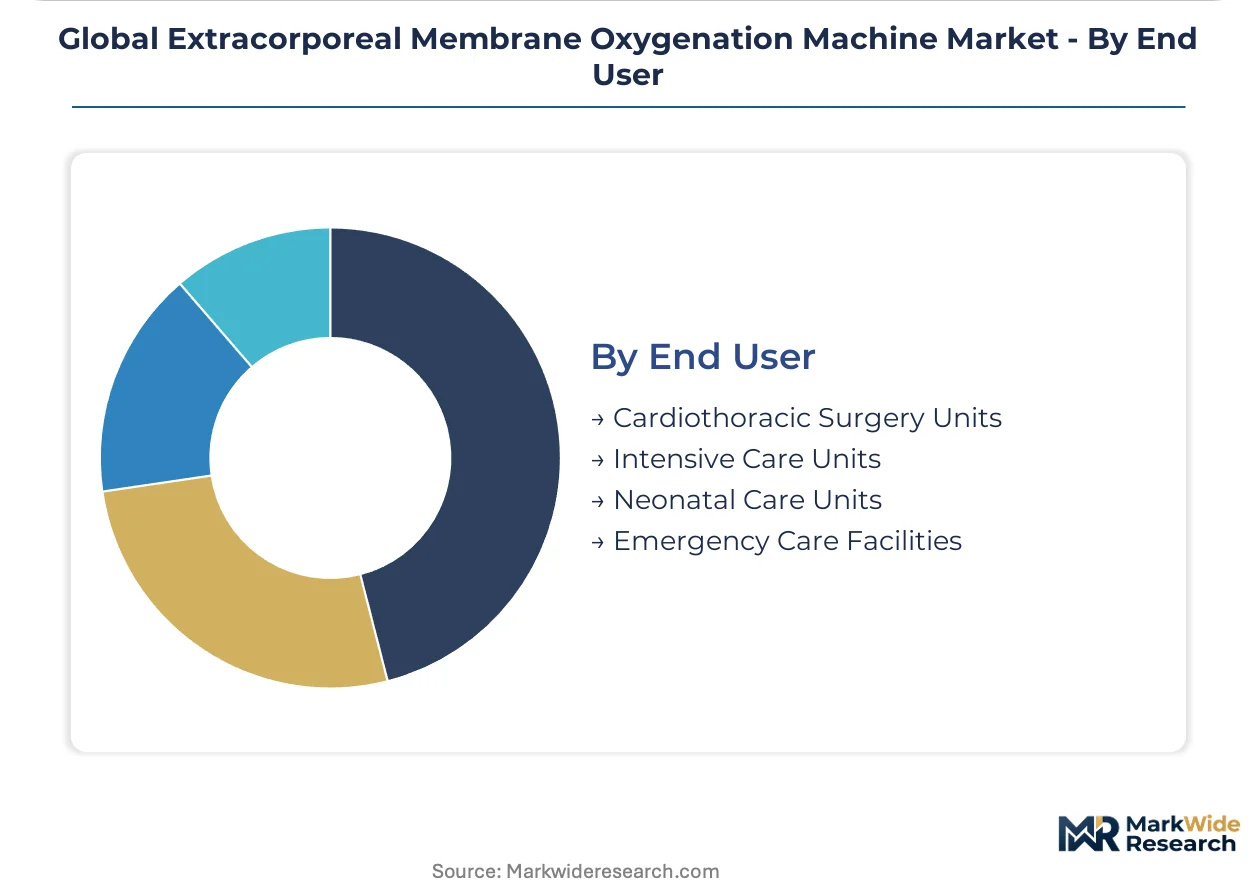
End User:
Customer type segmentation tracks the divergence between established surgical programs with captive perfusionist staff and expanding ICU deployments requiring simplified operator interfaces.
- Intensive Care Units:Non-surgical ECMO programs for respiratory failure require console designs that enable intensivist-led management without continuous perfusionist presence. Device manufacturers are automating anticoagulation monitoring and simplifying interfaces to address specialist shortages in United States community hospitals.
- Cardiothoracic Surgery Units:Established programs with dedicated perfusion teams manage complex cannulation and prolonged support, concentrated in German university hospitals and Japanese tertiary centers with centralized supply chain governance.
- Neonatal Care Units:Specialized low-flow systems for congenital cardiac defects and persistent pulmonary hypertension, with demand concentrated in United States children's hospitals.
- Emergency Care Facilities:Rapid-deployment protocols for refractory cardiac arrest and pre-hospital stabilization, expanding in Australian and South Korean emergency medical services networks.
Intensive care units are expanding most quickly as non-specialist deployment models mature. Cardiothoracic surgery units retain the highest revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor North American market access, while EMA Medical Device Regulation and Japan PMDA frameworks shape competitive entry across other concentrated geographies. Hospital accreditation programs and specialist training bottlenecks vary sharply by country.
United States
ECMO center accreditation programs through the Extracorporeal Life Support Organization mandate minimum case volumes and equipment standards. FDA 510(k) clearance pathways for oxygenator biocompatibility testing accelerate device iterations while maintaining safety benchmarks. Tertiary medical centers in Boston and Houston concentrate bridge-to-transplant protocols with integrated multidisciplinary teams.
Germany
University hospital networks establish ECMO center accreditation programs requiring standardized equipment and perfusionist staffing. EU Medical Device Regulation mandates costly post-market surveillance studies that extend recertification timelines for legacy oxygenator platforms. The Baden-Württemberg and Bavaria regions concentrate cardiothoracic installations with centralized supply chain governance.
Japan
PMDA requires local clinical trials for novel oxygenator materials, elevating barriers for new entrants. METI-funded initiatives expand ECMO specialist training programs to address perfusionist shortages. Tokyo and Osaka metropolitan hospital networks lead adoption of prolonged respiratory support configurations exceeding fourteen days.
Australia
Emergency medical services networks in New South Wales and Victoria expand field-deployable portable ECMO programs fastest. TGA registration pathways align with EU MDR clinical evidence requirements for streamlined market entry. Helicopter emergency response fleets in Queensland and Western Australia pilot rapid-deployment protocols for refractory cardiac arrest.
South Korea
Metropolitan hospital networks in Seoul and Busan expand extracorporeal cardiopulmonary resuscitation deployment for refractory cardiac arrest cases. MFDS regulatory frameworks emphasize post-market surveillance for algorithm-driven perfusion management systems. Daegu-Gyeongbuk medical clusters concentrate pediatric cardiac ECMO programs with dedicated perfusion teams.
Global Extracorporeal Membrane Oxygenation Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the ECMO market structure. The upper tier commands hospital network relationships through long-term service contracts and training academies, while mid-cap specialists differentiate via technology licensing and geographic niche focus. Three strategic archetypes dominate: integrated life-support conglomerates with diversified critical care portfolios, pure-play extracorporeal specialists with concentrated R&D pipelines, and dialysis-ECMO hybrid platform developers. Competitive moves concentrate on M&A for regulatory dossier accumulation and strategic partnerships for emergency medical services distribution.
Among integrated life-support conglomerates, Getinge AB and Fresenius Medical Care exemplify archetypes spanning European cardiothoracic installations and bridge-to-transplant segments. Medtronic occupies a position anchoring North American hospital networks through service contract structures. These three represent the dominant competitive anchors, with Terumo Corporation and LivaNova PLC sitting within the specialist tier focused on oxygenator technology and pump system refinement.
| Leading Market Players |
|---|
| Getinge AB |
| Medtronic |
| LivaNova PLC |
| Terumo Corporation |
| Fresenius Medical Care |
| Nipro Corporation |
| Eurosets |
| ABIOMED |
| MicroPort Scientific Corporation |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers and EU MDR conformity assessment levels simultaneously gate supplier qualification and stratify price levels across oxygenator platforms, compressing margin pools for uncertified entrants while rewarding established dossiers with premium positioning.
Pricing Analysis
Japanese metropolitan hospitals pay thirty to fifty percent premiums over German university networks for identical centrifugal pump configurations, reflecting PMDA-mandated local clinical trial costs embedded in landed pricing. Three-tier pricing structure across premium magnetic levitation, standard mechanical bearing, and economy roller pump tiers dominates procurement. Cost compression in economy tiers intensifies as Chinese manufacturers enter rotary pump segments. Emergency medical services in Australia and South Korea exhibit highest price sensitivity due to budget-constrained public tenders.
Supply Chain Analysis
Strategic stockpiling of silicone membrane sheeting and hollow-fiber oxygenator cartridges dominates procurement behavior given six-to-twelve-month shelf-life constraints and temperature-controlled logistics requirements. High-purity silicone production concentrates in Germany and Japan, with specialty polymer finishing in the United States. Raw material sourcing draws from medical-grade silicone feedstock, polypropylene hollow fibers, and heparin coating reagents. Single-source vulnerability runs through three German and Japanese polymer suppliers controlling oxygenator membrane grade material. Distribution runs through authorized device distributors with certified cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusionist training bottlenecks and regulatory dossier accumulation timelines create durable capability moats that favor incumbents with established service infrastructures, while fragmenting access for capital-constrained entrants.
For Market Incumbents: Secure exclusive supply agreements with German and Japanese silicone membrane suppliers to foreclose competitor access to oxygenator-grade material. Deepen backward integration into heparin coating chemistry to capture margin pools currently held by specialty reagent vendors. Counter continuous renal replacement therapy substitution threats by bundling hybrid dialysis-ECMO platforms under unified service contracts. For New Entrants and Emerging Players: Anchor in Australian and South Korean emergency medical services networks where portable ECMO procurement lacks entrenched incumbent relationships. Target field-deployable configurations with simplified operator interfaces that circumvent perfusionist staffing constraints. Pursue TGA and MFDS registration pathways that leverage EU MDR clinical evidence packages for streamlined market entry. For Investors and Strategic Acquirers: EU AI Act Class III risk designations for algorithm-driven perfusion management reshapes the acquisition landscape toward firms with validated safety interlock software and European notified body relationships. Five-to-ten-year viability hinges on regulatory dossier depth rather than hardware innovation velocity. Prioritize targets holding FDA breakthrough device designations for AI-integrated perfusion systems. Watch FDA guidance document releases on algorithmic transparency requirements as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Class III risk designation creates compliance moats around established safety algorithm dossiers. |
| Hospital System Partnership | Long-term service contracts with United States transplant centers lock out competing console vendors. |
| Backward Integration into Silicone Supply | Captive access to German and Japanese membrane-grade polymer secures oxygenator production continuity. |
| Software Companion Development | Algorithmic perfusion management tools capture margin pools shifting from hardware to clinical decision support. |
| Reimbursement Strategy | Bridge-to-transplant coding alignment with CMS Medicare coverage accelerates United States hospital adoption. |
Research Methodology
Operator-level perspectives from ECMO specialists, perfusionists, hospital purchasing committee members, and biomedical engineers anchored the qualitative base, cross-referenced against FDA 510(k) filings, EMA MDR technical documentation, PMDA approval summaries, and hospital procurement database extracts. Bottom-up equipment installation tracking across German university networks, Japanese tertiary centers, and United States transplant programs combined with top-down market sizing through manufacturer revenue attribution.
Sensitivity analysis tested forecast robustness across perfusionist training expansion scenarios, silicone membrane supply disruption events, and EU MDR recertification timeline extensions. Segmentation modeling spanned product configuration, pump technology tier, cannulation mode, clinical application, and end-user department type across the projection horizon. CAGR derivation incorporated historical installation growth patterns, accreditation program expansion schedules, and algorithmic safety feature adoption curves.
Decision-makers should treat outputs as directional under assumptions of steady regulatory pathway stability and sustained specialist shortage conditions; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement intensity or perfusionist training program graduation rates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market