
 Non-Invasive Pulse Wave Tonometer Market | 2026-2036
Non-Invasive Pulse Wave Tonometer Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Pulse Wave Tonometer Market Analytics
Modular integration of pulse wave analysis with optical coherence tomography is pivoting buyer preference toward multi-function diagnostic platforms. AtCor Medical Pty Ltd. leverages its vascular assessment heritage to anchor positioning in integrated cardiovascular-ophthalmic workflows. Topcon Corporation sustains manufacturing scale across tabletop and portable tonometer configurations. Kowa Company, Ltd. specializes in handheld device miniaturization for point-of-care deployment.
A non-invasive pulse wave tonometer measures arterial pulse wave velocity and central blood pressure through external applanation of a superficial artery, typically the radial or carotid, using a pressure-sensitive transducer array with sampling rates exceeding 1,000 Hz for waveform fidelity. The instrument serves cardiologists, ophthalmologists, and vascular specialists in detecting early arterial stiffness and stratifying cardiovascular risk without catheterization. Handheld devices dominate ambulatory and home care channels where portability commands premium positioning, while integrated systems capture hospital capital budgets through bundled ophthalmic suite configurations. Optical coherence tomography-enhanced tonometers represent the fastest-growing technology segment as clinicians seek simultaneous structural and functional vascular assessment.
The FDA's 510(k) pathway and the EU Medical Device Regulation shape product validation requirements and commercial timelines for manufacturers targeting the United States and European markets respectively. Japan's PMDA enforces JIS-compliant electromagnetic compatibility standards that filter non-conforming imports from Asian supply chains. Stakeholders must monitor evolving harmonization between ISO 81060-2 blood pressure measurement standards and ophthalmic-specific IEC 60601-1-2 electromagnetic immunity requirements as dual-certification demands reshape development roadmaps.
Market Dynamics
Modular convergence between pulse wave analysis and optical coherence tomography is compressing capital equipment procurement cycles as hospitals consolidate ophthalmic diagnostic suites into single-vendor platforms.
Growth Catalysts
- Cardiovascular-ophthalmic workflow integration:Hospital systems in the United States are bundling arterial stiffness assessment with glaucoma screening protocols, expanding device utilization rates across dual-specialty departments.
- FDA 510(k) pathway streamlining:Expedited clearance timelines for predicate-based ophthalmic submissions are compressing commercialization cycles for manufacturers with established vascular device portfolios.
- Radial artery applanation miniaturization:Advances in MEMS pressure transducer arrays are enabling handheld form factors that penetrate ambulatory and retail clinic channels previously inaccessible to tabletop systems.
Market Restraints
- Electromagnetic compatibility certification costs:Dual compliance with IEC 60601-1-2 and ISO 81060-2 standards imposes substantial validation burdens on development budgets, particularly for entrants targeting both United States and European markets.
- Japan PMDA import filtering:JIS-compliant electromagnetic immunity requirements create non-tariff barriers that limit Asian supply chain participation in the Japanese market.
- Optical coherence tomography substitution pressure:Standalone OCT systems with integrated pressure measurement modules are capturing budget allocations that previously flowed to dedicated tonometer platforms.
Strategic Opportunities
- Home-based arterial stiffness monitoring:Bluetooth-enabled handheld devices are penetrating direct-to-consumer channels in Germany where cardiovascular self-management programs receive statutory health insurance reimbursement.
- EU Medical Device Regulation harmonization:MDR Article 120 transition provisions are creating first-mover advantages for manufacturers with notified body relationships established before 2024 capacity constraints.
- Telemedicine platform integration:API-enabled tonometer data streams are embedding into remote cardiology workflows, opening recurring revenue models through software subscription layering.
Industry Challenges
- Dual-specialty clinical training deficits:Effective device operation requires competency in both vascular waveform interpretation and ophthalmic pressure measurement protocols, creating sales cycle friction where training infrastructure is underdeveloped.
- Legacy EMR integration complexity:HL7 FHIR connectivity requirements are extending implementation timelines for hospital deployments, particularly where cardiovascular and ophthalmic departments operate separate data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Pulse Wave Tonometer Market |
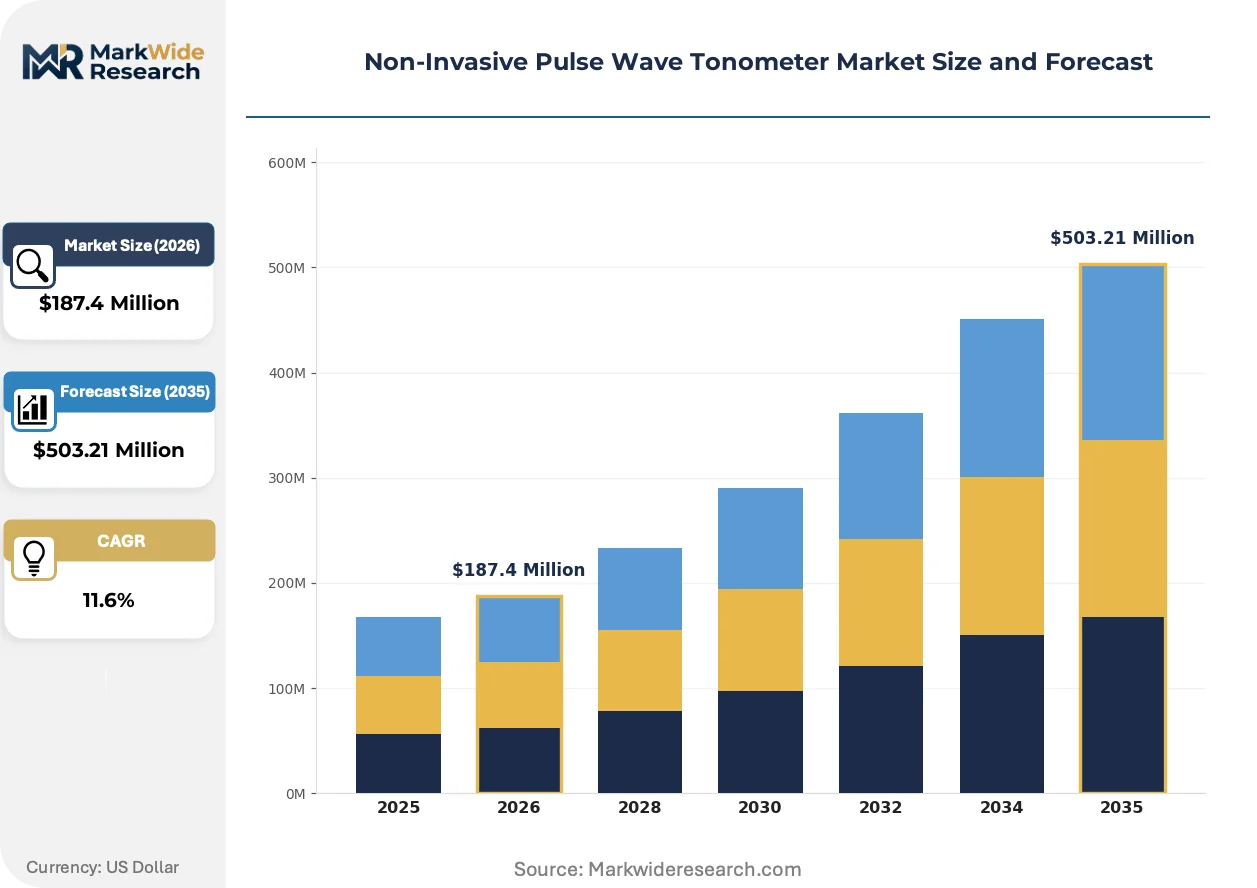
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tabletop Devices, Integrated Systems, Portable Units End User: Ophthalmology Clinics, Hospitals, Research Institutions, Home Care Settings Technology: Pulse Wave Analysis, Optical Coherence Tomography, Aerial Imaging, Radio Waves Application: Glaucoma Screening, Intraocular Pressure Monitoring, Routine Eye Exams, Clinical Research |
| Companies Covered | ADInstruments, Millar, DiaTecne s.r.l., AtCor Medical Pty Ltd., Reichert Technologies, Haag Streit AG, Ametek Industries Technology, Kowa Company, Ltd., Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Pulse Wave Tonometer Market Evolving Landscape
Sensor fusion architectures are displacing standalone measurement modalities as clinicians demand simultaneous structural and functional vascular assessment from single-procedure encounters.
Optical coherence tomography-enhanced pulse wave tonometers are expanding into integrated cardiovascular-ophthalmic diagnostic platforms. Academic medical centers in the United States are adopting these hybrid systems at accelerated replacement cycles, compressing the installed base of standalone devices. This convergence is expanding into multi-specialty revenue capture models that amortize capital costs across departmental budgets.
Japan's PMDA has tightened electromagnetic compatibility enforcement for radial artery measurement devices, requiring JIS C 60601-1-2:2022 compliance for all new market entrants. Domestic manufacturers with established testing infrastructure are capturing share from import-dependent competitors. European manufacturers are responding by establishing Tokyo-based electromagnetic testing partnerships to bypass certification delays.
Hospital procurement committees are consolidating ophthalmic capital allocations into multi-year enterprise agreements with single-vendor platform commitments. Independent ambulatory surgery centers are losing access to preferred pricing tiers as manufacturers reserve volume discounts for integrated health system contracts. This concentration is most visible in the United States, where hospital network consolidation has reduced the addressable independent clinic base by substantial margins over the past five years.
Non-Invasive Pulse Wave Tonometer Market Segmentation
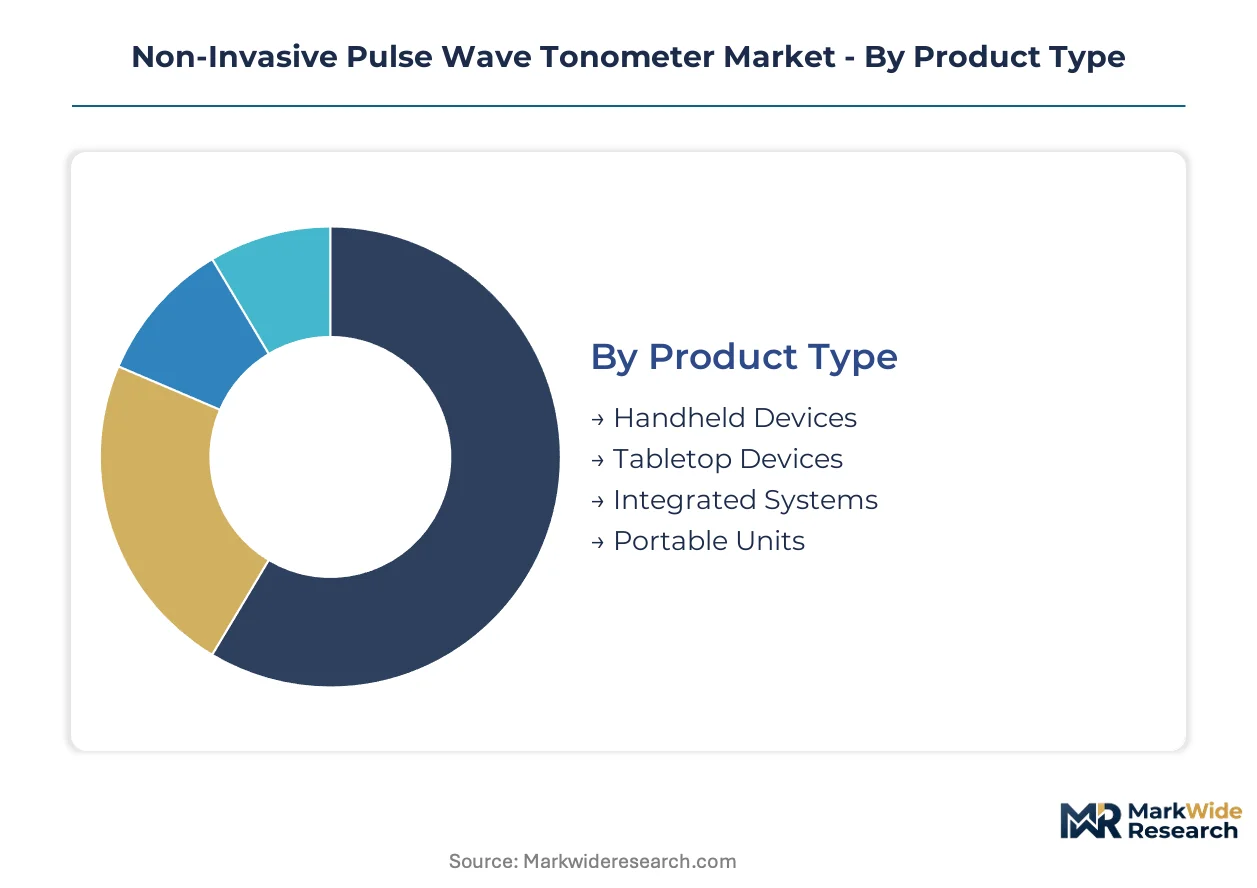
Segmentation in the non-invasive pulse wave tonometer market reveals distinct procurement patterns across clinical settings and technological configurations. Device form factors and integration capabilities determine capital allocation flows between hospital systems and ambulatory channels. Understanding these splits enables manufacturers to align development roadmaps with buyer budget cycles and specialty-specific workflow requirements.
Product Type:
Handheld configurations command premium pricing in mobile care settings while tabletop systems anchor hospital capital budgets through bundled ophthalmic suite purchases.
- Handheld Devices:MEMS pressure transducer arrays enable radial artery applanation at sampling rates exceeding 1,000 Hz within sub-200 gram enclosures. Ambulatory surgery centers in the United States are standardizing these units for pre-operative cardiovascular assessment where space constraints prohibit fixed installations.
- Tabletop Devices:Stationary platforms integrate pneumatic calibration systems and automated positioning arms for reproducible carotid artery measurement protocols. German statutory health insurance reimbursement frameworks favor these configurations in cardiology group practices seeking dual-purpose glaucoma and arterial stiffness screening capabilities.
- Integrated Systems:Multi-modality platforms combining pulse wave analysis with optical coherence tomography capture enterprise-level procurement commitments from academic medical centers.
- Portable Units:Wheeled cart-based configurations bridge the gap between handheld mobility and tabletop precision for hospital department sharing arrangements.
Today's leader: Tabletop Devices. Tomorrow's challenger: Handheld Devices.
End User:
Procurement authority concentrates in hospital network procurement committees while research institutions drive early adoption of experimental sensor fusion architectures.
- Hospitals:Integrated health systems in the United States are consolidating cardiovascular and ophthalmic diagnostic capital into single-vendor enterprise agreements spanning three-to-five year replacement cycles. These commitments amortize equipment costs across departmental budgets while standardizing EMR integration protocols.
- Ophthalmology Clinics:Independent specialty practices prioritize tabletop configurations with standalone operation capabilities where IT infrastructure for networked devices remains underdeveloped.
- Research Institutions:Academic medical centers in Japan and Germany validate novel pulse wave velocity algorithms through PMDA and EMA-aligned clinical trial frameworks.
- Home Care Settings:Direct-to-consumer channels in Germany leverage Bluetooth-enabled handheld devices reimbursable under cardiovascular self-management program statutes.
Hospital procurement committees currently dominate volume; home care reimbursement expansion is climbing the fastest.
Technology:
Sensor fusion architectures are displacing standalone measurement modalities as clinicians demand simultaneous structural and functional vascular assessment from single-procedure encounters.
- Optical Coherence Tomography:Cross-sectional retinal imaging combined with pulse wave analysis enables simultaneous glaucoma screening and central blood pressure estimation. Academic medical centers in the United States are adopting these hybrid systems at accelerated replacement cycles.
- Pulse Wave Analysis:Pressure-sensitive transducer arrays measuring arterial pulse wave velocity remain the foundational technology for cardiovascular risk stratification without catheterization.
- Aerial Imaging:Non-contact optical approaches to pulse detection are emerging in research settings where skin applanation presents measurement artifacts.
- Radio Waves:Electromagnetic sensing modalities for arterial wall motion detection remain experimental with limited commercial deployment.
Optical Coherence Tomography commands current premium positioning; Pulse Wave Analysis maintains the steepest expansion trajectory through miniaturization.
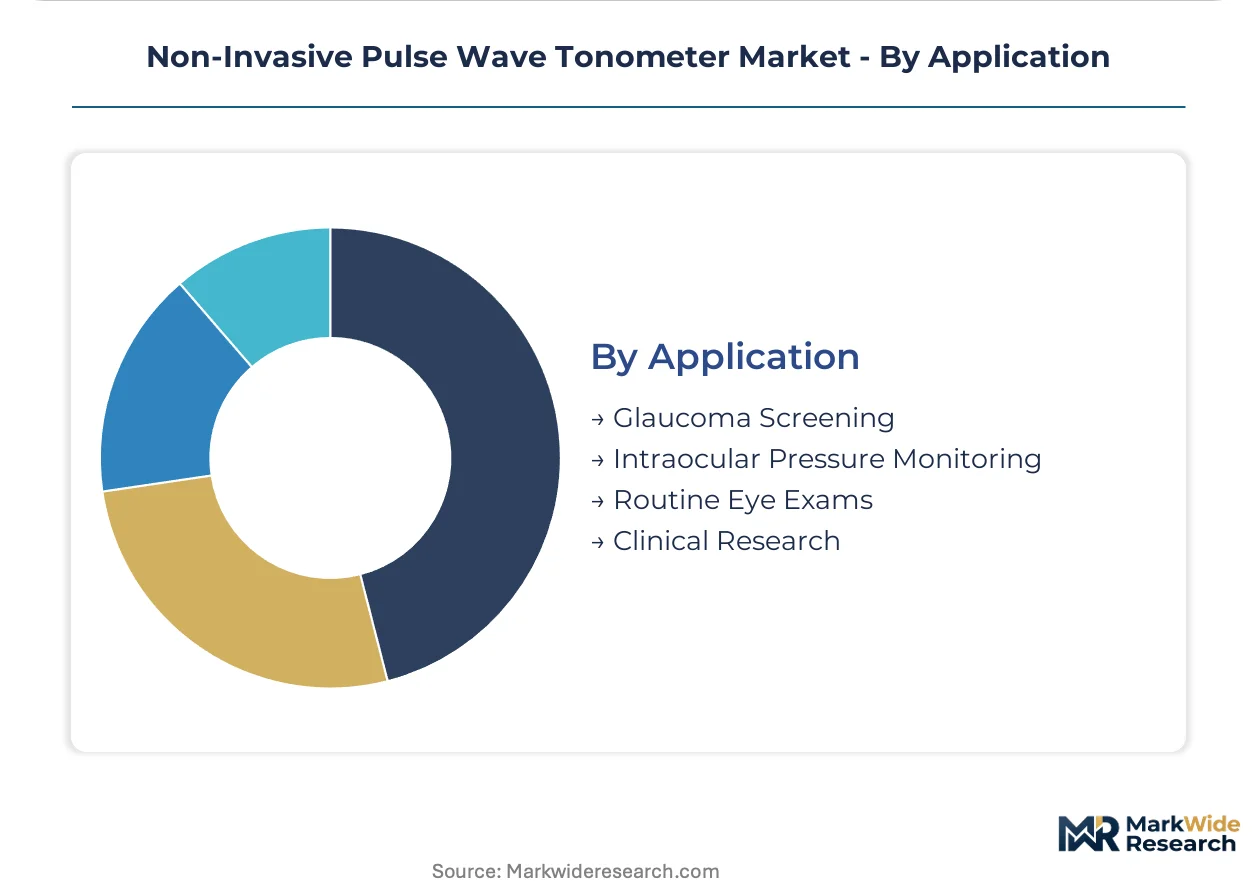
Application:
Clinical utility concentrates in cardiovascular-ophthalmic workflow convergence where single-device platforms capture revenue from previously separate specialty budgets.
- Glaucoma Screening:Intraocular pressure measurement protocols in United States hospital systems are expanding to include arterial stiffness assessment for comprehensive cardiovascular risk profiles during routine ophthalmic encounters.
- Intraocular Pressure Monitoring:Continuous or serial measurement requirements in glaucoma management drive demand for devices with validated repeatability metrics under ISO 81060-2 standards.
- Routine Eye Exams:General optometry practices in Germany incorporate pulse wave velocity screening as value-added services within statutory reimbursement frameworks.
- Clinical Research:Pharmaceutical trials for antihypertensive therapies utilize centralized pulse wave analysis to demonstrate arterial stiffness modification endpoints.
Glaucoma Screening anchors installed base expansion; Clinical Research applications are gaining share fastest through trial protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-invasive pulse wave tonometer technology originated in Japanese and German cardiovascular research laboratories during the 1990s, with commercialization accelerating through United States ophthalmology suites in the 2000s. The installed base now distributes across hospital networks in North America, Western Europe, and East Asia where reimbursement frameworks support dual-specialty diagnostic adoption.
United States
Hospital network consolidation and enterprise procurement agreements drive device standardization across integrated health systems. The FDA's 510(k) pathway for predicate-based ophthalmic submissions compresses clearance timelines for vascular device manufacturers. Academic medical centers in Boston and the Research Triangle anchor clinical validation studies for OCT-enhanced pulse wave platforms.
Germany
Statutory health insurance reimbursement for cardiovascular self-management programs creates direct-to-consumer demand for Bluetooth-enabled handheld devices. The EU Medical Device Regulation's Article 120 transition provisions favor manufacturers with established notified body relationships. Medical technology clusters in Baden-Württemberg and Bavaria host electromagnetic compatibility testing facilities serving continental European certification requirements.
Japan
Aging demographics and established eye care infrastructure sustain clinical uptake of multi-function diagnostic platforms. PMDA enforcement of JIS C 60601-1-2:2022 electromagnetic immunity standards filters non-conforming imports from regional supply chains. Tokyo-based testing partnerships enable European manufacturers to bypass certification delays for radial artery measurement devices.
United Kingdom
NHS procurement frameworks favor tabletop configurations with dual-purpose glaucoma and arterial stiffness screening capabilities. MHRA alignment with EU MDR technical documentation requirements streamlines parallel market access for continental manufacturers. London and Southeast England concentrate private ophthalmology clinic demand for portable unit deployments.
South Korea
MFDS regulatory harmonization with IEC 60601-1-2 standards accelerates approval timelines for MEMS pressure transducer arrays. Seoul Capital Area hospital networks pilot telemedicine platform integration for remote cardiology workflows. Domestic manufacturers leverage semiconductor fabrication expertise to advance sensor miniaturization for point-of-care deployment.
Non-Invasive Pulse Wave Tonometer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification sophistication and dual-specialty clinical training infrastructure. The vendor base organizes into three tiers: integrated health system contractors with enterprise agreement capabilities, ophthalmic suite specialists bundling tonometer modules with capital equipment platforms, and handheld device manufacturers penetrating ambulatory and retail clinic channels. Strategic moves concentrate on M&A for EMR integration capabilities and technology licensing for OCT sensor fusion architectures.
Among Asia-Pacific-based precision instrument specialists, Topcon Corporation and Kowa Company, Ltd. exemplify the ophthalmic suite bundling archetype. AtCor Medical Pty Ltd. occupies a distinct position representing vascular assessment heritage applied to cardiovascular-ophthalmic workflow convergence. These three anchors illustrate the geographic and functional segmentation structuring competitive positioning across hospital procurement committees and ambulatory surgery center buyers.
| Leading Market Players |
|---|
| ADInstruments |
| Millar |
| DiaTecne s.r.l. |
| AtCor Medical Pty Ltd. |
| Reichert Technologies |
| Haag Streit AG |
| Ametek Industries Technology |
| Kowa Company, Ltd. |
| Topcon Corporation |
| Others |
Value Network & Pricing Analysis
EU Medical Device Regulation harmonization gates qualified supply access and premium-tier pricing power for manufacturers navigating notified body capacity constraints. PMDA electromagnetic compatibility enforcement in Japan creates parallel certification barriers that stratify market entry costs across regional supply bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared integrated systems from CE-marked tabletop units and non-certified handheld imports. Certification grade and volume scale drive price differentiation, with hospital enterprise agreements commanding steepest discounts. Cost compression in the standard tier intensifies because OCT-substitution pressure erodes dedicated tonometer premiums. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers prioritize performance metrics over unit economics.
Supply Chain Analysis
Direct-to-hospital contracting handles integrated health system demand while distributor networks serve independent ophthalmology clinics. MEMS pressure transducer arrays draw from semiconductor fabrication clusters in Japan, South Korea, and Taiwan. Optical coherence tomography modules rest on precision optics supply chains anchored in Germany and Japan. Single-source vulnerability in MEMS foundry capacity exposes manufacturers to allocation constraints during demand surges. Distribution runs through specialized medical device distributors with ophthalmic capital equipment expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory milestones into demand acceleration, with FDA 510(k) pathway streamlining for predicate-based ophthalmic submissions driving replacement cycle compression.
For Market Incumbents: Hedge against standalone tonometer substitution by deepening OCT sensor fusion R&D partnerships. Fortify notified body relationships before MDR Article 120 transition deadlines strain certification capacity. Secure electromagnetic testing infrastructure in Tokyo to bypass PMDA import filtering. Anchor enterprise procurement committees through multi-year bundled service contracts.
For New Entrants and Emerging Players: Telemedicine platform integration offers the most penetrable route for API-enabled data streaming into remote cardiology workflows. Target German statutory reimbursement for cardiovascular self-management programs with Bluetooth-enabled handheld configurations. Pursue white-label manufacturing partnerships with established MEMS foundries to bypass capital-intensive fabrication investment.
For Investors and Strategic Acquirers: Roll-up economics work for EMR integration specialists because hospital procurement demands HL7 FHIR connectivity that fragments across cardiovascular and ophthalmic data architectures. Five-to-ten year viability hinges on software subscription layering recurring revenue atop hardware placements. Target acquisition archetype: API-first tonometer data platforms with established hospital system pilots. Signal to watch: telemedicine reimbursement code expansion for remote arterial stiffness monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Notified Body Relationship Establishment | Article 120 transition provisions favor manufacturers with pre-2024 capacity reservations. |
| Tokyo-Based Electromagnetic Testing Partnership | JIS C 60601-1-2:2022 compliance bypasses PMDA certification delays for radial artery devices. |
| Hospital System Enterprise Agreement Pursuit | Three-to-five year procurement commitments amortize capital costs across departmental budgets. |
| Bluetooth-Enabled Handheld Miniaturization | MEMS pressure transducer arrays penetrate German direct-to-consumer reimbursement channels. |
| OCT Sensor Fusion Architecture Licensing | Academic medical center adoption accelerates replacement cycles for hybrid diagnostic platforms. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and ophthalmology clinic directors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, PMDA approval databases, EU MDR technical documentation, and hospital capital equipment procurement records. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations across cardiovascular and ophthalmic diagnostic categories.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through the analytical framework. CAGRs were derived from installed base replacement cycles, reimbursement expansion trajectories, and telemedicine platform penetration curves. Forecast inputs incorporated MEMS component cost curves, electromagnetic certification timeline distributions, and enterprise agreement pricing elasticity assumptions.
Regulatory approval delays, reimbursement code revisions, and OCT substitution acceleration are the dominant revision risks. Forecasts reflect assumptions about notified body capacity normalization, statutory insurance framework stability, and sensor fusion adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market