
 Cardiovascular OCT Imaging Market | 2026-2036
Cardiovascular OCT Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular OCT Imaging Market Outlook
Japan is reconfiguring its cardiovascular imaging supply chain through expanded femtosecond laser manufacturing and precision optics clusters. Abbott leverages its integrated catheter-imaging platform to dominate interventional cardiology workflows across North American hospital networks. Terumo Corporation anchors its position through specialized imaging catheter production with deep ties to Japanese cardiac centers. Carl Zeiss Meditec AG extends its optical expertise from ophthalmology into cardiovascular applications, competing on wavefront engineering capabilities.
Cardiovascular OCT imaging deploys near-infrared light interferometry to generate micron-resolution cross-sectional images of coronary vessel walls, typically operating at 1300 nm wavelength to optimize tissue penetration depth. The technology enables real-time plaque morphology assessment and stent placement guidance during percutaneous coronary intervention. Frequency-Domain OCT systems lead installed base volumes due to faster acquisition speeds that reduce procedural ischemia time, while Swept-Source OCT captures growing interest for its enhanced imaging range in tortuous anatomy. Imaging catheters represent the highest-margin segment because disposable consumption ties directly to procedure volume, whereas optical coherence tomography systems face longer replacement cycles and greater capital budget scrutiny.
FDA premarket notification requirements and the EU Medical Device Regulation shape product development timelines, with CE marking under MDR demanding expanded clinical evidence for intravascular imaging indications. Japan's PMDA reviews cardiovascular devices through a structured consultation pathway that influences Asia-Pacific registration strategies. Stakeholders must monitor evolving CMS coverage determinations for image-guided PCI, as reimbursement parity with intravascular ultrasound will dictate cath lab capital allocation between competing modalities.
Market Dynamics
Hospital procurement committees now weight total cost of ownership against upfront capital expenditure, compressing replacement cycles for optical coherence tomography systems and favoring vendors with integrated catheter-platform ecosystems.
Growth Catalysts
- Image-Guided PCI Reimbursement:Medicare coverage determinations for intravascular imaging during coronary stenting procedures expand cath lab budget allocations toward OCT systems in United States hospital networks.
- Femtosecond Laser Manufacturing:Japan's precision optics clusters advance swept-source light source production, reducing component lead times for next-generation imaging engines.
- Operator Training Infrastructure:Dedicated interventional cardiology fellowship programs at Cleveland Clinic and Heidelberg University Hospital accelerate clinical adoption through standardized credentialing pathways.
Market Restraints
- Disposable Catheter Costs:Single-use imaging catheter pricing constrains procedure economics in publicly funded healthcare systems, particularly Italy and Spain where device budgets face annual caps.
- Capital Equipment Concentration:Frequency-domain OCT system manufacturing concentrates among German and Japanese optical component suppliers, creating vulnerability to regional supply disruptions.
- Intravascular Ultrasound Substitution:IVUS maintains reimbursement parity and established operator familiarity, limiting OCT penetration in cost-sensitive catheterization laboratories.
Strategic Opportunities
- Peripheral Vascular Extension:OCT application in femoropopliteal and renal artery interventions opens procedural volume beyond coronary anatomy, with early clinical validation at Munich's German Heart Center.
- Artificial Intelligence Integration:Real-time plaque characterization algorithms embedded within imaging consoles reduce operator interpretation burden and standardize lesion assessment across experience levels.
- Outpatient Cath Lab Expansion:Ambulatory surgical centers in Texas and Florida deploy compact OCT systems for same-day diagnostic angiography, bypassing hospital capital approval processes.
Industry Challenges
- Optical Engineer Scarcity:Specialized expertise in interferometric system design and fiber-optic catheter fabrication concentrates among aging workforces in Rochester, New York and Jena, Germany optics corridors.
- MDR Clinical Evidence Burden:EU Medical Device Regulation demands expanded prospective trials for intravascular imaging indications, extending CE marking timelines by eighteen to twenty-four months.
- Legacy System Interoperability:Proprietary data formats from first-generation OCT platforms resist integration with modern hospital information systems and picture archiving networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular OCT Imaging Market |
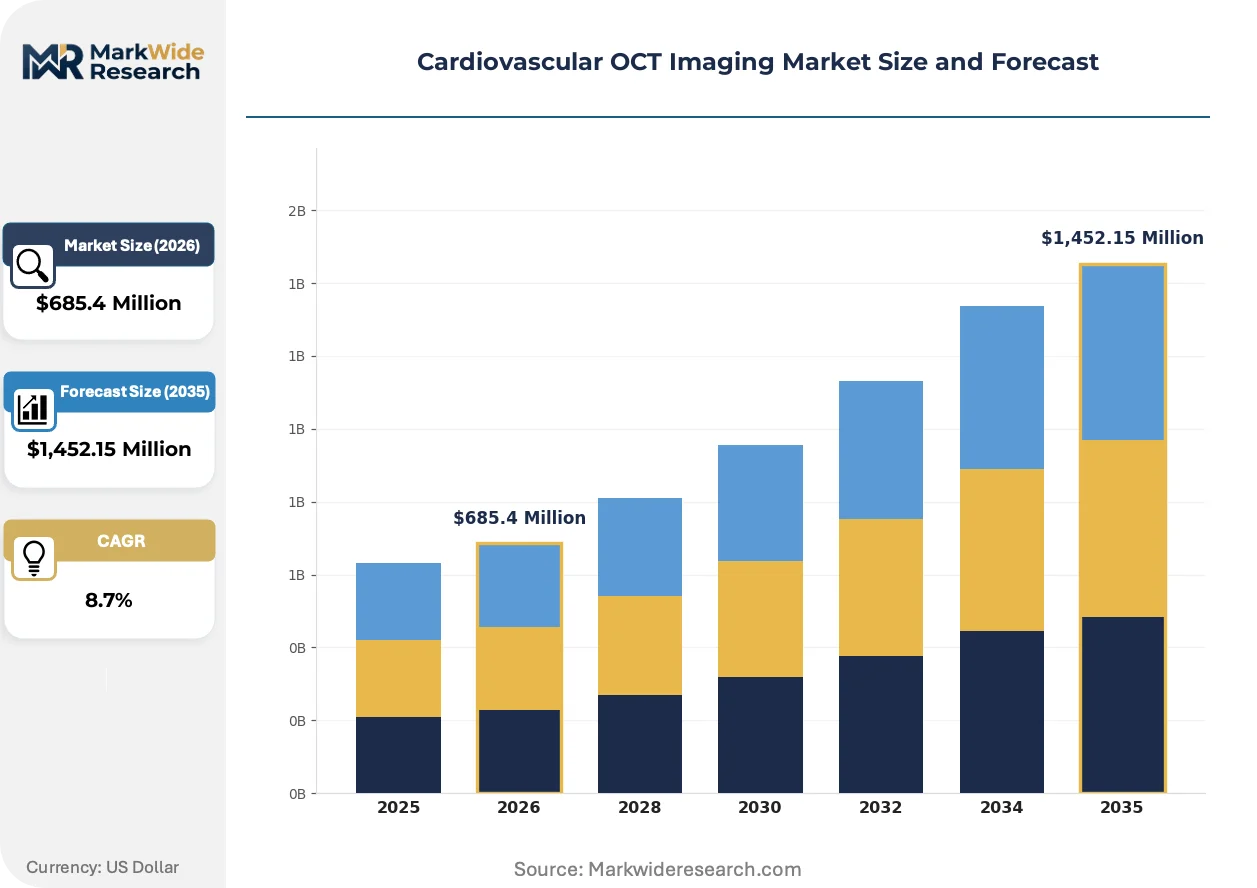
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtosecond Lasers, Optical Coherence Tomography Systems, Imaging Catheters, Contrast Agents Technology: Time-Domain OCT, Frequency-Domain OCT, Swept-Source OCT, Polarization-Sensitive OCT End User: Hospitals, Cardiology Clinics, Research Institutions, Outpatient Surgical Centers Application: Coronary Artery Disease, Plaque Characterization, Intravascular Imaging, Surgical Guidance |
| Companies Covered | Topcon Corporation, Terumo Corporation, Abbott, Medtronic, Canon Inc., Boston Scientific Corporation, Philips Healthcare, Optovue Inc., Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular OCT Imaging Market Strategic Shifts
Near-infrared interferometry is advancing through three parallel vectors: light source engineering that compresses acquisition time, regulatory frameworks that restructure clinical evidence requirements, and procurement models that unbundle capital from consumable commitments.
Swept-source OCT is collapsing the tradeoff between imaging depth and resolution through tunable laser architectures operating at 150 kHz A-line rates. Academic medical centers in Boston and Rotterdam adopt these systems for complex chronic total occlusion cases where vessel tortuosity exceeds conventional frequency-domain range. The technology is collapsing procedural ischemia time from occlusion balloon inflation, enabling complete lesion assessment without hemodynamic compromise.
Japan's PMDA structured consultation pathway now mandates adaptive trial designs for breakthrough device designations, compressing premarket review phases for novel intravascular imaging indications. This regulatory architecture accelerates first-in-human studies at Tokyo's National Cerebral and Cardiovascular Center. European manufacturers respond by front-loading Japanese clinical sites within global pivotal trials, anticipating PMDA approval as gateway to Asia-Pacific commercialization.
Hospital value analysis committees now unbundle imaging system acquisition from multi-year catheter supply agreements, reversing prior vendor lock-in structures. This purchasing evolution fragments installed base loyalty and opens competitive displacement at contract renewal points. The shift is most pronounced in integrated delivery networks across Pennsylvania and Ohio, where centralized procurement functions negotiate platform-agnostic catheter sourcing.
Cardiovascular OCT Imaging Market Segmentation
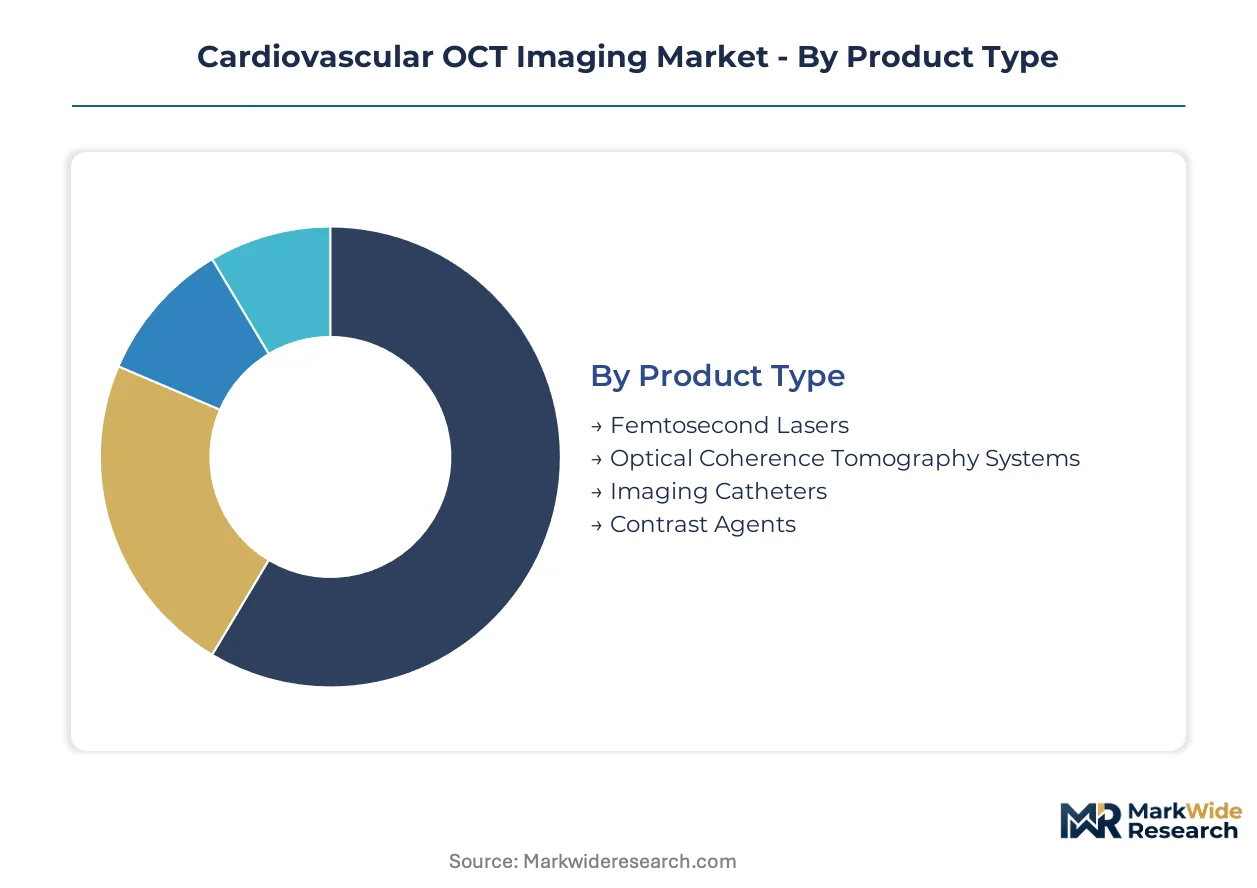
Cardiovascular OCT imaging segments reveal divergent margin profiles and replacement cycles. Product type determines capital intensity versus consumable recurrence, while technology choice shapes procedural workflow and imaging depth tradeoffs.
Product Type:
After-sales service intensity varies sharply across this category, with capital equipment demanding field engineering support and disposables requiring just-in-time supply chain responsiveness.
- Femtosecond Lasers:These ultrafast pulse sources generate near-infrared light at 1300 nm wavelength with sub-picosecond pulse duration, forming the interferometric core of swept-source OCT engines. Japanese precision optics clusters in Yamanashi and Shizuoka prefectures concentrate manufacturing capacity, with component lead times extending during periods of foundry allocation stress.
- Optical Coherence Tomography Systems:Console platforms integrate light sources, interferometers, and signal processing hardware for real-time image reconstruction. Hospital procurement committees in Germany evaluate total cost of ownership across seven-to-ten-year depreciation horizons, compressing vendor margins on replacement sales.
- Imaging Catheters:Single-use fiber-optic devices deliver rotational scanning within coronary lumens. Abbott and Terumo dominate catheter supply agreements through integrated platform ecosystems.
- Contrast Agents:Iodinated or gadolinium-based media enhance co-registration with angiographic imaging. Regulatory scrutiny from FDA and EMA constrains formulation innovation cycles.
By volume, Imaging Catheters lead. By growth pace, Femtosecond Lasers are expanding most quickly.
Technology:
Technology selection in this category stratifies by procedural throughput requirements and anatomical complexity, with acquisition speed and imaging range serving as primary differentiation vectors.
- Time-Domain OCT:Early-generation interferometric systems using mechanical reference arm scanning. Legacy installed bases in Italian public hospitals resist capital replacement due to budget freezes.
- Frequency-Domain OCT:Spectrometer-based detection enables 100 kHz A-line rates for rapid pullback imaging during balloon occlusion. Cleveland Clinic and Heidelberg University Hospital standardized training protocols around this modality, entrenching operator familiarity.
- Swept-Source OCT:Tunable laser architectures extend imaging depth beyond 10 mm for tortuous chronic total occlusion cases. Rotterdam's Erasmus MC adopted these systems for complex PCI workflows.
- Polarization-Sensitive OCT:Birefringence mapping distinguishes fibrous from lipid-rich plaque components. Research institutions in Boston and Tokyo pursue clinical validation for vulnerable plaque detection.
Frequency-Domain OCT commands the largest installed base. Swept-Source OCT shows the steepest expansion trajectory.
End User:
End user type determines purchasing authority structure and reimbursement pathway complexity, with hospital networks leveraging scale against ambulatory centers prioritizing capital efficiency.
- Hospitals:Academic medical centers and community hospital systems with interventional cardiology programs. Integrated delivery networks across Pennsylvania and Ohio centralize procurement functions for OCT system acquisition.
- Cardiology Clinics:Specialized outpatient facilities performing diagnostic angiography. Texas and Florida regulatory environments permit same-day discharge protocols that support compact system deployment.
- Research Institutions:Universities and government laboratories advancing imaging algorithm development. NIH funding cycles influence capital equipment grant timelines.
- Outpatient Surgical Centers:Ambulatory facilities bypassing hospital capital approval processes. Medicare site-of-service differentials shape equipment leasing versus purchase decisions.
Hospitals account for the majority of system placements. Outpatient Surgical Centers are gaining share fastest.
Application:
Application focus determines regulatory evidence requirements and reimbursement coding specificity, with coronary indications holding established coverage against emerging peripheral vascular extensions.
- Coronary Artery Disease:Stent placement guidance and post-procedural optimization in left anterior descending and right coronary arteries. CMS coverage determinations for image-guided PCI anchor demand in United States hospital networks.
- Plaque Characterization:Morphological assessment of fibrous cap thickness and lipid core volume. Artificial intelligence integration at Boston Scientific and Canon Medical reduces operator interpretation burden.
- Intravascular Imaging:Diagnostic pullback for lesion assessment prior to intervention. IVUS maintains reimbursement parity, constraining OCT penetration in cost-sensitive Italian and Spanish catheterization laboratories.
- Surgical Guidance:Real-time visualization during chronic total occlusion recanalization. Munich's German Heart Center validates peripheral vascular extensions beyond coronary anatomy.
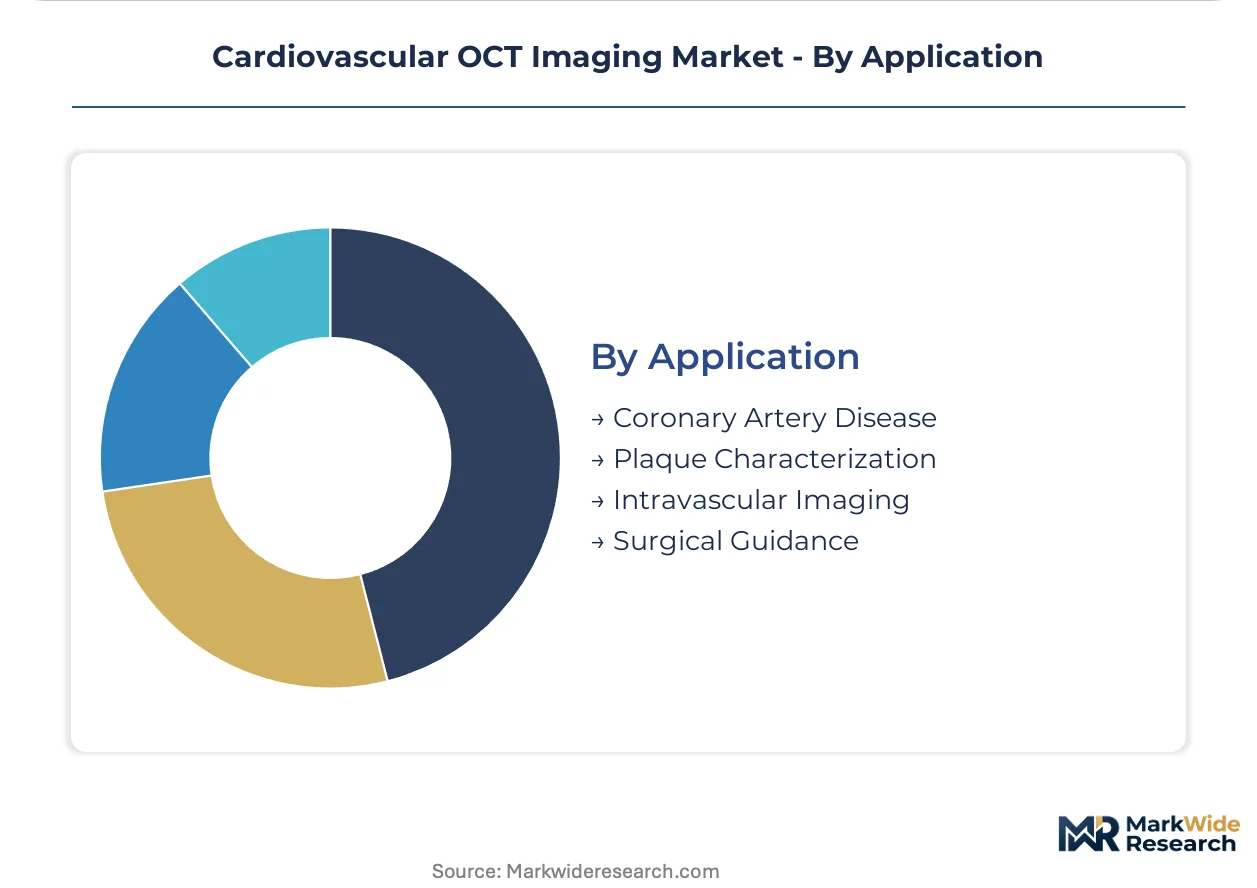
Coronary Artery Disease dominates procedure volume. Plaque Characterization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA coverage determinations for image-guided PCI procedures anchor United States demand. Hospital cath lab expansion concentrates in states with favorable Medicare reimbursement differentials.
United States
Cleveland Clinic and Mayo Clinic networks standardize OCT training protocols for interventional cardiology fellows. CMS site-of-service payment differentials favor hospital-based procedures over ambulatory settings. Texas and Florida outpatient surgical centers deploy compact systems for same-day diagnostic angiography.
Germany
Heidelberg University Hospital anchors European operator training infrastructure for frequency-domain OCT systems. EU MDR clinical evidence requirements extend CE marking timelines for intravascular imaging indications. Baden-Württemberg precision optics clusters supply interferometric components to system manufacturers.
Japan
Tokyo's National Cerebral and Cardiovascular Center validates breakthrough device designations through PMDA structured consultation pathways. METI funding supports femtosecond laser manufacturing scale-up in Yamanashi and Shizuoka prefectures. Japanese cardiac centers maintain deep procurement ties to domestic catheter suppliers.
United Kingdom
NHS England specialized commissioning frameworks allocate capital budgets for intravascular imaging in tertiary cardiac centers. MHRA post-Brexit regulatory autonomy streamlines approval pathways for CE-marked devices. London teaching hospitals integrate OCT into complex PCI referral networks.
Netherlands
Rotterdam's Erasmus MC adopts swept-source OCT systems for chronic total occlusion recanalization workflows. Dutch health technology assessment bodies evaluate cost-effectiveness against intravascular ultrasound alternatives. Eindhoven photonics clusters advance tunable laser architectures for next-generation imaging engines.
Cardiovascular OCT Imaging Market Competitive Environment
Integrated platform vendors and specialized component suppliers split the market into distinct competitive spheres. Hospital procurement committees favor vendors with catheter-system ecosystem integration. Three archetypes dominate: diversified medical technology conglomerates with interventional cardiology portfolios, precision optics specialists leveraging wavefront engineering capabilities, and catheter-focused manufacturers with deep ties to cardiac center networks. Competitive moves concentrate on unbundling capital equipment from consumable supply agreements and expanding peripheral vascular application validation.
Among diversified medical technology conglomerates, Abbott and Medtronic occupy positions spanning imaging consoles through disposable catheters. Terumo Corporation anchors the specialized catheter manufacturing tier with concentrated presence in Japanese cardiac networks. Boston Scientific Corporation exemplifies the interventional cardiology workflow integration archetype, competing through operator training infrastructure and clinical evidence generation.
| Leading Market Players |
|---|
| Topcon Corporation |
| Terumo Corporation |
| Abbott |
| Medtronic |
| Canon Inc. |
| Boston Scientific Corporation |
| Philips Healthcare |
| Optovue Inc. |
| Carl Zeiss Meditec AG |
| Others |
Value Chain & Pricing Dynamics
Yokohama-to-Long Beach container rates compress margins for Japanese femtosecond laser exports while amplifying price spreads between integrated platform vendors and standalone catheter suppliers. Cath lab procurement committees exploit this freight volatility to unbundle capital equipment from consumable commitments, forcing tiered pricing concessions across frequency-domain and swept-source OCT consoles.
Pricing Analysis
Price spreads between German-engineered consoles and Asian-assembled alternatives now exceed thirty percent at equivalent imaging specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA breakthrough device designations commanding substantial premia over CE-marked equivalents. Pricing pressure stems from IVUS reimbursement parity constraining cath lab budget elasticity. Public hospital systems in Italy and Spain exhibit highest price sensitivity due to annual device budget caps, while integrated delivery networks in Pennsylvania negotiate least aggressively when bundled training protocols are attached.
Supply Chain Analysis
Extended payment terms from German and Japanese optical component suppliers now stretch to one hundred twenty days, straining working capital for console assemblers lacking supply-chain finance facilities. Manufacturing concentrates in Japan's Yamanashi and Shizuoka prefectures for tunable laser architectures, Germany's Baden-Württemberg corridor for interferometric components, and Rochester, New York for fiber-optic catheter fabrication. Component sourcing draws from precision optics substrates, rare-earth doped fibers, and polarization-maintaining couplers. Single-source vulnerability concentrates in femtosecond laser foundry allocation. Distribution runs through hospital GPO contracts and direct cath lab agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in interferometric system design and rotational catheter mechanics now concentrates among aging workforces in Rochester and Jena, creating a structural bottleneck that favors incumbents with captive training pipelines and disadvantages entrants lacking apprenticeship depth.
For Market Incumbents: Build regulatory data moats through expanded prospective trials for MDR intravascular imaging indications, extending CE marking timelines as a competitive barrier against undercapitalized rivals. Deepen backward integration into femtosecond laser manufacturing to secure component allocation during foundry stress periods. IVUS substitution threat intensifies in Italian and Spanish publicly funded systems. For New Entrants and Emerging Players: Pursue peripheral vascular OCT validation at Munich's German Heart Center and Erasmus MC Rotterdam, where complex chronic total occlusion workflows lack established imaging modalities. Ambulatory surgical centers in Texas and Florida represent the most penetrable end-user segment, bypassing hospital capital approval processes through compact system leasing models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision optics specialists with wavefront engineering capabilities over diversified medical technology conglomerates facing portfolio rationalization pressure. Swept-source OCT platform viability extends across the five-to-ten year horizon as imaging depth requirements intensify for tortuous anatomy. Target acquisition archetype: catheter-focused manufacturers with deep ties to Japanese cardiac center networks. Monitor PMDA breakthrough device designation velocity as inflection signal for Asia-Pacific commercialization timing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Expansion | Extended CE marking timelines entrench incumbents with trial infrastructure at Heidelberg University Hospital. |
| Femtosecond Laser Manufacturing Scale-Up | METI-funded capacity in Yamanashi reduces component lead time vulnerability for swept-source engines. |
| AI Plaque Characterization Integration | Real-time algorithms at Boston Scientific and Canon Medical standardize lesion assessment across operator experience levels. |
| Outpatient Cath Lab Partnership | Texas and Florida ambulatory centers bypass hospital procurement committees through direct compact system deployment. |
| Peripheral Vascular Application Validation | Munich's German Heart Center clinical evidence opens procedural volume beyond coronary anatomy constraints. |
Study Parameters
A standing panel of interventional cardiologists, cath lab purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview waves. Secondary validation drew from FDA premarket notification filings, PMDA structured consultation pathway records, CMS coverage determination documents, and EU MDR technical documentation. Bottom-up procedure volume estimates triangulated against top-down imaging system installed base calculations.
Scenario-bracketing around reimbursement parity evolution, supply chain disruption probability, and technology substitution timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, technology generation, end-user purchasing authority structure, and application-specific regulatory evidence requirements. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with femtosecond laser manufacturing capacity and operator training program expansion serving as key forecast inputs.
Sensitivities concentrate around CMS coverage determination revisions for image-guided PCI, PMDA breakthrough device designation velocity, and EU MDR clinical evidence requirement enforcement intensity. Forecasts reflect assumptions regarding reimbursement pathway stability and cath lab capital budget allocation priorities. Macroeconomic contraction affecting hospital capital expenditure, regulatory deviation expanding IVUS reimbursement advantage, or technological leapfrog by alternative intravascular imaging modalities would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market