
 North America Interventional Cardiology and Peripheral Vascular Devices Market | 2026-2036
North America Interventional Cardiology and Peripheral Vascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Interventional Cardiology and Peripheral Vascular Devices Market Analytics
The capability gap between capital-heavy integrated manufacturers and asset-light distributors is collapsing as hospital procurement consolidates around single-source contracts. Boston Scientific Corporation leverages captive manufacturing of drug-eluting stents to sustain margin pools in coronary interventions. Abbott Laboratories anchors its position through vertical control over guidewire metallurgy and coating technologies. Medtronic dominates structural heart portfolios while competing aggressively on mechanical thrombectomy system placements across integrated delivery networks.
Interventional cardiology and peripheral vascular devices encompass minimally invasive instruments designed to restore luminal patency in occluded or stenosed vessels, typically fabricated from nitinol, cobalt-chromium alloys, or bioabsorbable polymers and deployed via femoral or radial access under fluoroscopic guidance. Their primary purpose is to obviate open surgical revascularization while reducing perioperative morbidity and accelerating recovery timelines. Stent systems command the largest revenue share among product types due to recurring restenosis-driven replacement cycles, while drug-eluting devices within the technology dimension capture premium pricing through paclitaxel and sirolimus analog formulations that suppress neointimal hyperplasia. Balloon catheters represent the most mature segment, with margin compression offset by high-volume coronary artery disease application throughput in hospital settings.
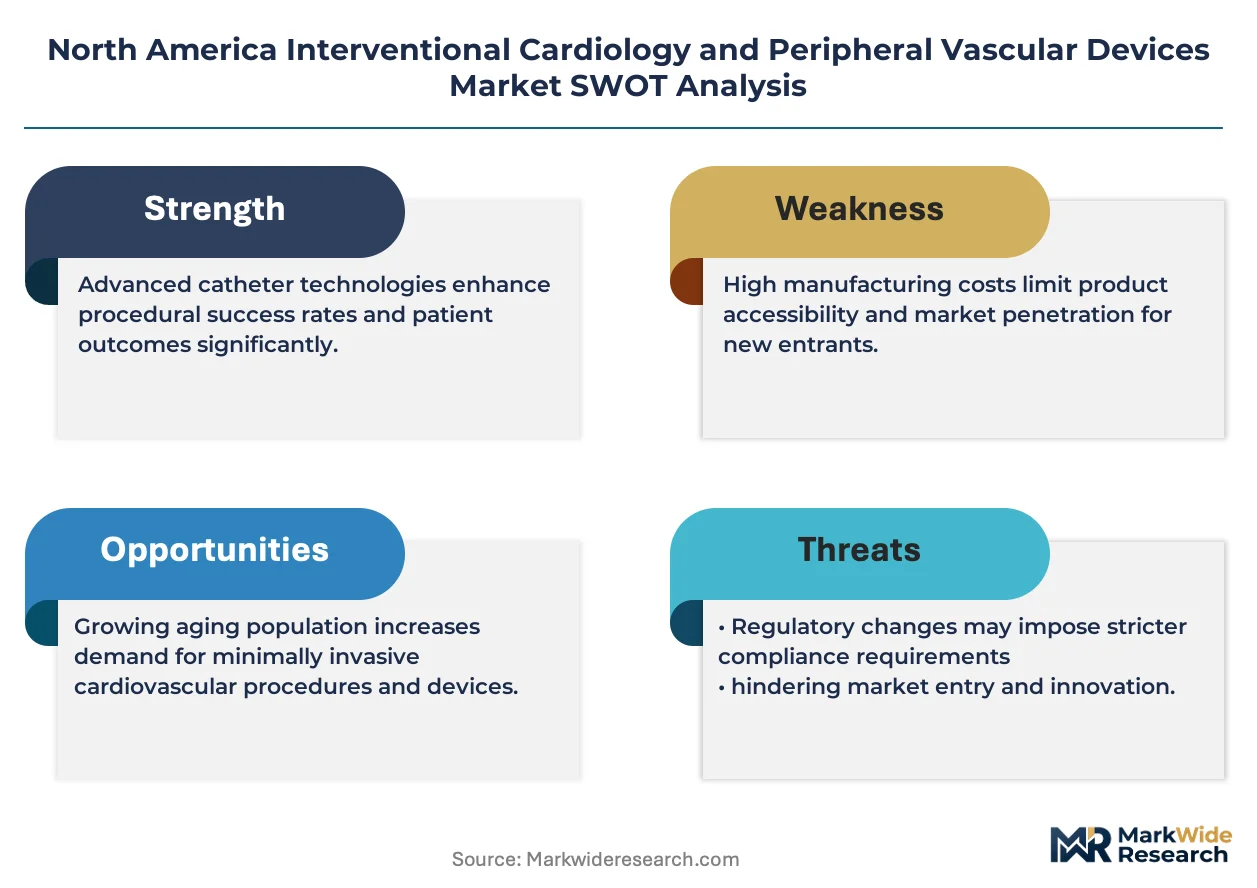
FDA premarket notification and premarket approval pathways govern device commercialization in the United States, while Health Canada and COFEPRIS establish parallel but divergent evidence standards that shape cross-border product launch sequencing. ISO 13485 quality management certification operates as a baseline threshold for supplier qualification across North American health system procurement boards. Stakeholders must monitor evolving CMS reimbursement determinations for transcatheter valve interventions and peripheral artery disease procedures, as coverage decisions will dictate capital allocation between coronary and peripheral vascular R&D portfolios.
Market Dynamics
Integrated health networks in the United States are consolidating procurement around single-source contracts for coronary stent and catheter systems, collapsing the traditional distributor-manufacturer boundary and forcing device makers to absorb inventory risk directly.
Growth Catalysts
- CMS reimbursement expansion:Coverage determinations for transcatheter valve interventions and peripheral artery disease procedures are pulling capital toward interventional portfolios. Hospital systems respond by expanding cath lab capacity.
- Drug-eluting stent technology:Paclitaxel and sirolimus analog formulations suppress neointimal hyperplasia with superior restenosis profiles. Recurring replacement cycles sustain revenue visibility for manufacturers.
- Ambulatory surgical center proliferation:Outpatient procedural volumes are rising as these facilities capture lower-acuity interventions. Device utilization expands outside traditional hospital settings.
Market Restraints
- Nitinol and cobalt-chromium alloy input costs:Price volatility in specialty metals compresses gross margins for stent and guidewire producers. Long-term supply agreements partially hedge exposure.
- FDA premarket approval pathway duration:Clinical evidence requirements for novel devices extend development timelines. Smaller entrants face capital constraints navigating PMA submissions.
- Structural heart surgical alternatives:Surgical aortic valve replacement retains preference in certain anatomical presentations. Transcatheter systems face indication boundaries.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring production reduces logistics costs for US distribution while maintaining FDA quality system compliance. Labor arbitrage supports margin recovery.
- Bioabsorbable polymer convergence:Scaffold technologies that fully resorb eliminate permanent foreign body concerns. Early clinical data supports premium positioning against metallic platforms.
- Radial access adoption:Transradial catheterization reduces bleeding complications and accelerates discharge. Training infrastructure investment unlocks procedural volume growth.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for supplier qualification create onboarding friction. Health system procurement boards enforce certification as a baseline threshold.
- Fluoroscopy-trained interventionalist scarcity:Specialized skill requirements for femoral and radial access procedures limit cath lab throughput expansion. Fellowship pipeline constraints persist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Interventional Cardiology and Peripheral Vascular Devices Market |
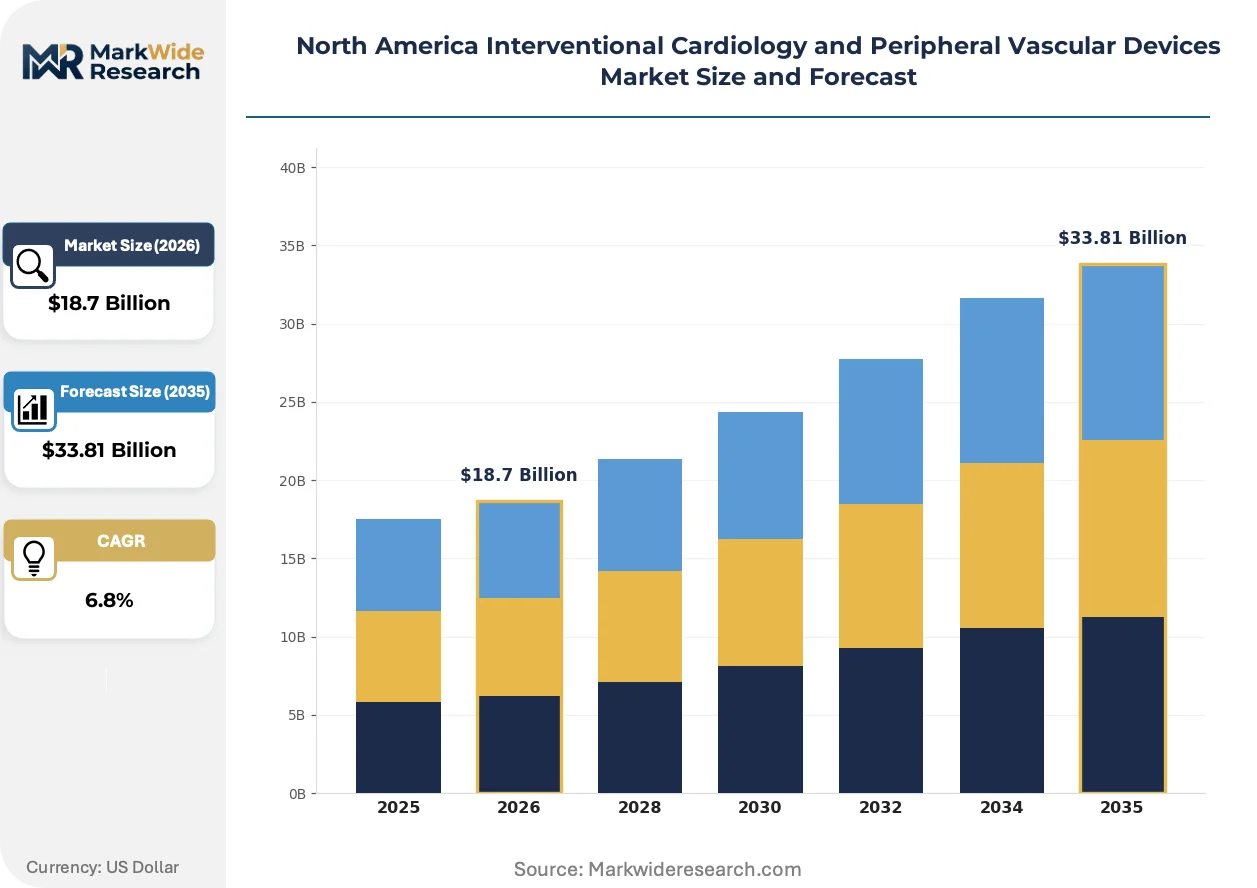
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stents, Guidewires, Catheters Application: Coronary Artery Disease, Peripheral Artery Disease, Aneurysm, Valvular Heart Disease End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Research Institutions Technology: Bioabsorbable Stents, Drug-eluting Devices, Imaging Techniques, Mechanical Thrombectomy |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Johnson & Johnson, B. Braun Melsungen AG, Terumo Corporation, BD, Cook Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Interventional Cardiology and Peripheral Vascular Devices Market Evolving Landscape
Device architectures are converging around drug-device combination platforms while regulatory evidence standards escalate and procurement centralization rewires commercial access pathways.
Mechanical thrombectomy aspiration systems are fragmenting the acute stroke intervention landscape. Neurovascular centers in integrated delivery networks are adopting these platforms for large vessel occlusion management. The technology is fragmenting historical stent retriever market segmentation and forcing portfolio diversification among interventional suppliers.
FDA's alignment with MDR quality benchmarks is elevating post-market surveillance obligations for coronary and peripheral devices. Manufacturers must maintain rigorous clinical follow-up registries to support continued marketing authorization. Drug-eluting stent portfolios face heightened scrutiny as FDA evaluates real-world performance data.
Health system procurement boards are unbundling after-sales service from device pricing. Capital equipment and disposable contracts now separate technical support, training, and inventory management. This pattern concentrates in the United States where IDN purchasing power has reached sufficient scale to dictate commercial terms.
North America Interventional Cardiology and Peripheral Vascular Devices Market Segmentation
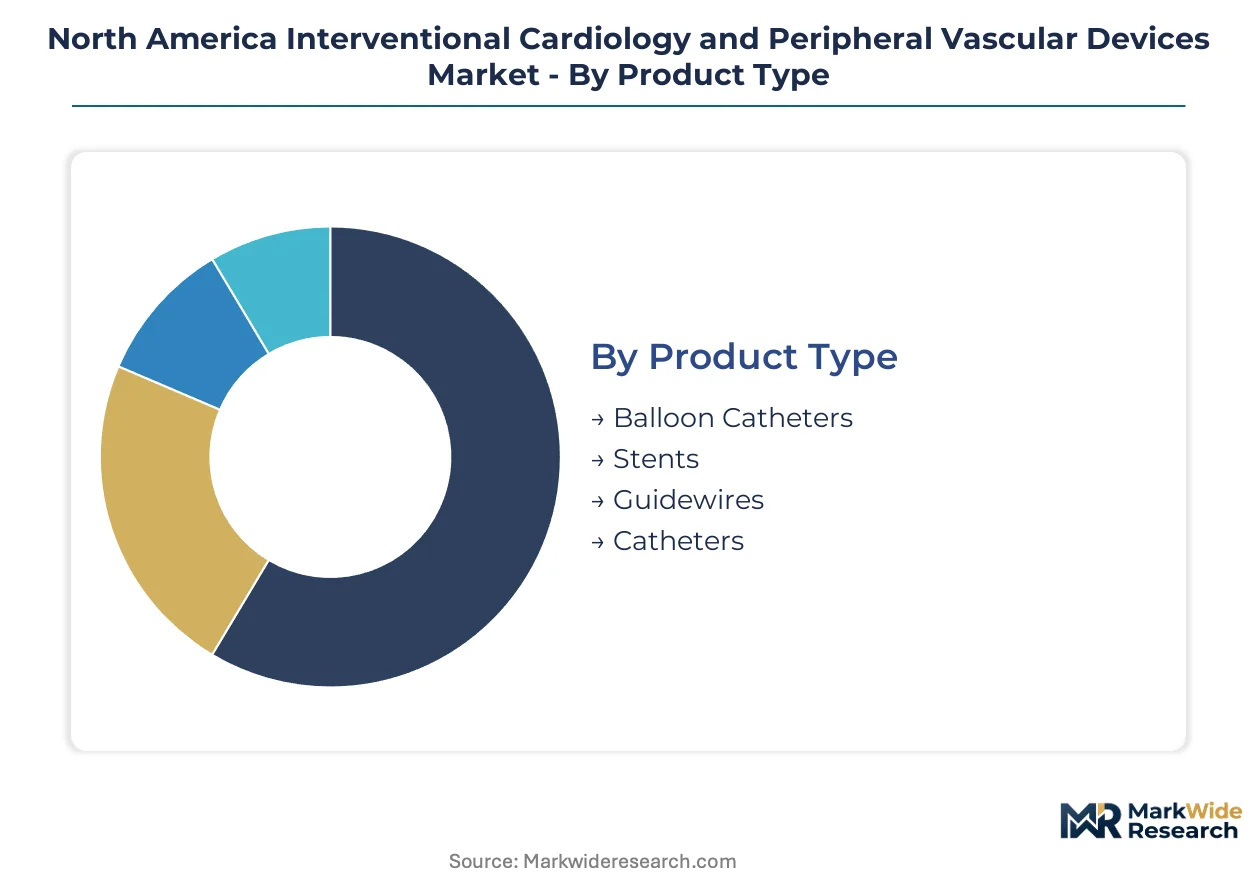
Segmentation in this market reveals how procurement centralization and site-of-care migration are redrawing competitive boundaries. Understanding these divisions exposes where pricing power concentrates and which technology platforms warrant R&D prioritization.
Product Type:
Domestic production dominates stent and balloon catheter supply chains, while guidewire manufacturing retains significant import dependency from European and Asian precision metallurgy suppliers.
- Balloon Catheters:Fabricated from polyethylene terephthalate or nylon with rated burst pressures calibrated for coronary and peripheral dilatation. United States hospital cath labs absorb the majority of volume, though margin compression from commoditization forces manufacturers toward proprietary scoring balloon designs.
- Stents:Cobalt-chromium and platinum-chromium alloy platforms with strut thicknesses below 80 micrometers dominate coronary applications. Integrated delivery networks in the United States negotiate single-source contracts that collapse distributor intermediaries and shift inventory risk to manufacturers.
- Guidewires:Nitinol core wires with hydrophilic polymer coatings enable lesion crossing in tortuous anatomy.
- Catheters:Diagnostic and guiding catheters in French sizes from 4F to 8F support femoral and radial access approaches.
Stents command the established base. The steepest expansion runs through drug-coated balloon variants within the balloon catheter category.
Application:
Cost tier stratification separates emergency coronary interventions from elective peripheral procedures, with the former commanding premium device pricing and the latter facing utilization management scrutiny.
- Coronary Artery Disease:Percutaneous coronary intervention with stent deployment addresses acute myocardial infarction and stable angina. United States integrated health networks drive centralized procurement of drug-eluting stent systems, with CMS reimbursement rates determining cath lab capital allocation.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal interventions address claudication and critical limb ischemia. Ambulatory surgical centers in the United States are capturing lower-acuity endovascular cases, expanding device utilization outside hospital settings.
- Aneurysm:Endovascular aneurysm repair with stent graft deployment treats abdominal and thoracic aortic pathology.
- Valvular Heart Disease:Transcatheter aortic and mitral valve interventions serve inoperable surgical candidates.
Coronary artery disease anchors revenue stability. Peripheral artery disease applications are climbing the fastest as outpatient migration accelerates.
End User:
Customer type determines service bundling requirements, with hospitals demanding comprehensive training and inventory management while ambulatory sites prioritize disposable cost minimization.
- Hospitals:Academic medical centers and community hospitals maintain cath lab infrastructure for high-acuity interventions. United States integrated delivery networks consolidate purchasing across multiple facilities, extracting volume discounts on stent and catheter contracts.
- Ambulatory Surgical Centers:Freestanding endovascular suites perform diagnostic angiography and lower-complexity interventions. These facilities in the United States are expanding procedural volumes as payers steer patients away from hospital-based care.
- Cardiology Clinics:Office-based labs handle diagnostic catheterization and selective interventions.
- Research Institutions:Academic centers conduct clinical trials for novel device platforms.
Hospitals retain the volume base. Ambulatory surgical centers post the steepest utilization trajectory.
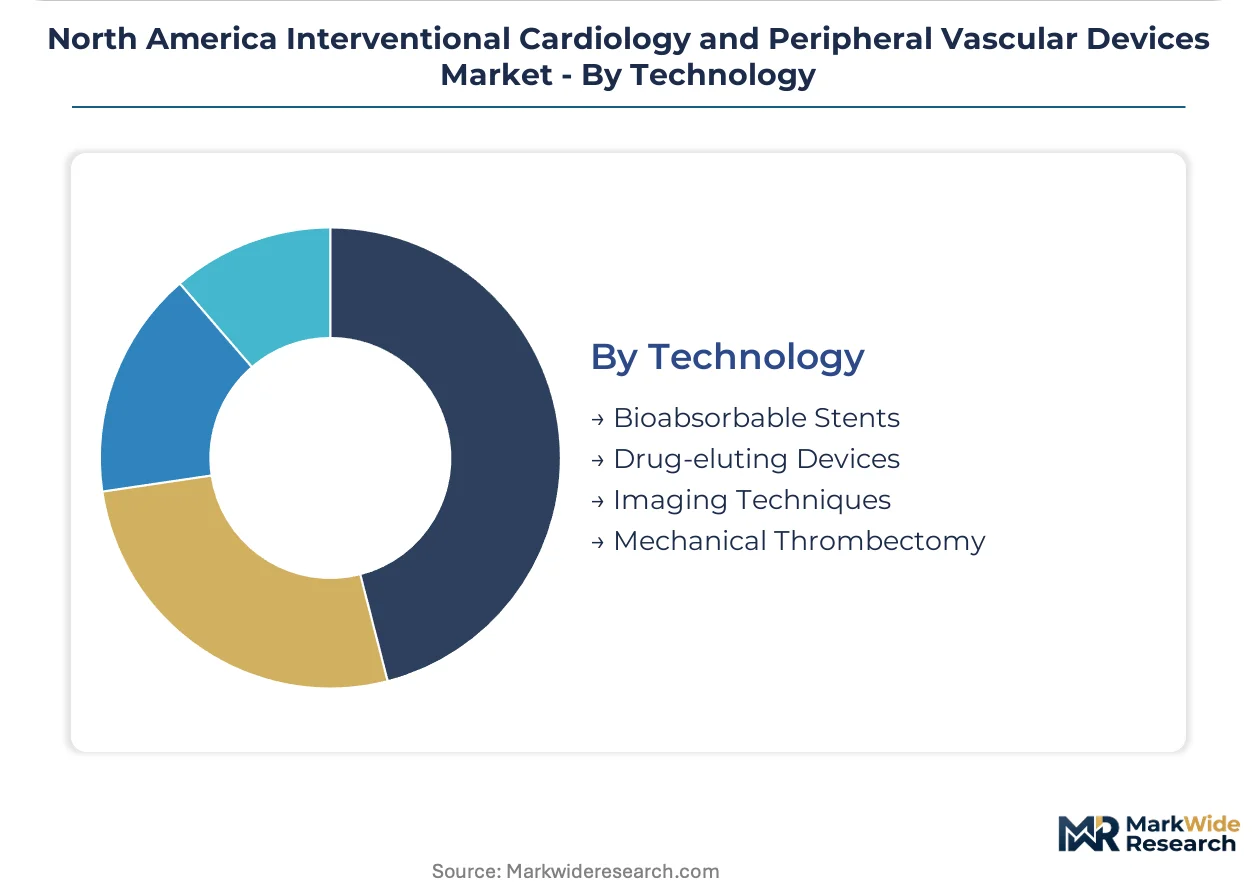
Technology:
Supply concentration in polymer chemistry and pharmaceutical coating expertise shapes competitive access to next-generation platforms.
- Drug-eluting Devices:Paclitaxel and sirolimus analog formulations suppress neointimal hyperplasia in coronary and peripheral applications. FDA post-market surveillance requirements for these combination products elevate clinical evidence burdens beyond bare-metal alternatives.
- Mechanical Thrombectomy:Aspiration catheters and stent retrievers address large vessel occlusion in acute ischemic stroke. United States neurovascular centers are adopting these platforms, fragmenting historical market segmentation.
- Bioabsorbable Stents:Poly-L-lactic acid scaffolds resorb over 24-36 months, eliminating permanent foreign body concerns.
- Imaging Techniques:Intravascular ultrasound and optical coherence tomography guide lesion assessment and stent optimization.
Drug-eluting devices command the installed revenue base. Mechanical thrombectomy is gaining share fastest as stroke networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across the North American landscape. United States integrated delivery networks extract maximum volume leverage on stent contracts, while Mexican facilities remain price-takers dependent on import channels. Canadian buyers occupy a middle tier, balancing cost containment against Health Canada compliance premiums.
United States
Integrated health networks in Texas and the Northeast Corridor consolidate cath lab purchasing across dozens of facilities. FDA PMA pathways govern drug-eluting stent commercialization, extending development timelines for novel platforms. Minneapolis and Boston anchor rival device engineering clusters, each feeding specialized talent into structural heart and coronary portfolios.
Canada
Provincial health authorities in Ontario and Quebec negotiate centralized device contracts with limited manufacturer switching. Health Canada aligns with FDA evidence standards but maintains independent review timelines for combination products. Toronto's university hospitals conduct pivotal trials that accelerate subsequent US regulatory submissions.
Mexico
Private hospital chains in Mexico City and Monterrey absorb premium-priced coronary devices for insured patient segments. COFEPRIS regulatory convergence with FDA benchmarks enables faster approval of US-validated platforms. The Bajío Region attracts manufacturing investment from US firms seeking nearshore production with maintained quality system compliance.
North America Interventional Cardiology and Peripheral Vascular Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American interventional device space. The market structure consolidates around three integrated manufacturers with captive stent and catheter production, while mid-scale specialists compete on guidewire metallurgy and niche access technologies. Strategic archetypes separate into vertical integrators with foundry control, coating technology specialists, and distribution-heavy regional suppliers. Competitive moves concentrate on single-source contract capture at integrated delivery networks and Mexico manufacturing expansion to recover margin pressure.
Among the integrated tier, Boston Scientific Corporation, Medtronic, and Abbott Laboratories exemplify divergent strategic positioning. Boston Scientific anchors coronary intervention portfolios through Massachusetts-based engineering density. Medtronic occupies the structural heart and mechanical thrombectomy vectors with Minnesota-rooted manufacturing scale. Abbott Laboratories represents vertical control over upstream metallurgy and pharmaceutical coating supply chains. Each firm navigates procurement centralization by absorbing inventory risk directly rather than ceding margin to distributor intermediaries.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Terumo Corporation |
| BD |
| Cook Medical |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Take-or-pay contracts with nitinol and cobalt-chromium alloy suppliers lock in multi-year price visibility for stent manufacturers while buffering against spot-market volatility in specialty metals. These arrangements bind integrated health networks to minimum volume commitments that sustain manufacturer margins even as ambulatory surgical centers negotiate leaner disposable pricing.
Pricing Analysis
After-sales service revenue—training, technical support, inventory management—drives lifetime value as health systems unbundle these elements from device pricing. Pricing stratifies across premium drug-eluting platforms, standard bare-metal stents, and economy balloon catheter tiers, with FDA PMA certification and ISO 13485 compliance acting as primary price differentiation drivers. Cost compression in the balloon catheter segment intensifies as commoditization erodes proprietary scoring designs. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Port congestion on transpacific lanes and container availability fluctuations elevate inbound logistics costs for nitinol wire shipments originating from European and Asian precision metallurgy centers. Supply concentrates in Germany, Japan, and the United States for cobalt-chromium alloy feedstock, while polymer coating chemistry draws from Switzerland and the Netherlands. Single-source vulnerability in guidewire hydrophilic coating technology creates concentration risk. Distribution runs through manufacturer-direct channels to integrated delivery networks, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as cath lab capacity expansion follows CMS reimbursement expansion for transcatheter interventions. Hospital capital allocation cycles drive the recovery trajectory.
For Market Incumbents: Consolidate single-source contract capture at expanding integrated delivery networks before ambulatory surgical center procurement fragments purchasing power. Absorb inventory risk directly through consignment models that lock out distributor intermediaries. Invest backward integration into Mexico manufacturing to recover margin pressure from nitinol alloy cost volatility. Prioritize ISO 13485 certification maintenance as procurement boards enforce quality system thresholds.
For New Entrants and Emerging Players: Differentiate on bioabsorbable scaffold platforms where clinical data gaps create white-space opportunity against entrenched metallic stent incumbents. Target mechanical thrombectomy aspiration systems for acute stroke intervention, the fastest-expanding technology segment with fragmented competitive positioning. Pursue hospital system partnership models that bundle training and technical support to overcome procurement board qualification barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward coating technology specialists with pharmaceutical formulation expertise and FDA combination product experience. Long-term viability across the projection horizon rests on clinical evidence generation capabilities and post-market surveillance infrastructure. Watch FDA real-world performance data requirements as the signal for regulatory burden escalation that favors scaled players.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Single-source contract capture at IDNs collapses distributor intermediaries and locks volume. |
| Mexico Manufacturing Expansion | Nearshoring reduces logistics costs while maintaining FDA quality system compliance. |
| Reimbursement Strategy | CMS coverage determinations for transcatheter interventions dictate cath lab capital allocation. |
| FDA Submission Pathway | PMA clinical evidence requirements extend timelines but create durable competitive moats. |
| Software Companion Development | Intravascular ultrasound and optical coherence tomography integration guides stent optimization. |
Research Methodology
Desk research of FDA PMA filings, CMS reimbursement determinations, and hospital procurement databases preceded structured interviews with cath lab directors, GPO contracts managers, biomedical engineers, and interventional cardiologists. Secondary validation drew from Health Canada device approvals, COFEPRIS regulatory convergence documentation, and integrated delivery network capital expenditure disclosures. Bottom-up stent and catheter volume estimates triangulated against top-down market sizing from health system purchasing consolidation trends.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from procedural volume trajectories, replacement cycle frequencies, and site-of-care migration patterns. Modeled inputs incorporated ambulatory surgical center penetration rates, radial access adoption curves, and drug-eluting device restenosis performance data.
Material uncertainties—FDA post-market surveillance requirement shifts, specialty metals commodity price spikes, and interventionalist fellowship pipeline constraints—sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and procurement centralization continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Cardiac Valve Market