
 Extracorporeal Membrane Oxygenation (ECMO) Market | 2026-2036
Extracorporeal Membrane Oxygenation (ECMO) Market Size, Share, and Industry Trends Forecast 2026-2036
Extracorporeal Membrane Oxygenation (ECMO) Market Analysis
The gap between premium integrated ECMO platforms and commodity perfusion components is expanding as procurement teams separate bundled system purchases from consumable replenishment cycles. Medtronic leverages its end-to-end portfolio to control hospital contracting dynamics across cannulation and oxygenator categories. Getinge AB anchors European supply through centralized manufacturing and direct service networks. LivaNova PLC differentiates via specialized cardiac surgery integration rather than broad critical care positioning.
Extracorporeal Membrane Oxygenation constitutes a temporary life-support modality that circulates blood through an external membrane oxygenator to enable gas exchange when native lung or cardiac function fails; systems integrate centrifugal pumps, heat exchangers, and polymethylpentene hollow-fiber membranes operating at blood flows of 3–7 liters per minute. Veno-Arterial ECMO dominates procedural volume due to its simultaneous cardiac and respiratory support capability in postcardiotomy shock and refractory cardiac arrest. Veno-Venous ECMO represents the fastest-growing configuration as acute respiratory distress syndrome protocols expand beyond traditional transplant centers. Mechanical Circulatory Support technology commands concentrated margin pools because pump and oxygenator replacement cycles generate recurring revenue streams.
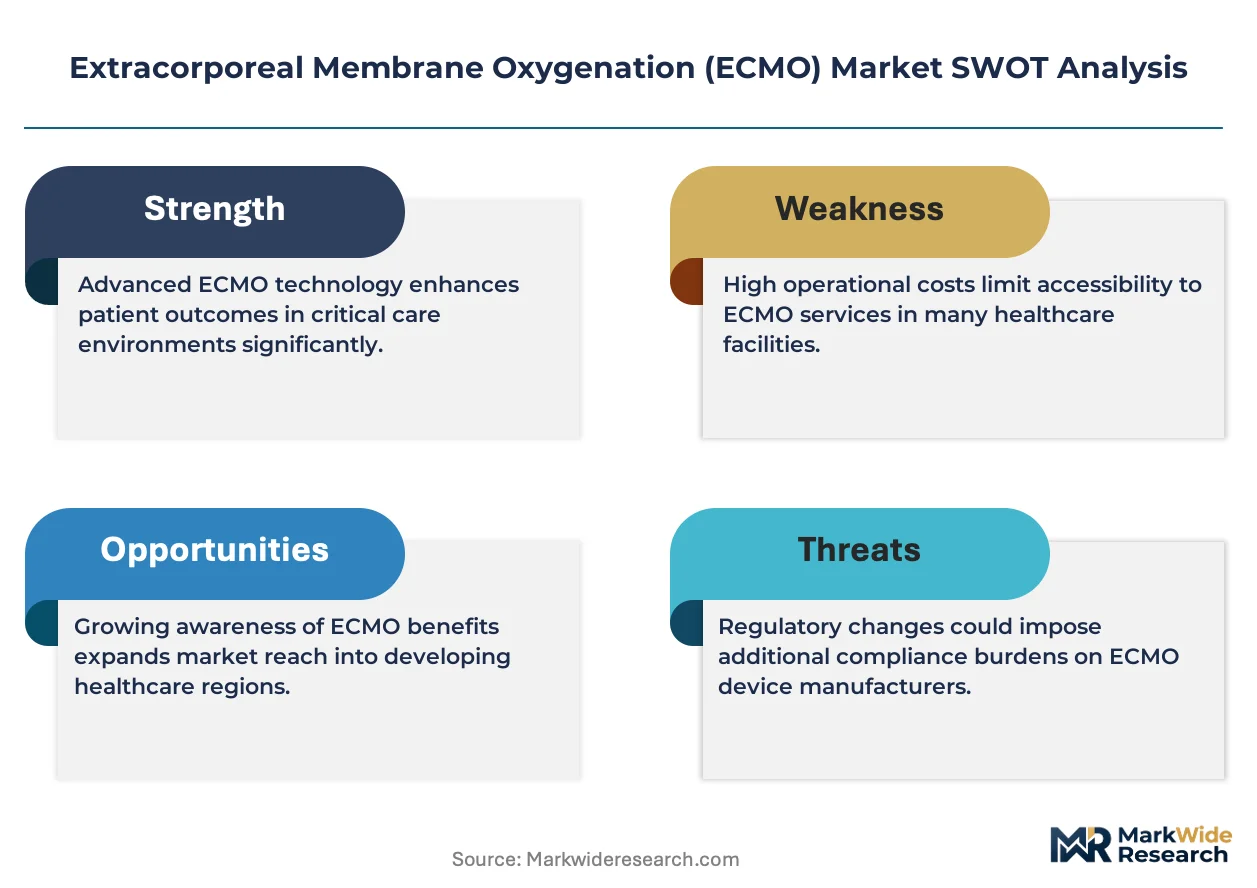
FDA Class III device designation and ISO 10993 biocompatibility standards govern premarket clinical evidence requirements for new ECMO systems in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for active implantable life-support equipment. Japan's PMDA enforces stringent post-market surveillance for extracorporeal circulation devices under the Pharmaceutical and Medical Device Act. Stakeholders must monitor evolving reimbursement pathways for prolonged ECMO runs as health technology assessment bodies recalibrate cost-effectiveness thresholds for temporary organ replacement therapies.
Market Dynamics
The ECMO market is being reshaped by the unbundling of integrated system procurement from consumable replenishment cycles, as hospital supply chains separate capital equipment decisions from ongoing oxygenator and circuit purchases.
Growth Catalysts
- Postcardiotomy shock protocols:Cardiac surgery programs in tertiary centers are standardizing veno-arterial ECMO as first-line mechanical circulatory support, expanding addressable procedure volumes beyond traditional transplant candidates.
- ISO 13485 quality mandates:Regulatory elevation of quality management requirements for Class III life-support devices is consolidating vendor pools toward certified manufacturers with established post-market surveillance infrastructure.
- Polymethylpentene membrane technology:Hollow-fiber oxygenators with enhanced biocompatibility profiles are extending permissible ECMO run durations, enabling broader application in acute respiratory distress syndrome management.
Market Restraints
- Silicone circuit component costs:Input volatility in medical-grade silicone supply chains creates margin pressure for disposable circuit manufacturers dependent on specialized extrusion processes.
- Centrifugal pump motor concentration:Precision magnetic levitation motor production concentrates among a limited supplier base in Germany and Japan, creating single-source vulnerability for pump module assembly.
- FDA premarket approval timelines:Class III device designation mandates 12-24 month clinical evidence generation periods that delay new entrant commercialization and entrench incumbent positions.
Strategic Opportunities
- India tertiary hospital expansion:Greenfield cardiac surgery center development in Delhi, Mumbai, and Chennai creates first-mover advantage for ECMO program establishment outside established transplant hubs.
- Mobile ECMO retrieval services:Pre-hospital cannulation and transport protocols are emerging as a distinct service layer, requiring portable pump-oxygenator configurations and specialized clinical teams.
- EU Medical Device Regulation transitional provisions:MDR Article 120 extensions for legacy device certifications create temporary competitive windows for manufacturers with notified body relationships to accelerate market entry.
Industry Challenges
- Perfusionist workforce scarcity:Extracorporeal life support programs require specialized clinical expertise that training pipelines have not scaled to match procedural volume expansion in high-acuity centers.
- Legacy EMR integration complexity:Pump data capture and hemodynamic monitoring interoperability with existing hospital information systems demands costly custom interface development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extracorporeal Membrane Oxygenation (ECMO) Market |
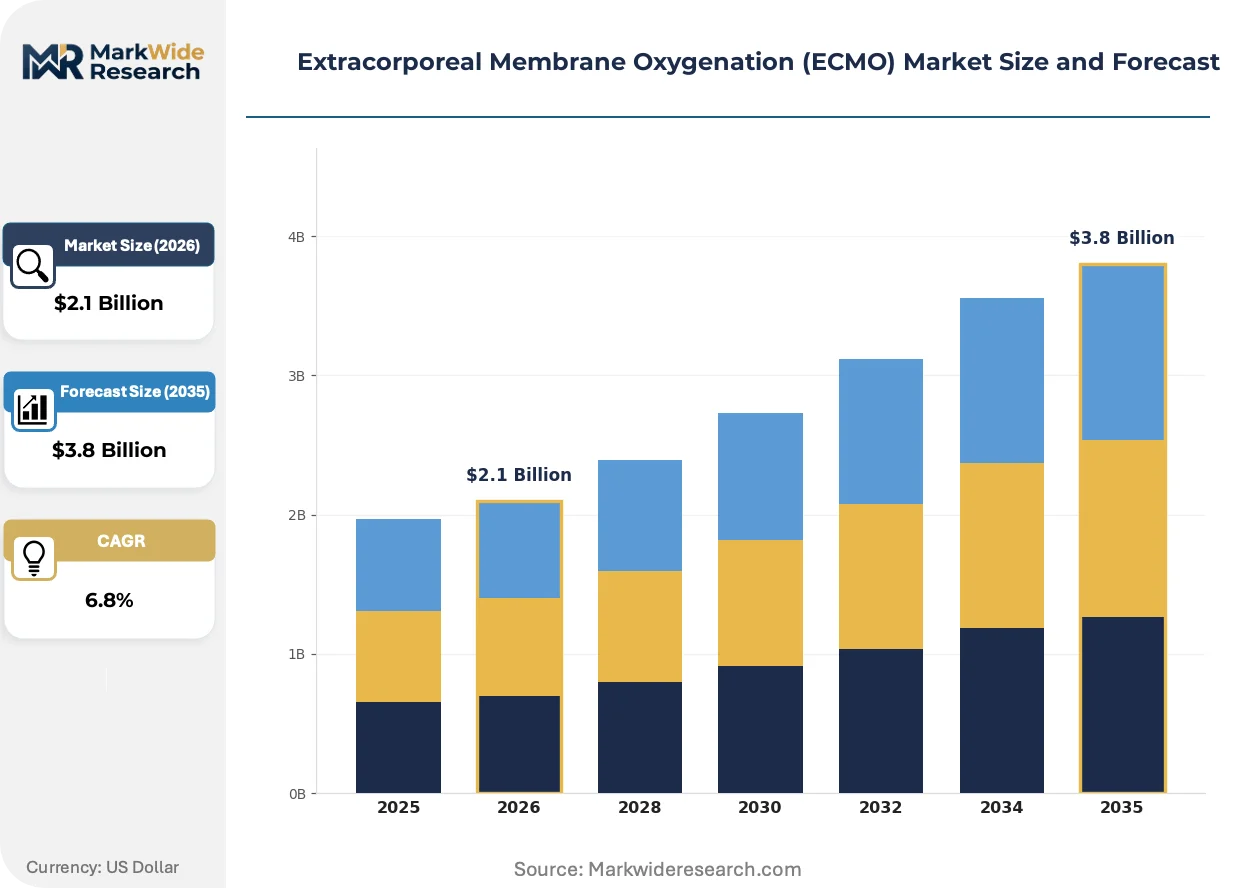
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veno-Arterial ECMO, Veno-Venous ECMO, Arterio-Venous ECMO, Dual Lumen ECMO Application: Cardiac Support, Respiratory Therapy, Sepsis Management, Congenital Heart Defects End User: Hospitals, Specialty Clinics, Nursing Facilities, Home Care Providers Technology: High-Frequency Oscillatory Ventilation, Continuous Renal Replacement Therapy, Mechanical Circulatory Support, Blood Purification |
| Companies Covered | Medtronic, Getinge AB, LivaNova PLC, Terumo Corporation, Fresenius Medical Care AG & Co. KGaA, Abbott Laboratories, Nipro Corporation, Eurosets S.r.l., MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extracorporeal Membrane Oxygenation (ECMO) Market Emerging Trajectories
ECMO technology is fragmenting into configurable subsystems that permit selective component replacement rather than complete platform overhaul, compressing hospital capital commitment cycles.
Polymethylpentene hollow-fiber membrane oxygenators with integrated heat exchangers are displacing silicone membrane alternatives in high-flow configurations. Academic medical centers in the United States and Germany are adopting these configurations for prolonged respiratory support runs exceeding fourteen days. The technology is modularizing pump-oxygenator pairings, allowing perfusion teams to mix subsystems from different manufacturers rather than accepting bundled platform constraints.
Japan's PMDA has tightened post-market surveillance requirements for extracorporeal circulation devices under amended Pharmaceutical and Medical Device Act enforcement ordinances. Manufacturers must now submit annual safety reports with device-specific adverse event stratification, elevating documentation burdens for foreign entrants. Japanese university hospitals are responding by consolidating purchasing authority through centralized procurement consortia that pre-qualify vendors based on surveillance compliance history.
Hospital supply chains are separating capital equipment acquisition from disposable replenishment through distinct contracting vehicles. Tertiary care systems in the United States are unbundling oxygenator and circuit purchases from initial platform procurement, treating consumables as category-managed spend rather than captive attachments. This shift is most pronounced in multi-hospital health systems with centralized value analysis committees that benchmark component pricing across independent service lines.
Extracorporeal Membrane Oxygenation (ECMO) Market Segmentation
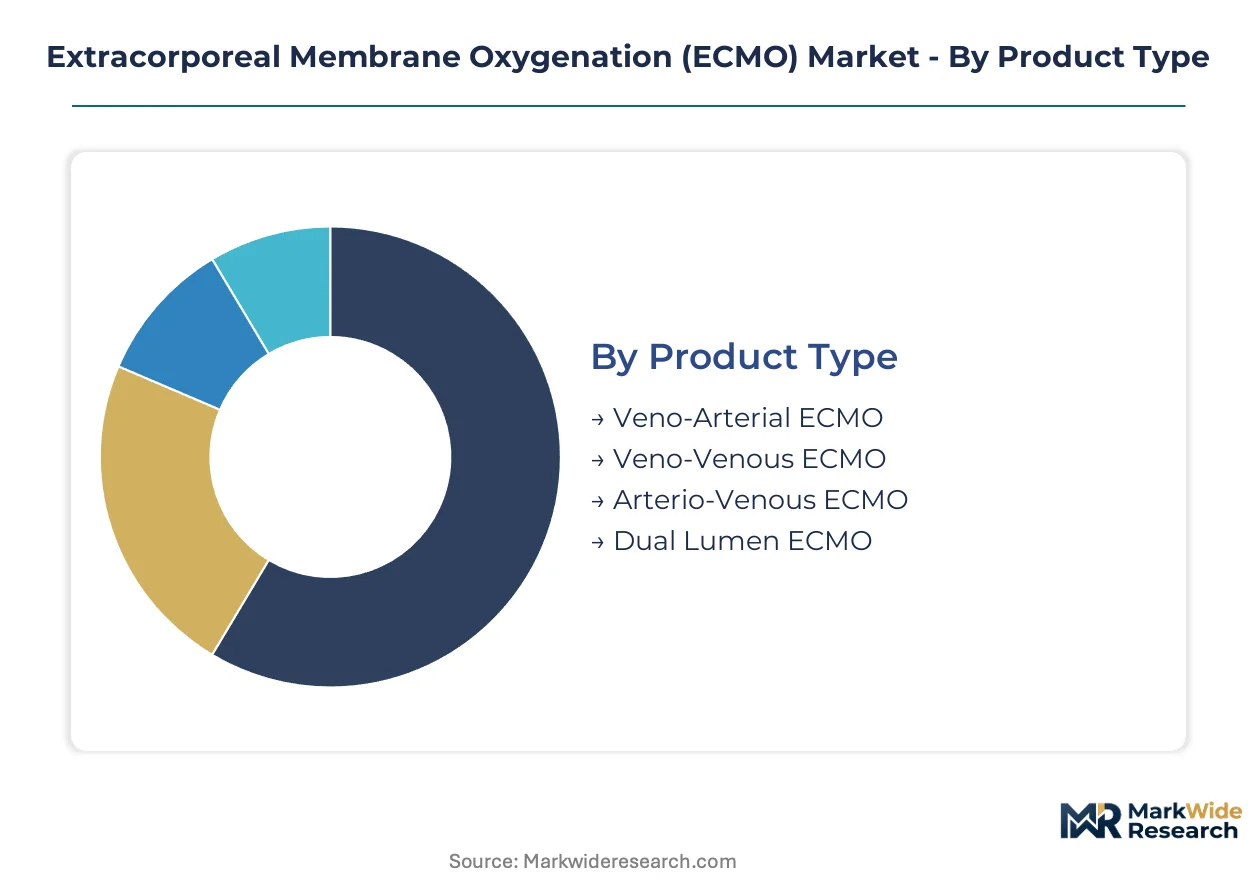
ECMO procurement patterns diverge sharply across clinical settings, with tertiary hospitals demanding integrated platforms while transport services prioritize modular portability. Understanding these segment boundaries reveals where margin pools concentrate and which configurations face commoditization pressure from unbundled consumable sourcing.
Product Type:
Supply concentration in centrifugal pump manufacturing creates asymmetric power dynamics across ECMO configurations, favoring vendors with captive magnetic levitation motor production.
- Veno-Arterial ECMO:Simultaneous cardiac and respiratory support through femoral or central cannulation routes. Postcardiotomy shock protocols in United States tertiary centers drive procedural volume concentration, though perfusionist workforce constraints limit program expansion velocity.
- Veno-Venous ECMO:Isolated respiratory support via internal jugular or femoral access with dual-site or single-site dual-lumen cannulation. Acute respiratory distress syndrome treatment protocols at German university hospitals are expanding addressable procedures beyond traditional transplant candidate pools.
- Arterio-Venous ECMO:Pumpless configurations leveraging native arterial pressure differentials for limited gas exchange support.
- Dual Lumen ECMO:Single-site cannulation systems reducing vascular access complications in prolonged respiratory support runs.
Today's leader: Veno-Arterial ECMO. Tomorrow's challenger: Veno-Venous ECMO.
Application:
Cost tier stratification separates capital-intensive cardiac surgical applications from respiratory therapy protocols with shorter equipment depreciation cycles.
- Cardiac Support:Postcardiotomy shock, bridge-to-transplant, and refractory cardiac arrest management requiring full hemodynamic support. Japanese cardiac surgery centers under PMDA surveillance mandates concentrate demand for extended-run certified systems.
- Respiratory Therapy:Acute respiratory distress syndrome and bridge-to-lung-transplant protocols. United States academic medical centers are standardizing prolonged run protocols exceeding fourteen days, expanding oxygenator replacement frequency.
- Sepsis Management:Adjunctive extracorporeal support for refractory septic shock with multi-organ dysfunction.
- Congenital Heart Defects:Pediatric and neonatal circulatory support during complex corrective procedures or as bridge to surgical intervention.
Cardiac Support commands premium pricing today; Respiratory Therapy is climbing the fastest as ARDS protocols proliferate.
End User:
Customer type determines contracting leverage, with multi-hospital health systems extracting volume discounts unavailable to standalone specialty clinics.
- Hospitals:Tertiary care systems with established extracorporeal life support programs. Centralized value analysis committees in United States multi-hospital systems are unbundling oxygenator purchases from initial platform procurement.
- Specialty Clinics:Cardiac surgery-focused facilities with limited critical care scope.
- Nursing Facilities:Long-term acute care settings managing prolonged ECMO weaning protocols.
- Home Care Providers:Emerging mobile ECMO retrieval and transport services requiring portable pump-oxygenator configurations.
Hospitals dominate procurement volume today; Home Care Providers represent the steepest expansion trajectory as pre-hospital cannulation protocols mature.
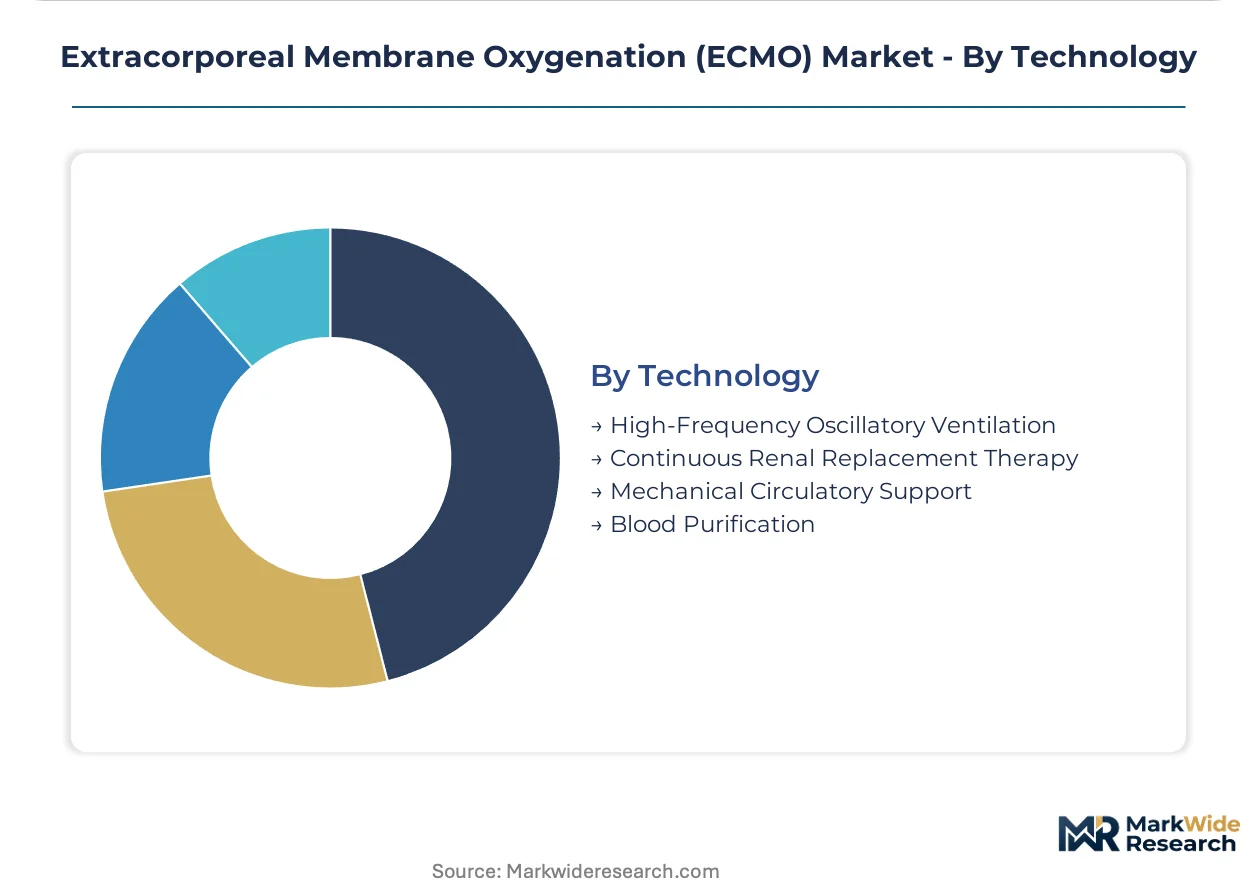
Technology:
Maturity gradients separate established mechanical circulatory support platforms from emerging blood purification integrations still seeking standardized reimbursement pathways.
- Mechanical Circulatory Support:Centrifugal pump and oxygenator systems constituting core ECMO functionality. Recurring revenue from pump head and oxygenator replacement cycles generates concentrated margin pools for incumbent manufacturers.
- Continuous Renal Replacement Therapy:Integrated renal support during prolonged ECMO runs. German intensive care protocols are standardizing combined renal-ECMO circuits for multi-organ failure management.
- High-Frequency Oscillatory Ventilation:Adjunctive respiratory support technology sometimes deployed prior to ECMO initiation.
- Blood Purification:Cytokine adsorption and hemoadsorption systems for sepsis and inflammatory modulation.
Mechanical Circulatory Support anchors revenue today; Blood Purification is gaining share fastest as inflammatory modulation protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perfusionist training programs in the United States, Germany, and Japan anchor ECMO expertise concentration, creating asymmetric access to qualified clinical teams across tertiary centers.
United States
Postcardiotomy shock protocols at Cleveland Clinic and Mayo Clinic drive veno-arterial ECMO procedural volume. FDA Class III premarket approval pathways enforce 12-24 month clinical evidence requirements that entrench incumbent manufacturers. Multi-hospital health systems in Texas and Florida unbundle oxygenator purchases from initial platform procurement through centralized value analysis committees.
Germany
Acute respiratory distress syndrome treatment protocols at Berlin and Munich university hospitals expand veno-venous ECMO addressable procedures. EU Medical Device Regulation notified body conformity assessments mandate technical documentation review for active implantable life-support equipment. The Rhine-Ruhr industrial corridor concentrates hollow-fiber membrane oxygenator manufacturing with integrated heat exchanger production.
Japan
PMDA post-market surveillance mandates under amended Pharmaceutical and Medical Device Act enforcement ordinances require annual safety reports with device-specific adverse event stratification. Tokyo and Osaka university hospitals consolidate purchasing authority through centralized procurement consortia that pre-qualify vendors based on surveillance compliance history. Japanese cardiac surgery centers concentrate demand for extended-run certified systems.
India
Greenfield cardiac surgery center development in Delhi, Mumbai, and Chennai creates first-mover advantage for ECMO program establishment outside established transplant hubs. CDSCO medical device registration requirements for Class C and D life-support equipment are tightening quality management system expectations. Maharashtra and Karnataka tertiary hospitals are importing complete ECMO platforms while building local perfusionist training capacity.
United Kingdom
Specialized respiratory ECMO retrieval services at Royal Brompton and Harefield NHS Foundation Trust standardize mobile cannulation protocols for acute respiratory failure. MHRA conformity assessment for CE-marked devices under retained EU law maintains pre-market technical documentation requirements. The Oxford-Cambridge-London golden triangle concentrates academic research on prolonged run oxygenator biocompatibility.
Extracorporeal Membrane Oxygenation (ECMO) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as integrated system manufacturers face unbundling pressure from hospital procurement teams separating platform purchases from consumable replenishment cycles. The vendor pool concentrates around certified manufacturers with established post-market surveillance infrastructure, consolidating toward ISO 13485-compliant entities. Three archetypes dominate: end-to-end portfolio holders controlling contracting dynamics, specialized cardiac surgery integrators, and regional supply anchors with direct service networks. Competitive moves center on unbundling resistance through consumable lock-in strategies and mobile ECMO service layer expansion.
Among diversified medical technology conglomerates, Medtronic exemplifies the end-to-end portfolio archetype spanning cannulation and oxygenator categories. Getinge AB occupies a position as the European supply anchor with centralized manufacturing and direct service network coverage. LivaNova PLC represents the specialized cardiac surgery integrator archetype, differentiating through procedural integration rather than broad critical care positioning. These three entities anchor competitive dynamics as hospital supply chains separate capital equipment decisions from ongoing circuit and oxygenator purchases.
| Leading Market Players |
|---|
| Medtronic |
| Getinge AB |
| LivaNova PLC |
| Terumo Corporation |
| Fresenius Medical Care AG & Co. KGaA |
| Abbott Laboratories |
| Nipro Corporation |
| Eurosets S.r.l. |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Perfusionist workforce concentration in the United States, Germany, and Japan anchors labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and standard configurations. Cost compression in consumable circuits intensifies as hospital procurement teams unbundle oxygenator replenishment from capital equipment purchases.
Pricing Analysis
The bundled-versus-unbundled service split separates capital platform acquisition from consumable replenishment cycles across tertiary care systems. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and after-sales service bundling. Price erosion runs through standard-tier oxygenators as multi-hospital health systems benchmark component pricing across independent service lines. Specialty clinics demonstrate highest price sensitivity; transplant centers with established extracorporeal life support programs exhibit lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Air freight and cold-chain logistics costs for medical-grade silicone circuits and polymethylpentene membrane modules elevate landed costs for peripheral hospital systems distant from manufacturing hubs. Supply concentrates in Germany, Japan, and the United States for precision magnetic levitation motors and hollow-fiber oxygenator production. Raw material dependencies center on medical-grade silicone, polymethylpentene resin, and specialized polymer extrusion equipment. Single-source vulnerability in centrifugal pump motor assembly creates structural risk. Distribution runs through direct manufacturer service networks and specialized medical device distributors with perfusionist training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on consumable replenishment frequency acceleration and premium-tier platform certification investments that command pricing premiums from high-acuity centers.
For Market Incumbents: Anchor market position through consumable lock-in strategies that resist unbundling pressure from centralized hospital value analysis committees. Deepen backward integration into magnetic levitation motor production to mitigate single-source supplier risk in Germany and Japan. Expand post-market surveillance infrastructure to satisfy PMDA annual safety reporting mandates and FDA Class III quality management requirements. For New Entrants and Emerging Players: Capture first-mover advantage in Indian tertiary hospital expansion corridors in Delhi, Mumbai, and Chennai where ECMO program establishment precedes incumbent saturation. Target mobile ECMO retrieval services as the most penetrable service layer requiring portable pump-oxygenator configurations. Pursue hospital system partnership go-to-market angle with perfusionist training program co-development. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking consumable revenue stream augmentation. Long-term viability centers on recurring revenue intensity from oxygenator and circuit replacement cycles rather than capital equipment cyclicality. Acquisition target archetype: specialized cardiac surgery integrators with established ISO 13485 certification and direct hospital contracting relationships. Signal to watch: EU MDR Article 120 transitional provision expiration timelines that compress competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management certification satisfies FDA and EU MDR premarket requirements for Class III devices. |
| Consumable Lock-In Strategy | Proprietary oxygenator-circuit interfaces resist hospital procurement unbundling and protect margin pools. |
| Perfusionist Training Program Expansion | Clinical workforce development addresses scarcity constraints limiting ECMO program velocity in high-acuity centers. |
| Mobile ECMO Service Layer Development | Pre-hospital cannulation protocols create portable configuration demand outside traditional hospital settings. |
| Backward Integration into Motor Production | In-house magnetic levitation pump motor manufacturing reduces single-source supplier vulnerability from German and Japanese concentration. |
Methodological Framework
Multiple input streams — structured interviews with perfusionists and ECMO program directors, hospital procurement database analysis, and regulatory filing review — were reconciled to construct market estimates. Primary fieldwork engaged perfusion team leads, biomedical engineers, GPO contracts managers, and cardiac surgery department chairs across tertiary centers in the United States, Germany, Japan, and India. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body documentation, PMDA safety reports, hospital procurement consortium records, and ISO certification registries. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning configuration type, application protocol, end-user facility tier, and technology integration level. CAGRs were derived from fitted growth curves against historical procedural volume trajectories and equipment replacement cycle patterns. Forecast inputs incorporated acute respiratory distress syndrome protocol expansion rates, postcardiotomy shock standardization velocity, and perfusionist training pipeline scaling assumptions.
Regulatory enforcement variance, silicone supply chain disruption, and reimbursement pathway recalibration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about procedural volume elasticity and equipment replacement frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Renal Denervation Devices Market