
 Global Sterilization Container Systems Market | 2026-2036
Global Sterilization Container Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterilization Container Systems Market Foresight
Trained sterile processing technicians is collapsing across North American hospital networks, forcing facilities to standardize on instrument sets that reduce handling complexity. B. Braun Melsungen AG leverages its German manufacturing base to dominate European aluminum container supply. STERIS sustains technology leadership in hydrogen peroxide plasma-compatible polymer designs. Integra LifeSciences specializes in silicone-sealed lids for orthopedic tray applications.
Sterilization container systems are enclosed reusable or single-use vessels engineered from anodized aluminum, medical-grade polypropylene, or stainless steel with validated microbial barrier properties, designed to maintain sterility of surgical instruments from processing through point of use. Steam sterilization method anchors volume demand due to its compatibility with metal containers and established hospital infrastructure. Rigid containers capture premium margin pools as hospitals amortize capital costs over multi-year replacement cycles. Peel pouches compete for low-volume specialty instruments where container inventory costs prove prohibitive.
FDA enforces 510(k) clearance for reusable rigid containers under sterile barrier device classifications, while EU MDR requires notified body intervention for all Class IIa sterile barrier systems. EPA regulates ethylene oxide emissions from sterilization facilities, indirectly constraining container selection for compatible processing workflows. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape material specifications for aluminum sourcing and polymer recyclability.
Market Dynamics
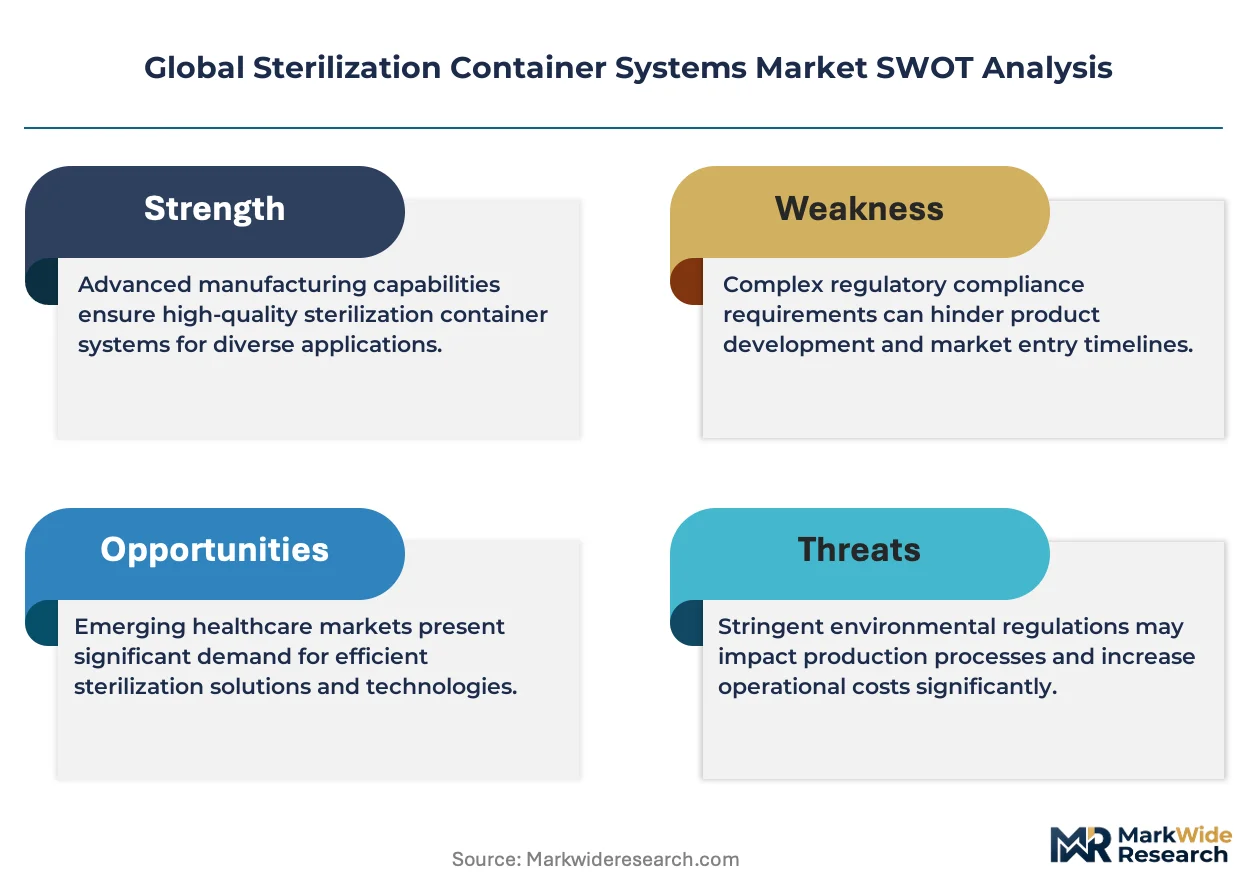
The sterilization container systems market pivots on regulatory tightening of sterile barrier validation requirements, forcing hospitals to replace aging instrument sets with validated rigid containers that withstand repeated steam and hydrogen peroxide plasma cycles.
Growth Catalysts
- EU MDR compliance mandates:Surgical centers across Germany, France, and Italy are accelerating container fleet replacements to meet Class IIa sterile barrier system requirements under notified body oversight.
- ASC consolidation in the United States:Ambulatory surgery center roll-ups by private equity operators standardize procurement on aluminum and polymer container platforms that reduce technician handling errors.
- Steam sterilization infrastructure:Existing hospital autoclave networks anchor demand for anodized aluminum containers compatible with established 134°C saturated steam protocols.
Market Restraints
- Aluminum price volatility:Anodized aluminum sheet input costs fluctuate with LME pricing, compressing margins for European container fabricators dependent on primary metal sourcing.
- Technician workforce collapse:North American sterile processing departments face 23% vacancy rates in certified technician roles, limiting hospital capacity to manage expanded reusable container inventories.
- Peel pouch substitution:Low-volume specialty instruments increasingly bypass rigid containers for single-use sterile barrier systems where capital carrying costs prove prohibitive.
Strategic Opportunities
- China dual carbon alignment:Domestic hospital procurement tenders now prioritize aluminum containers with recycled content certificates and polymer designs meeting circular economy standards under MEE guidelines.
- Orthopedic tray specialization:Silicone-sealed lid configurations for joint replacement instrument sets command premium positioning as procedure volumes rise in aging populations.
- Direct-to-facility distribution:Container manufacturers bypassing traditional medical-surgical distributors capture margin by managing hospital fleet replenishment through vendor-managed inventory programs.
Industry Challenges
- FDA 510(k) clearance timelines:Reusable rigid container submissions face 180-day review cycles for novel polymer formulations, delaying product commercialization and revenue recognition.
- Legacy system integration:RFID-enabled container tracking requires hospital investment in sterile processing department IT infrastructure that interfaces with existing instrument management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterilization Container Systems Market |
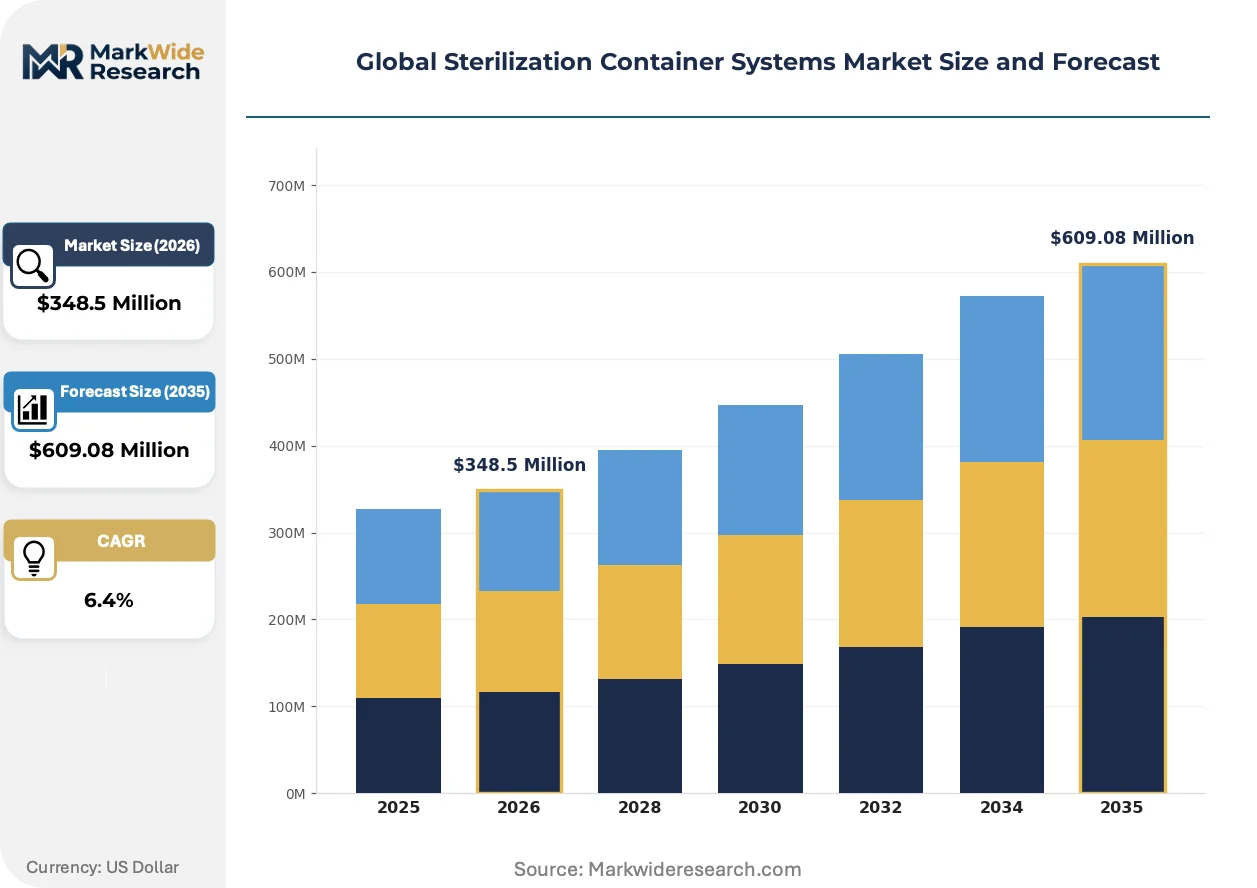
| Market Size in 2026 | $348.5 Million |
| Market Size in 2035 | $609.08 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Peel Pouches, Wraps, Barrier Systems, Sealers Sterilization Method: Steam, Ethylene Oxide, Hydrogen Peroxide Plasma, Radiation, Peracetic Acid End User: Hospitals, Surgical Centers, Diagnostic Laboratories, Dental Clinics, Veterinary Clinics Material: Aluminum, Stainless Steel, Medical Grade Plastics, Silicone, Polypropylene |
| Companies Covered | B. Braun Melsungen AG, Johnson & Johnson, Becton, Dickinson and Company, STERIS, Medline Industries, Integra LifeSciences, KLS Martin Group, Aesculap, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterilization Container Systems Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are fragmenting container design pathways, with polymer and metal platforms diverging toward procedure-specific optimization rather than universal compatibility.
Polypropylene container technology is bifurcating between hydrogen peroxide plasma-compatible formulations for temperature-sensitive instruments and steam-sterilizable grades for general surgery. Academic medical centers in the United States adopt plasma-compatible designs at triple the rate of community hospitals, compressing the addressable market for traditional aluminum containers in high-value orthopedic and cardiovascular sets.
EU MDR technical documentation requirements for Class IIa sterile barrier systems are extending notified body review timelines and forcing container manufacturers to maintain clinical evidence portfolios for each sterilization modality claimed. German surgical centers now demand ISO 17665-1 validation certificates as standard procurement preconditions, shifting competitive advantage toward suppliers with established European regulatory infrastructure.
Hospital purchasing cooperatives are consolidating sterile processing supply contracts, displacing individual facility autonomy with standardized container specifications across multi-hospital networks. This concentration is most visible in the United States, where GPO-administered tenders now specify aluminum container dimensions and silicone seal grades that lock out non-conforming suppliers for multi-year contract periods.
Global Sterilization Container Systems Market Segmentation
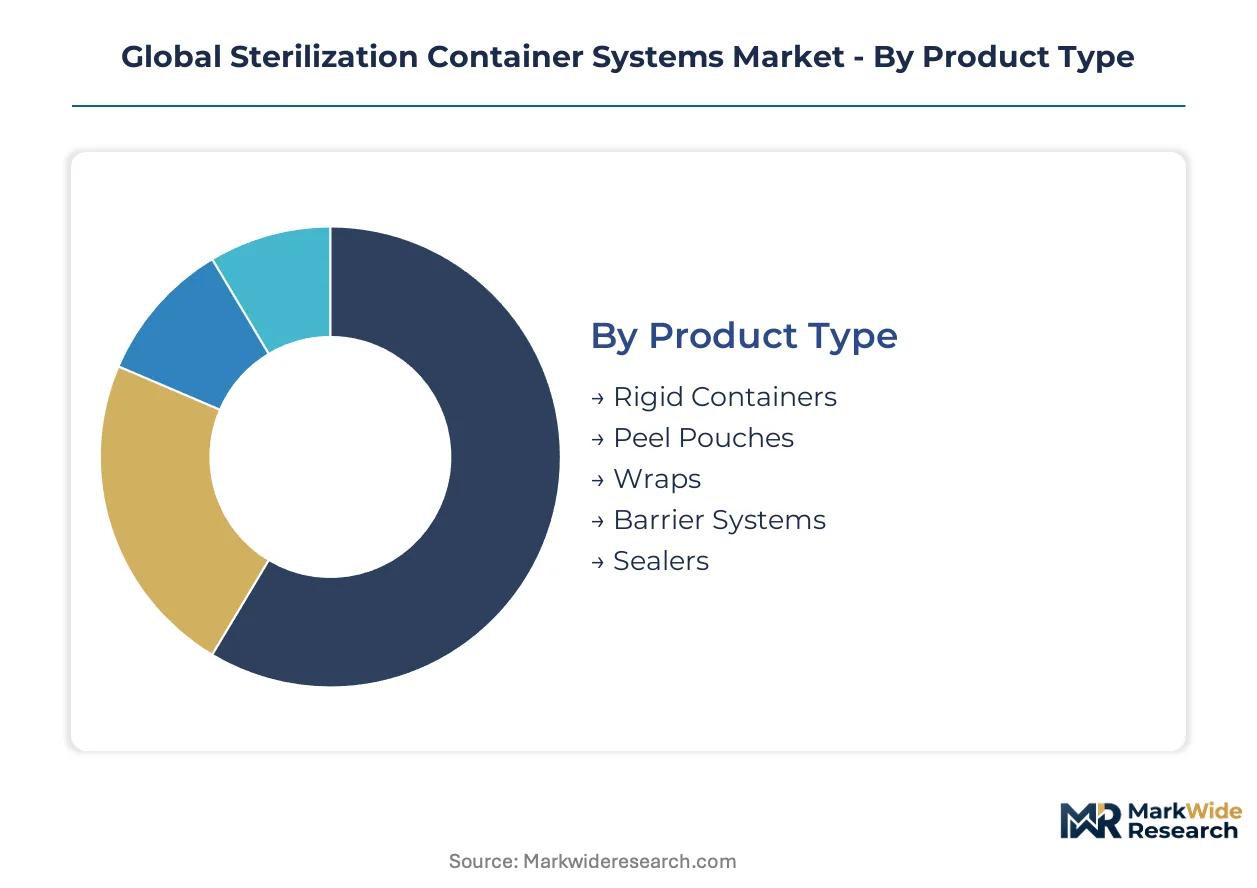
Sterilization container systems fragment across four critical dimensions where material science, regulatory validation, and end-use workflow requirements intersect. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape supplier competitive positioning.
Product Type:
FDA 510(k) clearance requirements and EU MDR Class IIa validation protocols create tiered entry barriers across product formats, concentrating premium positioning in validated reusable systems while disposable alternatives capture cost-sensitive niches.
- Rigid Containers:Anodized aluminum and medical-grade polymer vessels with validated microbial barrier properties designed for 500+ steam or plasma sterilization cycles. German surgical centers and US hospital networks standardize procurement on these platforms to satisfy EU MDR technical documentation and Joint Commission audit requirements.
- Peel Pouches:Single-use sterile barrier systems comprising medical-grade paper and polymer film laminates. Low-volume specialty instruments in ambulatory settings favor these where capital carrying costs for rigid container fleets prove prohibitive.
- Wraps:Woven and non-woven textile barriers for instrument tray coverage. Community hospitals in India and Southeast Asia deploy these for cost containment in high-turnover general surgery sets.
- Barrier Systems:Integrated sterile field maintenance solutions combining container, filter, and documentation components. Academic medical centers in the United States adopt these for complex orthopedic and cardiovascular procedure workflows.
- Sealers:Heat-sealing equipment for pouch and tray closure validation. Diagnostic laboratories in Japan and South Korea invest in these to support in-house sterilization capacity expansion.
Established volume favors Rigid Containers; emerging adoption favors Peel Pouches.
Sterilization Method:
Hospital infrastructure investment patterns and instrument heat tolerance specifications determine method selection, with steam dominance in metal-compatible general surgery and plasma penetration in temperature-sensitive specialty sets.
- Steam:Saturated steam at 134°C remains the backbone of hospital sterile processing departments. Anodized aluminum container demand concentrates here due to thermal conductivity and established autoclave network compatibility across United States and European facilities.
- Ethylene Oxide:Low-temperature gas sterilization for heat-sensitive polymers and electronics. EPA emission regulations constrain United States facility expansion, shifting compatible container demand toward outsourced sterilization service providers.
- Hydrogen Peroxide Plasma:Low-temperature vaporized hydrogen peroxide for temperature-sensitive instruments. Academic medical centers in the United States adopt polymer containers validated for this method at triple the rate of community hospitals for orthopedic and cardiovascular sets.
- Radiation:Gamma and electron beam sterilization for single-use device manufacturing. Contract sterilization facilities in Belgium and the Netherlands drive container demand for medical device OEM supply chains.
- Peracetic Acid:Liquid chemical sterilization for flexible endoscopes and lumened instruments. Ambulatory surgery centers in France and Italy deploy these systems for gastrointestinal procedure suites.
Steam sterilization anchors installed base economics; hydrogen peroxide plasma gains share fastest in high-value instrument sets.
End User:
Capital intensity and regulatory scrutiny scale inversely across end-user tiers, with hospital networks amortizing container investments over decade-long replacement cycles while smaller facilities prioritize disposable alternatives.
- Hospitals:Multi-specialty acute care facilities with centralized sterile processing departments. United States hospital purchasing cooperatives and German hospital networks consolidate procurement on standardized aluminum and polymer container specifications.
- Surgical Centers:Ambulatory facilities performing same-day procedures. Private equity roll-ups in the United States drive fleet standardization to reduce technician handling errors across multi-site operations.
- Diagnostic Laboratories:Clinical and pathology testing facilities with instrument sterilization requirements. Indian and Chinese laboratory networks expand in-house processing capacity.
- Dental Clinics:Private practice and corporate dental chains with instrument reprocessing needs. European dental service organizations adopt compact rigid container systems for practice consolidation efficiency.
- Veterinary Clinics:Animal health facilities with surgical and diagnostic instrument sterilization. North American veterinary hospital chains invest in human-grade container systems for specialty procedure expansion.
Hospital procurement concentrates volume purchasing power; surgical centers represent the steepest expansion trajectory through ASC consolidation.
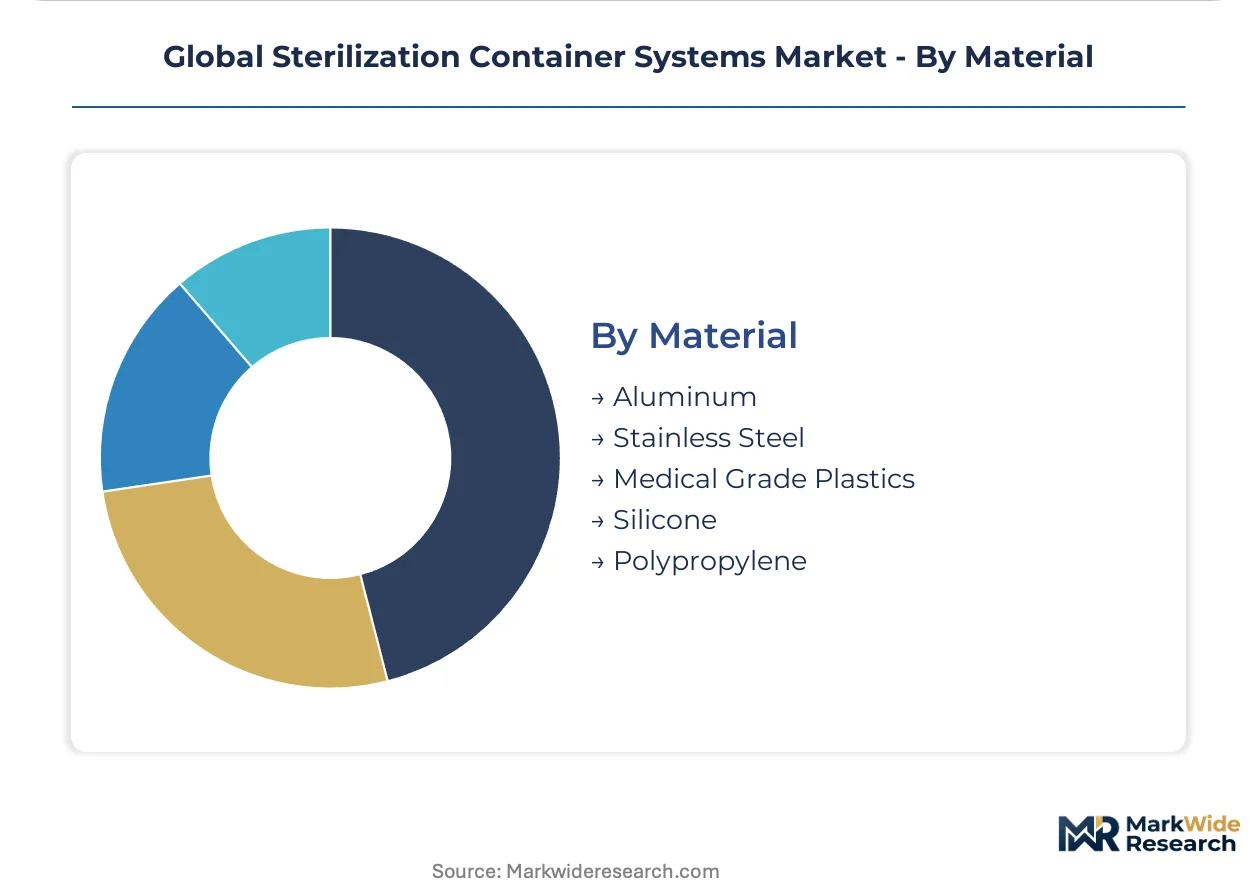
Material:
Supply chain provenance and circular economy compliance are reshaping material specifications, with recycled content certificates and carbon footprint documentation emerging as standard tender requirements in European and Chinese procurement.
- Aluminum:Anodized aluminum sheet formed into perforated sterilization containers with microbial barrier filtration systems. European fabricators dependent on LME-priced primary metal face margin compression from input cost volatility.
- Stainless Steel:304 and 316-grade surgical steel for heavy-duty instrument sets and orthopedic trays. Japanese and German manufacturers maintain specialty production for high-wear applications.
- Medical Grade Plastics:Engineered polymers including polycarbonate and PPSU for single-use and limited-reuse applications. Chinese domestic tenders now prioritize circular economy compliance under MEE guidelines.
- Silicone:Elastomeric seals and gaskets for lid closure validation in orthopedic tray configurations. Aging population joint replacement volumes drive premium positioning for silicone-sealed designs.
- Polypropylene:Steam and plasma-compatible formulations for general surgery and temperature-sensitive instrument sets. Bifurcation between sterilization modalities is fragmenting supplier product development pathways.
Aluminum retains dominant share in established hospital infrastructure; polypropylene climbs fastest in plasma-compatible specialty applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German surgical centers prioritize reusable aluminum containers under EU MDR validation mandates, while United States facilities balance rigid container fleets against peel pouch substitution for low-volume sets. Chinese hospital procurement increasingly weights recycled content certificates in aluminum sourcing decisions.
United States
Ambulatory surgery center consolidation by private equity operators standardizes procurement on aluminum and polymer container platforms. FDA 510(k) clearance requirements for reusable rigid containers enforce 180-day review cycles that delay novel polymer commercialization. Greater Boston academic medical centers adopt hydrogen peroxide plasma-compatible designs at triple the rate of community hospitals.
Germany
Surgical centers accelerate container fleet replacements to satisfy EU MDR Class IIa sterile barrier system requirements under notified body oversight. ISO 17665-1 validation certificates now serve as standard procurement preconditions in federal hospital tenders. Bavarian manufacturing clusters anchor European aluminum container fabrication despite LME price volatility compressing fabricator margins.
China
Domestic hospital procurement tenders prioritize aluminum containers with recycled content certificates under MEE circular economy guidelines. Dual carbon goals reshape material specifications for polymer designs targeting steam and plasma sterilization compatibility. Yangtze River Delta medical device manufacturing hubs expand sterile processing capacity for export-oriented instrument sets.
Japan
Diagnostic laboratories invest in heat-sealing equipment for pouch and tray closure validation to support in-house sterilization expansion. METI industrial standards govern medical-grade polymer specifications for temperature-sensitive instrument applications. Kansai region clinical testing facilities drive demand for compact rigid container systems in consolidated laboratory networks.
India
Community hospitals deploy woven and non-woven textile wraps for cost containment in high-turnover general surgery sets. CDSCO medical device regulations tighten sterile barrier validation requirements for imported container systems. Maharashtra diagnostic laboratory networks expand in-house processing capacity with human-grade container procurement.
Global Sterilization Container Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sterilization container supply. German and United States-based manufacturers dominate validated aluminum and polymer platform production, while regional fabricators compete on cost-sensitive wrap and pouch formats. Strategic archetypes separate plasma-compatible polymer specialists from steam-sterilization aluminum fabricators and integrated sterile barrier system providers. Competitive moves concentrate on M&A-driven portfolio diversification and vendor-managed inventory programs that bypass traditional medical-surgical distribution.
Among Germany-based integrated suppliers, B. Braun Melsungen AG occupies a position exemplifying European aluminum container dominance through manufacturing scale. STERIS and Integra LifeSciences represent United States-based archetypes differentiated by technology specialization—STERIS anchors plasma-compatible polymer design leadership, while Integra LifeSciences exemplifies silicone-sealed lid configuration expertise for orthopedic tray applications. These three companies sit within distinct competitive vectors that shape procurement segmentation across hospital purchasing cooperatives and academic medical center tenders.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Becton, Dickinson and Company |
| STERIS |
| Medline Industries |
| Integra LifeSciences |
| KLS Martin Group |
| Aesculap |
| Getinge AB |
| Others |
Supply & Pricing Matrix
Polypropylene substitution for anodized aluminum in plasma-compatible container designs simultaneously shifts procurement geography toward German and United States polymer compounders while compressing margin pools for European metal fabricators tethered to volatile LME pricing.
Pricing Analysis
Long-term offtake contracts dominate hospital purchasing cooperative procurement, with GPO-administered tenders locking aluminum container specifications for multi-year periods. Three-tier pricing structure across premium, standard, and economy levels separates silicone-sealed orthopedic configurations from general surgery sets and cost-sensitive wrap alternatives. Cost compression in standard aluminum tiers is intensifying because LME price volatility transfers directly to fabricator margins. Ambulatory surgery centers exhibit highest price sensitivity due to capital carrying cost constraints, while academic medical centers prioritize plasma compatibility over unit economics.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta manufacturing hubs to European hospital networks fluctuate with Red Sea shipping lane congestion and container availability at Shanghai terminals. Primary aluminum supply concentrates in China, Germany, and the United States, with anodized sheet fabrication anchored in Bavarian industrial clusters. Polypropylene resin draws from petrochemical complexes in South Korea, Saudi Arabia, and the United States Gulf Coast. Single-source vulnerability persists for medical-grade silicone seal compounds used in orthopedic tray lids. Distribution runs through medical-surgical distributors and direct-to-facility vendor-managed inventory programs serving consolidated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterilization container systems market sits in early-cycle recovery as EU MDR compliance deadlines force hospital fleet replacements and ASC consolidation standardizes procurement specifications across multi-site operations.
For Market Incumbents: Compound regulatory infrastructure advantage by accelerating ISO 17665-1 validation certificate portfolios ahead of notified body review timeline extensions. Deepen backward integration into recycled aluminum sourcing to satisfy Chinese MEE circular economy tender requirements and offset LME price volatility. Defend against peel pouch substitution in low-volume specialty sets by bundling container fleet management software with hardware procurement.
For New Entrants and Emerging Players: RFID-enabled container tracking integration services represent an under-served layer where incumbent hardware manufacturers lack sterile processing department IT infrastructure expertise. Target diagnostic laboratory networks in India and Southeast Asia expanding in-house sterilization capacity with compact rigid container systems priced below hospital-grade specifications. Pursue direct-to-facility distribution partnerships that bypass entrenched medical-surgical distributor relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with established European regulatory infrastructure and United States FDA 510(k) clearance pathways. Long-term viability centers on suppliers capable of spanning both steam and hydrogen peroxide plasma sterilization modalities as academic medical center adoption bifurcates. Watch for inflection signals in Chinese domestic tender awards prioritizing dual carbon-aligned material specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body oversight extends competitive moats for established European suppliers. |
| Plasma-Compatible Polymer R&D Expansion | Academic medical center adoption triples addressable market in high-value instrument sets. |
| Recycled Content Certificate Procurement | Chinese MEE guidelines and EU Green Deal reshape aluminum sourcing tender requirements. |
| Vendor-Managed Inventory Program Deployment | Direct hospital relationships capture margin from traditional medical-surgical distribution. |
| RFID Tracking Platform Integration | Sterile processing department IT infrastructure requirements lock in multi-year contract renewals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile processing department managers, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and container manufacturing operations executives. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, hospital procurement tender records, and aluminum LME pricing archives. Bottom-up facility-level demand estimates triangulated against top-down market sizing across product type, sterilization method, end user, and material segmentation dimensions.
Across the analysis window, volume and value outputs reflect segmented modeling of replacement cycle timing, fleet standardization patterns, and modality adoption rates. CAGRs were derived from installed base depreciation schedules and new procurement flow projections. Forecast inputs incorporated EU MDR implementation phasing, United States ASC consolidation velocity, and Chinese dual carbon procurement weighting evolution.
Underlying assumptions cover regulatory timeline adherence, aluminum price band stability, and technician workforce availability, with deviation risk concentrated in FDA review cycle extensions and peel pouch technology substitution rates. Recalibration cycles align with material shifts in EU MDR enforcement intensity and notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Breast Shells Market
Medical Supplies
Finger Splint Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Foley Trays Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Luer Plug Market