
 Argentina Mobile Wallet Market | 2026-2036
Argentina Mobile Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Mobile Wallet Market Intelligence
Market Context
Multi-source platform aggregation is consolidating as Argentina's mobile wallet infrastructure matures beyond single-bank silos. Mercado Pago leverages its merchant network density to sustain payment volume leadership across Latin America's third-largest economy. Ualá anchors consumer onboarding through fee-free digital accounts and integrated prepaid card issuance. Naranja X competes via its credit-union heritage and deep penetration in provincial retail corridors.
Technical Definition and Segment Structure
An Argentina mobile wallet constitutes a software-based payment instrument enabling value storage, transfer, and redemption through smartphone interfaces, typically incorporating tokenized credential management and real-time settlement protocols aligned with BCRA Sistema de Transferencias de Bajo Valor specifications. QR code payments dominate transaction volume among retail customers due to minimal hardware requirements and interoperability mandates under BCRA Resolution B-12000, while NFC payments remain concentrated among large corporations with point-of-sale infrastructure budgets. Cloud-based solutions occupy the fastest-expanding technology tier as providers abandon on-premise architectures to reduce latency and compliance overhead.
Regulatory Framework and Outlook
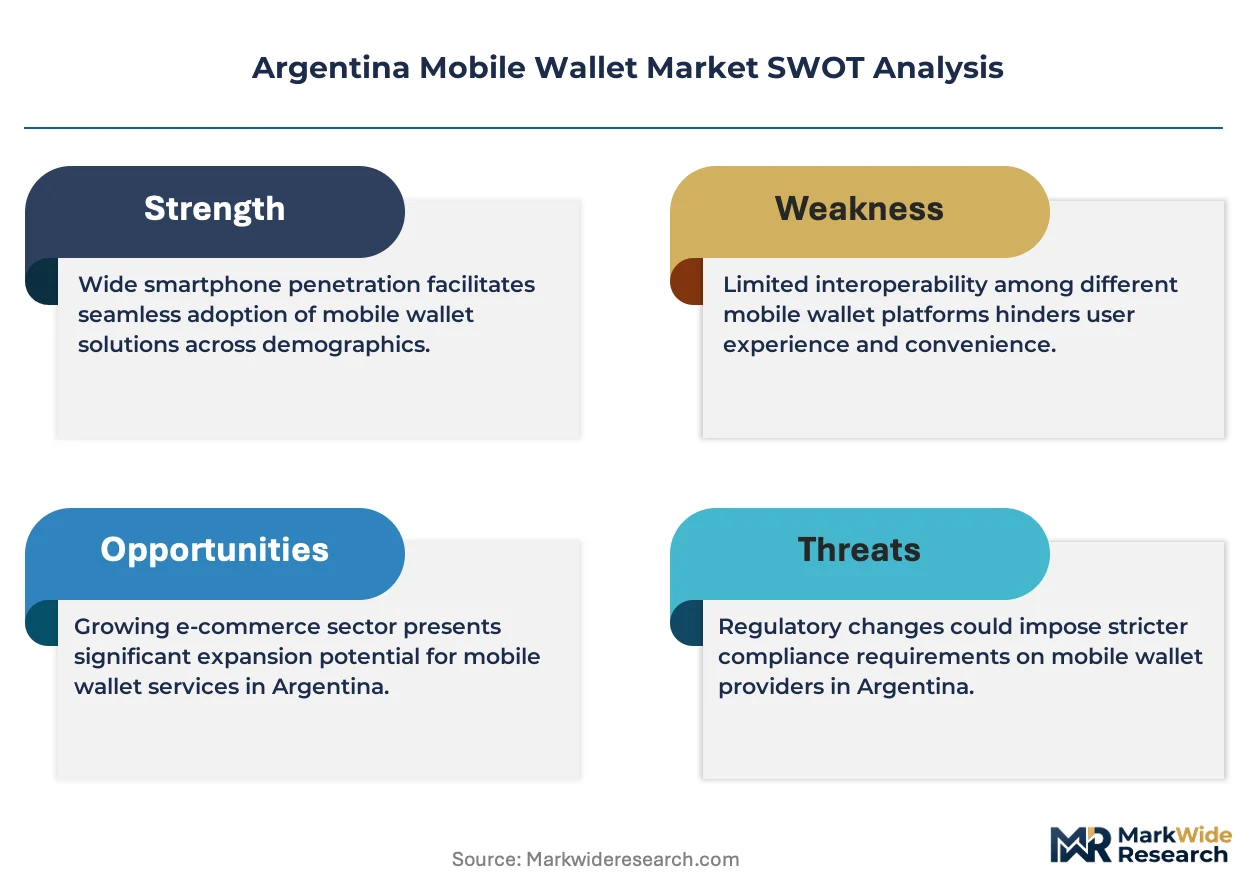
BCRA licensing requirements, SEPRODATA cybersecurity standards, and AFIP tax reporting obligations collectively elevate operational barriers for new entrants while accelerating formalization of previously informal payment flows. The central bank's fintech sandbox and peso-denominated settlement rules constrain foreign platform participation but strengthen domestic provider ecosystems. Stakeholders must monitor BCRA regulatory tightening on foreign-exchange linked wallets and evolving SEPRODATA data localization mandates that will reshape platform architecture decisions.
Market Dynamics
QR code interoperability mandates under BCRA Resolution B-12000 are compressing settlement friction between competing wallet ecosystems, forcing providers to abandon proprietary closed-loop architectures in favor of open-rail integration that accelerates merchant onboarding velocity across Argentina's cash-heavy retail corridors.
Growth Catalysts
- BCRA Sistema de Transferencias de Bajo Valor:Real-time settlement infrastructure eliminates interbank clearing delays, reducing transaction abandonment rates among unbanked users in Greater Buenos Aires.
- SEPRODATA cybersecurity certification:Mandatory data localization standards build consumer trust in cloud-based wallet architectures, accelerating formalization of informal merchant payment flows.
- Prepaid card issuance integration:Digital account providers leverage physical card distribution networks to bridge cash-to-digital conversion gaps in Córdoba and Rosario retail corridors.
Market Restraints
- Peso volatility and foreign-exchange controls:BCRA restrictions on dollar-linked wallet balances constrain product innovation for wealth preservation use cases among high-income segments.
- Hardware dependency in NFC infrastructure:Point-of-sale terminal upgrade costs limit contactless adoption to large-format retailers, excluding small merchants from premium payment experiences.
- Tax reporting granularity under AFIP:Transaction-level visibility requirements increase compliance overhead for micro-merchants, creating onboarding friction in informal economy strongholds.
Strategic Opportunities
- Provincial retail corridor penetration:Interior provinces beyond Buenos Aires exhibit sub-40% wallet adoption rates, presenting first-mover advantages for providers with agent network density.
- Credit-union partnership models:Cooperative financial institutions in Mendoza and Tucumán seek white-label wallet infrastructure to retain deposit bases against fintech disintermediation.
- Cross-border remittance rails:BCRA sandbox provisions for regional payment interoperability enable corridor-specific products targeting Argentine diaspora flows from Chile and Uruguay.
Industry Challenges
- Tokenized credential management expertise:Shortage of engineers with EMVCo and PCI-DSS compliance experience delays product certification timelines for new market entrants.
- Legacy core banking integration:Incumbent financial institutions operate on decades-old batch-processing architectures that resist real-time API connectivity required for wallet interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Mobile Wallet Market |
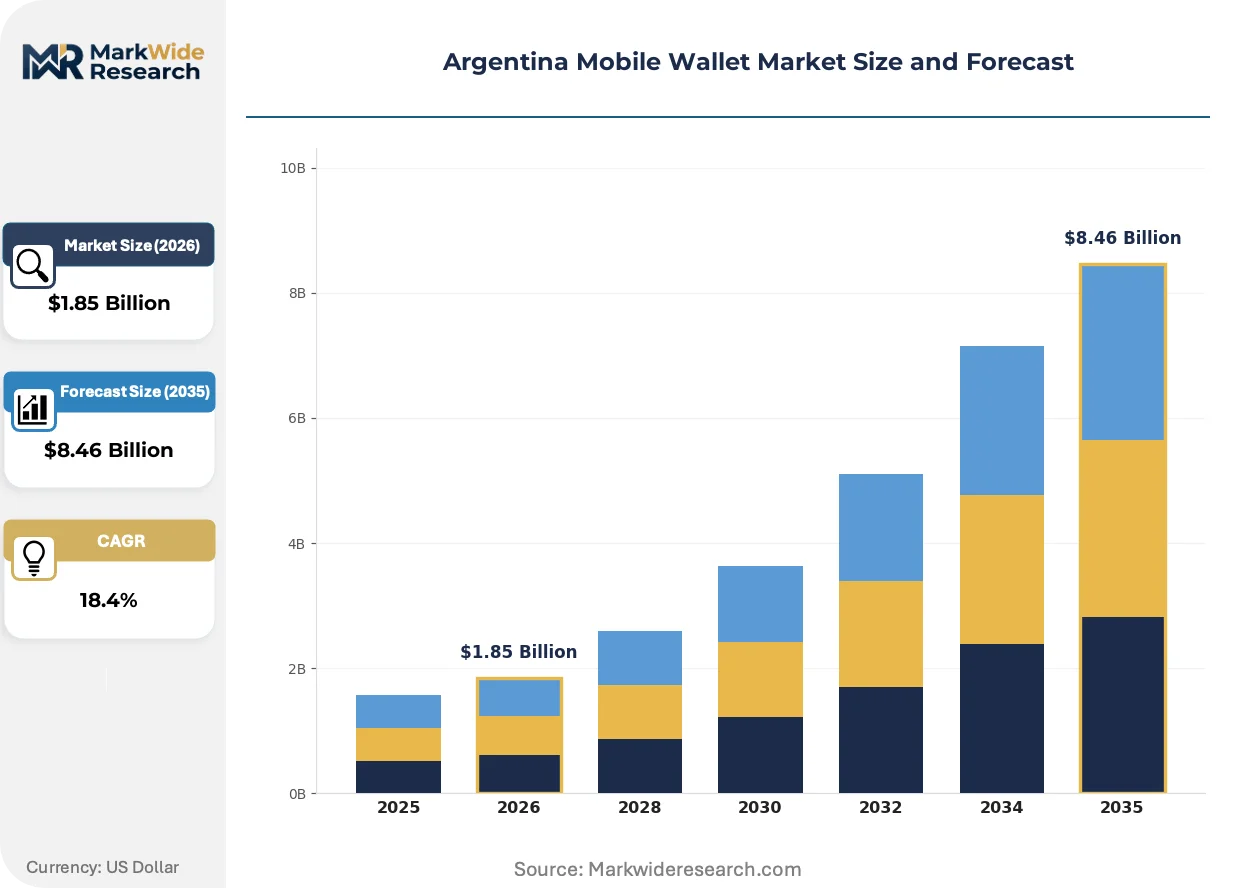
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer Payments, Merchant Payments, Bill Payments, Top-Up Services End User: Retail Customers, Small Enterprises, Large Corporations, Financial Institutions Technology: NFC Payments, QR Code Payments, Cloud-Based Solutions, Blockchain Integration Level: API Integrated, Standalone Solutions, Multi-Platform Support, Customizable Options |
| Companies Covered | Naranja X, EBANX, Mercado Pago, TodoPago, Ohana, Ualá, PayPal Argentina, VALEpei, Brubank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Mobile Wallet Market Strategic Shifts & Innovations
Cloud-native wallet architectures are displacing on-premise deployments as providers prioritize latency reduction and elastic scaling capacity, while regulatory pressure on data sovereignty accelerates domestic infrastructure investment patterns across the Argentine fintech ecosystem.
Biometric authentication protocols anchored in device-native fingerprint and facial recognition are automating Know-Your-Customer verification workflows for digital account origination. Micro-merchants in Buenos Aires informal markets adopt these frictionless onboarding flows at triple the rate of traditional document-based processes. This automation is compressing customer acquisition costs and collapsing the time-to-first-transaction interval from days to minutes.
BCRA fintech licensing reforms introduced through the central bank's regulatory sandbox framework mandate operational separation between payment processing and deposit-taking functions. Domestic wallet providers restructure corporate entities to comply with ring-fencing requirements while foreign platforms face exclusion from peso-denominated settlement rails. Small and mid-size fintechs absorb disproportionate compliance costs as they lack legal infrastructure scale to navigate multi-regulator coordination between BCRA and SEPRODATA.
Merchant acquisition patterns pivot from hardware-dependent POS terminal distribution toward software-only QR code enablement that eliminates upfront capital expenditure barriers. Neighborhood grocery stores and street vendors in Greater Buenos Aires replace cash handling with printed static codes that route transactions through interoperable clearing infrastructure. This behavioral shift concentrates transaction volume growth in sub-500-peso ticket sizes previously dominated by physical currency exchange.
Argentina Mobile Wallet Market Segmentation
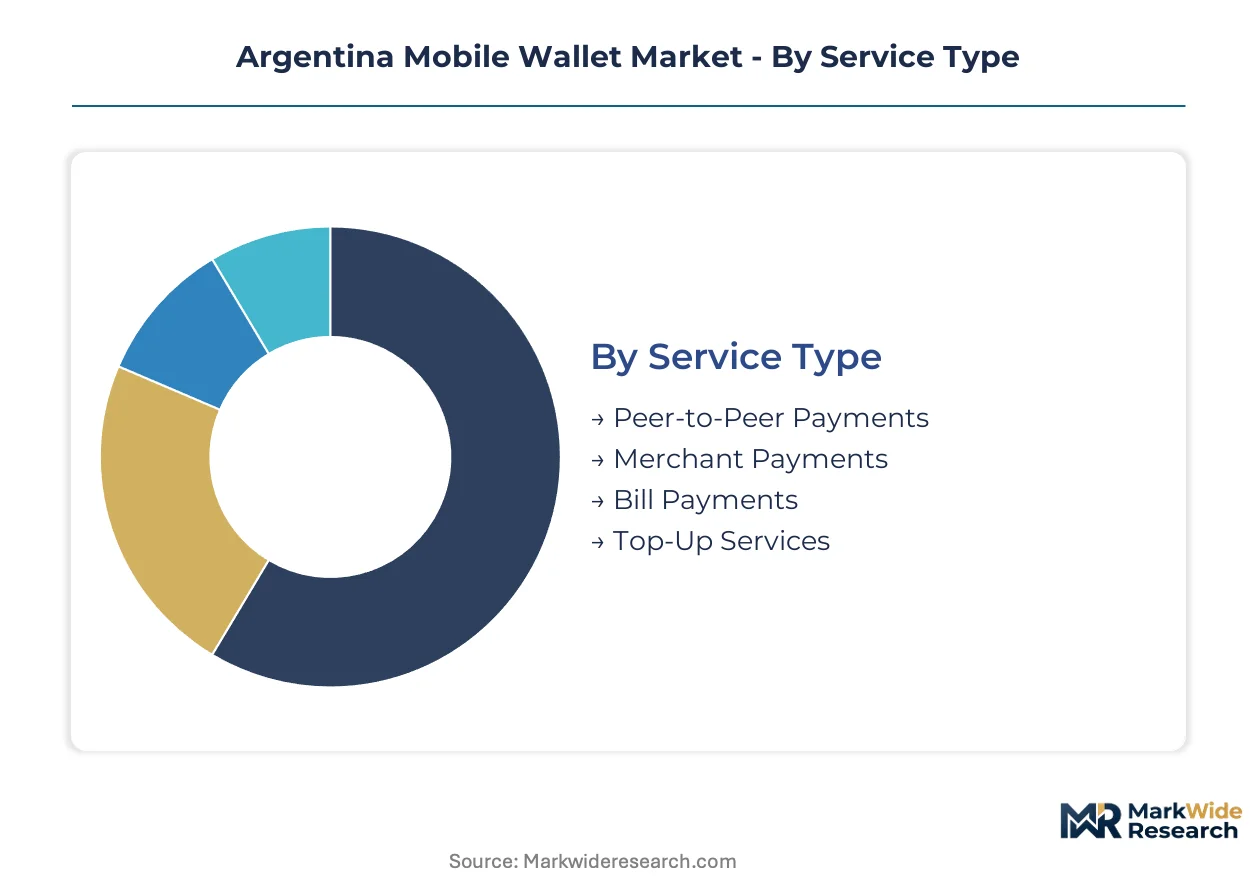
Segmentation in Argentina's mobile wallet market reveals how BCRA regulatory tiers and SEPRODATA compliance obligations concentrate provider investment across distinct operational models. Each dimension carries divergent certification burdens that reshape competitive economics and customer acquisition strategies.
Service Type:
Merchant Payments and Peer-to-Peer Payments require BCRA Sistema de Transferencias de Bajo Valor certification plus AFIP transaction reporting integration, while Bill Payments and Top-Up Services operate under lighter SEPRODATA data localization standards alone.
- Merchant Payments:QR code-based settlement infrastructure dominates transaction volume among Buenos Aires street vendors and neighborhood grocers. Demand concentrates in Greater Buenos Aires informal retail corridors where cash-to-digital conversion accelerates fastest, driven by BCRA interoperability mandates that eliminated proprietary closed-loop systems.
- Peer-to-Peer Payments:Real-time fund transfers between individual users leverage tokenized credential management aligned with EMVCo security protocols. Adoption clusters among unbanked populations in Córdoba and Rosario where traditional banking access remains limited, constrained by peso volatility affecting wallet balance retention.
- Bill Payments:Utility and service payment aggregation through mobile interfaces. Providers integrate with AFIP tax authority APIs for automated fiscal receipt generation.
- Top-Up Services:Prepaid mobile credit and transportation card value loading. Demand tracks prepaid card distribution network density across provincial agent locations.
Leading the category by volume: Merchant Payments. Growing fastest: Peer-to-Peer Payments.
End User:
Cost tier differentiation separates fee-sensitive micro-merchants from enterprise clients absorbing premium API integration expenses, with compliance overhead scaling disproportionately for smaller entities lacking dedicated legal infrastructure.
- Retail Customers:Individual consumers seeking basic payment storage and transfer capabilities. Buenos Aires unbanked households drive onboarding velocity through biometric KYC automation that compresses account origination to minutes.
- Small Enterprises:Neighborhood stores and service providers adopting QR code acceptance. Mendoza and Tucumán cooperative financial institutions seek white-label wallet infrastructure to retain deposit bases against fintech disintermediation.
- Large Corporations:Enterprise treasury management and employee disbursement platforms. NFC infrastructure investment concentrates here due to dedicated POS upgrade budgets unavailable to smaller merchants.
- Financial Institutions:Banks and credit unions deploying branded wallet applications. Legacy core banking integration challenges delay real-time API connectivity for this segment.
Retail Customers anchor volume. Small Enterprises expand most rapidly.
Technology:
Application focus distinguishes hardware-dependent infrastructure from software-only deployment models, with cloud architectures attracting accelerated investment due to elastic scaling capacity and reduced latency.
- QR Code Payments:Static and dynamic code generation enabling merchant acceptance without terminal investment. Street vendors across Greater Buenos Aires replace cash handling with printed codes routing through interoperable clearing infrastructure.
- Cloud-Based Solutions:Distributed server architectures replacing on-premise deployments. Providers prioritize domestic data center investment to satisfy SEPRODATA localization mandates while reducing compliance overhead.
- NFC Payments:Contactless transaction protocols requiring upgraded point-of-sale hardware. Large-format retailers in Buenos Aires metropolitan area concentrate adoption.
- Blockchain:Distributed ledger experimentation within BCRA fintech sandbox framework. Foreign-exchange linked applications face regulatory restriction under peso-denominated settlement rules.
QR Code Payments dominate transaction count. Cloud-Based Solutions attract fastest provider migration.
Integration Level:
Customer type stratification separates developers seeking deep system embedding from merchants demanding plug-and-play simplicity, with customization premiums correlating to technical sophistication requirements.
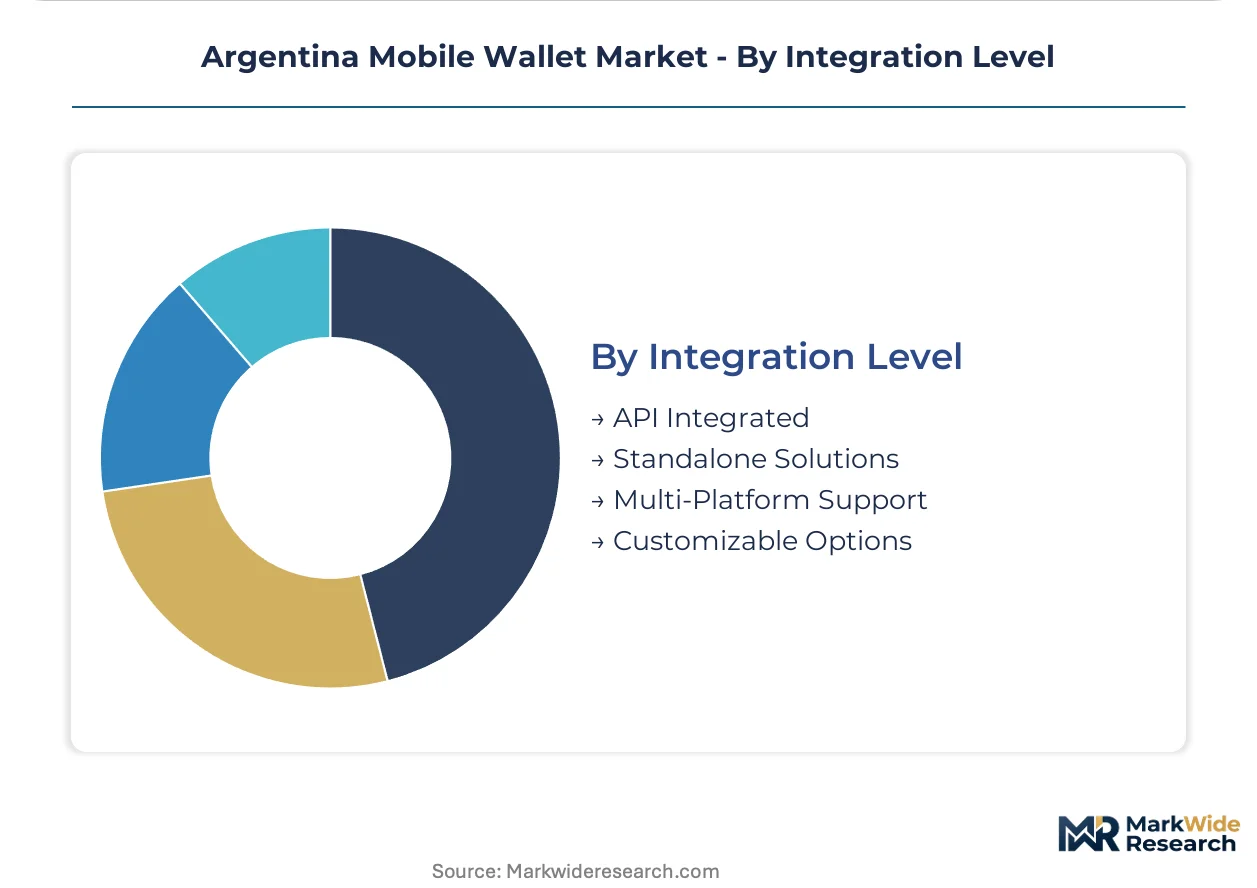
- API Integrated:Deep system connectivity enabling embedded finance applications. Fintechs and neobanks leverage these rails for account aggregation and automated reconciliation.
- Standalone Solutions:Self-contained wallet applications requiring no external system connection. Informal economy micro-merchants prefer this reduced complexity despite limited feature depth.
- Multi-Platform Support:Cross-device synchronization across iOS, Android, and web interfaces. Provincial retail corridors with heterogeneous device ecosystems drive demand.
- Customizable Options:White-label infrastructure for credit unions and cooperative banks. Mendoza and Tucumán institutions deploy these to differentiate against national fintech brands.
API Integrated solutions command premium pricing. Standalone Solutions penetrate fastest among underbanked segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean export earnings from the Pampas grain belt finance fintech infrastructure deployment across Argentina's central provinces. Currency volatility in this commodity-dependent economy accelerates demand for peso-denominated digital payment rails that bypass traditional banking friction.
Greater Buenos Aires
Unbanked retail households drive the steepest cash-to-digital conversion velocity nationwide. BCRA Resolution B-12000 mandates QR code interoperability that eliminates closed-loop wallet silos. Street vendors in La Matanza and Lomas de Zamora replace physical currency with printed static codes routing through real-time clearing infrastructure.
Córdoba Province
Cooperative financial institutions seek white-label wallet infrastructure to retain deposit bases against fintech disintermediation. SEPRODATA data localization standards elevate compliance costs for smaller credit unions. Agent network density in Córdoba capital and Villa María accelerates prepaid card distribution bridging cash-to-digital gaps.
Santa Fe and Rosario Corridor
Grain trading settlements generate concentrated B2B payment flows demanding API-integrated treasury solutions. AFIP transaction-level reporting requirements increase onboarding friction for agricultural micro-merchants. The Rosario commodity exchange cluster pushes for real-time settlement integration with mobile wallet rails.
Mendoza and Western Provinces
Wine export corridors exhibit sub-40% wallet adoption rates among tourism-facing merchants. Provincial retail banking penetration lags central Argentina, creating first-mover opportunities for providers with agent network scale. Mendoza's cooperative banks deploy customizable wallet options to differentiate against national brands.
Argentina Mobile Wallet Market Key Industry Players
Global majors compete with regional champions across merchant network density and regulatory compliance capabilities. The market structures around three tiers: fintech-native platforms with cloud-native architectures, incumbent financial institutions with legacy core banking integration, and cooperative credit unions seeking white-label infrastructure. Strategic moves concentrate on QR code interoperability certification and prepaid card distribution network expansion.
Within the fintech-native tier, Mercado Pago and Ualá exemplify divergent customer acquisition strategies. Mercado Pago leverages its e-commerce merchant density to sustain payment volume leadership. Ualá anchors consumer onboarding through fee-free digital accounts and integrated prepaid card issuance. Naranja X occupies a position bridging credit-union heritage with provincial retail corridor penetration.
| Leading Market Players |
|---|
| Naranja X |
| EBANX |
| Mercado Pago |
| TodoPago |
| Ohana |
| Ualá |
| PayPal Argentina |
| VALEpei |
| Brubank |
| Others |
Cost & Logistics Intelligence
SEPRODATA data localization mandates gate both qualified cloud infrastructure supply and premium-tier pricing access for Argentina mobile wallet providers, compressing margins for entrants lacking domestic data center scale while rewarding compliant incumbents with BCRA certification priority.
Pricing Analysis
Warranty and service bundling separates full-stack providers from unbundled API-only competitors, with SEPRODATA compliance certification and real-time settlement uptime guarantees commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels tracks BCRA licensing tier and AFIP reporting integration depth. Cost compression in the economy tier intensifies because micro-merchant onboarding subsidies drain unit economics. Small enterprises in Greater Buenos Aires informal corridors exhibit highest price sensitivity, while large corporations absorbing API integration fees show lowest.
Supply Chain Analysis
Single-source vulnerability sits with AWS and Google Cloud's Argentine data center presence under SEPRODATA localization rules. Cloud compute infrastructure draws from Brazil, Chile, and domestic Buenos Aires facilities. Tokenization hardware security modules and EMVCo-certified SDKs rest on limited vendor pools. Logistics chokepoint risk concentrates in undersea cable latency to São Paulo routing nodes. Distribution runs through fintech-native platform direct sales and cooperative financial institution white-label partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a vertical-integration race, with prepaid card distribution networks and agent banking footprints serving as the decisive downstream lever players are consolidating to lock in merchant acquisition velocity.
For Market Incumbents: Acquire agent banking network density in Mendoza and Tucumán corridors before cooperative credit unions consolidate provincial retail access. Defensive consolidation demands backward integration into cloud infrastructure to reduce SEPRODATA compliance overhead, while API standardization investments preempt fintech-native disintermediation of legacy core banking relationships.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in NFC-enabled enterprise solutions creates entry space for QR-native challengers. White-space targets concentrate in bill payment aggregation for agricultural micro-merchants in Santa Fe and Rosario grain corridors. Go-to-market execution should anchor in biometric KYC automation that collapses onboarding friction for unbanked retail households.
For Investors and Strategic Acquirers: BCRA fintech sandbox graduation announcements are the leading indicator that regulatory moats are hardening around viable acquisition targets. Long-term viability frames around providers with demonstrated interoperability certification and domestic data center operational scale. Target acquisition archetype: cloud-native platforms with proven provincial agent network economics. Monitor SEPRODATA enforcement actions as the inflection signal for compliance-cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| SEPRODATA Certification Investment | Domestic data center deployment satisfies BCRA localization mandates while reducing compliance latency. |
| Agent Network Expansion | Prepaid card distribution density in Córdoba and Rosario bridges cash-to-digital conversion gaps. |
| API Interoperability Development | Real-time settlement integration with BCRA Sistema de Transferencias de Bajo Valor eliminates closed-loop silos. |
| Biometric KYC Automation | Facial recognition onboarding compresses customer acquisition costs for unbanked Greater Buenos Aires households. |
| Credit-Union White-Label Partnership | Customizable wallet infrastructure retains deposit bases in Mendoza and Tucumán cooperative corridors. |
Research Approach
Central bank regulatory filings, SEPRODATA certification registries, and AFIP transaction reporting databases formed the secondary backbone, cross-referenced with primary interviews of BCRA policy officers, fintech platform CTOs, cooperative credit union executives, and merchant acquisition leads. Bottom-up wallet transaction volume estimates triangulated against top-down payment systems data from BCRA statistical releases.
Historical trendline analysis tracked QR code adoption velocity and real-time settlement penetration across the projection horizon. Segmentation modeling incorporated service type tier, end-user scale, technology deployment architecture, and provincial regulatory cluster. CAGRs derived from S-curve diffusion analysis of cash-to-digital conversion patterns, with peso volatility and BCRA foreign-exchange control stringency serving as scenario-weighting inputs.
Underlying measurement precision varies by segment; merchant payment volume estimates carry tighter precision than blockchain experimentation adoption projections. Forecasts reflect assumptions around regulatory enforcement consistency and macroeconomic stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Cryptocurrency Payment Apps Market
Payments
Transit Cards Market
Payments
Vehicle Toll Collection and Access System Market
Payments
GCC Mobile Payment Market
Payments
Canada Prepaid Cards Market
Payments
United States POS Terminals Market
Payments
Direct Carrier Billing Platform Market
Payments
India Gift Card and Incentive Card Market
Payments
Global Accounts Payable Automation Market
Payments
Europe POS Terminal Market
Payments
Singapore Payments Market
Payments
Cloud Billing Market
Payments
United Kingdom Mobile Payments Market
Payments
Japan Virtual Cards Market
Payments
Brazil POS Terminal Market
Payments
India Payments Market