
 India Payments Market | 2026-2036
India Payments Market Size, Share, and Industry Trends Forecast 2026-2036
India Payments Market Outlook
RBI's digital payment security framework is consolidating compliance obligations across the ecosystem. PhonePe Private Limited leverages its UPI-first architecture to sustain merchant acquisition momentum in tier-2 and tier-3 cities. One 97 Communications Limited anchors consumer wallet engagement through soundbox deployments at physical retail counters. Razorpay Software Private Limited dominates the SME banking-API segment with integrated payout and payroll modules.
India Payments encompasses the infrastructure, protocols, and service layers enabling fund transfers between consumers, businesses, and government entities through electronic rails, with UPI processing transactions via NPCI's real-time settlement switch operating on ISO 20022 messaging standards. The market serves commercial purposes spanning retail commerce, bill settlement, salary disbursement, and cross-border remittance execution. UPI Transactions command the highest volume velocity among transaction type segments, while Merchant Services within the service model dimension captures disproportionate margin pools as SaaS-enabled value-added features attach to core payment processing. E-commerce Platforms represent the fastest-expanding customer segment as platform-native checkout experiences embed financial services deeper into purchase journeys.
RBI, NPCI, and SEBI collectively govern licensing, interoperability mandates, and payment aggregator capital requirements that determine market access thresholds and operational continuity standards for participants. BIS specifications for data localization and tokenization shape product architecture decisions for domestic versus offshore infrastructure deployment. Stakeholders must monitor how the central bank's incremental tightening of KYC norms and merchant onboarding diligence affects customer acquisition economics and platform scalability trajectories.
Market Dynamics
UPI's real-time settlement architecture is compressing transaction latency to near-zero while NPCI's interoperability mandates force incumbents to open their rails to third-party aggregators, fundamentally restructuring merchant acquisition economics across India's payment stack.
Growth Catalysts
- RBI's Digital Payment Security Framework:Consolidated compliance obligations reduce fragmentation costs for new entrants entering merchant services.
- Kirana store digitization:Micro-retailers in tier-2 and tier-3 cities adopt soundbox-enabled QR acceptance, expanding addressable merchant base.
- ISO 20022 messaging standards:Standardized data formats enable richer transaction analytics and embedded credit underwriting at checkout.
Market Restraints
- Merchant Discount Rate compression:UPI's zero-MDR regime for peer-to-merchant transactions squeezes revenue pools for payment aggregators processing low-ticket commerce.
- Data localization requirements:BIS specifications mandate domestic server infrastructure, raising capital deployment thresholds for foreign platform operators.
- Feature phone dependency:USSD fallback rails for non-smartphone users impose higher per-transction technical costs than app-based protocols.
Strategic Opportunities
- Cross-border remittance corridors:UPI-PayNow linkages with Singapore and UAE create real-time settlement rails for diaspora flows.
- Account Aggregator framework:RBI-licensed AA entities enable consent-based financial data sharing, unlocking embedded lending at merchant checkout.
- SaaS-enabled value-added services:Integrated payout, payroll, and inventory modules attach to core processing, capturing disproportionate margin pools in SME banking.
Industry Challenges
- KYC norm tightening:RBI's incremental merchant onboarding diligence extends verification timelines and raises customer acquisition costs for platform scaling.
- Soundbox hardware supply constraints:Semiconductor shortages and logistics bottlenecks delay deployment schedules for physical retail counter devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Payments Market |
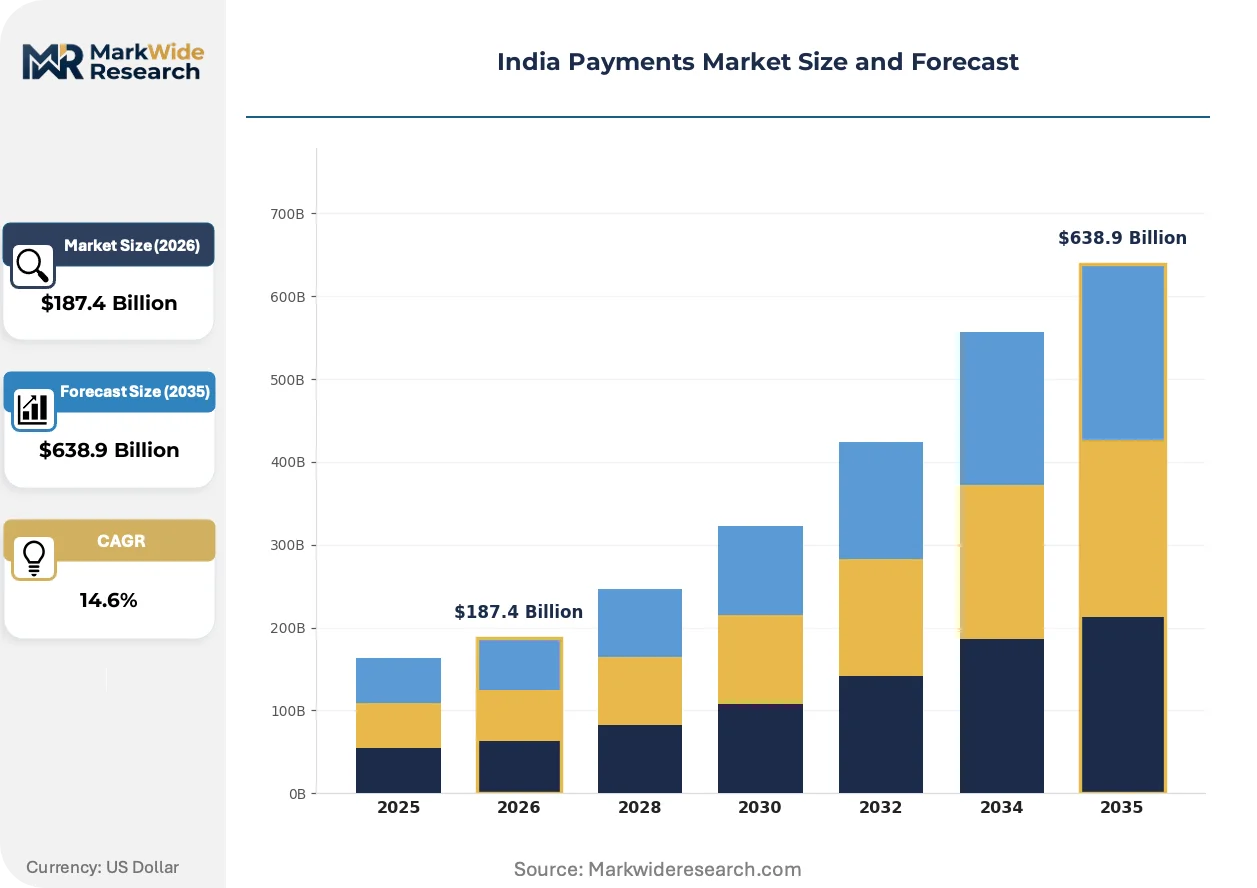
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Online Payments, Mobile Wallets, UPI Transactions, Credit/Debit Cards Customer Segment: Retail Customers, SMEs, Corporates, E-commerce Platforms Payment Method: Contactless, QR Code, Bank Transfers, Cash Service Model: Peer-to-Peer, Merchant Services, Payment Aggregators, Remittances |
| Companies Covered | PhonePe Private Limited, One 97 Communications Limited, Razorpay Software Private Limited, PayU Payments Private Limited, Google Pay, BharatPe, IndiaIdeas.com Limited, Infibeam Avenues Limited, Pine Labs Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Payments Market Strategic Shifts
India's payment infrastructure is undergoing protocol-level transformation as real-time rails subsume batch-based settlement, regulatory architecture consolidates fragmented oversight, and merchant-facing hardware proliferates beyond smartphones into dedicated audio-visual confirmation devices.
Soundbox devices are expanding into physical retail counters as dedicated audio confirmation hardware for UPI transactions. Kirana stores and micro-merchants in Maharashtra and Karnataka deploy these battery-powered units to verify payment receipt without smartphone dependency. The technology is expanding into tier-3 towns where merchant trust barriers require audible transaction confirmation rather than screen-based verification.
RBI's incremental tightening of KYC norms and merchant onboarding diligence is reshaping platform operational workflows. Payment aggregators must now maintain enhanced documentation standards and physical verification protocols for high-risk merchant categories. SME-focused fintechs in Delhi NCR are responding by building dedicated field verification teams and API-integrated document validation layers.
Platform-native checkout experiences are embedding financial services deeper into purchase journeys across e-commerce marketplaces. Consumers encounter buy-now-pay-later options, insurance micro-products, and loyalty-linked credit at the point of transaction rather than through separate banking interfaces. This convergence is most visible in Karnataka's Bangalore cluster where marketplace operators and fintechs co-locate engineering talent.
India Payments Market Segmentation
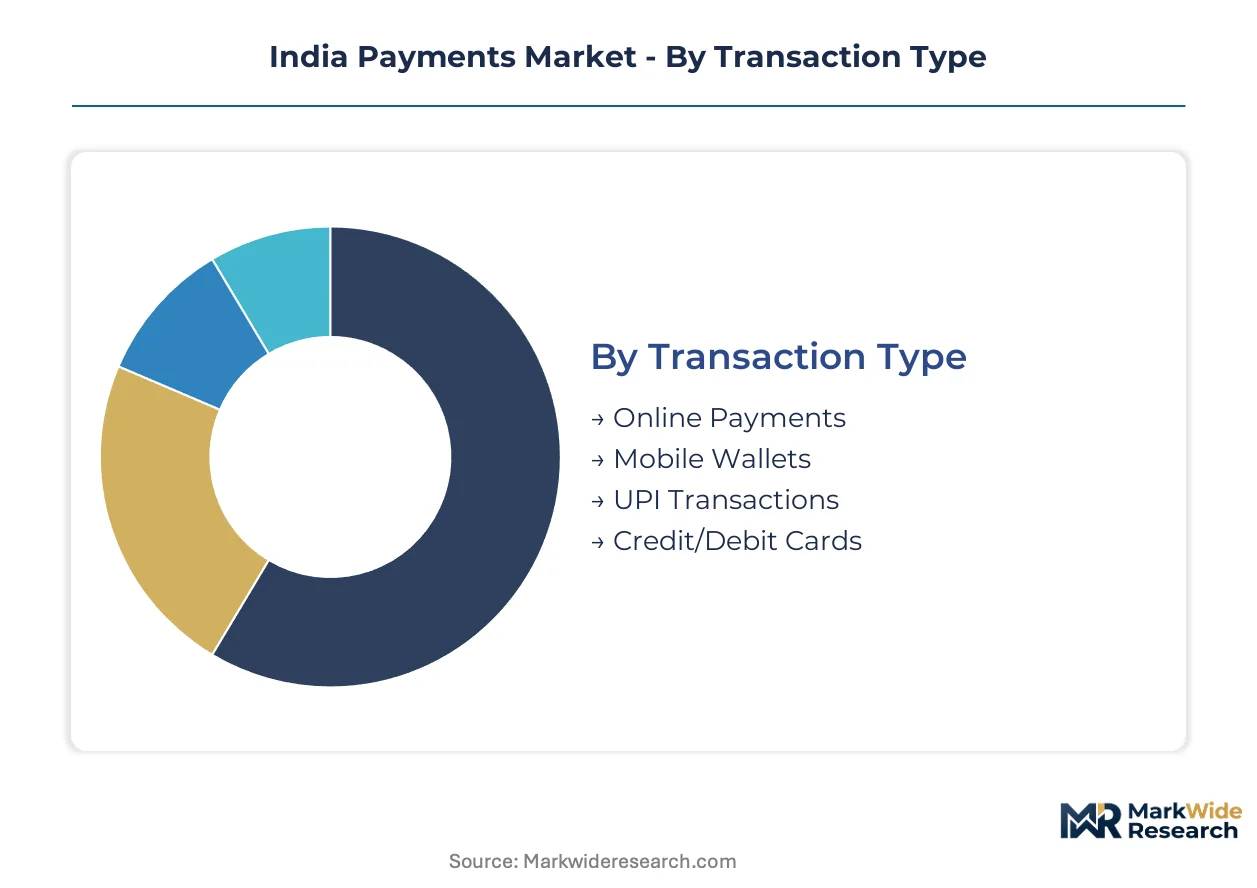
India's payments landscape fragments across transaction protocols, customer sophistication tiers, and service delivery architectures. Each segmentation dimension captures distinct margin structures and regulatory exposure profiles that shape platform strategy.
Transaction Type:
Velocity and settlement architecture differentiate transaction protocols across India's payment stack.
- UPI Transactions:Real-time settlement rails operating on NPCI's ISO 20022 messaging infrastructure process the highest volume velocity. Demand concentrates in Maharashtra and Karnataka where merchant density and fintech engineering clusters overlap, with zero-MDR policy compressing aggregator margins while expanding addressable base.
- Mobile Wallets:Stored-value instruments with pre-funded balances enable closed-loop merchant ecosystems and loyalty integration. Soundbox-enabled physical retail counters in Delhi NCR drive wallet engagement through audio confirmation hardware that bridges trust barriers among micro-merchants.
- Online Payments:Gateway-mediated card and net-banking transactions for e-commerce checkout.
- Credit/Debit Cards:Card-present and card-not-present rails with interchange fee structures.
Volume sits with UPI Transactions; growth tilts toward Mobile Wallets.
Customer Segment:
Digital maturity and transaction scale determine service configuration requirements across buyer tiers.
- E-commerce Platforms:Marketplace operators embedding native checkout with embedded credit and insurance micro-products. Bangalore's engineering talent concentration accelerates platform-native financial service integration, with RBI's Account Aggregator framework enabling consent-based data sharing for underwriting at purchase.
- SMEs:Micro-retailers and small enterprises requiring integrated payout, payroll, and inventory modules. Tier-2 and tier-3 city kirana stores in Karnataka adopt QR-enabled acceptance with SaaS-attached value-added services capturing disproportionate margin pools.
- Retail Customers:Individual consumers accessing P2P transfers and merchant payments through smartphone interfaces.
- Corporates:Large enterprises with treasury management and bulk disbursement requirements.
Revenue concentration favors SMEs; steepest expansion trajectory belongs to E-commerce Platforms.
Payment Method:
Hardware dependency and authentication protocols shape deployment economics across acceptance modes.
- QR Code:Static and dynamic quick-response codes enabling smartphone-mediated merchant acceptance. Maharashtra's micro-retail density drives deployment, with RBI's merchant onboarding diligence extending verification timelines for high-risk categories.
- Contactless:NFC-enabled tap-to-pay protocols for card and device proximity transactions.
- Bank Transfers:Account-to-account rails including NEFT, RTGS, and IMPS batch or real-time settlement.
- Cash:Physical currency remaining prevalent in tier-3 towns with feature phone dependency.
Deployment scale favors QR Code; technology transition accelerates for Contactless.
Service Model:
Value chain position and regulatory capital requirements distinguish competitive economics across service layers.
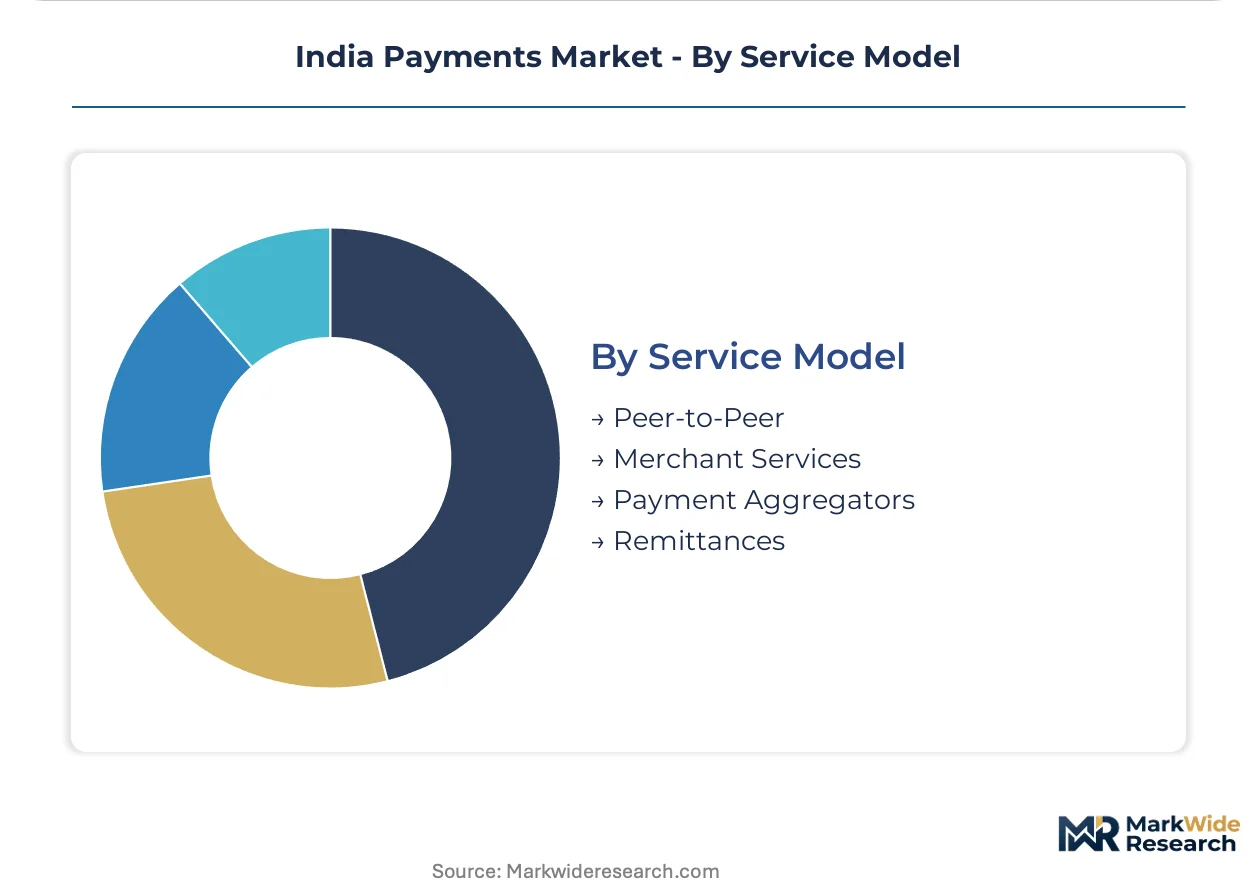
- Merchant Services:SaaS-enabled payment acceptance with attached inventory, payroll, and credit modules. Delhi NCR fintech clusters dominate SME banking-API segments, with BIS data localization mandates raising infrastructure deployment thresholds for foreign operators.
- Payment Aggregators:Licensed entities consolidating multiple payment instruments under single integration. RBI's capital requirements and interoperability mandates force rail openness to third-party providers, restructuring acquisition economics.
- Peer-to-Peer:Individual fund transfers between consumer accounts.
- Remittances:Cross-border flows including UPI-PayNow linkages with Singapore and UAE.
Margin capture concentrates in Merchant Services; regulatory expansion targets Payment Aggregators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's payments infrastructure consumption concentrates in western and southern states where merchant density overlaps with fintech engineering clusters, while regulatory production of standards emanates from Mumbai and Delhi NCR.
Maharashtra
Mumbai anchors merchant acquisition velocity and NPCI's operational headquarters. RBI's digital payment security framework mandates consolidated compliance obligations for payment aggregators operating in the state. Pune's engineering corridor hosts soundbox manufacturing facilities serving kirana store digitization across tier-2 towns.
Karnataka
Bangalore's fintech cluster drives platform-native checkout innovation and UPI transaction protocol development. BIS data localization specifications shape domestic server infrastructure deployment decisions for operators in the state. Mysore and Hubli-Dharwad corridors witness expanding QR code acceptance among micro-retailers.
Delhi NCR
The National Capital Region concentrates SME banking-API development and merchant service module integration. RBI's incremental KYC norm tightening extends verification timelines for payment aggregators onboarding high-risk merchant categories. Gurgaon's technology parks house dedicated field verification teams for physical documentation protocols.
Gujarat
Surat and Ahmedabad textile clusters generate concentrated demand for integrated payout and payroll modules among SME exporters. The central bank's payment aggregator capital requirements determine market access thresholds for new entrants in the state. Vadodara's emerging fintech presence targets merchant services for manufacturing supply chains.
Telangana
Hyderabad's IT corridor attracts payment technology R&D investments and blockchain-based settlement pilots. SEBI's oversight of payment-linked investment products intersects with RBI's licensing framework for fintech operators in the state. Warangal and Nizamabad districts see expanding UPI penetration among agricultural procurement networks.
India Payments Market Competitive Environment
The competitive structure tilts toward UPI-first aggregators with merchant-facing hardware deployment capabilities. Market concentration remains moderate with three to five dominant players controlling transaction volume velocity while dozens of regional specialists capture niche SME segments. Strategic archetypes include soundbox-enabled physical retail acquirers, API-integrated banking service providers, and cross-border remittance corridor operators. Dominant competitive moves encompass merchant acquisition network expansion and SaaS-attached value-added service bundling.
Among UPI-native acquirers, PhonePe Private Limited and One 97 Communications Limited occupy positions exemplifying the soundbox-enabled physical retail archetype, while Razorpay Software Private Limited represents the SME banking-API integration tier. These entities anchor distinct competitive vectors without overlapping core service configurations, reflecting regulatory-mandated interoperability that forces rail openness across the ecosystem.
| Leading Market Players |
|---|
| PhonePe Private Limited |
| One 97 Communications Limited |
| Razorpay Software Private Limited |
| PayU Payments Private Limited |
| Google Pay |
| BharatPe |
| IndiaIdeas.com Limited |
| Infibeam Avenues Limited |
| Pine Labs Private Limited |
| Others |
Value Chain & Pricing Dynamics
SME banking-API demand concentration in Delhi NCR and Bangalore anchors tiered SaaS subscription models, with merchant acquirers bundling soundbox hardware into per-terminal fee structures that compress headline processing rates.
Pricing Analysis
Margin tightening in merchant services reflects UPI's zero-MDR regime squeezing transaction revenue pools, forcing aggregators toward value-added service attachment. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and data analytics depth. Price differentiation traces to ISO 20022 compliance tier and embedded credit underwriting capability. Tier-2 kirana stores exhibit highest price sensitivity; enterprise marketplace operators absorb premium SaaS tiers for unified treasury control.
Supply Chain Analysis
Semiconductor supply for soundbox audio-visual confirmation hardware rests on Taiwan and South Korea specialty foundries, with battery cell production drawing from China and domestic India assembly. RBI's data localization mandates and BIS tokenization specifications create regulatory chokepoints for foreign platform operators. Distribution runs through NPCI-certified payment aggregator networks with direct field deployment teams for physical merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soundbox manufacturing capacity constraints prop merchant acquisition pricing power, with semiconductor lead times extending hardware deployment schedules and preserving incumbent field network advantages.
For Market Incumbents: Anchor merchant stickiness through proprietary soundbox-integrated SaaS modules spanning inventory and payroll, countering Razorpay's SME banking-API encroachment. Deepen upstream control over field verification teams to absorb RBI's KYC tightening cost inflation. Prioritize ISO 20022 analytics investment for embedded credit underwriting differentiation. For New Entrants and Emerging Players: Tier-3 town kirana digitization presents the most penetrable white-space corridor, with trust-barrier audio confirmation requirements unmet by smartphone-dependent solutions. Partner with domestic semiconductor distributors to bypass soundbox hardware supply constraints. Lead with vernacular-language merchant onboarding interfaces to outflank incumbent app-centric workflows. For Investors and Strategic Acquirers: The window for entry favors Account Aggregator-licensed entities with consent-architecture IP and embedded lending pipelines. Long-term viability hinges on UPI protocol governance participation and NPCI interoperability mandate navigation. Watch RBI's incremental merchant onboarding diligence intensity as inflection signal for customer acquisition cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Soundbox Hardware Scale-Up | Domestic manufacturing expansion addresses semiconductor supply constraints for tier-3 merchant penetration. |
| Account Aggregator Licensing | RBI consent-framework authorization unlocks embedded credit underwriting at merchant checkout points. |
| ISO 20022 Analytics Investment | Rich transaction data formats enable real-time risk scoring for SME lending products. |
| Cross-Border Corridor Activation | UPI-PayNow linkages with Singapore and UAE capture diaspora remittance flows. |
| Field Verification Network Buildout | Dedicated physical documentation teams absorb RBI's KYC norm tightening cost pressures. |
Study Parameters
Document review covered NPCI annual reports, RBI circulars on payment aggregator licensing, and BIS data localization specifications, complemented by interviews with payment platform CTOs, merchant acquisition heads at tier-2 fintechs, soundbox hardware procurement managers, and SME banking product directors. Secondary validation drew from SEBI filings, NPCI transaction volume disclosures, and customs import data for semiconductor components. Bottom-up merchant deployment estimates and top-down addressable market sizing were triangulated against regulatory filing aggregates.
Revenue and transaction volume outputs were generated through segmented modeling across transaction protocol, customer sophistication tier, service delivery architecture, and regional infrastructure density dimensions. CAGRs were derived from historical UPI adoption velocity and merchant digitization penetration curves. Forecast inputs incorporated RBI policy trajectory assumptions and NPCI interoperability mandate implementation schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory MDR policy reversals and geopolitical disruptions to semiconductor supply chains. Forecasts reflect documented assumptions on merchant onboarding cost trajectories and soundbox deployment velocity. A small set of named triggers warrants ongoing watch: RBI's KYC norm tightening intensity, NPCI's real-time settlement architecture evolution, and Account Aggregator framework adoption rates among lending partners.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America POS Terminal Market
Payments
Spain Payments Market
Payments
Europe Real Time Payments Market
Payments
Italy Payments Market
Payments
Luxembourg POS Terminals Market
Payments
Denmark Payments Market
Payments
Instant Payments Market
Payments
Online Charging System (OCS) Market
Payments
Mobile Payment Data Protection Market
Payments
Retail POS Terminals Market
Payments
Digital Remittance Service Market
Payments
Cloud Billing Market
Payments
Europe POS Terminal Market
Payments
Slovakia POS Terminal Market
Payments
South Korea Payments Market
Payments
North America Mobile Payments Market