
 Digital Currency Wallet Market | 2026-2036
Digital Currency Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Currency Wallet Market Insights
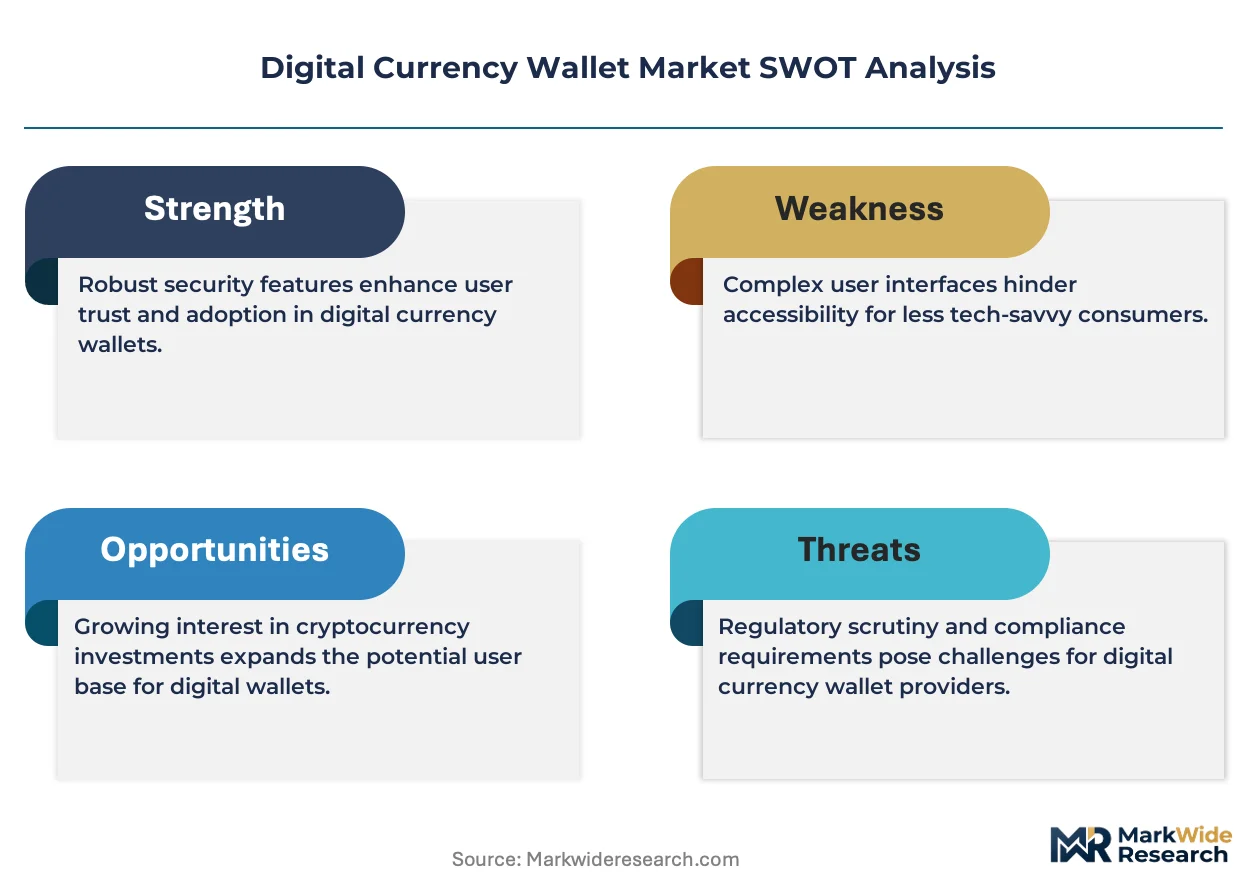
MiCA is repositioning the European competitive landscape by mandating capital reserves and operational transparency for custodial wallet providers. Ledger SAS anchors its hardware dominance through secure element chip architecture and direct-to-consumer channel control. Coinbase leverages its exchange-integrated wallet ecosystem to sustain user retention across trading and staking functions. Binance competes through multi-chain support and reduced fee structures for native token holders.
A digital currency wallet constitutes software or hardware that generates and stores cryptographic key pairs—comprising a public address for receiving assets and a private key for transaction authorization—typically employing elliptic curve cryptography with 256-bit entropy standards. These systems execute blockchain transaction signing locally, enabling peer-to-peer value transfer without intermediary settlement. Hardware wallet configurations command premium pricing due to air-gapped security architectures and tamper-resistant silicon, while mobile deployments capture volume through biometric verification integration and near-field communication payment rails. Individual traders represent the deepest user category, though payment processors are concentrating fastest as merchant onboarding tools proliferate.
The SEC enforces securities law compliance for wallets offering yield-bearing products, while the EU AI Act imposes algorithmic transparency requirements on automated transaction monitoring systems. The F-Gas Regulation indirectly shapes hardware wallet manufacturing through restrictions on cooling agents used in semiconductor foundries. Stakeholders must monitor how jurisdictional licensing fragmentation affects cross-border key custody and recovery service architectures.
Market Dynamics
MiCA implementation in Europe is forcing custodial wallet providers to restructure capital reserves and operational transparency, while hardware manufacturers face semiconductor supply constraints from F-Gas Regulation cooling agent restrictions.
Growth Catalysts
- MiCA Framework Mandate:Europe's unified licensing regime reduces jurisdictional fragmentation for wallet providers operating across EU member states, lowering compliance overhead.
- Merchant Payment Rails:Retail processors in Southeast Asia are deploying mobile-first wallet integrations for street-level commerce, accelerating consumer onboarding velocity.
- Hardware Security Modules:Secure element chip architectures with tamper-resistant silicon are penetrating high-net-worth individual segments seeking air-gapped key custody.
Market Restraints
- Semiconductor Foundry Concentration:Taiwan and South Korea dominate secure element production, creating single-source vulnerability for hardware wallet manufacturers.
- SEC Securities Enforcement:Yield-bearing wallet products face classification uncertainty under US securities law, freezing product development pipelines.
- Biometric Sensor Cost Structure:Fingerprint and facial recognition modules add 15-25% to mobile wallet bill-of-materials, compressing margin at economy price tiers.
Strategic Opportunities
- Nigeria Cashless Policy:Central bank digital currency rollout and withdrawal limits are concentrating demand for mobile-first, offline-capable wallet architectures.
- Multi-Chain Convergence:Wallet platforms integrating Bitcoin, Ethereum, and Solana key management through unified interfaces are capturing power-user migration from single-chain tools.
- Staking-as-a-Service:Non-custodial wallets with native validator delegation interfaces are displacing exchange-based staking for sophisticated holders seeking self-custody.
Industry Challenges
- Elliptic Curve Cryptography Talent Scarcity:Firmware engineers with 256-bit entropy implementation expertise command premium compensation, constraining R&D velocity at mid-size providers.
- Cross-Border Recovery Architecture:Jurisdictional licensing fragmentation complicates key custody and social recovery service deployment across operating regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Currency Wallet Market |
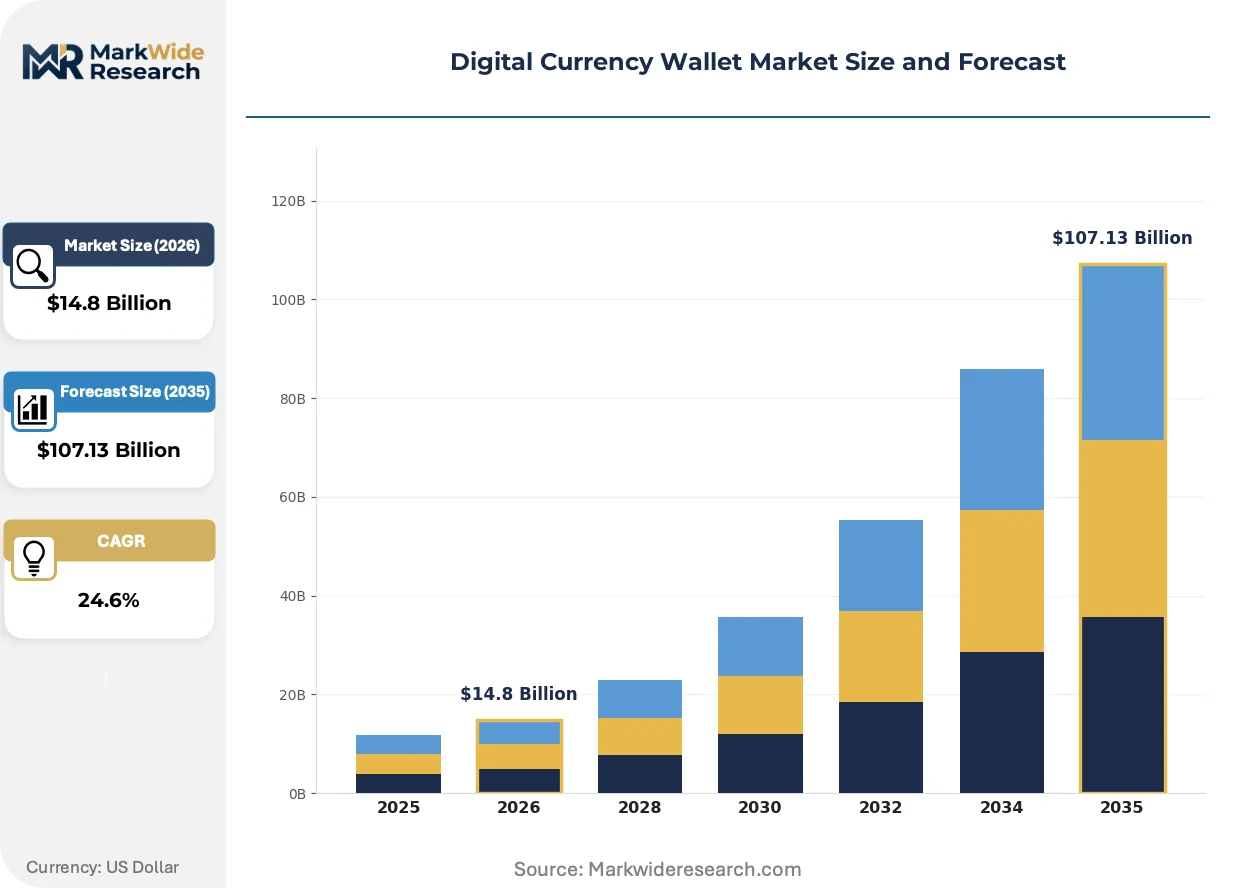
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Wallet Type: Hardware, Software, Web-Based, Mobile, Paper Security Feature: Two-Factor Authentication, Biometric Verification, Multi-Signature, Encryption, PIN Code User Category: Individual Traders, Startups, SMEs, Payment Processors, Cryptocurrency Exchanges Supported Currency: Bitcoin, Ethereum, Ripple, Litecoin, Stablecoins |
| Companies Covered | Coinbase, Binance, Ledger SAS, Trezor, PayPal, Exodus Movement, Inc., BitGo Holdings, Inc., Crypto.com, Alipay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Currency Wallet Market Trends and Innovations
Biometric authentication modules and programmable smart contract interfaces are compressing the functional gap between custodial exchanges and self-custody tools, reshaping user acquisition economics.
Account abstraction standards are expanding into mainstream wallet deployments, enabling social recovery, multi-signature authorization, and gasless transaction sponsorship without seed phrase management. Retail users in Southeast Asia and Latin America are adopting these interfaces fastest, bypassing traditional onboarding friction. This architecture is compressing support costs while expanding addressable market into non-technical demographics previously excluded by key management complexity.
Europe's F-Gas Regulation restricts hydrofluorocarbon use in semiconductor foundry cooling systems, indirectly constraining secure element chip supply for hardware wallet manufacturers. German and French foundries are retooling thermal management infrastructure, extending lead times for tamper-resistant silicon modules. Hardware providers are responding with dual-sourcing strategies and inventory pre-positioning ahead of phased cooling agent phase-outs.
Payment processors are unbundling wallet infrastructure from merchant acquiring services, enabling independent software vendors to embed white-label custody and settlement. Southeast Asian fintech platforms are displacing traditional bank-integrated point-of-sale systems with direct crypto-to-fiat conversion rails. This channel shift is most visible in Indonesia and Vietnam, where regulatory sandboxes permit limited commercial deployment ahead of formal licensing frameworks.
Digital Currency Wallet Market Segmentation
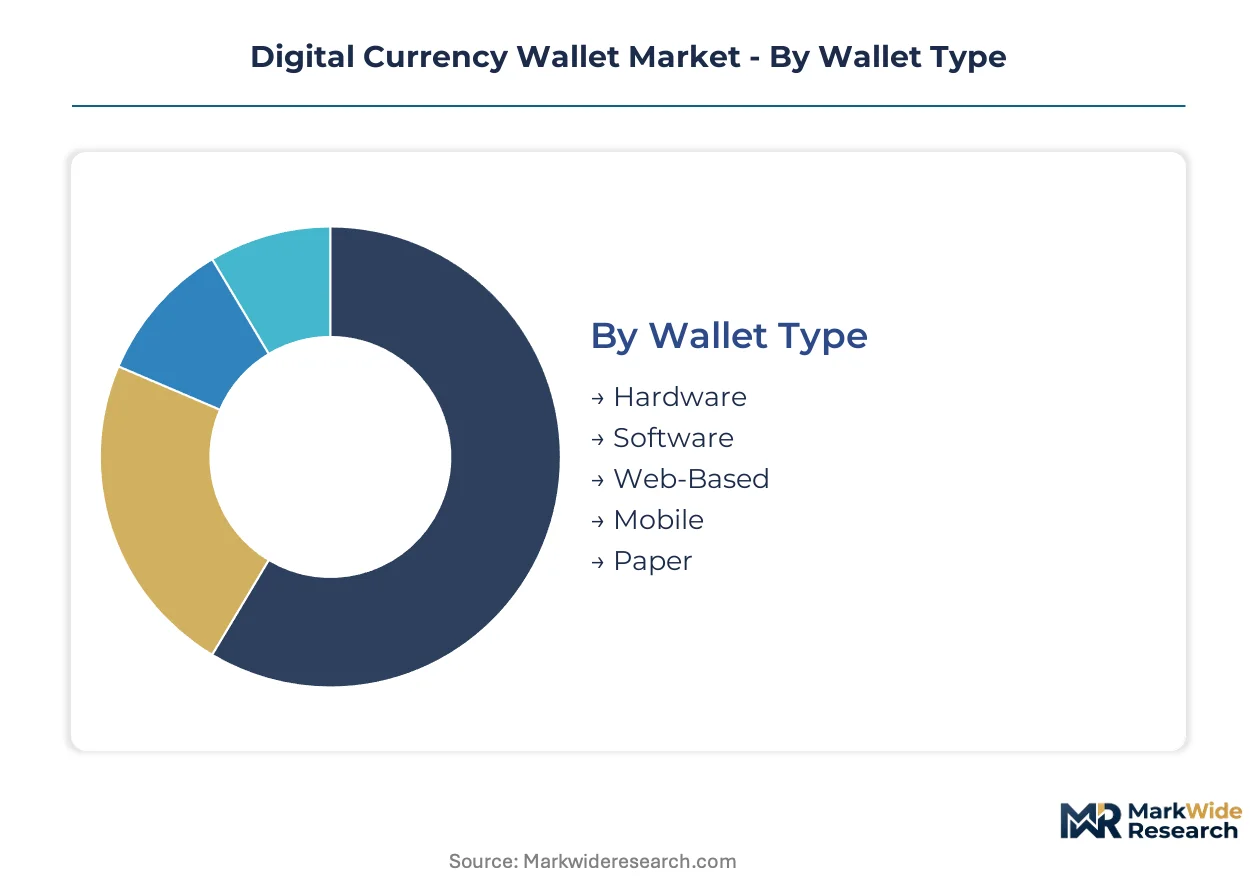
Wallet architectures fragment across custody models, security layers, and currency support matrices. Each dimension carries distinct margin profiles and regulatory exposure. The analysis maps four structural categories governing procurement decisions and vendor positioning.
Wallet Type:
Integration depth varies sharply—standalone hardware devices operate air-gapped from networked systems, while software deployments embed directly into exchange and merchant platforms.
- Hardware:Secure element chips with tamper-resistant silicon isolate private keys from internet-connected attack surfaces. High-net-worth holders in Germany and Singapore concentrate demand here, driven by institutional custody mandates and personal asset protection requirements.
- Software:Desktop and browser-native applications manage keys within host operating system environments. Individual traders across Southeast Asia favor these tools for multi-chain portfolio aggregation, though malware exposure constrains enterprise adoption.
- Web-Based:Cloud-hosted key management through browser interfaces sacrifices self-custody for convenience. Custodial providers embed these wallets into exchange dashboards, capturing onboarding velocity from first-time cryptocurrency users.
- Mobile:Smartphone-native architectures leverage biometric sensors and NFC payment rails for street-level commerce. Nigeria's eNaira rollout and Indonesia's merchant processor integrations are concentrating mobile-first deployment.
- Paper:Physical key pair storage through QR code printing offers cold storage without electronic components. Long-term holders seeking inheritance planning and disaster recovery maintain niche demand for this zero-tech format.
Mobile wallets lead volumes today; hardware configurations are gaining share fastest among regulated institutional segments.
Security Feature:
Cost tiering separates premium biometric modules from baseline PIN architectures, with compliance mandates in Europe and the US forcing upward feature adoption.
- Two-Factor Authentication:SMS and authenticator-app secondary verification layers add friction without specialized hardware. Regulatory guidance from the SEC and EU cybersecurity frameworks mandate 2FA for custodial services above threshold asset values.
- Biometric Verification:Fingerprint and facial recognition modules embed into mobile and hardware form factors. Samsung and Apple secure enclave integrations are driving premium tier adoption, though sensor costs compress margins at economy price points.
- Multi-Signature:Threshold signature schemes requiring M-of-N key holder authorization enable corporate treasury controls and escrow workflows. Enterprise procurement in Switzerland and Liechtenstein favors these architectures for board-governed digital asset policies.
- Encryption:AES-256 and ChaCha20 cipher implementations protect key material at rest and in transit. Open-source library audits and formal verification processes differentiate vendor offerings in security-conscious segments.
- PIN Code:Numeric entry barriers provide baseline access control without hardware dependencies. Emerging market deployments prioritize this layer for feature phone compatibility and minimal bill-of-materials overhead.
PIN and encryption dominate installed base; biometric verification is climbing the fastest as sensor costs decline and EU AI Act transparency requirements reshape authentication procurement.
User Category:
Application intensity separates trading-focused individual users from infrastructure-dependent payment processors, with diverging support and compliance requirements.
- Individual Traders:Retail holders executing spot trades and self-custody operations represent the deepest volume pool. Advanced users migrate toward non-custodial tools with native staking interfaces, displacing exchange-integrated alternatives.
- Startups:Early-stage ventures require lightweight custody without enterprise compliance overhead. Venture-backed teams in Singapore and Dubai favor multi-signature software wallets with team-based access controls.
- SMEs:Small and medium enterprises adopt white-label wallet infrastructure for customer reward programs and cross-border settlement. Latin American import-export businesses leverage stablecoin rails to bypass correspondent banking delays.
- Payment Processors:Merchant acquiring services embed wallet functionality for crypto-to-fiat conversion at point-of-sale. Indonesian and Vietnamese fintech platforms are unbundling this infrastructure from traditional banking relationships.
- Cryptocurrency Exchanges:Trading venues integrate proprietary wallets for user asset aggregation and liquidity management. MiCA licensing in Europe is forcing operational separation between exchange and custody functions.
Individual traders anchor volume today; payment processors are expanding most quickly as merchant onboarding tools proliferate across Southeast Asian markets.
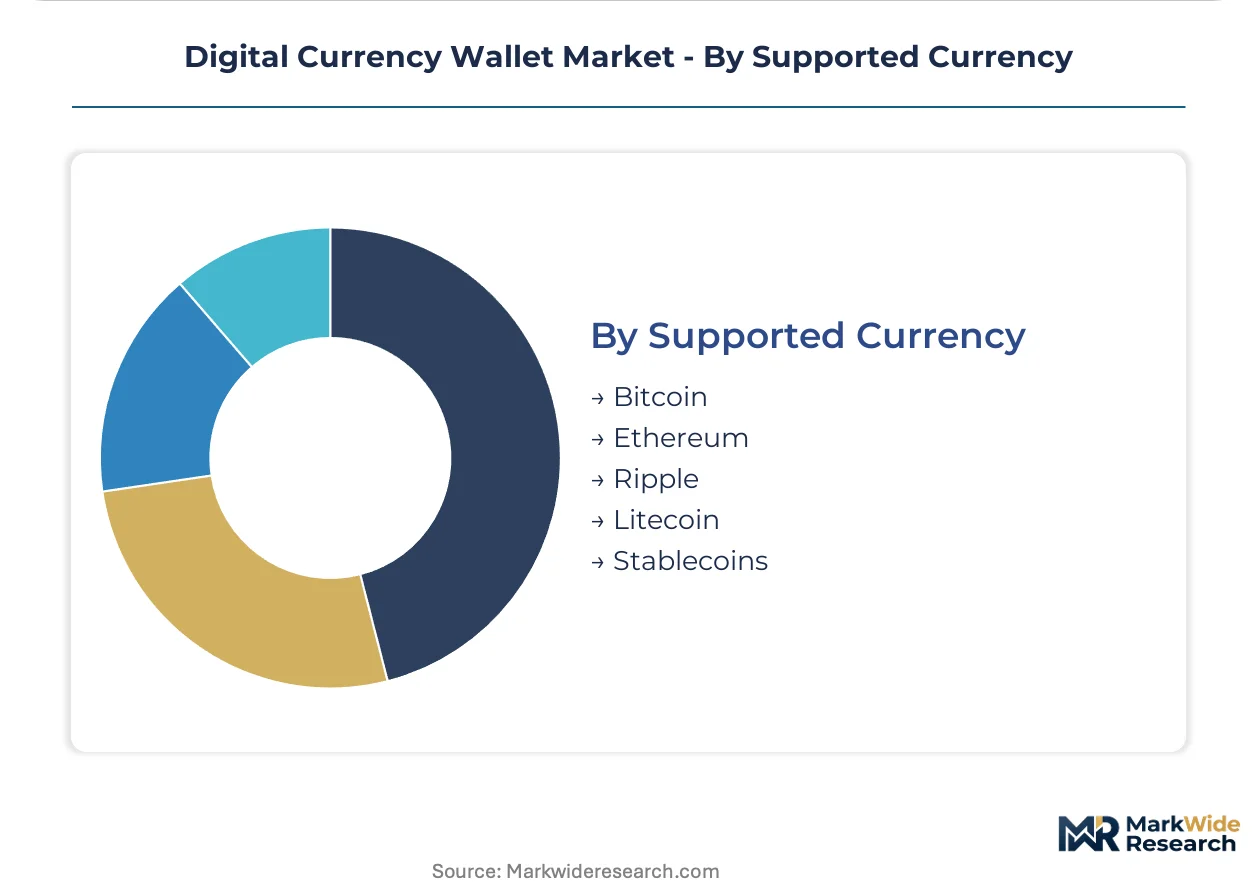
Supported Currency:
Network maturity and regulatory clarity determine which blockchain assets wallet providers prioritize for native integration.
- Bitcoin:Original cryptocurrency with established custody standards and institutional acceptance. Hardware wallet manufacturers optimize secure element firmware specifically for Bitcoin's ECDSA signature scheme.
- Ethereum:Smart contract platform enabling DeFi integrations and account abstraction standards. Wallet providers race to support ERC-4337 implementations for gasless transactions and social recovery.
- Ripple:Payment-focused ledger targeting correspondent banking replacement. Regulatory uncertainty surrounding XRP securities classification constrains US wallet integration efforts.
- Litecoin:Bitcoin derivative with faster block confirmation times. Merchant payment processors in emerging markets maintain support for this established alternative despite declining developer activity.
- Stablecoins:Fiat-pegged tokens dominate transaction volume for remittance and commerce applications. Circle's USDC and Tether's USDT integration is now mandatory for payment-focused wallet architectures.
Bitcoin and Ethereum lead addressable coverage; stablecoins are gaining share fastest as merchant payment rails displace speculative holding as the primary wallet use case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blockchain engineering talent concentrates in Singapore, Zurich, and San Francisco, anchoring wallet innovation clusters. Regulatory arbitrage between jurisdictions is accelerating regional specialization. Merchant payment rails are expanding fastest where central bank digital currencies intersect with mobile-first economies.
United States
Institutional custody demand from hedge funds and family offices drives hardware wallet adoption. The SEC enforces securities law compliance for yield-bearing wallet products, freezing certain development pipelines. San Francisco and New York host the deepest concentrations of cryptographic engineering talent.
Germany
High-net-worth individuals prioritize air-gapped security architectures for personal asset protection. The F-Gas Regulation restricts cooling agents in semiconductor foundries, extending secure element chip lead times. Munich and Berlin anchor hardware wallet R&D clusters with strong ties to industrial cybersecurity.
Singapore
Venture-backed fintech startups require multi-signature software wallets with team-based access controls. The Monetary Authority of Singapore licenses payment institutions under clear digital asset frameworks. The city-state's engineering pool supports white-label wallet infrastructure for Southeast Asian expansion.
Nigeria
Mobile-first wallet demand concentrates around the eNaira rollout and central bank cashless policies. Withdrawal limits and currency instability push street-level commerce toward offline-capable architectures. Lagos anchors fintech development clusters serving West African remittance corridors.
Indonesia
Merchant processors deploy crypto-to-fiat conversion rails for street-level commerce acceleration. Regulatory sandboxes permit limited commercial deployment ahead of formal licensing frameworks. Jakarta and Bali host payment infrastructure startups unbundling wallet services from traditional banking.
Digital Currency Wallet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across custody model boundaries. The vendor base stratifies into three tiers: exchange-integrated platforms with captive user bases, hardware manufacturers with secure element chip control, and white-label infrastructure providers serving merchant processors. Strategic moves concentrate on account abstraction integration and multi-chain key management unification.
Among exchange-integrated platforms, Coinbase and Binance occupy positions defined by trading ecosystem retention. Ledger SAS anchors the hardware security tier through direct-to-consumer channel control. These three exemplify divergent archetypes: exchange-captive distribution, silicon-level security specialization, and hybrid service unification.
| Leading Market Players |
|---|
| Coinbase |
| Binance |
| Ledger SAS |
| Trezor |
| PayPal |
| Exodus Movement, Inc. |
| BitGo Holdings, Inc. |
| Crypto.com |
| Alipay |
| Others |
Pricing and Supply Chain Analysis
Europe's F-Gas Regulation gates qualified supply of tamper-resistant secure element chips while simultaneously constraining premium-tier pricing access for hardware wallet manufacturers seeking German and French foundry partnerships. This environmental mandate extends lead times for cooling-agent-compliant semiconductor production, concentrating pricing power among dual-sourced vendors and compressing margins for single-source dependent providers.
Pricing Analysis
Bundled custody-and-exchange services command subscription premiums from retail users seeking seamless trading integration, while unbundled self-custody tools compete on transaction-fee minimization. Pricing stratifies across premium hardware with secure element architectures, standard software with biometric modules, and economy mobile deployments with PIN-only verification. Cost compression in the economy tier stems from 15-25% biometric sensor bill-of-materials overhead. Payment processors exhibit highest price sensitivity due to thin merchant-acquiring margins, while high-net-worth individuals in Germany and Singapore absorb premium hardware pricing for air-gapped security assurance.
Supply Chain Analysis
Elliptic curve cryptography firmware engineers with 256-bit entropy implementation expertise are scarce in Taiwan and South Korea, constraining secure element production velocity for hardware wallet manufacturers. Semiconductor foundry capacity draws from Taiwan Semiconductor Manufacturing, Samsung Foundry, and GlobalFoundries, with specialized tamper-resistant silicon requiring dedicated process nodes. Single-source vulnerability in secure element design creates exposure to geopolitical disruption or environmental regulation phase-outs. Distribution runs through direct-to-consumer channels for hardware specialists and white-label API integrations for merchant processor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with Europe's MiCA framework implementation mandating capital reserves and operational transparency that concentrates demand among compliant custodial providers.
For Market Incumbents: To counter exchange-integrated wallet erosion from non-custodial staking-as-a-service alternatives, incumbents should deepen backward integration into secure element chip supply through foundry partnerships in Germany and France, while accelerating account abstraction standard adoption to compress onboarding friction against software-native competitors. For New Entrants and Emerging Players: Capture white-space in Nigeria's mobile-first, offline-capable wallet architectures driven by eNaira rollout and central bank cashless policies, targeting street-level commerce merchants with lightweight NFC-enabled deployments and local language interfaces bypassing incumbent exchange complexity. For Investors and Strategic Acquirers: Roll-up economics work for white-label infrastructure specialists because payment processor unbundling from traditional banking in Indonesia and Vietnam creates fragmented demand for embeddable custody solutions. Long-term viability hinges on multi-chain key management unification capabilities. Watch MiCA licensing completion rates as inflection indicator for European consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Account Abstraction Integration | ERC-4337 implementation enables social recovery and gasless transactions for non-technical users in Southeast Asia. |
| Secure Element Dual-Sourcing | German and French foundry partnerships mitigate F-Gas Regulation cooling agent phase-out risks for hardware manufacturers. |
| Multi-Chain Key Management Unification | Bitcoin-Ethereum-Solana interfaces capture power-user migration from single-chain tools in Singapore and Dubai. |
| Staking-as-a-Service Interface Development | Native validator delegation displaces exchange-based staking for sophisticated holders seeking self-custody. |
| White-Label Merchant Infrastructure | Indonesian and Vietnamese fintech platforms embed custody and settlement unbundled from traditional banking relationships. |
Research Methodology
Multiple input streams — primary interviews with wallet platform CTOs, exchange custody leads, semiconductor foundry procurement managers, and merchant processor integration specialists; secondary validation through SEC filings, EU MiCA regulatory texts, and central bank digital currency policy documents; plus customs data on secure element chip trade flows — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Historical transaction volume patterns across wallet type, security feature tier, user category, and supported currency matrix were cross-referenced against panel input from cryptographic engineering executives and regulatory compliance officers to construct projection assumptions across the analysis window. CAGRs were derived from segmented adoption curve modeling incorporating merchant payment rail deployment rates, hardware security module penetration in high-net-worth segments, and account abstraction standard implementation velocity.
Regulatory enforcement intensity, semiconductor supply disruption, and central bank digital currency adoption velocity are the dominant revision risks that could materially alter trajectory assumptions. Material deviation in these triggers warrants pause and re-evaluation of competitive positioning and investment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market