
 GCC Mobile Payment Market | 2026-2036
GCC Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Mobile Payment Market Intelligence
Merchant acquiring channels across the GCC are reconfiguring as mobile-first transaction rails displace traditional point-of-sale infrastructure. Mastercard Incorporated leverages its tokenization infrastructure to anchor cross-border remittance flows between Gulf states and South Asia. STC Pay sustains domestic dominance in Saudi Arabia through wallet-based salary disbursements and government benefit distribution. Network International competes aggressively for hospitality and retail merchant portfolios in Dubai and Abu Dhabi.
Mobile payment systems in the GCC encompass digital transaction platforms enabling fund transfers through smartphone applications, typically incorporating NFC contactless protocols, QR code scanning, and cloud-hosted token vaults to authenticate users without exposing primary account numbers. These systems serve commercial purposes by collapsing checkout latency, reducing cash handling costs, and enabling real-time settlement for merchants previously dependent on card-present hardware. Mobile wallet deployment among consumers leads transaction volume, while NFC technology captures premium in-store use cases across luxury retail and quick-service restaurants in Dubai Mall and Riyadh Boulevard corridors. Peer-to-peer transfers represent the fastest-growing transaction type, driven by expatriate worker remittances from the UAE and Qatar to India, Pakistan, and the Philippines.
SAMR and UAE Central Bank digital payment regulations govern licensing, capital reserves, and consumer protection standards for non-bank payment providers operating across the Gulf. PCI-DSS compliance mandates and GDPR-aligned data localization requirements in Bahrain and Qatar shape how Checkout.com and Stripe architect their regional data centers and encryption protocols. Stakeholders must monitor evolving open banking API standards and central bank digital currency pilot programs that could recast interoperability obligations and wallet funding mechanics across the six GCC member states.
Market Dynamics
Merchant acquiring infrastructure across the GCC is collapsing toward smartphone-native rails as NFC and QR protocols displace dedicated point-of-sale hardware, compressing deployment costs and accelerating wallet onboarding for small retailers previously excluded from electronic payments.
Growth Catalysts
- SAMR-style digital payment frameworks:Saudi Arabia's SAMR and the UAE Central Bank have established licensing pathways for non-bank payment providers, lowering capital barriers for fintech entrants and expanding wallet service coverage to unbanked expatriate populations.
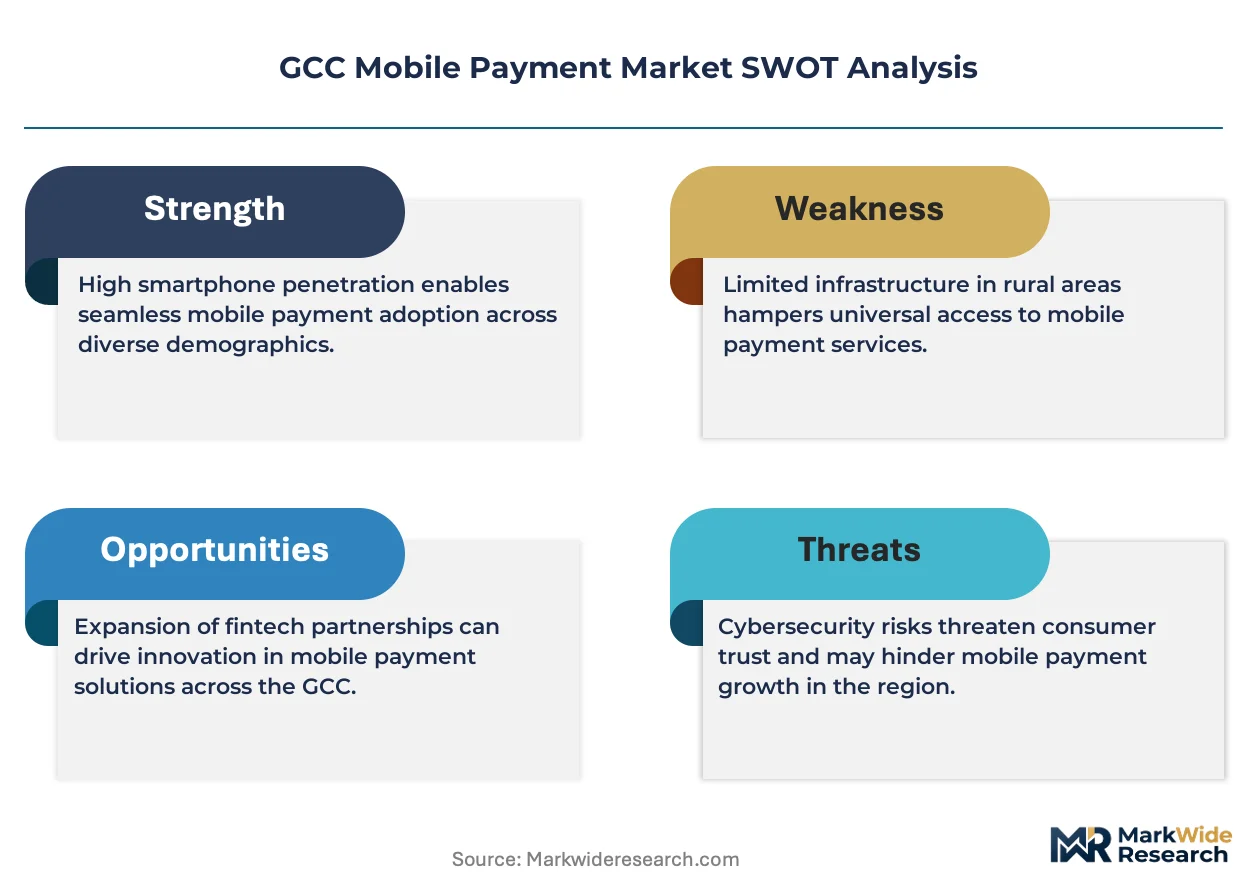
- Smartphone penetration convergence:Device ownership rates exceeding 90% across the UAE and Saudi Arabia eliminate the hardware barrier that constrained mobile payment adoption in other emerging markets.
- Government digitization agendas:National transformation programs in Qatar and Bahrain mandate salary and benefit disbursement through traceable electronic channels, creating captive transaction volume for wallet providers.
Market Restraints
- Interoperability fragmentation:Proprietary wallet protocols across the six GCC states prevent seamless cross-border consumer payments, forcing merchants to maintain multiple settlement relationships.
- Data localization mandates:GDPR-aligned requirements in Bahrain and Qatar compel foreign payment processors to establish dedicated regional data centers, elevating fixed cost structures against centralized cloud architectures.
- Cash preference inertia:Traditional merchant segments in Kuwait and Oman, particularly informal retail and construction labor payments, resist electronic settlement due to transaction fee sensitivity and documentation concerns.
Strategic Opportunities
- Cross-border remittance corridors:The India-UAE and Pakistan-Saudi Arabia corridors represent concentrated demand for low-cost peer-to-peer transfers currently served by expensive traditional money transfer operators.
- Hospitality merchant portfolios:Dubai and Abu Dhabi's tourism recovery creates acquisition opportunities for integrated payment-loyalty platforms serving hotels, restaurants, and experience operators.
- Open banking API convergence:Regulatory mandates for standardized account access interfaces in Saudi Arabia and the UAE enable wallet providers to link directly to bank accounts, bypassing card network interchange fees.
Industry Challenges
- Cybersecurity talent scarcity:PCI-DSS compliance and token vault architecture require specialized engineering capabilities that command premium compensation in the constrained Gulf technology labor market.
- Legacy core banking integration:Established financial institutions in Qatar and Kuwait operate on decades-old mainframe systems that resist real-time API connectivity, delaying wallet funding and settlement speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Mobile Payment Market |
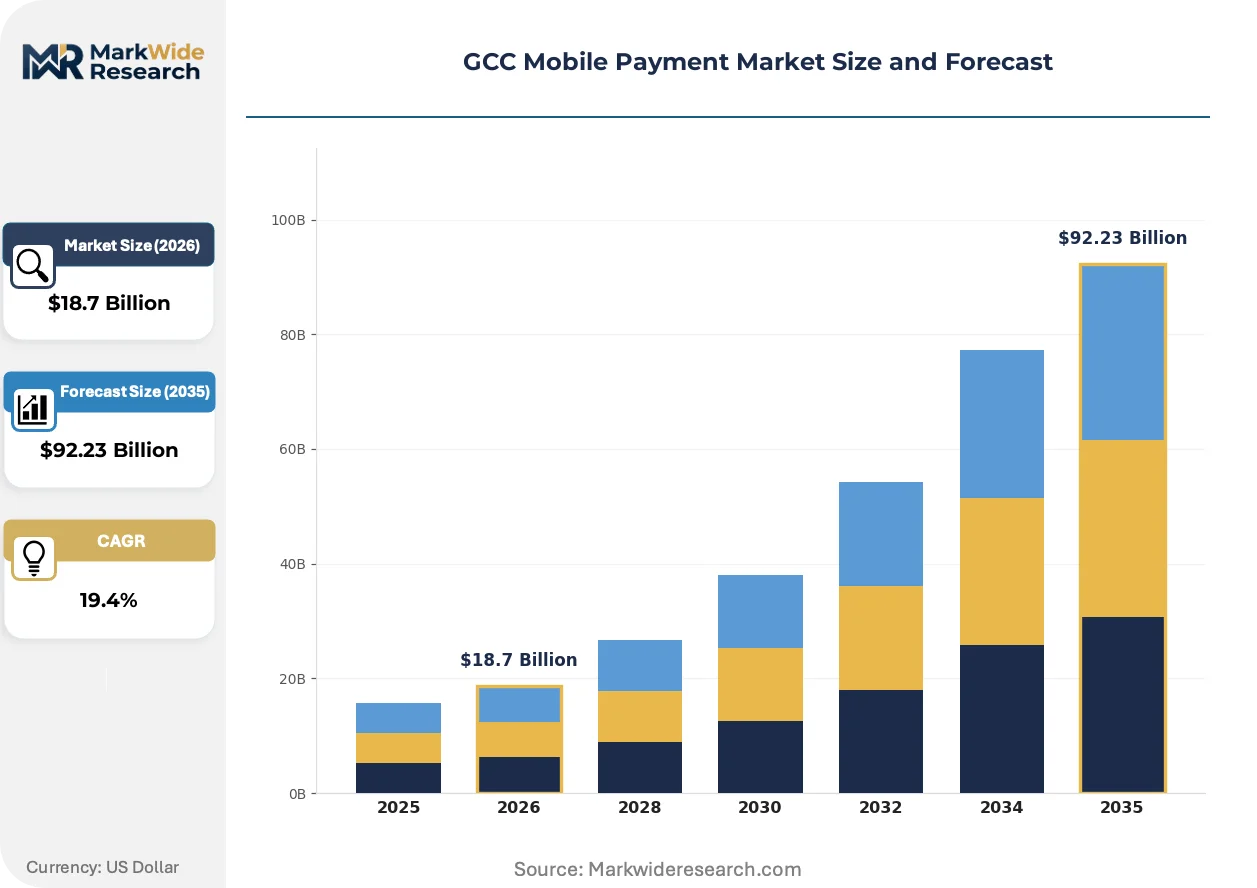
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Consumers, Retailers, E-commerce Platforms, Service Providers Transaction Type: In-store Payments, Online Transactions, Peer-to-Peer Transfers, Bill Payments Technology: NFC, QR Code, SMS Payments, Cloud-based Solutions |
| Companies Covered | Mastercard Incorporated, HyperPay, Stripe, Inc., STC Pay, Emirates NBD, PayPal Holdings, Inc., Network International, Checkout.com, Visa Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Mobile Payment Market Strategic Shifts & Innovations
Payment infrastructure across the Gulf is shedding physical form factors as cloud-hosted tokenization and software-defined acquiring replace hardware-dependent authentication. This shift compresses merchant onboarding timelines and collapses the distinction between online and in-store transaction processing.
Cloud-native token vaults are virtualizing cardholder data protection across GCC payment networks. Network operators and wallet providers are migrating primary account number storage from merchant premises to centralized encrypted repositories. This architecture is virtualizing the security perimeter, enabling small retailers to accept contactless payments without investing in certified hardware security modules.
SAMR and UAE Central Bank open banking directives are mandating standardized API access to customer account data. These regulations compel traditional banks to expose transaction histories and balance information to licensed third-party providers. Retail merchant acquirers in Dubai and Riyadh are responding by integrating account-to-account payment rails that circumvent card network fees.
Salary disbursement patterns among Gulf expatriate workers are pivoting from cash collection toward wallet-based digital receipt. Construction and domestic labor employers in Qatar and the UAE face regulatory pressure to document wage payments electronically. This behavioral shift concentrates transaction volume in peer-to-peer corridors linking Gulf wallets to South Asian receiving accounts, displacing informal hawala networks.
GCC Mobile Payment Market Segmentation
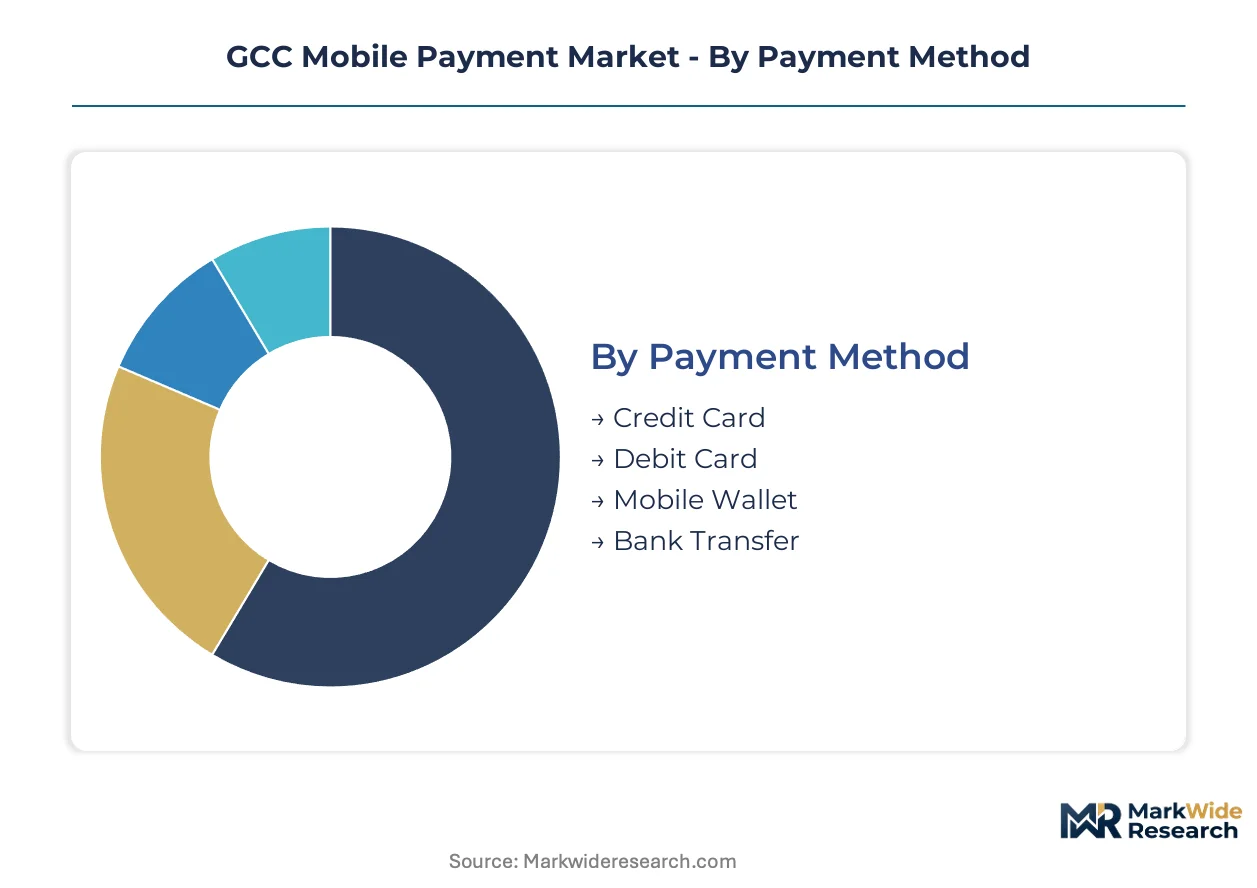
Mobile payment segmentation across the GCC reveals how transaction infrastructure fragments across funding sources, user categories, and technical protocols. Each dimension captures distinct regulatory exposure and merchant integration requirements that shape provider strategies in Saudi Arabia and the UAE.
Payment Method:
Cost tier differentiation across funding instruments determines merchant acceptance economics and consumer adoption velocity in Gulf markets.
- Credit Card:Premium rewards-linked instruments dominate hospitality and luxury retail in Dubai Mall corridors. Saudi SAMR capital reserve requirements elevate issuer compliance costs for revolving credit products.
- Debit Card:Direct account-linked rails capture salary disbursement volume from government digitization mandates in Qatar and Bahrain. Lower interchange rates accelerate small merchant onboarding previously excluded from electronic settlement.
- Mobile Wallet:STC Pay and similar providers anchor domestic dominance through wallet-based government benefit distribution.
- Bank Transfer:Account-to-account rails gain traction as UAE Central Bank open banking APIs enable direct funding bypassing card networks.
Mobile Wallet holds installed capacity. Bank Transfer is rotating up the share rankings.
End User:
Customer type concentration determines platform architecture requirements and regulatory licensing pathways across Gulf states.
- Consumers:Expatriate workers in the UAE and Qatar drive peer-to-peer remittance corridor demand to India and Pakistan. Smartphone penetration exceeding 90% eliminates hardware barriers that constrained adoption elsewhere.
- Retailers:Small merchants in Riyadh Boulevard and Dubai Mall corridors adopt QR-native acceptance to avoid dedicated point-of-sale hardware investments. SAMR licensing pathways reduce capital barriers for fintech service providers.
- E-commerce Platforms:Checkout latency compression priorities shape tokenization infrastructure investments.
- Service Providers:Hospitality operators in Abu Dhabi seek integrated payment-loyalty platforms as tourism recovers.
Retailers command transaction volume concentration. E-commerce Platforms are climbing the fastest in share rankings.
Transaction Type:
Application context dictates settlement speed requirements and authentication protocol selection across merchant categories.
- In-store Payments:NFC contactless protocols capture premium use cases in luxury retail and quick-service restaurants. Cloud-hosted token vaults enable small retailers to accept payments without certified hardware security modules.
- Peer-to-Peer Transfers:Expatriate worker remittances from the UAE and Qatar to the Philippines represent concentrated demand for low-cost alternatives to traditional money transfer operators.
- Online Transactions:E-commerce checkout flows prioritize latency reduction through stored credential frameworks.
- Bill Payments:Government utility and telecom settlement mandates create recurring transaction volume.
Peer-to-Peer Transfers hold installed capacity. In-store Payments are gaining share fastest as merchant infrastructure shifts.
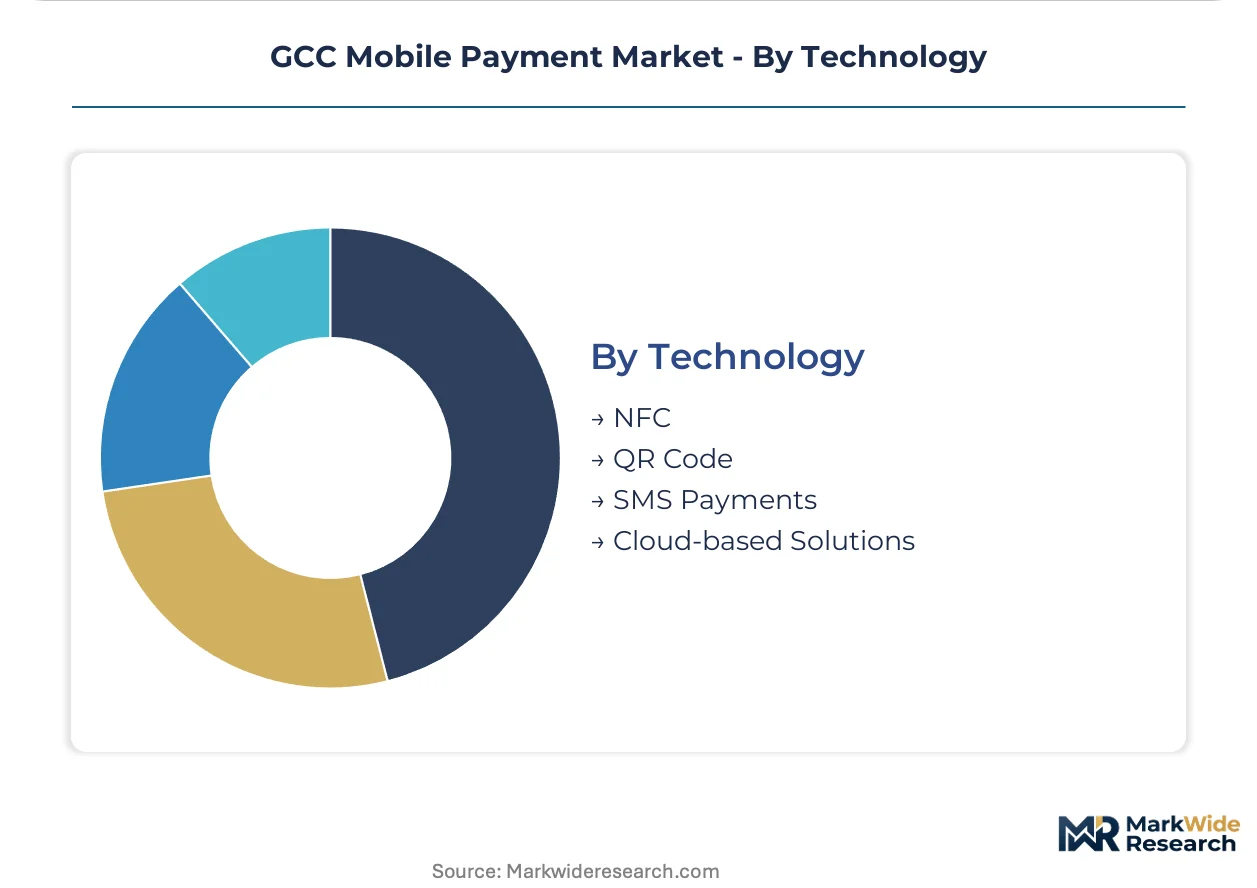
Technology:
Maturity curves across authentication protocols determine deployment cost structures and interoperability constraints in Gulf markets.
- NFC:Near-field communication anchors premium in-store experiences across Dubai and Riyadh retail corridors. Device compatibility requirements limit penetration among older smartphone installed bases in Oman and Kuwait.
- QR Code:Visual scanning protocols displace dedicated hardware for small merchant onboarding at minimal deployment cost. Proprietary wallet implementations across the six GCC states prevent seamless cross-border consumer payments.
- SMS Payments:Text-message rails retain relevance for feature phone users in labor camp disbursement scenarios.
- Cloud-based Solutions:Centralized token vault architectures virtualize security perimeters for merchant acquirers.
NFC holds installed capacity. QR Code is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the UAE and Saudi Arabia, where merchant acquiring margins compress in Dubai's saturated corridors while Riyadh's regulatory sandbox preserves fintech premiums. Bahrain and Qatar occupy intermediate positions shaped by data localization costs and smaller addressable bases.
United Arab Emirates
Dubai Mall and Abu Dhabi hospitality corridors drive NFC contactless volume at luxury retail and quick-service restaurants. UAE Central Bank open banking APIs mandate standardized account access for licensed third-party providers. Network International and Checkout.com compete for merchant portfolios across Dubai's tourism recovery zones.
Saudi Arabia
Wallet-based salary disbursements and government benefit distribution anchor domestic transaction volume among expatriate workers. SAMR digital payment frameworks establish licensing pathways with reduced capital barriers for non-bank fintech entrants. STC Pay sustains dominance through Riyadh Boulevard retail integration and cross-border remittance corridors to South Asia.
Qatar
Construction and domestic labor employers face regulatory pressure to document wage payments through traceable electronic channels. Qatar Central Bank directives mandate salary disbursement digitization for worker protection compliance. Doha merchant acquiring concentrates in hospitality and retail corridors serving FIFA legacy tourism infrastructure.
Bahrain
GDP-aligned data localization requirements compel foreign payment processors to establish dedicated regional data centers. The Central Bank of Bahrain licenses digital payment providers under consumer protection standards that elevate fixed cost structures. Manama's financial district hosts regional headquarters for processors serving the broader Gulf corridor.
Kuwait
Informal retail and construction labor segments resist electronic settlement due to transaction fee sensitivity and documentation concerns. The Central Bank of Kuwait maintains conservative licensing frameworks that preserve traditional banking dominance. Kuwait City merchant acquiring advances slowly in formal retail corridors while cash preference persists in traditional souks.
GCC Mobile Payment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in tokenization and acquiring infrastructure. The vendor base spans consolidated global networks, regional banking consortia, and emerging fintech licensees. Three archetypes dominate: tokenization infrastructure operators, wallet-native domestic champions, and cross-border remittance specialists. Competitive moves concentrate on merchant portfolio acquisition and open banking API integration partnerships.
Within the global network tier, Mastercard Incorporated and Visa Inc. anchor tokenization infrastructure for cross-border flows. STC Pay exemplifies the domestic champion archetype through Saudi wallet dominance. Network International occupies a position among regional merchant acquirers competing for UAE hospitality portfolios.
| Leading Market Players |
|---|
| Mastercard Incorporated |
| HyperPay |
| Stripe, Inc. |
| STC Pay |
| Emirates NBD |
| PayPal Holdings, Inc. |
| Network International |
| Checkout.com |
| Visa Inc. |
| Others |
Cost & Logistics Intelligence
Token vault infrastructure concentration in the United States and Western Europe anchors downstream margin capture for GCC merchant acquirers, with cloud-hosted encryption modules commanding premium licensing fees that compress domestic wallet provider economics.
Pricing Analysis
Configured-to-order API integration pricing spreads widely from standardized QR-code acceptance rates across Dubai and Riyadh retail corridors. Per-unit transactional models dominate, with interchange differentiation driven by SAMR licensing tier and PCI-DSS certification level. Cost compression in small-merchant onboarding runs through open banking API commoditization. Informal retail segments in Kuwait and Oman exhibit highest price sensitivity; luxury hospitality operators in Abu Dhabi show lowest.
Supply Chain Analysis
Tariff exposure between United States and China dominates hardware security module sourcing for NFC terminal deployment across Gulf markets. Tokenization software draws from Ireland, Singapore, and United States development centers. Raw material dependencies span semiconductor wafers, encryption chipsets, and cloud compute capacity. Single-source vulnerability concentrates in Mastercard and Visa token vault architectures. Distribution runs through regional data centers in Bahrain and Qatar mandated by GDPR-aligned localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from account-to-account payment rails that bypass card network infrastructure entirely, threatening interchange-dependent revenue models.
For Market Incumbents: Build regulatory moats through SAMR and UAE Central Bank licensing pre-emption before open banking API standards fully commoditize wallet funding. Deepen vertical integration into cloud-native token vault infrastructure to reduce dependency on Mastercard and Visa licensing. Secure hospitality merchant portfolios in Dubai and Abu Dhabi through integrated payment-loyalty platforms that resist pure-price competition.
For New Entrants and Emerging Players: Establish a beachhead in Qatar construction labor disbursement corridors where regulatory mandates create captive transaction volume. Target Bahrain data center infrastructure requirements as foreign processors face localization cost barriers. Deploy white-label wallet solutions for regional banking consortia seeking rapid digital payment deployment without SAMR direct licensing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional merchant acquirers holding Dubai hospitality portfolios. Long-term viability hinges on open banking API convergence enabling account-to-account payment displacement of card rails. Monitor STC Pay cross-border remittance corridor expansion as inflection signal for domestic champion defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | Enables UAE Central Bank-mandated account access that circumvents card network interchange. |
| Cloud-Native Token Vault Deployment | Virtualizes PCI-DSS compliance for small merchants without hardware security module investment. |
| Cross-Border Remittance Corridor Expansion | Captures India-UAE and Pakistan-Saudi Arabia peer-to-peer volume from traditional money transfer operators. |
| Hospitality Merchant Portfolio Acquisition | Secures Dubai and Abu Dhabi tourism recovery zones with integrated payment-loyalty platforms. |
| Regional Data Center Localization | Satisfies Bahrain and Qatar GDPR-aligned mandates that elevate fixed costs for foreign processors. |
Research Approach
Cross-validation between primary interviews with digital payment executives and secondary regulatory filings anchors the qualitative findings. Stakeholder consultations spanned wallet platform CTOs, SAMR licensing officers, merchant acquiring heads at regional banks, and hospitality payment operations directors. Secondary sources included UAE Central Bank open banking directives, SAMR digital payment framework circulars, PCI-DSS compliance documentation, and customs records for payment hardware imports. Bottom-up transaction volume estimates triangulated against top-down GDP electronic payment penetration benchmarks.
Calibration against historical wallet adoption curves and smartphone penetration saturation points shaped the projection framework. Segmentation dimensions modeled encompass payment method, end user category, transaction type, and technology protocol across the analysis window. CAGRs derived from logistic diffusion curves applied to regulatory mandate implementation timelines. Industry-specific inputs included SAMR licensing velocity and Qatar Central Bank salary disbursement digitization compliance rates.
Sensitivities concentrate around open banking API standardization pace and central bank digital currency pilot program outcomes. Forecasts reflect assumptions regarding regulatory enforcement consistency and merchant onboarding cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Payments Market
Payments
China POS Terminals Market
Payments
Wearable Payments Market
Payments
United Kingdom Payment Market
Payments
Singapore Remittance Market
Payments
North America Real Time Payment Market
Payments
Denmark Mobile Payments Market
Payments
Nigeria Mobile Money Market
Payments
Mobile Point of Sale (POS) Market
Payments
Portugal POS Terminals Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Asia Pacific POS Terminal Market
Payments
US Buy Now Pay Later Services Market
Payments
POS Terminals Market
Payments
Germany Payment Gateway Market
Payments
QR Codes Payment Market